
 South Africa Food Preservatives Market | 2026-2036
South Africa Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Preservatives Market Analytics
Buyer concentration among large food manufacturers is pivoting toward mid-tier processors as private-label expansion fragments procurement across Gauteng and Western Cape production zones. Crown National leverages its integrated spice and ingredient distribution network to control channel access across South African retail and foodservice segments. Corbion sustains R&D intensity in fermentation-derived preservation solutions, competing with synthetic alternatives on clean-label positioning. DSM anchors its regional presence through micronutrient and biopreservative portfolios that extend shelf life in dairy and meat applications.
Food preservatives comprise chemical or biological compounds—typically organic acids, their salts, or antioxidant systems—formulated to inhibit microbial proliferation, enzymatic browning, or oxidative rancidity in processed foods, with effective concentrations often ranging from 0.05% to 0.3% by weight depending on water activity and pH conditions. Sorbates dominate volume consumption in South African bakery and dairy applications where pH conditions favor potassium sorbate efficacy, while nitrates and nitrites retain structural importance in cured meat segments despite clean-label pressures. Benzoates face margin compression as beverage formulators shift toward alternative preservation systems, though powder and granular forms retain manufacturing efficiency advantages in large-scale food production settings.
The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act governs maximum permissible preservative levels, while the National Regulator for Compulsory Specifications enforces packaging and labeling standards that shape product registration timelines. BIS alignment pressures and SADC trade harmonization initiatives are forcing reformulation investments among suppliers serving cross-border food manufacturers. Stakeholders must monitor pending amendments to preservative maximum limits and the accelerating shift toward biopreservative alternatives as retail chains impose stricter ingredient specifications.
Market Dynamics
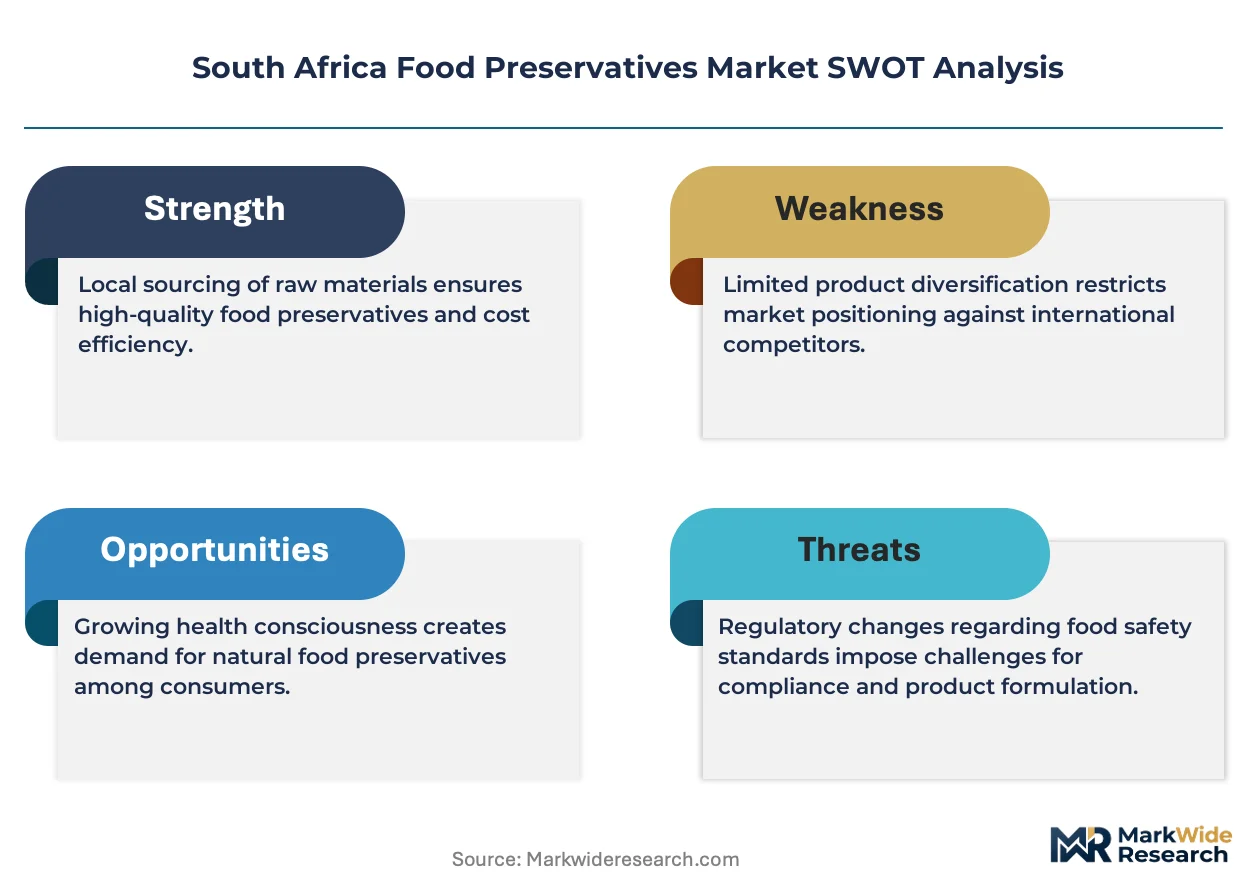
Reformulation mandates under the Foodstuffs, Cosmetics and Disinfectants Act are compressing synthetic preservative volumes while biopreservative R&D accelerates across Gauteng and Western Cape manufacturing clusters.
Growth Catalysts
- Clean-label retail specifications:Major South African supermarket chains now enforce ingredient transparency protocols that favor fermentation-derived preservation systems over synthetic alternatives in processed meat and dairy categories.
- SADC trade harmonization:Cross-border manufacturers serving Zimbabwe, Botswana, and Namibia must align formulations with South African maximum permissible levels, standardizing demand for compliant additive blends.
- Extended distribution networks:Cold chain expansion into rural Limpopo and Eastern Cape provinces requires shelf-life extension technologies that maintain product integrity across longer logistics cycles.
Market Restraints
- Propionic acid supply volatility:Bakery sector dependence on imported organic acid precursors exposes margins to currency fluctuation and port congestion at Durban container terminals.
- Clean-label cost premium:Nisin and natamycin biopreservatives command 40-60% higher unit costs than benzoate systems, constraining adoption among price-sensitive mid-tier processors.
- Maximum limit compression:Pending amendments to the Foodstuffs Act threaten to reduce sorbate and benzoate thresholds in beverage applications, forcing costly reformulation cycles.
Strategic Opportunities
- Western Cape wine preservative pivot:Sulfite reduction trends in export-oriented viticulture create demand for alternative antioxidant systems that maintain sensory stability without triggering allergen labeling requirements.
- Direct-to-manufacturer channel development:Digital procurement platforms are bypassing traditional ingredient distributors, enabling preservative suppliers to capture margin previously allocated to Crown National's integrated network.
- Fermentation capacity expansion:DSM and Corbion are scaling Cape Town-area biomanufacturing assets to serve regional dairy and meat processors seeking clean-label positioning for EU export markets.
Industry Challenges
- Formulation chemist scarcity:South African universities produce insufficient food science graduates with specialized expertise in hurdle technology design and pH-water activity optimization.
- Dual registration complexity:Suppliers must secure separate approvals from the Department of Health and SADC member state regulators, extending product launch timelines by 18-24 months.
- Legacy equipment incompatibility:Powder-to-liquid preservative system transitions require capital investment in automated dosing infrastructure that many KwaZulu-Natal processors have deferred since 2019.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Preservatives Market |
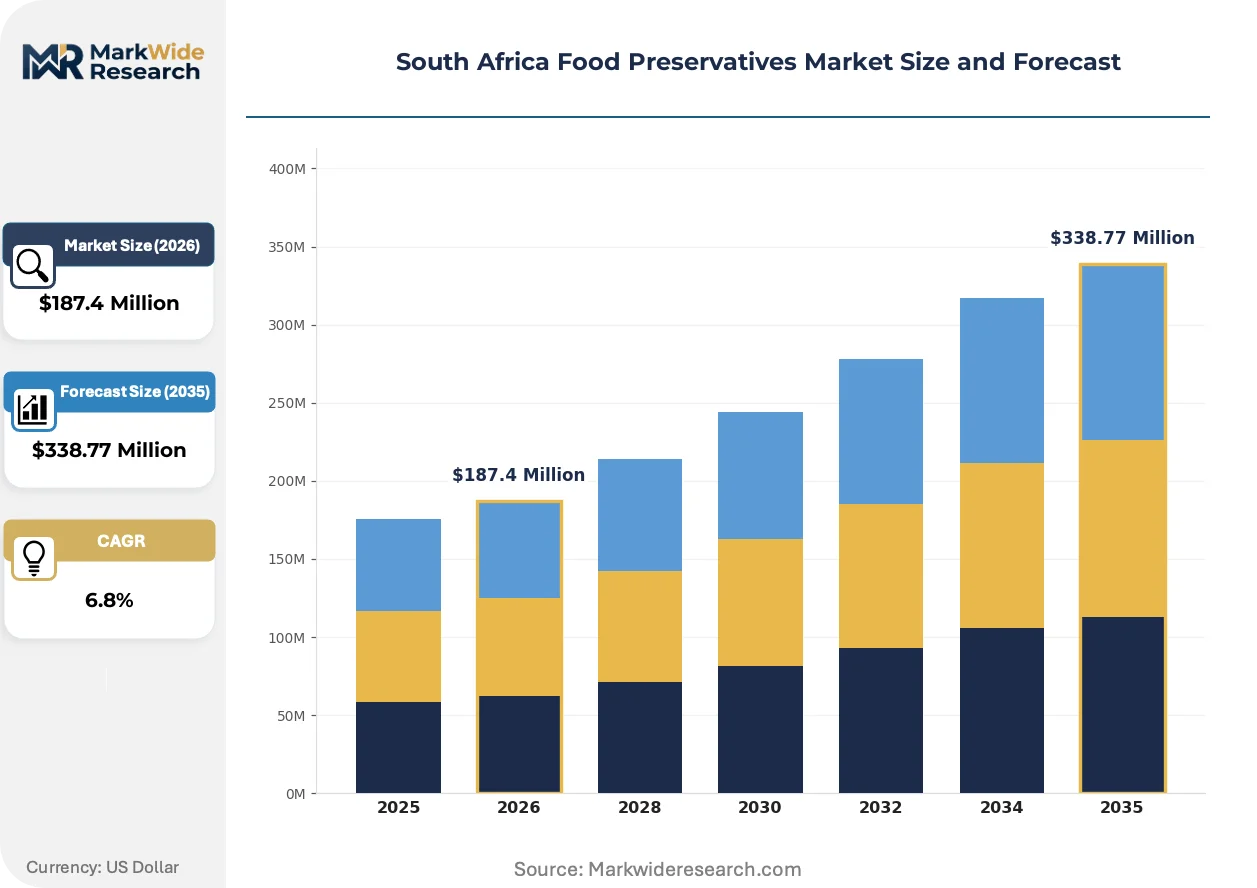
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrates, Nitrites Form: Liquid, Powder, Granular, Solid Application: Meat Products, Dairy, Bakery, Beverages End User: Food Manufacturers, Retailers, Restaurants, Households |
| Companies Covered | Crown National, Cape Food Ingredients, Corbion, Kayo Fine Chemicals, Protea Chemicals, DSM, Prime Pharma, Jungbunzlauer Ag, Kerry Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Preservatives Market Evolving Landscape
Active packaging integration and fermentation-derived preservation systems are displacing conventional chemical additives across South African meat, dairy, and bakery processing operations.
Bacteriocin-based biopreservation is electrifying shelf-life extension protocols in the country's processed meat sector. Large-scale abattoirs and curing facilities in Johannesburg's northern industrial corridor are adopting nisin-lactate combinations at accelerated rates. This technology is electrifying competitive positioning by enabling clean-label claims that command retail shelf placement premiums without sacrificing the 45-60 day distribution windows required by national supermarket networks.
The Department of Health's pending amendments to preservative maximum limits under the Foodstuffs Act are forcing systematic reformulation investments across beverage and condiment categories. Manufacturers must submit revised product registrations with accelerated stability data packages. Mid-tier processors in Gauteng face the steepest compliance burden, as their technical service capabilities lack the scale to parallel-track multiple reformulation projects while maintaining existing production schedules.
Private-label expansion among Shoprite, Pick n Pay, and Woolworths is fragmenting procurement authority across decentralized quality assurance teams. National brand managers who once controlled preservative specifications now negotiate with category-specific buyers who prioritize unit cost over supplier continuity. This pattern concentrates in Western Cape fruit processing and KwaZulu-Natal snack manufacturing, where retailer-owned brands have captured 35-40% of shelf space previously allocated to multinational food manufacturers.
South Africa Food Preservatives Market Segmentation
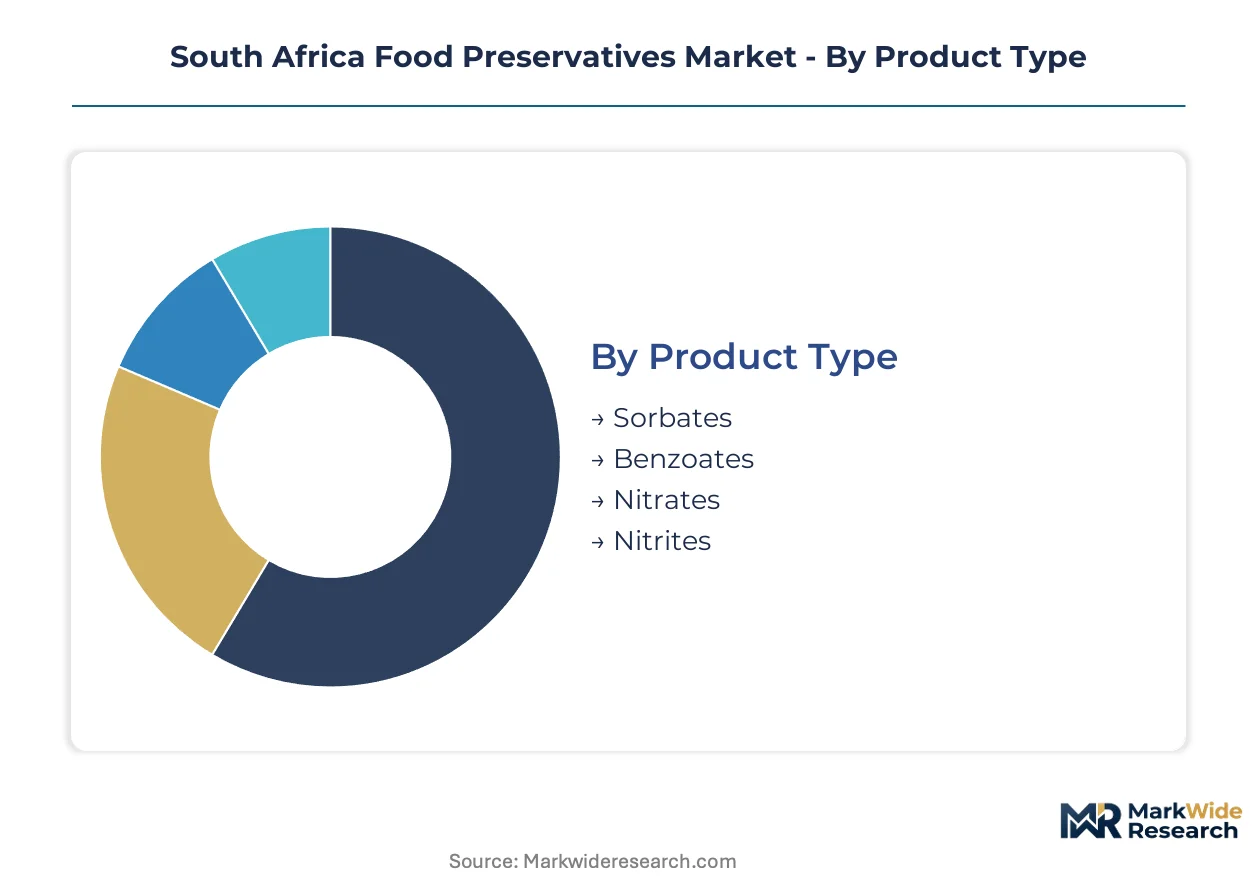
Preservative selection in South Africa hinges on pH compatibility, water activity thresholds, and Department of Health registration pathways. Each segmentation axis reveals distinct procurement patterns across Gauteng manufacturing clusters and Western Cape processing facilities.
Product Type:
Potassium sorbate and sodium benzoate dominate volume flows through Durban chemical import terminals, while nitrate systems retain structural importance in meat curing protocols.
- Sorbates:Potassium sorbate inhibits mold and yeast proliferation in pH ranges below 6.5, making it indispensable for Johannesburg-based dairy processors and Cape Town fruit preparation facilities. Demand concentrates in UHT milk and yogurt applications where extended ambient distribution requires fungal control without refrigeration dependency.
- Benzoates:Sodium benzoate delivers antimicrobial efficacy in acidic matrices below pH 4.5, serving carbonated beverage bottlers in Gauteng and condiment manufacturers in KwaZulu-Natal. Western Cape wine processors are reducing sulfite dependence by exploring benzoate-sorbate blends for low-alcohol ready-to-drink formulations.
- Nitrates:Sodium nitrate serves as a reservoir for nitrite release in traditional biltong and droëwors curing cycles, maintaining color stability across 30-60 day maturation periods.
- Nitrites:Sodium nitrite provides immediate antioxidant protection and botulism inhibition in cooked ham and bacon processing at large-scale abattoirs near Pretoria.
Sorbates lead on scale across dairy and bakery applications; nitrites lead on momentum as clean-label alternatives force reformulation investments in cured meat segments.
Form:
Physical state determines dosing precision, dissolution kinetics, and compatibility with legacy mixing equipment prevalent in mid-tier South African processing plants.
- Liquid:Aqueous solutions enable automated injection systems in continuous meat processing lines and spray applications for surface treatment of bakery products. Large manufacturers in Johannesburg's northern industrial corridor favor liquid sorbate systems for reduced dust exposure and faster batch turnover.
- Powder:Fine particulate grades offer manufacturing flexibility for dry blend operations in seasoning and soup base production. Powdered benzoate retains cost advantages for beverage concentrate manufacturers in Durban and Port Elizabeth.
- Granular:Intermediate particle size reduces caking during humid coastal storage while maintaining flowability for volumetric dosing equipment.
- Solid:Compressed tablets and blocks serve specialized applications in artisanal cheese brining and controlled-release packaging inserts.
Liquid formulations capture the highest volume throughput; powder forms retain the broadest equipment compatibility across legacy installations.
Application:
End-use category dictates regulatory scrutiny intensity, shelf-life targets, and clean-label substitution pressure across South African food manufacturing.
- Meat Products:Cured and processed meats depend on nitrite-nitrate systems for color fixation and pathogen control, though Pick n Pay and Woolworths specifications are accelerating natural antioxidant adoption in premium ranges.
- Dairy:Cultured products and cheese require fungal inhibitors where cold chain gaps create spoilage risk in Eastern Cape and Limpopo distribution networks.
- Bakery:Propionate and sorbate blends extend mold-free shelf life for sliced bread and crumpets sold through Shoprite's rural store expansion program.
- Beverages:Acidified drinks and fruit juices utilize benzoate-sorbate combinations, though pending Foodstuffs Act amendments threaten maximum limit reductions.
Meat applications command the highest preservative spend per unit volume; dairy applications are expanding most quickly as UHT processing capacity scales in Free State and Mpumalanga.
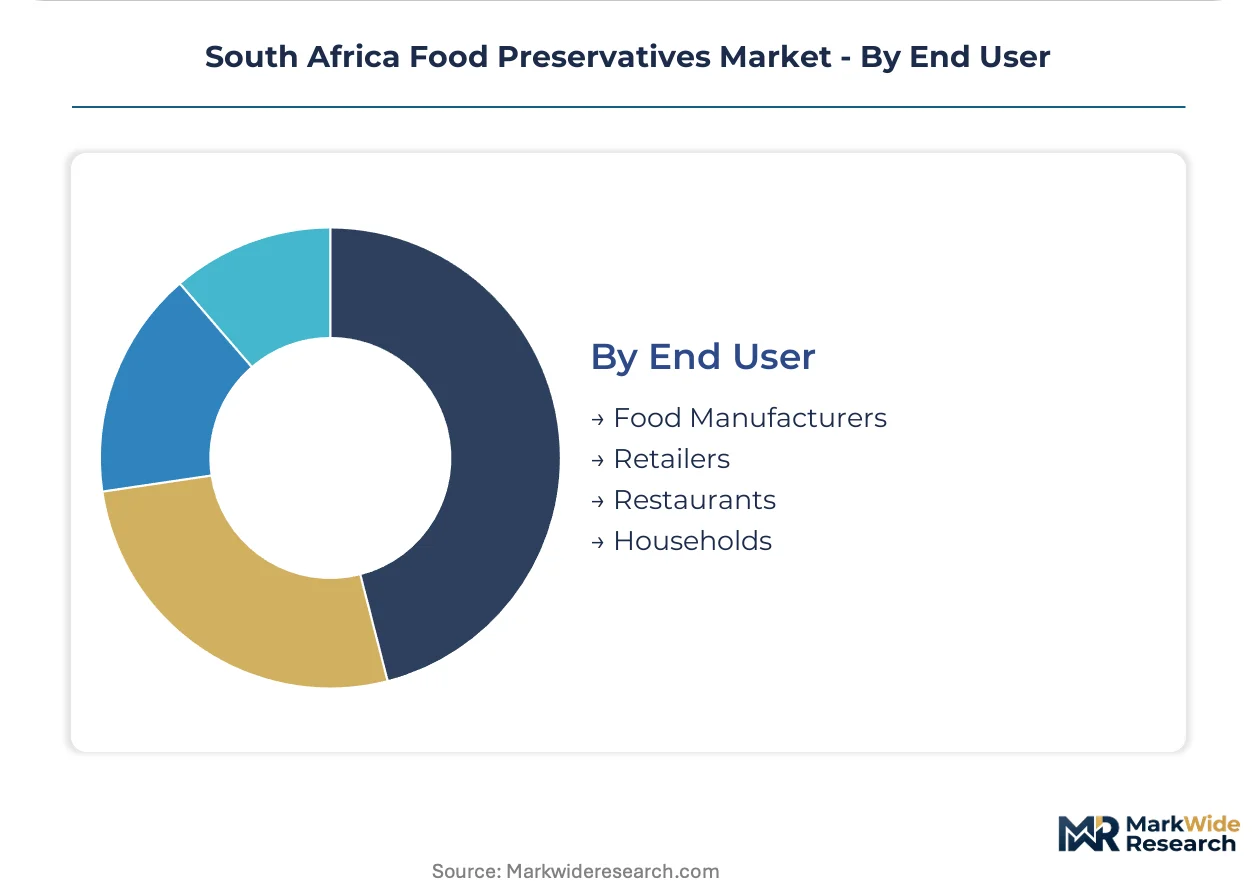
End User:
Procurement authority fragments across centralized technical teams and decentralized quality assurance functions as private-label expansion restructures buyer relationships.
- Food Manufacturers:Multinational processors and domestic brands specify preservative systems during product development, locking in supplier relationships through multi-year formulation service agreements.
- Retailers:Supermarket chains now dictate ingredient approvals for own-brand products, with category buyers overriding manufacturer preferences on clean-label positioning.
- Restaurants:Foodservice distributors supply pre-mixed preservation solutions for centralized kitchen operations and sauce manufacturing.
- Households:Direct consumer sales remain negligible, confined to niche canning salt and curing mix products through specialty retailers.
Food manufacturers retain the deepest technical integration; retailers are gaining procurement influence fastest as private-label shelf space expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province outpaces Western Cape in preservative consumption intensity, while KwaZulu-Natal import terminals handle the bulk of chemical additive volumes entering South African manufacturing corridors.
Gauteng
Johannesburg-based meat processors and dairy manufacturers drive sorbate and nitrite demand as shelf-life requirements tighten for national distribution networks. The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act compliance deadlines concentrate reformulation investment in Pretoria-Tshwane industrial zones. Crown National's integrated distribution hub in Johannesburg northern corridor controls channel access for mid-tier processors expanding private-label production.
Western Cape
Cape Town fruit preparation facilities and wine processors pivot toward alternative antioxidant systems as sulfite reduction trends accelerate in export-oriented viticulture. SADC trade harmonization protocols force alignment with South African maximum permissible levels for cross-border manufacturers serving Namibian and Botswanan markets. DSM and Corbion are scaling Cape Town-area biomanufacturing assets to serve regional dairy processors seeking clean-label positioning.
KwaZulu-Natal
Durban container terminals expose bakery sector margins to propionic acid supply volatility and currency fluctuation on imported organic acid precursors. Beverage concentrate manufacturers in Port Elizabeth retain powdered benzoate cost advantages despite clean-label pressures from retail chains. Legacy equipment incompatibility constrains powder-to-liquid system transitions among mid-tier processors who deferred capital investment since 2019.
Free State and Mpumalanga
UHT processing capacity expansion in these provinces accelerates dairy application growth for fungal inhibitors addressing cold chain gaps in rural distribution networks. Extended logistics cycles into Limpopo and Eastern Cape provinces require shelf-life extension technologies that maintain product integrity across longer transport corridors. Provincial industrial development zones attract preservative suppliers seeking proximity to emerging dairy processing clusters.
South Africa Food Preservatives Market Competitive Landscape
Dutch and Swiss producers anchor the fermentation-derived tier; South African specialists hold channel control across retail and foodservice segments. The market structure splits between multinational biopreservative developers with Cape Town manufacturing assets and domestic distributors leveraging integrated spice and ingredient networks. Three archetypes dominate: fermentation technology licensors, integrated distribution conglomerates, and regional chemical importers. Capacity expansion and direct-to-manufacturer digital procurement represent the dominant competitive vectors reshaping supplier relationships.
Among fermentation-focused multinationals, Corbion and DSM exemplify the technology-licensing archetype through their Cape Town-area biomanufacturing presence. Crown National occupies a distinct position as the integrated distribution anchor controlling retail and foodservice channel access across Gauteng and Western Cape production zones. These three companies represent the structural poles around which mid-tier processors and private-label manufacturers organize their procurement strategies.
| Leading Market Players |
|---|
| Crown National |
| Cape Food Ingredients |
| Corbion |
| Kayo Fine Chemicals |
| Protea Chemicals |
| DSM |
| Prime Pharma |
| Jungbunzlauer Ag |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Crown National's backward integration into spice and ingredient distribution anchors both supply position and pricing power across Gauteng and Western Cape manufacturing corridors. This channel control enables margin capture that pure-play chemical suppliers cannot replicate when serving mid-tier processors.
Pricing Analysis
Capacity additions in Cape Town-area biomanufacturing are reshaping price floors for fermentation-derived preservatives. Three-tier pricing structure across premium clean-label, standard synthetic, and economy bulk chemical levels stratifies around certification grade and volume scale. Pricing pressure stems from nisin and natamycin cost premiums running 40-60% above benzoate systems. Mid-tier processors in KwaZulu-Natal exhibit highest price sensitivity due to deferred capital investment since 2019, while multinational dairy exporters absorb premium positioning costs.
Supply Chain Analysis
Regional distribution centers in Johannesburg northern corridor and Cape Town industrial zones organize hub-and-spoke patterns reaching Free State and Mpumalanga dairy clusters. Geographic supply concentration draws from China, India, and Germany for organic acid precursors and fermentation feedstocks. Raw material dependencies rest on propionic acid imports, potassium sorbate bulk chemicals, and specialized yeast extracts for biopreservative production. Single-source vulnerability concentrates at Durban container terminals where port congestion exposes bakery sector margins. Distribution runs through Crown National's integrated network and direct-to-manufacturer digital platforms serving large-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's Foodstuffs, Cosmetics and Disinfectants Act compliance deadlines create geographic-arbitrage potential between domestic reformulation investments and SADC cross-border standardization, where regulatory alignment costs in Zimbabwe and Botswana lag Pretoria's enforcement intensity.
For Market Incumbents: Deploy fermentation capacity expansion in Western Cape to capture clean-label premiums before synthetic preservative thresholds compress under pending Foodstuffs Act amendments. Defend channel position by locking mid-tier processors into multi-year technical service agreements that embed hurdle technology expertise. Counter emerging digital procurement platforms with formulation chemist scarcity leverage that smaller entrants cannot replicate. For New Entrants and Emerging Players: SADC trade harmonization protocols open a window for compliant additive blend suppliers serving Zimbabwean and Botswanan manufacturers aligning with South African maximum permissible levels. Target Free State and Mpumalanga UHT dairy expansion where cold chain gaps demand fungal inhibitors. Pursue direct-to-manufacturer digital procurement positioning that bypasses Crown National's distribution control. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity concentrates technical capability among incumbent suppliers with captive R&D infrastructure. Long-term viability favors fermentation technology licensors over commodity chemical importers as retail clean-label specifications harden. Acquisition focus should center on Cape Town-area biomanufacturing assets with EU export pathway certifications. Monitor pending Foodstuffs Act amendment timing as inflection signal for synthetic preservative volume displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | DSM and Corbion scale Cape Town assets to serve EU-exporting dairy processors seeking clean-label positioning. |
| Direct-to-Manufacturer Channel Development | Digital procurement platforms bypass Crown National's integrated network, capturing margin from mid-tier processors. |
| Regulatory Compliance Investment | Reformulation service capabilities lock in multi-year agreements as Foodstuffs Act deadlines concentrate technical demand. |
| Backward Integration into Distribution | Crown National's spice and ingredient network controls retail and foodservice access across Gauteng production zones. |
| SADC Market Entry Positioning | Cross-border manufacturers in Zimbabwe and Botswana must align with South African maximum permissible levels, standardizing demand. |
Research Methodology
Coverage spans Gauteng, Western Cape, KwaZulu-Natal, and Free State-Mpumalanga corridors, with primary inputs from each. Formulation chemists at mid-tier processors, procurement leads at multinational dairy exporters, technical directors at Cape Town biomanufacturing facilities, and category buyers at Shoprite and Pick n Pay provided structured interviews. Secondary validation drew from Department of Health regulatory filings, SADC trade harmonization documentation, customs import records for organic acid precursors, and food manufacturing capacity databases. Bottom-up preservative volume estimates triangulated against top-down food processing output projections.
Rate-of-change decomposition structured the analytical framework across the analysis window. Segmentation dimensions modeled include product type, physical form, application category, and end-user procurement authority. CAGRs derived from weighted average of historical trajectory and forward-looking regulatory impact assessment. Industry-specific forecast inputs incorporated pending Foodstuffs Act amendment probabilities and cold chain expansion timelines into Eastern Cape and Limpopo distribution networks.
Revisions become necessary when regulatory amendment timing, currency fluctuation severity, or biopreservative cost compression trajectories materialize outside modeled ranges. Forecasts reflect documented assumptions around SADC harmonization pace and retail clean-label specification adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Brazil Food Preservatives Market