
 Fish Tank Water Additives Market | 2026-2036
Fish Tank Water Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Tank Water Additives Market Foresight
North American specialty chemical production is shifting toward concentrated, low-dose formulations that reduce shipping volumes and shelf-space requirements. Seachem Laboratories leverages its in-house synthesis capabilities to control active ingredient purity across water conditioner lines. API (Mars, Inc.) sustains mass-market penetration through veterinary clinic partnerships and big-box retail distribution. Tetra (Spectrum Brands) anchors European demand with region-specific hardness adjusters tailored to carbonate-rich municipal supplies.
Fish tank water additives comprise formulated chemical and biological preparations designed to modify aquarium water chemistry, typically dosed in parts per million to achieve target parameters for ammonia, nitrite, nitrate, pH, and dissolved organic load. These products function as essential life-support inputs, preventing toxic accumulation while supporting nitrifying bacterial colonization in closed aquatic systems. Water conditioners and biological supplements command the largest revenue pools, reflecting their non-disposable status in both freshwater and saltwater maintenance routines. Dechlorinators and pH regulators represent faster-growing niches as municipal water treatment intensifies and specialized biotope keeping expands among dedicated hobbyists.
The EPA oversees algaecide and antimicrobial additive registration under FIFRA, while the FDA Center for Veterinary Medicine monitors products making therapeutic claims about fish health outcomes. State-level agriculture departments in California and Florida impose additional testing protocols for products entering aquaculture channels, creating a layered compliance architecture that favors established formulators with regulatory affairs staff. Stakeholders must monitor emerging restrictions on quaternary ammonium compounds and formaldehyde-releasing preservatives, as these chemistries face renewed toxicological scrutiny in both household and commercial aquarium settings.
Market Dynamics
The EPA's FIFRA enforcement is compressing algaecide formulation options while residential nano-tank proliferation pulls demand toward precision-dosed, low-volume conditioners.
Growth Catalysts
- Nano-tank proliferation:Residential aquarists in the United States are expanding biotope-specific setups that require tailored pH and hardness adjusters, creating pull for specialized additive portfolios.
- FIFRA compliance infrastructure:Established formulators with dedicated regulatory affairs staff are capturing share as smaller competitors exit antimicrobial registration pathways.
- Municipal chloramine treatment:Water utilities across Germany and France are intensifying secondary disinfection, forcing hobbyists toward advanced dechlorinator chemistries.
Market Restraints
- Active ingredient concentration:Quaternary ammonium compound suppliers face toxicological scrutiny under REACH evaluation timelines, tightening precursor availability.
- Specialty retail consolidation:United States pet specialty chains are reducing SKU counts, compressing shelf access for mid-tier conditioner brands.
- Formaldehyde-releasing preservative phase-out:California Department of Pesticide Regulation testing protocols are eliminating legacy biocide stabilizers from aquaculture-channel formulations.
Strategic Opportunities
- Direct-to-consumer subscription models:Specialty brands are bypassing retail intermediaries via automated dosing programs tied to water testing IoT devices.
- Carbonate-rich municipal supply adaptation:United Kingdom and Netherlands water chemistry profiles favor region-specific hardness reducer development.
- Biological supplement premiumization:Live nitrifying bacterial concentrates command margin expansion as planted aquarium enthusiasts prioritize instant cycle establishment.
Industry Challenges
- Formulation chemist scarcity:Expertise in ppm-scale dosing stability across variable temperature and pH conditions concentrates among legacy aquatic chemical specialists.
- Multi-jurisdiction registration synchronization:Products claiming therapeutic outcomes must align FDA Center for Veterinary Medicine filings with EPA antimicrobial registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Tank Water Additives Market |
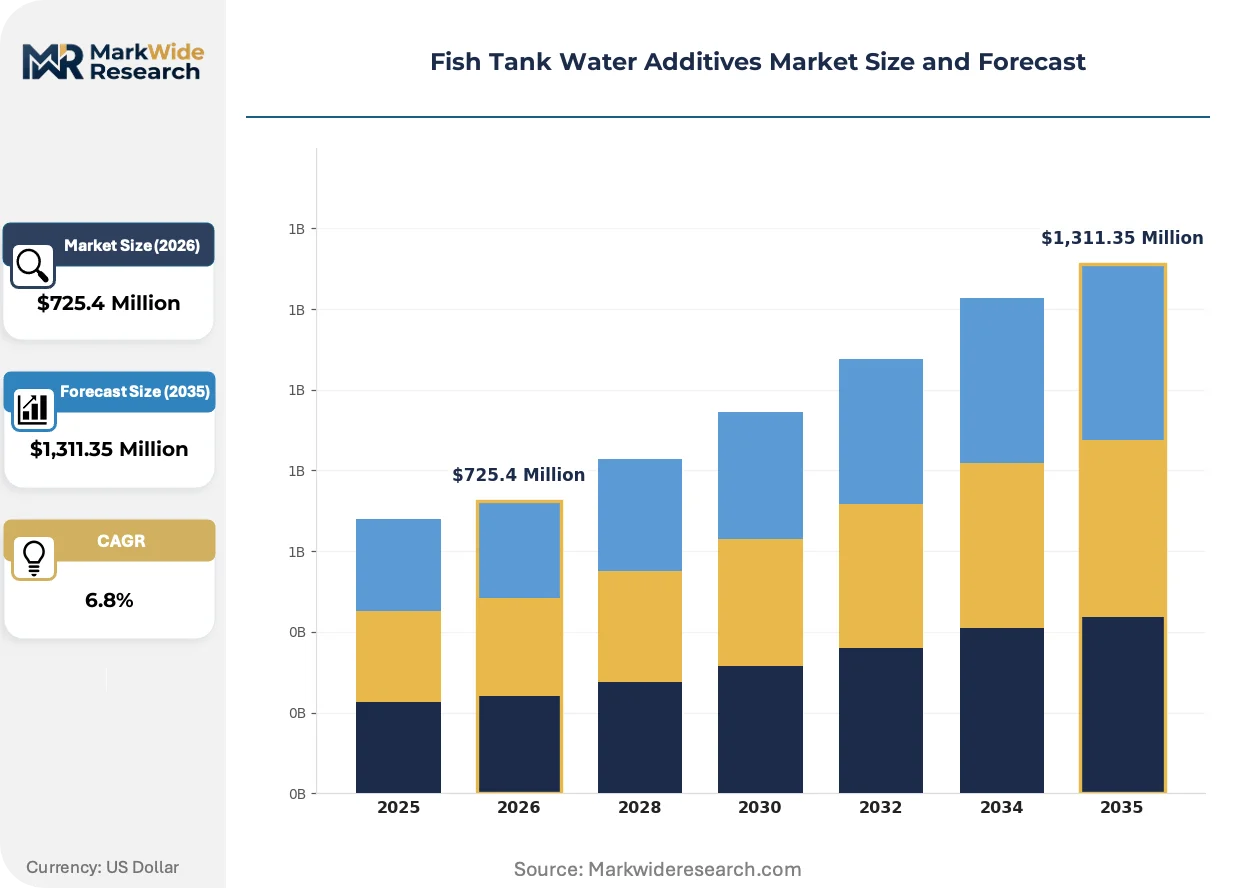
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,311.35 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Conditioners, pH Regulators, Algaecides, Dechlorinators, Biological Supplements Application: Freshwater Tanks, Saltwater Tanks, Reef Tanks, Planted Aquariums, Breeding Tanks End User: Aquarium Stores, Pet Owners, Aquaculture Facilities, Laboratory Research, Public Aquariums Distribution Channel: Online Retailers, Specialty Shops, Veterinary Clinics, Supermarkets, Wholesale Distributors |
| Companies Covered | Seachem Laboratories, API (Mars, Inc.), Tetra (Spectrum Brands), Fluval (Hagen Group), Fritz Aquatics, ADM, Kemin Industries, Skretting, Brightwell Aquatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Tank Water Additives Market Shifts & Advancements
Formulation science is pivoting toward concentrated, stability-engineered chemistries that reduce logistics burden while maintaining efficacy across diverse municipal water profiles.
Ultra-concentrated water conditioners employing thiosulfate and amine-based neutralization chemistries are consolidating market share among space-constrained urban aquarists. Hobbyists operating sub-10-gallon planted systems are adopting half-dose precision bottles that reduce storage footprint by 60 percent versus legacy quart formats. This concentration trajectory is compressing per-unit manufacturing costs while elevating shipping efficiency premiums as decisive purchase criteria.
REACH authorization timelines for quaternary ammonium compounds are forcing reformulation of algaecide and antimicrobial additive lines across European Union member states. Formulators with captive synthesis capabilities are internalizing active ingredient production to circumvent supply interruptions from third-party chemical distributors. Saltwater reef maintenance segments are most affected, with hobbyists migrating toward peroxide-based alternatives ahead of regulatory sunset dates.
Subscription-based replenishment programs are displacing episodic retail purchasing among dedicated freshwater planted tank enthusiasts. United States direct-to-consumer brands are capturing recurring revenue through automated dosing calculators linked to smartphone water parameter logging. This channel shift is most visible in coastal metropolitan clusters where specialty retail access has contracted post-pandemic.
Fish Tank Water Additives Market Segmentation
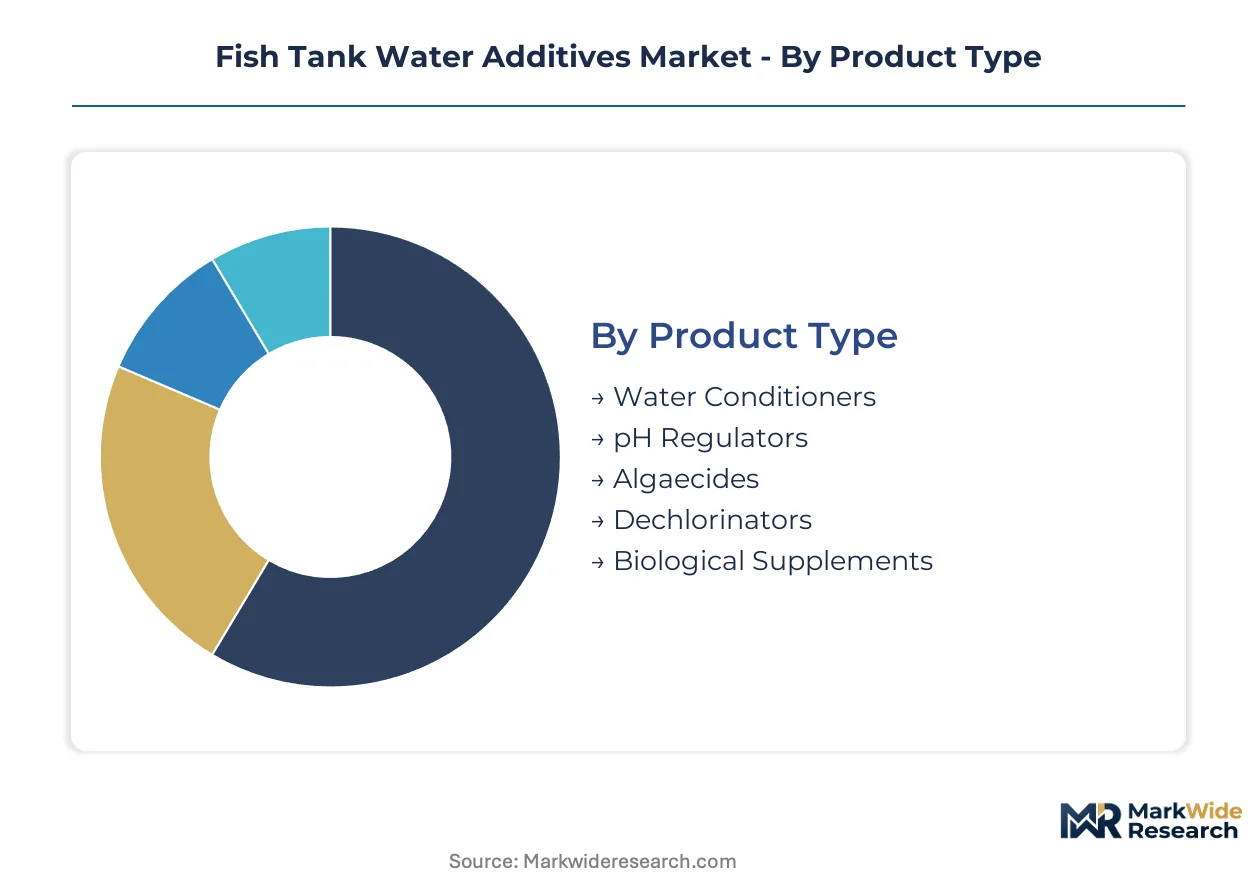
Water additive purchasing patterns diverge sharply between standalone hobbyist use and integrated commercial systems, with formulation requirements varying by tank bioload density and maintenance automation levels. Understanding these segment boundaries clarifies where precision-dosed concentrates command premium positioning versus where bulk commodity formulations dominate procurement decisions.
Product Type:
Standalone water conditioners and dechlorinators function as independent purchase decisions for residential aquarists, while algaecides and biological supplements increasingly embed into managed maintenance protocols for commercial facilities.
- Water Conditioners:Sodium thiosulfate and amine-based neutralization chemistries form the core composition, with concentrated formulations reducing bottle volume by 60 percent for urban nano-tank operators. Demand clusters among United States residential aquarists facing chloramine-treated municipal supplies, where EPA FIFRA compliance infrastructure favors established formulators with dedicated regulatory staff.
- Dechlorinators:Advanced chemistries targeting chloramine bond cleavage rather than simple chlorine neutralization now dominate formulation pipelines. Municipal utilities across Germany and France intensify secondary disinfection protocols, forcing hobbyists toward premium dechlorinator tiers that handle combined chlorine residuals.
- pH Regulators:Phosphate-buffered and carbonate-based adjusters tailored to regional water hardness profiles.
- Algaecides:Peroxide-based alternatives displace quaternary ammonium compounds ahead of ECHA REACH authorization timelines.
- Biological Supplements:Live nitrifying bacterial concentrates for instant cycle establishment in planted aquariums.
Water conditioners lead volumes today; biological supplements are gaining share fastest.
Application:
Cost-tier stratification separates basic freshwater maintenance from precision-dependent reef and breeding applications, with planted aquariums occupying a mid-tier position on input intensity.
- Freshwater Tanks:Standardized conditioner and dechlorinator protocols serve the mass-market entry segment, with formulation stability across variable municipal water chemistry as the critical specification. United States pet specialty chains reduce SKU counts here, compressing shelf access for mid-tier brands while direct-to-consumer subscriptions capture dedicated hobbyists.
- Reef Tanks:Calcium, alkalinity, and magnesium dosing precision demands define this saltwater segment, with hobbyists accepting 3-5x per-gallon input costs versus freshwater equivalents. Peroxide-based algaecide migration accelerates here as ECHA REACH timelines eliminate legacy biocide options.
- Planted Aquariums:CO2 supplementation integration with macronutrient dosing drives input complexity.
- Saltwater Tanks:General marine maintenance below reef-specific precision thresholds.
- Breeding Tanks:Parameter stability for sensitive fry development dictates specialized conditioner selection.
Freshwater tanks anchor volume concentration; reef tanks command the steepest margin expansion trajectory.
End User:
Customer-type segmentation separates episodic retail purchasers from contract-based procurement systems, with aquaculture and laboratory channels imposing documentation and certification requirements absent from consumer markets.
- Pet Owners:Subscription-based replenishment programs displace episodic retail purchasing among dedicated enthusiasts, with United States direct-to-consumer brands capturing recurring revenue through smartphone-linked dosing calculators. California Department of Pesticide Regulation testing protocols for aquaculture-channel products create compliance barriers that consumer-facing SKUs bypass.
- Aquaculture Facilities:State-level agriculture departments in Florida and California impose additional testing protocols, creating layered compliance architecture that favors established formulators. Batch documentation, lot traceability, and therapeutic claim restrictions under FDA Center for Veterinary Medicine oversight distinguish this channel.
- Aquarium Stores:Resale margin requirements and inventory turnover velocity drive private-label conditioner sourcing.
- Laboratory Research:Reproducible water chemistry parameters and contaminant-free certification priorities.
- Public Aquariums:Volume-scale procurement with species-specific biotope replication demands.
Pet owners generate the broadest revenue base; aquaculture facilities exhibit the most inelastic supply relationships.
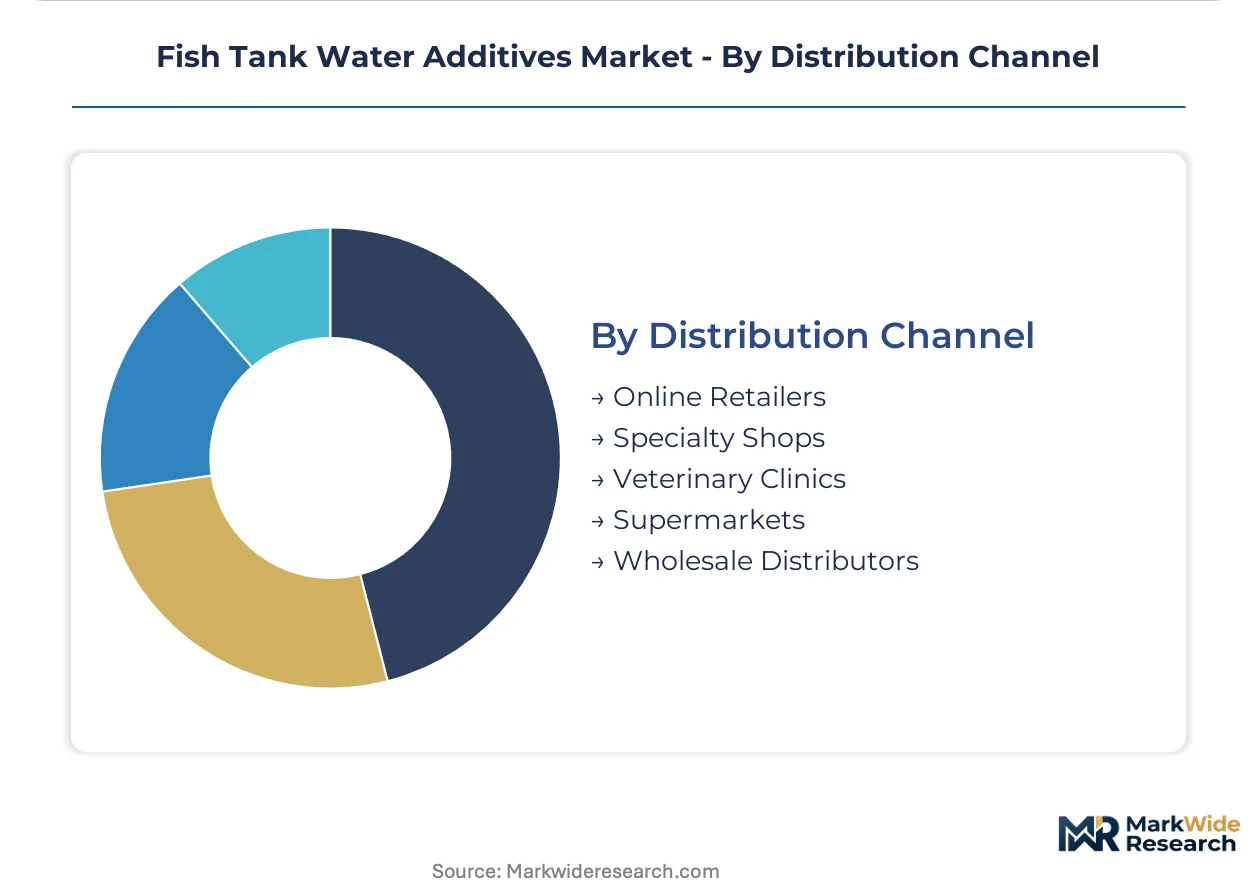
Distribution Channel:
Geographic access fragmentation shapes channel selection, with coastal metropolitan clusters showing divergent patterns from inland markets where specialty retail density varies.
- Specialty Shops:Staff expertise and immediate problem-solving consultation sustain this channel against online price competition, with United States coastal metropolitan clusters showing post-pandemic contraction in physical access. Premium positioning for nano-tank precision conditioners and biotope-specific hardness adjusters depends on trained sales staff capable of translating municipal water reports into product recommendations.
- Online Retailers:Automated dosing program subscriptions tied to water testing IoT devices capture recurring revenue from planted aquarium enthusiasts, bypassing retail intermediaries entirely. Shipping efficiency premiums for concentrated formulations elevate this channel's competitiveness for urban space-constrained aquarists.
- Veterinary Clinics:Therapeutic claim products requiring FDA Center for Veterinary Medicine alignment.
- Supermarkets:Mass-market dechlorinator and basic conditioner placement for entry-level hobbyists.
- Wholesale Distributors:Bulk formulation supply to aquaculture and public aquarium channels.
Specialty shops retain the highest customer lifetime value; online retailers are expanding share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as formulators relocate synthesis operations toward jurisdictions with streamlined chemical registration pathways. The EPA's FIFRA compliance burden in the United States is pushing antimicrobial additive manufacturing toward alternative venues while domestic brands retain formulation and packaging stages.
United States
Nano-tank proliferation in coastal metropolitan clusters drives precision-dosed conditioner demand. The EPA enforces FIFRA registration requirements for algaecide chemistries, compressing formulation options for domestic producers. California and Florida state agriculture departments impose additional aquaculture-channel testing protocols, creating layered compliance barriers that favor established players with dedicated regulatory affairs staff in San Diego and Miami corridors.
Germany
Municipal utilities intensify chloramine-based secondary disinfection across Bavaria and North Rhine-Westphalia, forcing hobbyists toward advanced dechlorinator chemistries. ECHA REACH authorization timelines for quaternary ammonium compounds are eliminating legacy biocide options from formulation pipelines. Berlin-based specialty retailers anchor European demand for region-specific hardness adjusters tailored to carbonate-rich municipal supplies.
China
Contract manufacturing concentration for thiosulfate and amine-based neutralization chemistries supplies global private-label conditioner programs. The Ministry of Ecology and Environment enforces GB standards for industrial chemical discharge, elevating environmental compliance costs for captive synthesis operations. Guangdong Province hosts concentrated additive packaging and logistics hubs serving Asia-Pacific distribution networks.
United Kingdom
Carbonate-rich municipal water chemistry across London and Southeast England favors hardness reducer development for planted aquarium enthusiasts. The Health and Safety Executive aligns with REACH implementation timelines for biocide active substance approvals. Manchester and Birmingham specialty retail clusters sustain staff expertise channels against online price competition for nano-tank precision products.
Netherlands
Randstad urban aquarists adopt subscription-based replenishment programs tied to smartphone water parameter logging. The Dutch national chemical regulator enforces EU Biocidal Products Regulation compliance for antimicrobial additive claims. Rotterdam logistics infrastructure supports concentrated formulation shipping efficiency premiums for space-constrained hobbyists across Benelux markets.
Fish Tank Water Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and IoT-integrated dosing platforms. The vendor base stratifies across legacy aquatic chemical specialists with captive synthesis capabilities, mass-market consumer brands leveraging veterinary clinic partnerships, and regional formulators serving carbonate-specific municipal profiles. Three archetypes dominate: regulatory-compliance infrastructure holders, concentrated-formulation technology leaders, and biotope-specialist precision brands. Competitive moves center on backward integration into active ingredient production and automated replenishment program deployment.
Among North American formulators, Seachem Laboratories and API (Mars, Inc.) exemplify contrasting scale positions within the water conditioner segment. Seachem represents the captive-synthesis archetype with in-house active ingredient purity control. API anchors mass-market penetration through veterinary clinic and big-box retail distribution density. Tetra (Spectrum Brands) occupies the regional-adaptation tier, serving European hardness-adjustment requirements through country-specific formulation lines. These three entities collectively illustrate how regulatory compliance infrastructure, synthesis depth, and channel access differentiate competitive positioning across residential and commercial additive segments.
| Leading Market Players |
|---|
| Seachem Laboratories |
| API (Mars, Inc.) |
| Tetra (Spectrum Brands) |
| Fluval (Hagen Group) |
| Fritz Aquatics |
| ADM |
| Kemin Industries |
| Skretting |
| Brightwell Aquatics |
| Others |
Supply & Pricing Matrix
Thiosulfate spot pricing volatility in Guangdong Province cascades through contract manufacturing tiers into three distinct conditioner price bands: captive-synthesis premium, outsourced-mid, and private-label economy.
Pricing Analysis
Distributor margin layers absorb 15-25 points before specialty retail markup, compressing landed costs for direct-to-consumer subscription brands. Three-tier pricing structure across premium, standard, and economy levels separates Seachem-grade synthesis purity from API mass-market formulations and Tetra private-label supply. Cost compression in the economy tier is intensifying because Chinese contract manufacturers face GB standards compliance cost elevation. Aquaculture facilities exhibit the lowest price sensitivity due to batch documentation requirements; urban nano-tank hobbyists show highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale aquaculture procurement through wholesale distributors, while specialty shops and online retailers fragment residential demand. Active ingredient synthesis concentrates in China, Germany, and the United States; formulation and packaging regionalizes to California, Florida, and Guangdong. Supply chains draw from sodium thiosulfate, amine-based neutralizers, and live bacterial cultures as core inputs. Single-source vulnerability in quaternary ammonium compound precursors intensifies as ECHA REACH authorization timelines eliminate European suppliers. Distribution runs through three-tier wholesale-specialty-direct structures with divergent margin retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
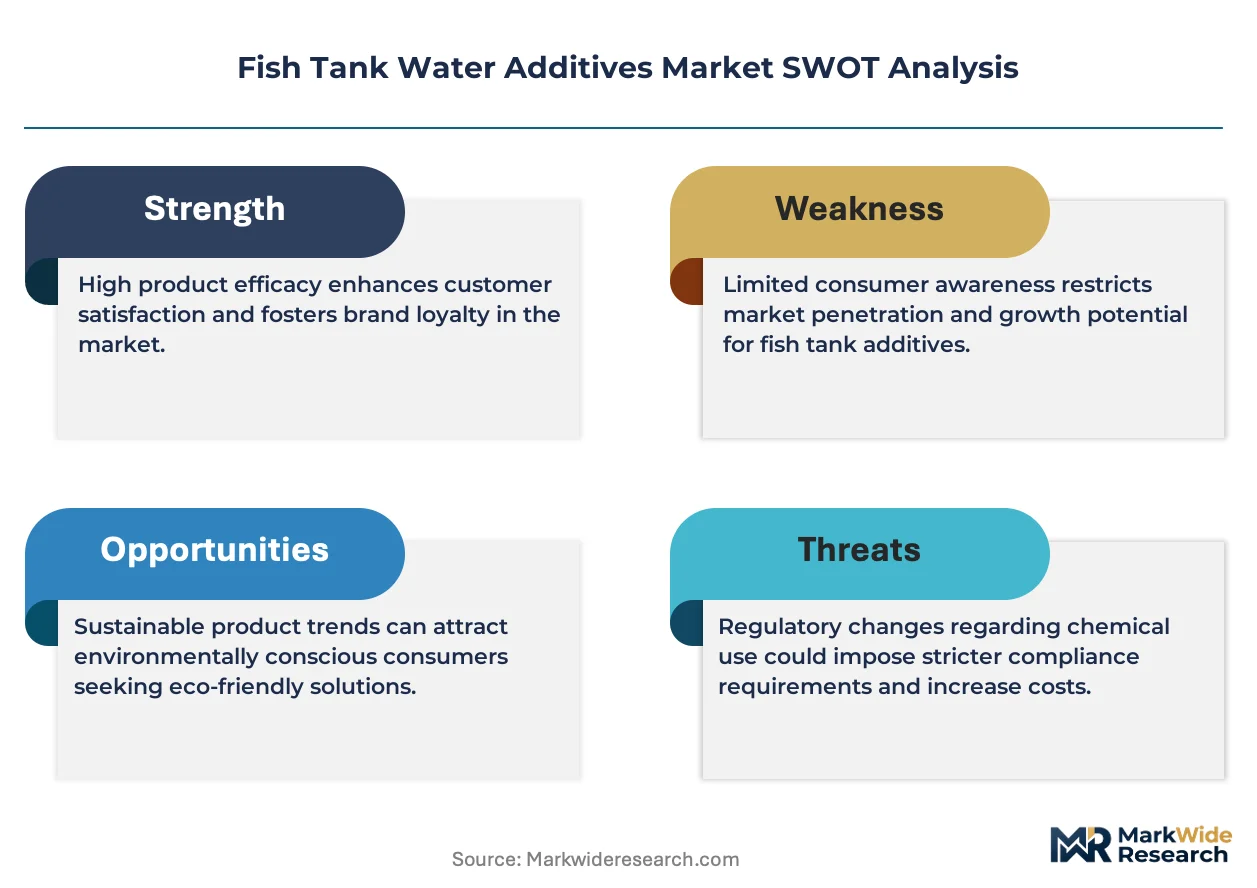
FIFRA registration deadlines function as a regulatory compounder, consolidating market share toward established formulators with dedicated compliance infrastructure as smaller competitors exit antimicrobial pathways.
For Market Incumbents: Hedge algaecide revenue exposure by accelerating peroxide-based formulation pipelines ahead of ECHA REACH sunset dates. Deepen backward integration into amine-based neutralizer synthesis to circumvent third-party distributor price volatility. Channel control through veterinary clinic partnerships anchors mass-market positioning against direct-to-consumer subscription erosion. For New Entrants and Emerging Players: Nano-tank precision conditioner buyers represent an underserved archetype with unmet demand for half-dose stability-engineered formats. Capture this white-space through smartphone-integrated dosing calculators and automated replenishment programs bypassing retail intermediaries. The most penetrable segment sits in coastal United States metropolitan clusters where specialty shop access has contracted. For Investors and Strategic Acquirers: Asymmetric upside sits with captive-synthesis specialists possessing in-house active ingredient purity control and existing EPA FIFRA registration infrastructure. Long-term viability over the projection horizon favors formulators with regulatory affairs depth over pure-play distribution brands. Watch ECHA REACH authorization timeline acceleration as the critical inflection signal for algaecide portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Seachem Laboratories demonstrates margin control through in-house thiosulfate purity management. |
| Direct-to-Consumer Subscription Launch | United States brands capture recurring revenue via IoT-linked dosing calculators bypassing retail. |
| Regulatory Compliance Infrastructure Investment | EPA FIFRA registration capabilities consolidate share as smaller competitors exit antimicrobial pathways. |
| Region-Specific Hardness Adjuster Development | Tetra anchors European demand through carbonate-rich municipal supply adaptation in Germany and Netherlands. |
| Peroxide-Based Algaecide Formulation Pipeline | Saltwater reef segments migrate ahead of quaternary ammonium compound regulatory sunset dates. |
Research Methodology
Bottom-up residential and aquaculture facility modeling reconciled against top-down chemical production tracking forms the analytical core of this study. Primary interviews with formulation chemists, specialty retail buyers, aquaculture procurement officers, and regulatory affairs directors combined with secondary validation from EPA FIFRA registration databases, ECHA biocidal product submissions, United States customs import records, and pet specialty chain SKU audits. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map thiosulfate and amine-based neutralizer feedstock flows through contract manufacturing tiers into packaged conditioner, dechlorinator, and biological supplement outputs across the analysis window. Segmentation dimensions include product type, application tier, end-user archetype, and distribution channel. CAGRs derive from trend-line extrapolation of nano-tank proliferation rates, municipal chloramine treatment adoption curves, and FIFRA registration pathway completion timelines.
Underlying measurement precision varies by segment; aquaculture facility procurement carries tighter precision than dispersed residential hobbyist demand. Forecasts reflect assumptions regarding REACH authorization enforcement intensity and EPA registration backlog clearance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
France Anti Caking Market