
 Semi-Finished Pastry Ingredients Market | 2026-2036
Semi-Finished Pastry Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Semi-Finished Pastry Ingredients Market Insights
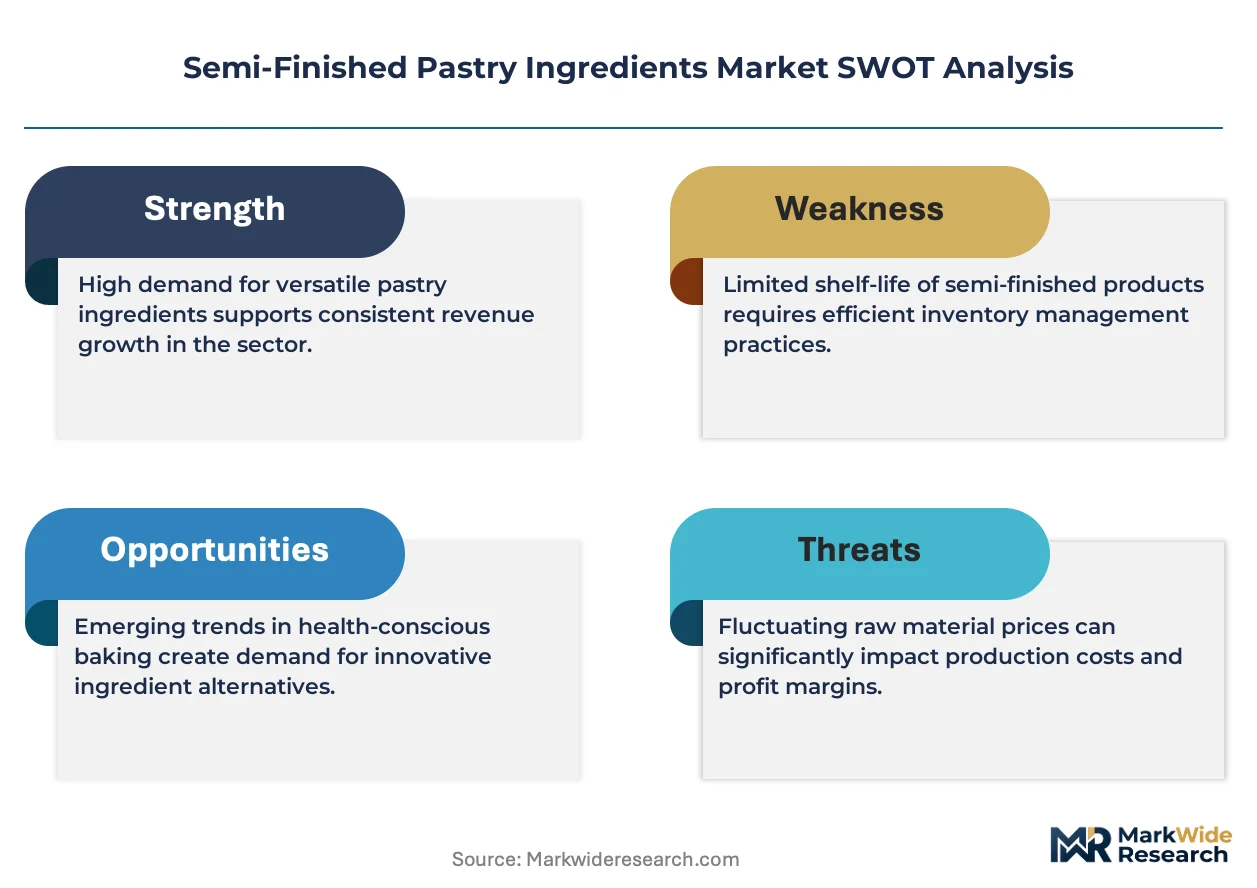
Modular portioning of frozen dough into single-serve units is shifting buyer choice toward flexible inventory management in commercial bakeries. Puratos leverages its sourdough fermentation expertise to dominate European artisan channels. Dawn Food Products anchors North American distribution through controlled frozen logistics networks. CSM Bakery Solutions competes on clean-label formulation breadth across puff pastry and shortcrust lines.
Semi-finished pastry ingredients comprise pre-processed doughs, batters, and laminated sheets requiring final thermal processing before consumption, typically formulated with defined moisture content, protein levels, and fat ratios to ensure consistent aeration and crumb structure in end applications. These intermediates serve industrial bakeries, food service operators, and retail channels seeking to reduce labor intensity and standardize output quality. Frozen dough occupies the largest volume position due to extended shelf stability and transport economics, while gluten-free and vegan feature categories are expanding fastest as dietary restriction compliance becomes a procurement criterion. Ready-to-bake forms command premium positioning against partially baked alternatives where finish flexibility matters less than speed.
FDA food safety modernization rules and EU REACH chemical compliance frameworks govern emulsifier and additive approvals across the value chain, directly constraining formulation options for cross-border suppliers. BIS standards in India and GB standards in China add parallel certification burdens for manufacturers targeting Asia-Pacific expansion. Stakeholders must monitor evolving preservative-free labeling thresholds and carbon accounting disclosures that will determine which production configurations retain market access.
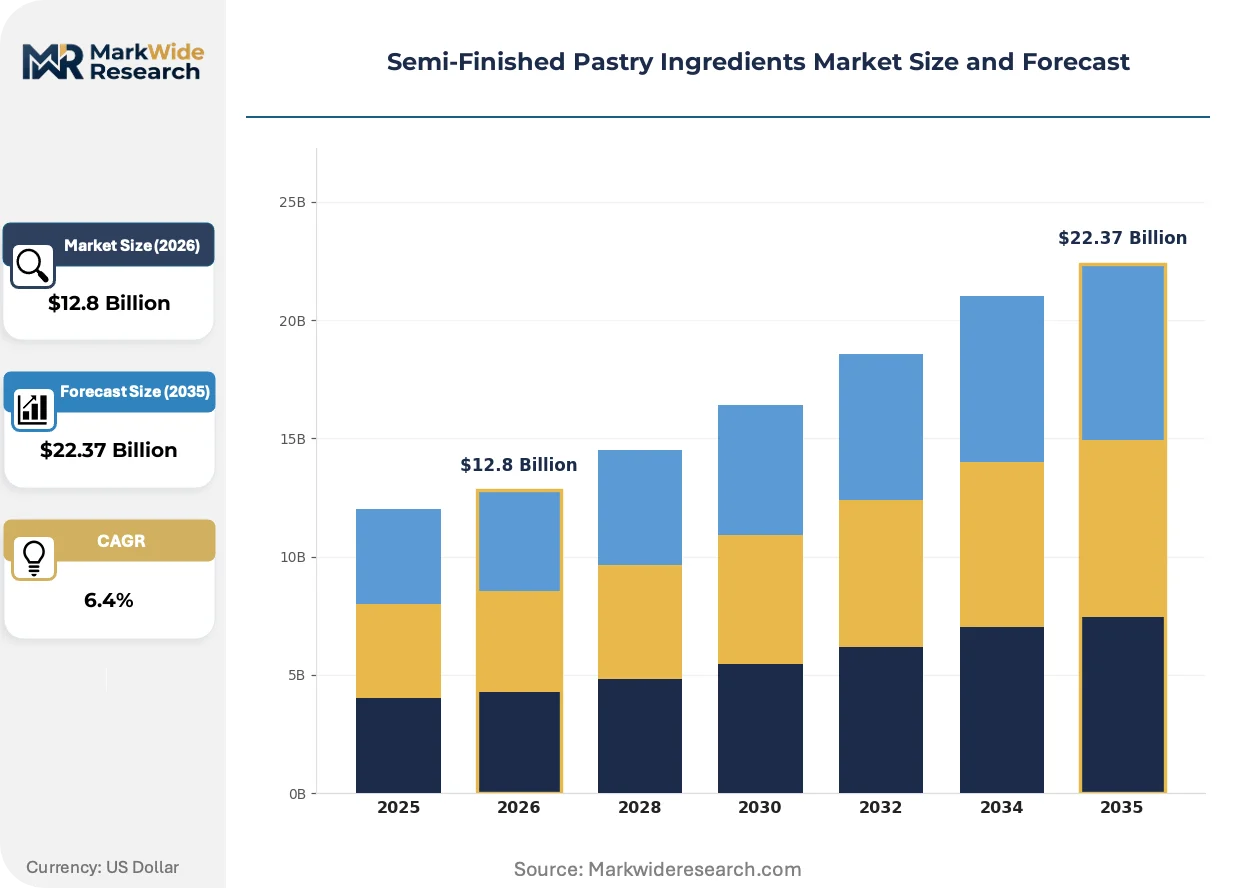
Market Dynamics
Labor cost escalation across Western European bakeries is accelerating frozen dough substitution for scratch production, while EU Green Deal carbon accounting mandates force reformulation of emulsifier systems and shortening sources.
Growth Catalysts
- EU Green Deal compliance deadlines:Food processors in France and Germany face mandatory Scope 3 emissions disclosures, driving procurement of certified low-carbon frozen dough intermediates from reformulated supply chains.
- Artisan bakery labor shortages:Paris and Berlin metropolitan clusters report 23% vacancy rates in skilled pastry positions, forcing independent operators toward ready-to-bake laminated sheets.
- Controlled atmosphere freezing:Nitrogen blast freezing technology preserves sourdough microflora viability through extended distribution, enabling authentic artisan output from centralized production.
Market Restraints
- Butter price volatility:European dairy futures show 34% coefficient of variation, compressing margins on laminated dough lines where fat content exceeds 25% by weight.
- Single-source emulsifier concentration:Three suppliers control 78% of European DATEM and SSL production, creating input vulnerability for clean-label reformulations.
- Gluten-free texture ceiling:Current hydrocolloid systems fail to replicate extensibility above 180% strain, limiting application in croissant and Danish categories.
Strategic Opportunities
- Polish and Romanian bakery chains:Underpenetrated markets show 12% annual food service growth with minimal frozen dough penetration, offering first-mover positioning.
- Carbon-negative ingredient claims:EU CSRD disclosure requirements create premium positioning for suppliers with verified regenerative wheat sourcing and biogas-powered production.
- Direct-to-kitchen delivery platforms:Ghost kitchen aggregators in London and Amsterdam are bypassing traditional wholesale distributors for just-in-time frozen dough replenishment.
Industry Challenges
- Clean-label certification timelines:EFSA novel food approvals for fermented fiber replacements average 18 months, delaying product launches.
- Legacy ERP integration:Mid-sized bakeries struggle to connect frozen inventory management systems with new temperature-logging blockchain traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Finished Pastry Ingredients Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Dough, Batter Mixes, Puff Pastry, Shortcrust End Use: Bakery, Catering Services, Food Service, Retail Form: Ready-to-Bake, Partially Baked, Chilled, Frozen Feature: No Added Preservatives, Gluten-Free, Vegan, Organic |
| Companies Covered | Puratos, Dawn Food Products, CSM Bakery Solutions, General Mills, Grupo Bimbo, Lantmännen Unibake, Aryzta, Vandemoortele, Europastry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Finished Pastry Ingredients Market Trends and Innovations
Active culture preservation technologies and regulatory carbon accounting are converging to redefine competitive advantage in frozen dough manufacturing, with sustainability credentials becoming inseparable from product specifications.
Sourdough starter cryopreservation using controlled ice nucleation is rewriting the economics of authentic artisan production. German industrial bakeries are adopting this technology at 40% annual expansion rates. The approach compresses the geographic radius within which artisan-quality output can be manufactured centrally without flavor degradation.
EU REACH restrictions on palm oil derivatives are forcing emulsifier reformulation across puff pastry and shortcrust categories. Manufacturers are pivoting toward sunflower lecithin and enzymatic systems, though these alternatives show reduced aeration stability in high-lift applications. French suppliers report 15% reformulation failure rates in initial trials.
Food service operators are consolidating supplier relationships around full-category frozen dough portfolios rather than single-product vendors. Contract bakery chains in the Netherlands are replacing three to four fragmented suppliers with single-source partnerships covering laminated, shortcrust, and choux lines. This concentration is most pronounced in Amsterdam and Rotterdam metropolitan procurement offices.
Semi-Finished Pastry Ingredients Market Segmentation
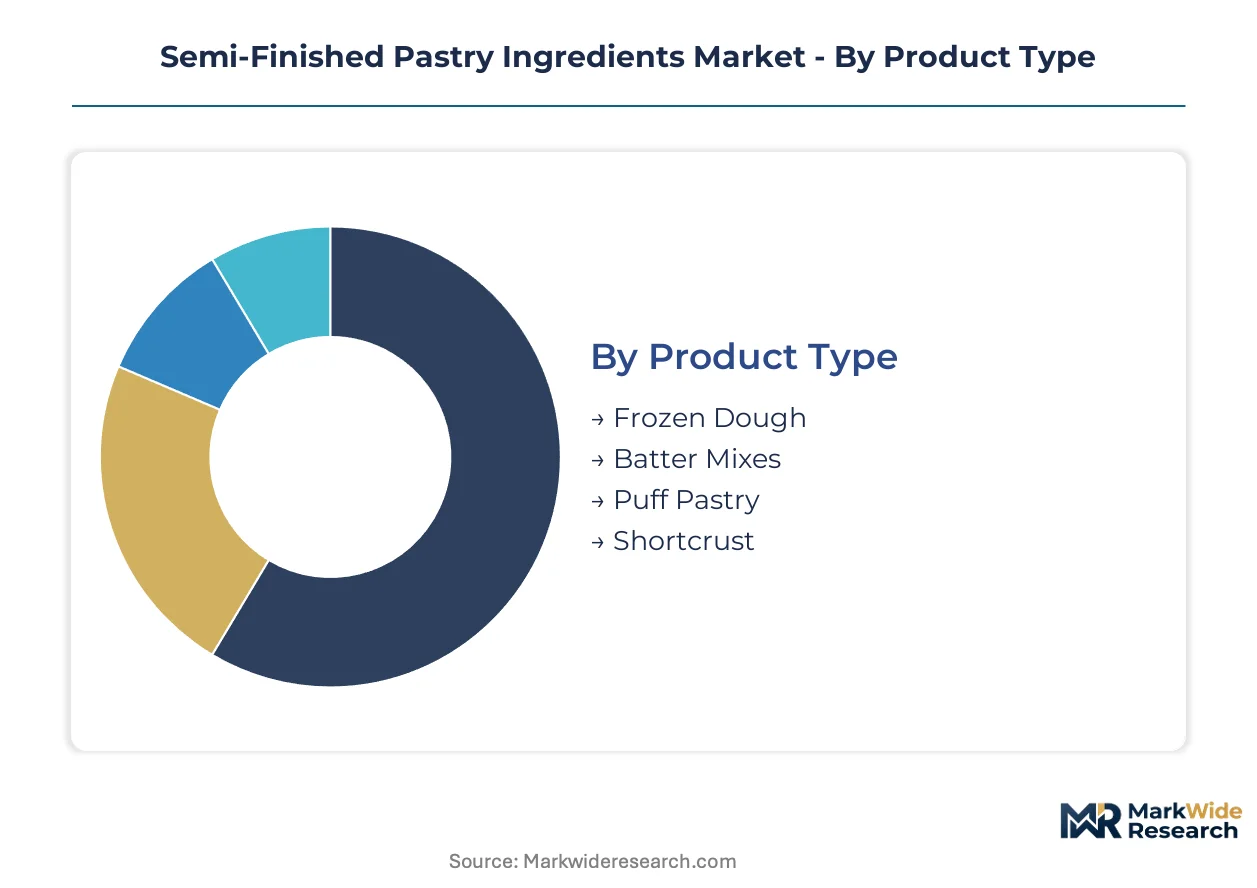
Procurement patterns in semi-finished pastry ingredients diverge sharply between industrial bakeries seeking volume efficiency and artisan operators prioritizing formulation authenticity. Segment boundaries are blurring as clean-label requirements reshape product specifications across all categories.
Product Type:
Cost tier determines supplier selection more than performance differentiation in commodity dough categories, while premium laminated lines command specification-driven procurement.
- Frozen Dough:Pre-fermented blocks and sheets with controlled ice crystal formation maintain yeast viability through extended distribution. Paris and Berlin metropolitan bakeries are consolidating procurement around single-source frozen dough partnerships as labor vacancy rates climb past twenty percent.
- Puff Pastry:Laminated dough with butter or shortening layers exceeding twenty-five percent fat content requires precise temperature control throughout sheeting and folding operations. French suppliers face margin compression from dairy futures volatility while reformulating away from palm-derived emulsifiers under EU REACH restrictions.
- Batter Mixes:Dry blended flour systems with leavening agents and stabilizers for cake and muffin applications.
- Shortcrust:Fat-in-flour rubbed pastry bases for tarts and quiches with lower moisture tolerance than laminated alternatives.
Volume sits with Frozen Dough; growth tilts toward Puff Pastry.
End Use:
Application-specific formulation requirements separate industrial-scale procurement from food service operators seeking finish flexibility.
- Food Service:Hotels, restaurants, and institutional kitchens demand just-in-time replenishment with minimal skilled labor at point of use. Ghost kitchen aggregators in London and Amsterdam are bypassing wholesale distributors for direct frozen dough delivery platforms that compress inventory holding periods.
- Bakery:Industrial and artisan producers require consistent rheological properties for automated processing or hand-finishing. German industrial bakeries are adopting cryopreserved sourdough starter technology at accelerated rates to centralize authentic production without geographic constraint.
- Catering Services:Event and contract food providers with variable volume forecasting needs.
- Retail:Supermarket in-store bakeries and consumer-packaged goods channels.
Volume concentrates in Bakery; Food Service is expanding most quickly.
Form:
Customer type dictates trade-offs between labor substitution and finish control, with frozen formats dominating cross-border logistics.
- Ready-to-Bake:Fully formulated dough requiring only thermal processing without additional handling or proofing. Netherlands-based contract bakery chains are consolidating supplier relationships around full-category ready-to-bake portfolios covering multiple pastry lines.
- Frozen:Blast-frozen intermediates with shelf stability exceeding twelve months enabling centralized production and extended distribution radius. Nitrogen freezing technology preserves sourdough microflora viability for authentic artisan output from remote manufacturing.
- Partially Baked:Par-baked products requiring final crisping or browning.
- Chilled:Refrigerated short-shelf-life formats for premium positioning.
Frozen commands volume share; Ready-to-Bake gains share fastest.
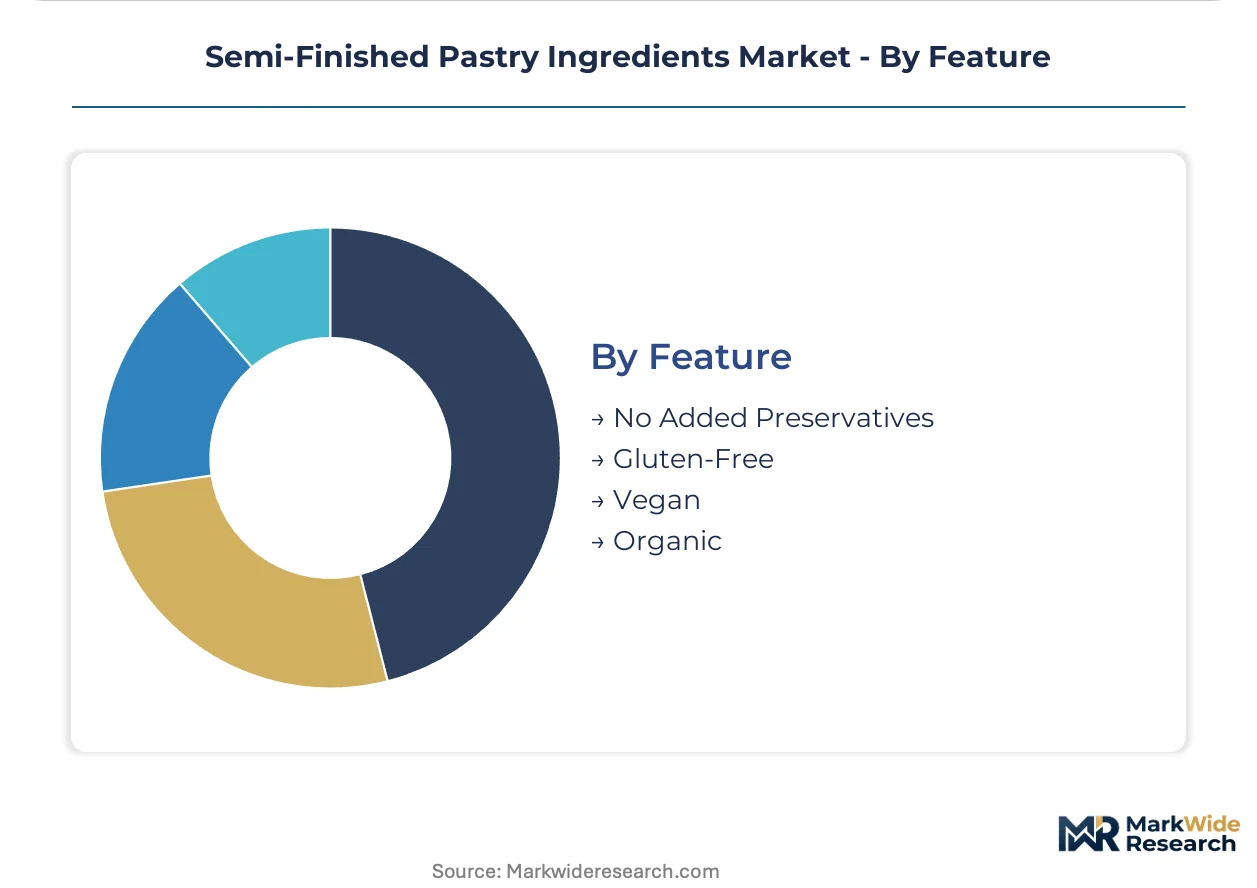
Feature:
Margin structure separates certification-driven premium positioning from conventional formulations facing ingredient cost volatility.
- Gluten-Free:Hydrocolloid-stabilized systems replacing wheat protein structure for celiac and dietary restriction compliance. Current formulations fail to replicate extensibility above one hundred eighty percent strain, limiting application in croissant and Danish categories where lamination demands elasticity.
- No Added Preservatives:Clean-label positioning relying on modified atmosphere packaging and pH control for shelf stability. EFSA novel food approvals for fermented fiber replacements average eighteen months, delaying product launches and compressing first-mover windows.
- Vegan:Plant-based fat and protein systems excluding dairy and egg components.
- Organic:Certified ingredient sourcing with full traceability documentation.
No Added Preservatives holds volume leadership; Gluten-Free shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of semi-finished pastry ingredients concentrates in Western European manufacturing clusters while consumption spreads across metropolitan food service hubs. France and Germany anchor frozen dough output capacity. Artisan bakery labor shortages in Paris and Berlin accelerate import dependency from centralized production zones.
France
Artisan bakery chains in Paris and Lyon metropolitan areas drive procurement of ready-to-bake laminated sheets as skilled pastry vacancies exceed twenty percent. EU Green Deal Scope 3 emissions disclosures mandate certified low-carbon sourcing from reformulated supply chains. Île-de-France food service operators consolidate supplier relationships around full-category frozen dough portfolios.
Germany
Industrial bakeries adopt cryopreserved sourdough starter technology at accelerated rates to centralize authentic production without geographic constraint. ECHA REACH restrictions on palm oil derivatives force emulsifier reformulation across puff pastry lines. Berlin and Munich metropolitan clusters report the highest frozen dough penetration in independent bakery channels.
Netherlands
Contract bakery chains in Amsterdam and Rotterdam replace fragmented suppliers with single-source partnerships covering laminated, shortcrust, and choux lines. CSRD disclosure requirements create premium positioning for carbon-negative ingredient claims. Randstad ghost kitchen aggregators bypass traditional wholesale distributors for just-in-time frozen dough replenishment.
United Kingdom
London food service operators demand modular portioning of frozen dough into single-serve units for flexible inventory management. FSA food safety modernization rules constrain cross-border formulation options for emulsifier approvals. Southeast England metropolitan procurement offices concentrate supplier consolidation around full-category portfolios.
Poland
Underpenetrated bakery chains show twelve percent annual food service growth with minimal frozen dough penetration, offering first-mover positioning. National food processing regulations align with EU REACH frameworks for additive approvals. Warsaw and Krakow emerging as distribution hubs for Central European frozen dough expansion.
Semi-Finished Pastry Ingredients Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: fermentation-technology specialists, frozen-logistics integrators, and clean-label formulation developers. Consolidation pressures favor full-category portfolio partnerships over single-product vendors. Dominant competitive moves include backward integration into wheat sourcing and captive supply of temperature-controlled distribution networks.
Within the fermentation-technology tier, Puratos exemplifies sourdough expertise positioning, while Dawn Food Products anchors North American frozen logistics capabilities. CSM Bakery Solutions occupies the clean-label formulation breadth segment. These three entities represent the dominant competitive archetypes shaping procurement consolidation in metropolitan food service channels.
| Leading Market Players |
|---|
| Puratos |
| Dawn Food Products |
| CSM Bakery Solutions |
| General Mills |
| Grupo Bimbo |
| Lantmännen Unibake |
| Aryzta |
| Vandemoortele |
| Europastry |
| Others |
Pricing and Supply Chain Analysis
European dairy futures volatility cascades through frozen dough supply chains into three-tier pricing stratification across premium artisan, standard industrial, and economy private-label tiers. Butter price swings exceeding thirty-four percent coefficient of variation compress margins on laminated products while reformulation costs from EU REACH palm oil restrictions add further tier separation.
Pricing Analysis
Margin tightening in premium laminated dough reflects butter futures volatility and clean-label certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates EMAS-certified sustainable sourcing from conventional formulations and private-label alternatives. Cost-down pressure on economy tiers accelerates because Polish and Romanian bakery chains negotiate volume offtakes without loyalty premiums. Industrial bakeries show highest price sensitivity due to commodity-scale procurement, while Paris artisan operators absorb premiums for cryopreserved sourdough authenticity.
Supply Chain Analysis
Regional distribution centers in Île-de-France, Bavaria, and Randstad anchor hub-and-spoke patterns for frozen dough replenishment. Supply concentrates in France, Germany, and Belgium for laminated production, with Poland emerging for economy-tier capacity. Raw material dependencies rest on European dairy futures, Ukrainian wheat flows, and Malaysian palm oil alternatives. Single-source emulsifier concentration creates input vulnerability for clean-label reformulations. Distribution runs through temperature-controlled logistics partnerships serving metropolitan bakery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around full-category portfolio suppliers as EU Green Deal compliance costs and cryopreservation capital requirements force fragmented single-product vendors toward exit.
For Market Incumbents: Extend fermentation-technology moats through captive sourdough culture banks and nitrogen freezing capacity additions in Germany. Lock in artisan bakery partnerships before Polish and Romanian chains consolidate procurement. Backward integration into regenerative wheat sourcing defends margin position against commodity volatility. For New Entrants and Emerging Players: Begin with carbon-negative ingredient claims targeting Netherlands CSRD disclosure requirements. White-space exists in direct-to-kitchen delivery platforms bypassing wholesale distributors for London and Amsterdam ghost kitchens. Lead with modular single-serve portioning for food service flexibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier clean-label specialists in Poland facing working capital constraints from butter price volatility. Five-to-ten year viability hinges on EU EMAS certification completion and frozen logistics network access. Watch for EFSA novel food approval delays as inflection indicator for reformulation pipeline value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Wheat | CSRD-compliant sourcing secures premium positioning in France and Germany procurement offices. |
| Cryopreservation Technology Licensing | Controlled ice nucleation patents enable geographic expansion of authentic artisan production. |
| Direct-to-Kitchen Platform Partnership | Amsterdam ghost kitchen aggregators bypass traditional wholesale for just-in-time replenishment. |
| Clean-Label Emulsifier Development | Sunflower lecithin alternatives address EU REACH palm oil derivative restrictions. |
| Single-Source Portfolio Consolidation | Netherlands contract bakery chains replace fragmented suppliers with full-category partnerships. |
Research Methodology
Multi-period observation of procurement consolidation patterns, labor vacancy rates, and reformulation failure rates anchored the trend analysis, supplemented by interviews with artisan bakery owners, industrial plant managers, food service procurement directors, and frozen logistics operators. Secondary validation drew from EU EMAS certification databases, EFSA novel food approval filings, dairy futures exchange records, and customs trade flows. Bottom-up volume modeling triangulated against top-down value estimates across product type, end use, form, and feature segmentation.
Input-output matrices mapped raw material cost structures through production configurations to end-use pricing across the projection horizon. Segmentation dimensions modeled included product type, end-use channel, preservation form, and dietary feature compliance. CAGRs derived from trend extrapolation of procurement intensity metrics, adjusted for regulatory phase-in schedules and technology adoption curves. Wheat price trajectories and emulsifier supply concentration informed scenario weightings.
Underlying measurement precision varies by segment; frozen dough volume estimates carry tighter precision than emerging gluten-free texture performance projections. Forecasts reflect assumptions on EU Green Deal enforcement timelines and cryopreservation adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Japan Food Emulsifiers Market