
 North America Corrugated Packaging Market | 2026-2036
North America Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Corrugated Packaging Market Outlook
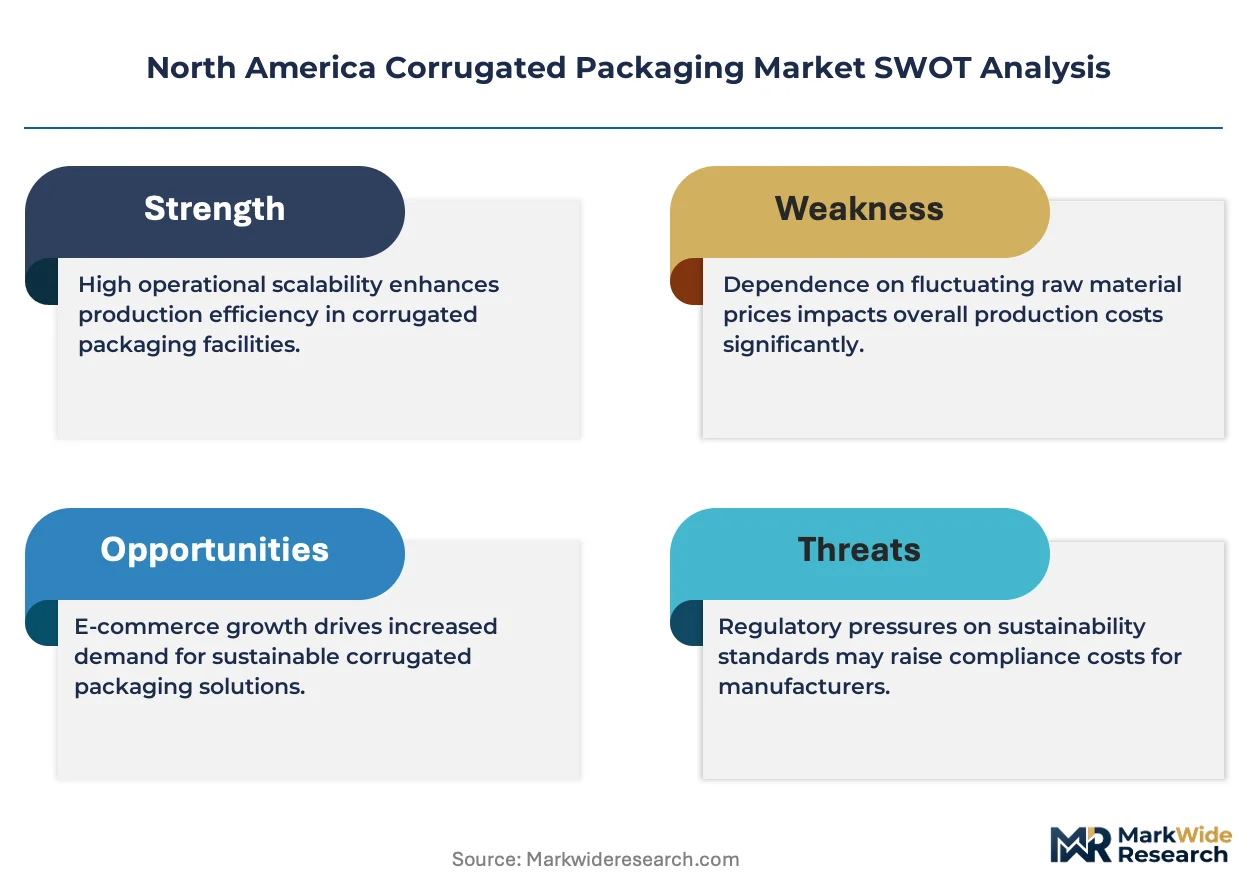
EPA recycled-content thresholds for paper-based packaging is decoupling virgin fiber economics from traditional cost structures across the value chain. International Paper Company leverages its integrated pulp-to-box infrastructure to sustain margin capture under tightening fiber rules. Smurfit Westrock anchors North American capacity through mill network density that competitors struggle to replicate. Packaging Corporation of America differentiates via lightweight flute engineering that reduces dimensional weight charges for e-commerce shippers.
Corrugated packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed from kraft paper with burst strengths ranging from 200 to 1,100 pounds per square inch depending on wall construction. The material functions primarily as protective, stackable, and printable secondary packaging for goods in transit and retail display. Boxes dominate product type revenue due to universal applicability across fulfillment channels, while kraft paper commands material preference for its tensile strength and recyclability profile. E-commerce as a distribution channel carries the fastest expansion trajectory, though direct sales to large food and beverage accounts retains the deepest margin pools.
FDA food-contact substance regulations, EPA recycled fiber mandates, and OSHA workplace safety standards collectively govern material selection, plant emissions, and box plant operating protocols across the United States and Canada. These frameworks elevate compliance costs for smaller converters while rewarding capital-intensive players with certified recycling streams and automated hazard controls. Stakeholders must monitor how state-level extended producer responsibility bills in California and New York reshape post-consumer collection economics and linerboard feedstock availability.
Market Dynamics
EPA recycled-content mandates are decoupling virgin fiber economics from traditional cost structures, forcing converters to reconfigure mill networks and box plant operations across the United States and Canada.
Growth Catalysts
- E-commerce fulfillment networks:Direct-to-consumer shipping volumes are expanding box demand across Michigan, Ohio, and Illinois distribution corridors.
- OSHA workplace safety standards:Automated hazard controls at box plants are reducing injury rates while accelerating throughput in high-volume facilities.
- Kraft linerboard innovations:Lightweight flute engineering is cutting dimensional weight charges for parcel carriers serving food and beverage accounts.
Market Restraints
- Recycled fiber supply concentration:Post-consumer collection economics in California and New York constrain linerboard feedstock availability for smaller converters.
- Old corrugated container price volatility:OCC bale costs swing with municipal collection program participation rates across the Great Lakes region.
- Substitution by reusable totes:Closed-loop packaging systems are capturing share in automotive parts logistics between Detroit and Windsor.
Strategic Opportunities
- Canadian prairie expansion:Underpenetrated agricultural packaging demand in Saskatchewan and Manitoba offers greenfield box plant positioning.
- State-level extended producer responsibility bills:Post-consumer collection mandates in California are creating certified recycling stream premiums for integrated producers.
- Digital printing convergence:Variable-data corrugated displays are displacing pre-printed litho labels in seasonal retail campaigns.
Industry Challenges
- Automated converting technician shortage:Box plants struggle to staff flexo folder-gluer operations with certified maintenance personnel.
- FDA food-contact substance certification timelines:New barrier coatings for direct food packaging face extended safety review backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Corrugated Packaging Market |
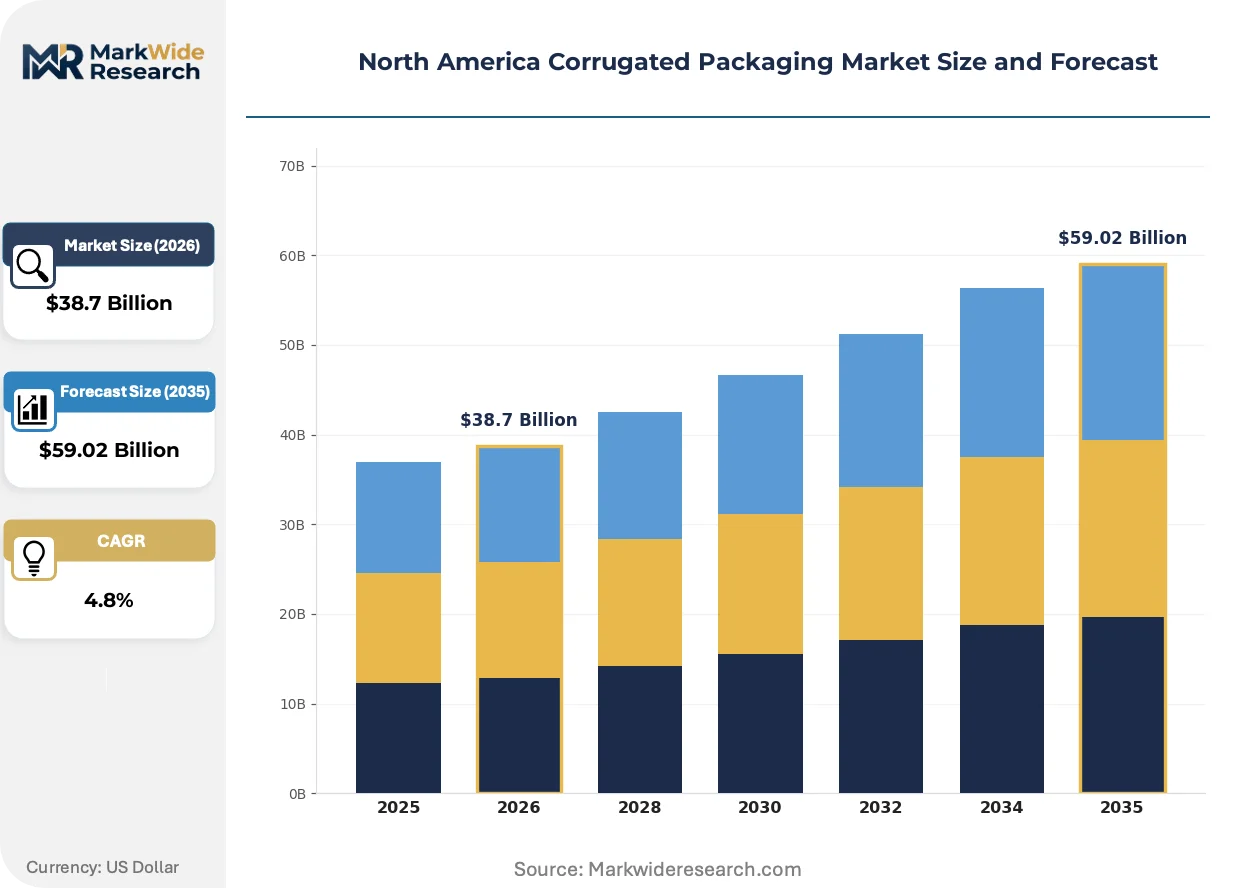
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Crates, Sheets Material: Recycled Paper, Duplex Board, Kraft Paper, Others End User: Food & Beverage, Electronics, Pharmaceuticals, Household Goods Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale |
| Companies Covered | International Paper Company, Smurfit Westrock, Packaging Corporation of America, Georgia-Pacific LLC, Mondi Group, DS Smith, Cascades Inc., Oji Holdings Corporation, Rengo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Corrugated Packaging Market Strategic Shifts
Corrugated packaging is absorbing digital and material innovations that compress production cycles and expand functional performance beyond traditional containment roles.
Water-based flexographic printing with expanded-gamut color management is absorbing short-run customization demand that previously required litho lamination. Food and beverage brand managers in Chicago and Toronto are adopting seven-color process systems for seasonal promotional campaigns. This technology is absorbing margin pressure from minimum order quantity reductions while enabling just-in-time graphic refreshes.
EPA recycled fiber mandates are tightening post-consumer content thresholds for paper-based packaging sold into federal procurement channels. Integrated mill-to-box producers with certified recycling streams are capturing compliance premiums while standalone converters face feedstock certification costs. The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Illinois is responding fastest due to proximity to established OCC collection infrastructure.
Shippers are consolidating corrugated specifications across fulfillment channels to reduce SKU complexity in warehouse management systems. E-commerce operations are displacing retail-ready packaging with dual-purpose designs that survive parcel transit and shelf presentation. This pattern is most visible in health and personal care distribution through Dallas-Fort Worth and Atlanta regional hubs.
North America Corrugated Packaging Market Segmentation
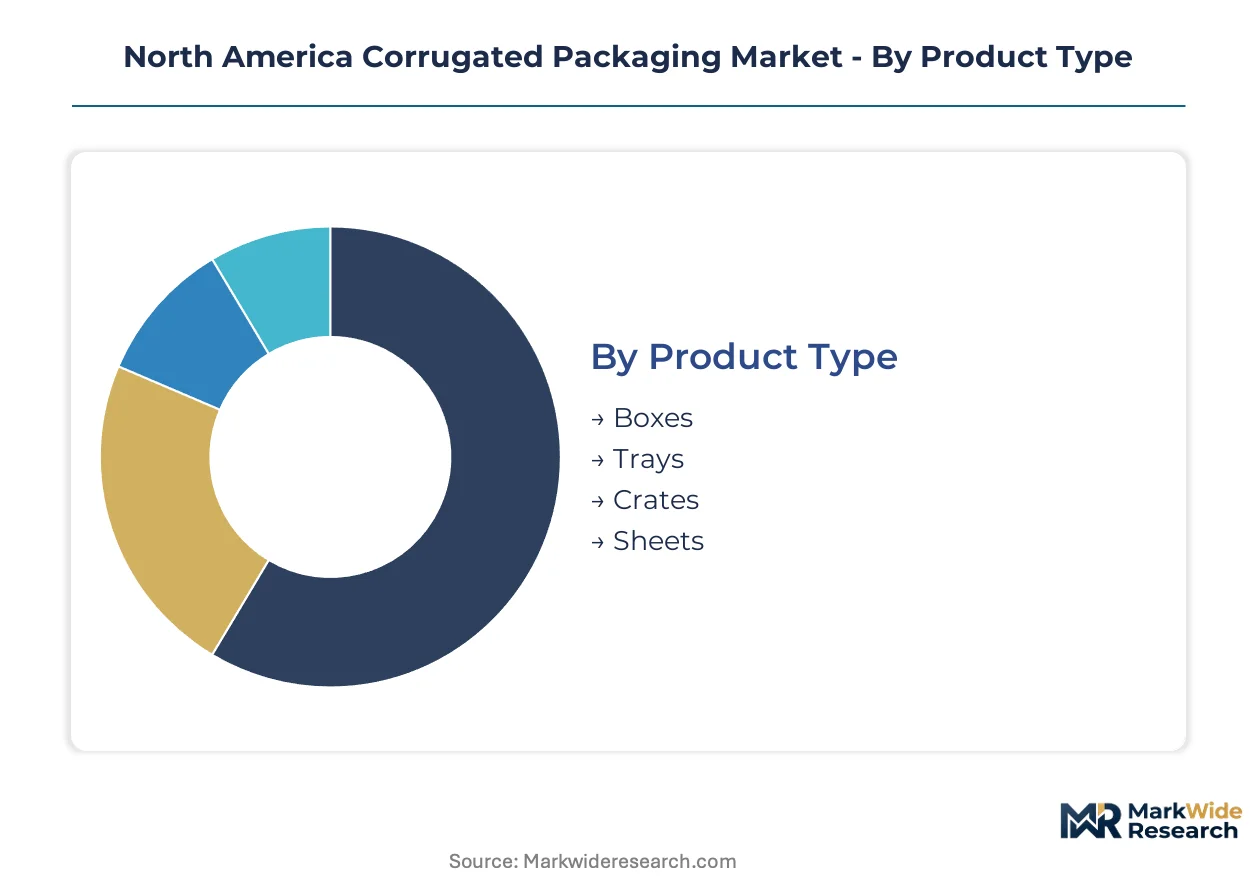
Corrugated packaging segmentation reflects divergent technical requirements across fulfillment channels. Product geometry, fiber composition, and channel economics each create distinct margin pools and capacity allocation decisions across the United States and Canada.
Product Type:
Standardization dominates at the commodity end while customization concentrates in protective formats for fragile goods.
- Boxes:RSC and FOL styles constructed from 32 ECT to 44 ECT board handle the majority of parcel shipments. Michigan and Ohio box plants run these formats at highest throughput for e-commerce fulfillment centers.
- Trays:Die-cut designs with display-ready graphics serve retail-ready produce and club store packaging. Chicago-area converters specialize in high-graphic trays for food and beverage accounts requiring shelf impact.
- Crates:Heavy-duty triple-wall constructions protect automotive components in Detroit-Windsor logistics corridors.
- Sheets:Unconverted linerboard layers function as pallet pads and void fill across Great Lakes distribution networks.
Most installed capacity flows through Boxes. Expansion is steepest in Trays.
Material:
Cost tiers separate virgin fiber premiums from recycled feedstock commoditization.
- Kraft Paper:Virgin unbleached pulp delivers burst strengths exceeding 275 psi for heavy-load applications. Food and beverage shippers in California specify kraft linerboard for moisture resistance in produce distribution.
- Recycled Paper:Post-consumer OCC pulp forms the basis of 200-series board grades. EPA procurement mandates are accelerating certified recycled content adoption across federal supply chains.
- Duplex Board:Clay-coated white top layers enable high-fidelity printing for retail display packaging. Toronto-area health and personal care brands specify duplex for shelf differentiation.
- Others:Specialty barrier coatings and flame-retardant treatments serve niche pharmaceutical and electronics applications.
Kraft Paper commands the deepest margin pools. Recycled Paper is climbing the fastest as regulatory thresholds tighten.
End User:
Volume concentration versus margin sophistication shapes converter targeting strategies.
- Food & Beverage:Moisture-resistant coatings and FDA-compliant barriers dominate specifications. Direct sales relationships with Illinois dairy and California produce distributors sustain long-term contract volumes.
- Electronics:Anti-static coatings and precision-fit inserts protect high-value components. Dallas-Fort Worth fulfillment hubs for consumer electronics drive anti-static corrugated demand.
- Pharmaceuticals:Serialization-ready surfaces and temperature-stable constructions meet Health Canada and FDA distribution requirements.
- Household Goods:Standard-duty board suffices for non-fragile consumables with lower damage liability thresholds.
Food & Beverage absorbs the greatest tonnage. Electronics is gaining share fastest on per-unit value metrics.
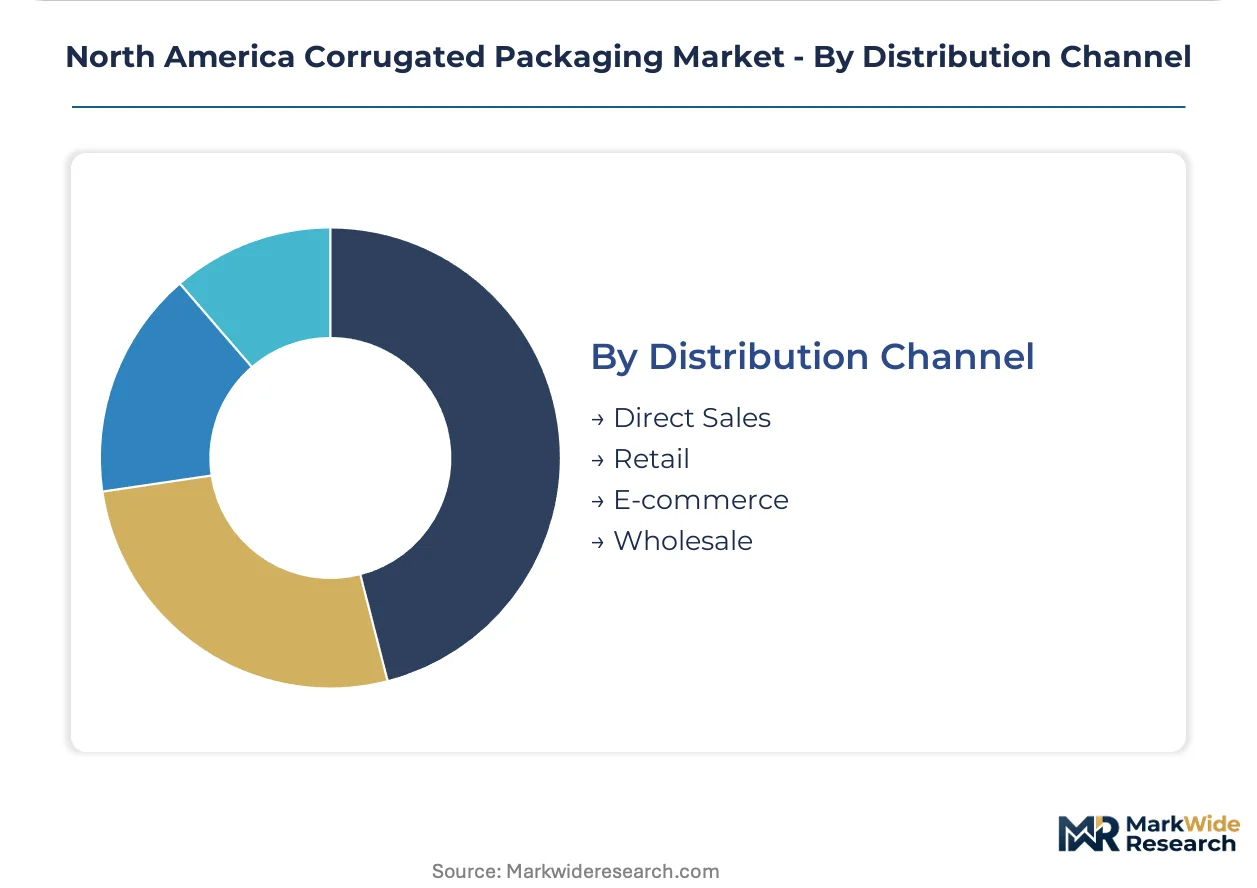
Distribution Channel:
Customer type determines order cadence, specification complexity, and relationship economics.
- E-commerce:Variable-dimension designs with burst strengths optimized for parcel carrier sorting systems. Ohio and Michigan regional hubs for national e-tailers specify lightweight flute to minimize dimensional weight charges.
- Direct Sales:Long-term contracts with integrated mill-to-box producers anchor capacity planning for food and beverage accounts. International Paper and Smurfit Westrock dominate direct sales relationships through captive linerboard supply.
- Retail:Seasonal promotional cycles drive short-run, high-graphic requirements with compressed lead times.
- Wholesale:Stock box distributors serve small and mid-sized accounts with limited customization needs.
Direct Sales captures the most stable margin pools. E-commerce is expanding most quickly on shipment volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled converting technicians and flexographic press operators concentrate in the Great Lakes manufacturing corridor, anchoring North American corrugated capacity. This workforce density shapes regional investment patterns and plant location decisions. The analysis examines three countries where production clusters, regulatory frameworks, and demand drivers create distinct competitive environments.
United States
E-commerce fulfillment centers in Ohio and Michigan drive box demand through regional distribution hubs. EPA recycled fiber mandates tighten procurement standards for federal packaging contracts. Chicago-area converters specialize in high-graphic retail trays for food and beverage accounts requiring shelf differentiation.
Canada
Agricultural packaging demand in Saskatchewan and Manitoba remains underpenetrated relative to US Midwest benchmarks. Health Canada and PMRA pharmaceutical distribution requirements shape barrier coating specifications for temperature-stable constructions. Toronto-area health brands specify clay-coated duplex board for retail display differentiation.
Mexico
Nearshoring manufacturing investments in Nuevo León and Baja California generate protective packaging demand for automotive and electronics exports. Mexico's environmental regulator SEMARNAT implements packaging waste reduction programs affecting post-consumer collection economics. Mexico City Metro distribution corridors handle growing cross-border e-commerce parcel volumes.
North America Corrugated Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure consolidates around integrated mill-to-box producers with captive linerboard supply and standalone converters dependent on spot fiber markets. Three archetypes dominate: vertically integrated giants with pulp-to-box infrastructure, regional specialists with lightweight engineering capabilities, and diversified materials conglomerates with packaging divisions. Capacity expansion and certified recycling stream development represent the dominant competitive moves reshaping positioning.
Within the integrated producer tier, International Paper Company and Smurfit Westrock exemplify scale-driven archetypes with mill network density. Packaging Corporation of America occupies a position representing lightweight flute engineering specialization. These three entities anchor competitive dynamics through distinct strategic postures rather than overlapping capability claims.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Westrock |
| Packaging Corporation of America |
| Georgia-Pacific LLC |
| Mondi Group |
| DS Smith |
| Cascades Inc. |
| Oji Holdings Corporation |
| Rengo Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive mill-to-box integration anchors both supply security and pricing power for corrugated producers across the United States and Canada. Integrated players with in-house linerboard production command premium contract terms while standalone converters absorb OCC spot market volatility.
Pricing Analysis
Bundled design-and-deliver services capture premium margins against unbundled commodity box sales. Three-tier pricing structure across premium, standard, and economy levels separates certified recycled-content contracts from virgin kraft specifications and generic stock grades. Price differentiation hinges on EPA compliance certification and volume scale commitments. Pricing pressure stems from lightweight flute engineering commoditizing protective performance. Small and mid-sized e-commerce shippers exhibit highest price sensitivity; integrated food and beverage accounts with direct mill relationships show least.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale linerboard demand from integrated producers, while distributor networks serve fragmented small-account demand. Geographic supply concentrates in the United States, Canada, and Mexico. Raw material dependencies center on old corrugated container bales, virgin kraft pulp, and starch adhesives. Supply chain risk runs through single-source OCC collection concentration in California and New York municipal programs. Distribution runs through regional box plant networks anchored in the Great Lakes manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Corrugated Packaging Market functions as a regulatory compounder where EPA recycled fiber mandates continuously tighten procurement standards and reward certified stream investment.
For Market Incumbents: Cement mill network density advantages through certified recycling stream expansion in the Great Lakes corridor. Lock in long-term direct sales relationships with food and beverage accounts before state-level extended producer responsibility bills reshape collection economics. Channel control over linerboard feedstock remains the critical defensive lever against lightweight flute commoditization. For New Entrants and Emerging Players: Enter via agricultural packaging specialization in Saskatchewan and Manitoba where box plant penetration lags US Midwest benchmarks. Target produce distribution cooperatives seeking moisture-resistant kraft specifications absent from incumbent catalogs. A digital printing convergence play for seasonal retail campaigns offers the most penetrable wedge against litho-laminated incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone converters face feedstock certification costs that integrated producers absorb through captive recycling infrastructure. Five-to-ten-year viability favors mill-to-box specialists with OCC stream control over pure-play converters dependent on spot fiber markets. Watch California and New York extended producer responsibility implementation timelines as inflection signals for feedstock cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Recycling Stream Development | EPA procurement mandates reward verified post-consumer content with compliance premiums in federal contracts. |
| Lightweight Flute Engineering Investment | Dimensional weight charge reduction strengthens positioning with Ohio and Michigan e-commerce fulfillment hubs. |
| Digital Printing Capability Expansion | Seven-color flexo systems displace litho lamination for Chicago and Toronto seasonal promotional campaigns. |
| Canadian Prairie Box Plant Positioning | Underpenetrated Saskatchewan and Manitoba agricultural demand offers greenfield capacity with limited incumbent presence. |
| Direct Sales Relationship Deepening | Long-term food and beverage contracts anchor capacity planning against e-commerce volume volatility. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down mill capacity tracking forms the analytical core of this study. Primary interviews with box plant operations managers, linerboard procurement directors, e-commerce fulfillment center packaging engineers, and retail category buyers combined with secondary validation from EPA procurement databases, American Forest and Paper Association industry statistics, and SEC 10-K filings from integrated producers. Triangulation across these sources ensures demand estimates align with verified supply-side capacity announcements.
Historical trendline analysis of linerboard pricing cycles, OCC bale cost movements, and box plant operating rates informed projection frameworks across the analysis window. Segmentation modeling incorporated product type geometry, material fiber composition, end-use damage liability thresholds, and distribution channel order cadence. CAGRs derived from regression-adjusted growth rates applied to verified baseline consumption figures, with e-commerce shipment velocity and EPA mandate phase-in schedules serving as primary forecast inputs.
The model holds under stable recycled fiber collection economics and incremental regulatory tightening; deviation in California or New York extended producer responsibility implementation intensity would shift feedstock cost assumptions materially. Periodic stress-testing of base assumptions against OCC price volatility and lightweight substitution rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Kraftliner Market