

Protective Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Paperboard Market Insights
Aftermarket recycling and closed-loop fiber recovery is reconfiguring margin pools across the protective paperboard value chain. Smurfit Westrock leverages integrated containerboard and recycling infrastructure across Europe and the Americas. DS Smith anchors its competitive position through lightweight corrugated innovation and e-commerce fulfillment specialization. Mondi plc differentiates via sustainable kraft paper solutions and barrier-coated grades for sensitive electronics.
Protective paperboard denotes engineered paper-based materials—typically multi-ply constructions ranging from 200 to 500 grams per square meter—manufactured through kraft pulping, bleaching, and calendering to deliver puncture resistance, moisture buffering, and structural cushioning for transit-sensitive goods. Solid bleached sulfate dominates pharmaceutical and food-contact applications where purity and printability command premium positioning, while molded fiberboard is gaining fastest in electronics protection as brands eliminate expanded polystyrene. Coated paperboard captures concentrated margin pools in luxury goods wrapping where surface aesthetics and tactile finish drive buyer selection.
The EPA governs recycled content claims and fiber sourcing disclosures in the United States, while REACH and the EU Green Deal mandate chemical safety and carbon footprint reductions across European supply chains. FDA food-contact regulations and EU MDR medical device packaging standards shape product certification requirements and market access thresholds for protective paperboard used in pharmaceutical and food applications. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in regional recycling infrastructure or outsource compliance to specialized fiber recovery partners.
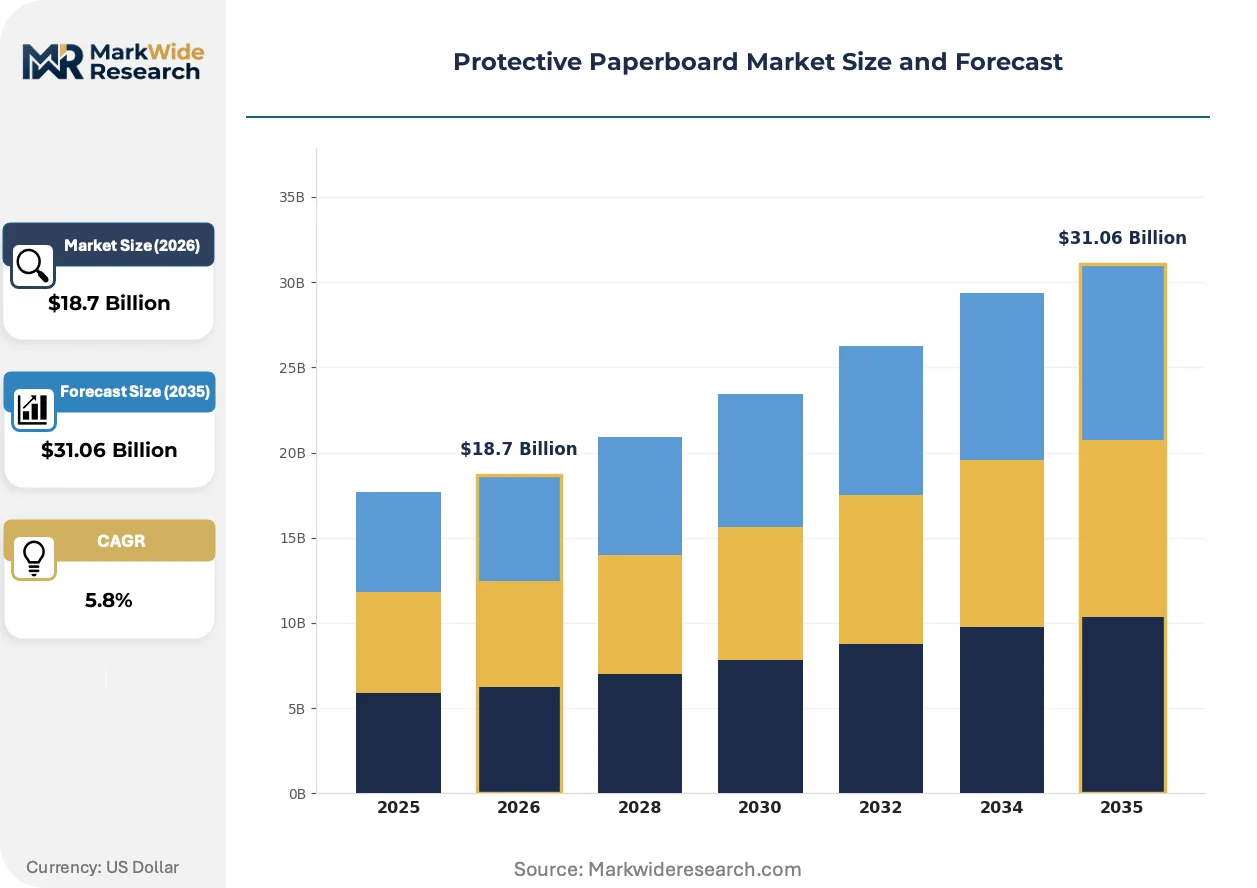
Market Dynamics
Extended producer responsibility frameworks are restructuring capital allocation across the protective paperboard value chain as brands internalize end-of-life costs previously externalized to municipal waste systems.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are forcing format standardization that favors fiber-based cushioning over multi-material alternatives in cross-border e-commerce flows.
- Electronics assemblers:Device manufacturers are eliminating expanded polystyrene from premium unboxing experiences, redirecting specification budgets toward molded fiberboard with barrier-coated surfaces.
- German automotive clusters:Just-in-sequence parts delivery near Stuttgart and Wolfsburg is concentrating demand for precision-cut paperboard dunnage with integrated RFID tracking.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import quota adjustments, compressing converter margins on fixed-price annual contracts.
- Nordic pulp concentration:Three integrated producers control 60% of European kraft pulp supply, creating bottleneck risk during maintenance turnarounds or energy price spikes.
- Moisture sensitivity:Uncoated fiberboard loses structural integrity above 85% relative humidity, limiting adoption for ocean freight legs through tropical ports without desiccant augmentation.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO serialization mandates and EU MDR compliance requirements are creating specification gaps that barrier-coated solid bleached sulfate can fill for temperature-sensitive biologics.
- Chemical recycling partnerships:Pyrolysis-to-fiber pathways for contaminated post-industrial waste offer margin recovery where mechanical re-pulping fails.
- Direct-to-consumer appliance brands:Unboxing experience investments are opening specification slots for premium printed paperboard inserts previously reserved for luxury cosmetics.
Industry Challenges
- Barrier coating chemistries:PFAS-free grease and moisture resistance remains technically immature, with FDA food-contact approval timelines stretching 18-24 months for novel bio-based formulations.
- Legacy equipment retrofitting:Converting lines built for 2mm corrugated struggle to handle sub-1mm solid board with precision die-cutting tolerances below 0.5mm.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Paperboard Market Trends and Innovations
Active material substitution and regulatory compliance automation are compressing traditional specification cycles while opening premium positioning for fiber solutions with embedded intelligence.
Molded fiber thermoforming is collapsing the cost gap with expanded polystyrene for electronics cushioning. Smartphone and laptop brands in South Korea and Taiwan are qualifying fiber-based inserts at volumes exceeding 10 million units annually. The technology is collapsing virgin resin demand in premium unboxing segments where surface finish tolerances now match injection-molded alternatives.
REACH substance restriction updates are accelerating chemical disclosure requirements across European supply chains. Paperboard converters must now document coating constituents down to 0.1% weight concentration for SVHC candidate list substances. Pharmaceutical packaging lines in Ireland and Switzerland are pre-emptively shifting to fully characterized solid bleached sulfate grades to avoid batch rejection at customs.
Brand sustainability scorecards are reshaping procurement authority structures. Packaging engineers at major appliance and electronics OEMs now hold veto power over sourcing decisions previously controlled by purchasing departments alone. This shift is most pronounced in German and Dutch headquarters where supervisory board sustainability committees review quarterly packaging carbon footprint trajectories.
Protective Paperboard Market Segmentation
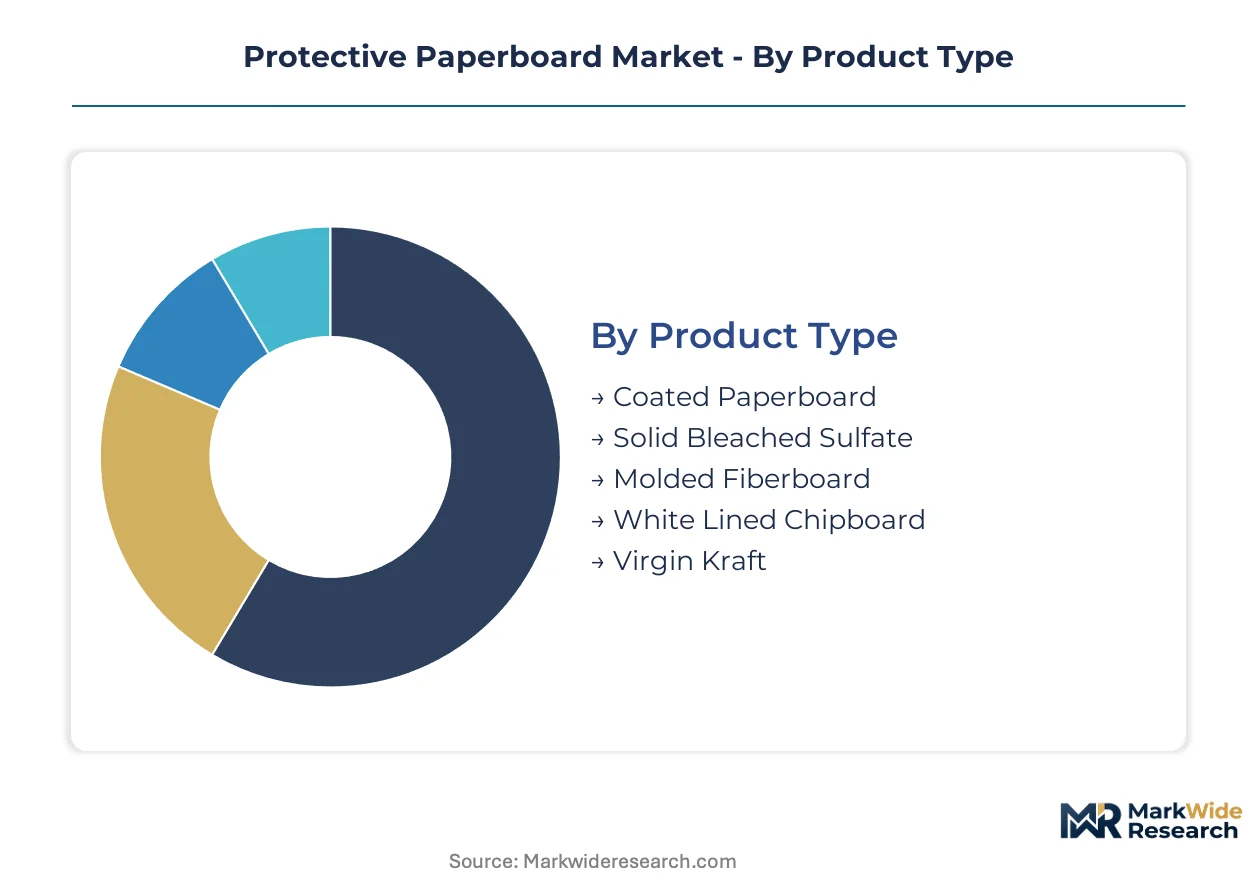
Protective paperboard segmentation reveals divergent specification cycles across material grades and end-use applications. Product type selection determines capital intensity and margin stability, while application-driven demand concentrates in geographies with stringent transit safety mandates.
Product Type:
Cycle times vary dramatically across paperboard grades, with commodity chipboard turning inventory weekly while barrier-coated specialties lock in six-month specification windows.
- Solid Bleached Sulfate:Manufactured through bleached kraft pulping to achieve pharmaceutical-grade purity and superior printability. Demand concentrates in German pharmaceutical clusters where EU MDR compliance mandates documented fiber provenance and extractable limits.
- Molded Fiberboard:Thermoformed from recycled pulp slurries into complex geometries matching expanded polystyrene cushioning profiles. Electronics assemblers in South Korea and Taiwan are qualifying this grade at volumes exceeding ten million units annually for premium unboxing experiences.
- Coated Paperboard:Clay or polymer-barrier surface treatments enable moisture and grease resistance for food-contact applications.
- White Lined Chipboard:Recycled fiber core with bleached top ply delivers cost-efficient rigidity for dry goods secondary packaging.
- Virgin Kraft:Unbleached long-fiber construction provides maximum puncture resistance for industrial dunnage and heavy-goods transit.
Solid Bleached Sulfate dominates installed base. Molded Fiberboard is where expansion concentrates.
Application:
Margin tiers separate applications by regulatory burden and surface finish requirements, with pharmaceutical and luxury commanding three-to-five-fold premiums over industrial bulk packaging.
- Electronics Protection:Precision die-cut inserts and molded fiber cushioning protect high-value devices through multi-modal transit. Specification authority has shifted to packaging engineers at Dutch and German OEMs who now hold veto power over purchasing decisions based on sustainability scorecards.
- Pharmaceutical Containers:Solid bleached sulfate with barrier coatings maintains sterility and stability for temperature-sensitive biologics. Indian export manufacturers face specification gaps as CDSCO serialization mandates converge with EU MDR compliance requirements.
- Food Packaging:FDA and EFSA food-contact regulations govern coating chemistry approvals.
- Industrial Packaging:Heavy-duty corrugated and rigid formats protect automotive and machinery components through just-in-sequence delivery.
- Luxury Goods Wrapping:Premium tactile finishes and foil stamping drive surface aesthetics specifications.
Pharmaceutical Containers command premium positioning. Electronics Protection is gaining share fastest.
End User:
Procurement sophistication varies by vertical, with pharmaceuticals and electronics enforcing supplier audits while industrial buyers prioritize landed cost minimization.
- Electronics Assemblers:Device manufacturers in Taiwan and South Korea are eliminating expanded polystyrene from premium unboxing experiences, redirecting specification budgets toward molded fiberboard with barrier-coated surfaces.
- Pharmaceuticals Producers:Packaging lines in Ireland and Switzerland pre-emptively shift to fully characterized solid bleached sulfate grades to avoid batch rejection at customs under REACH substance disclosure rules.
- Consumer Goods Manufacturers:Direct-to-consumer appliance brands invest in unboxing experience upgrades.
- Industrial Suppliers:German automotive clusters near Stuttgart and Wolfsburg concentrate demand for precision-cut paperboard dunnage.
- Specialty Packaging Firms:Converters serving multiple end-use verticals balance equipment flexibility against dedicated line efficiency.
Pharmaceuticals Producers anchor premium demand. Electronics Assemblers drive specification innovation.
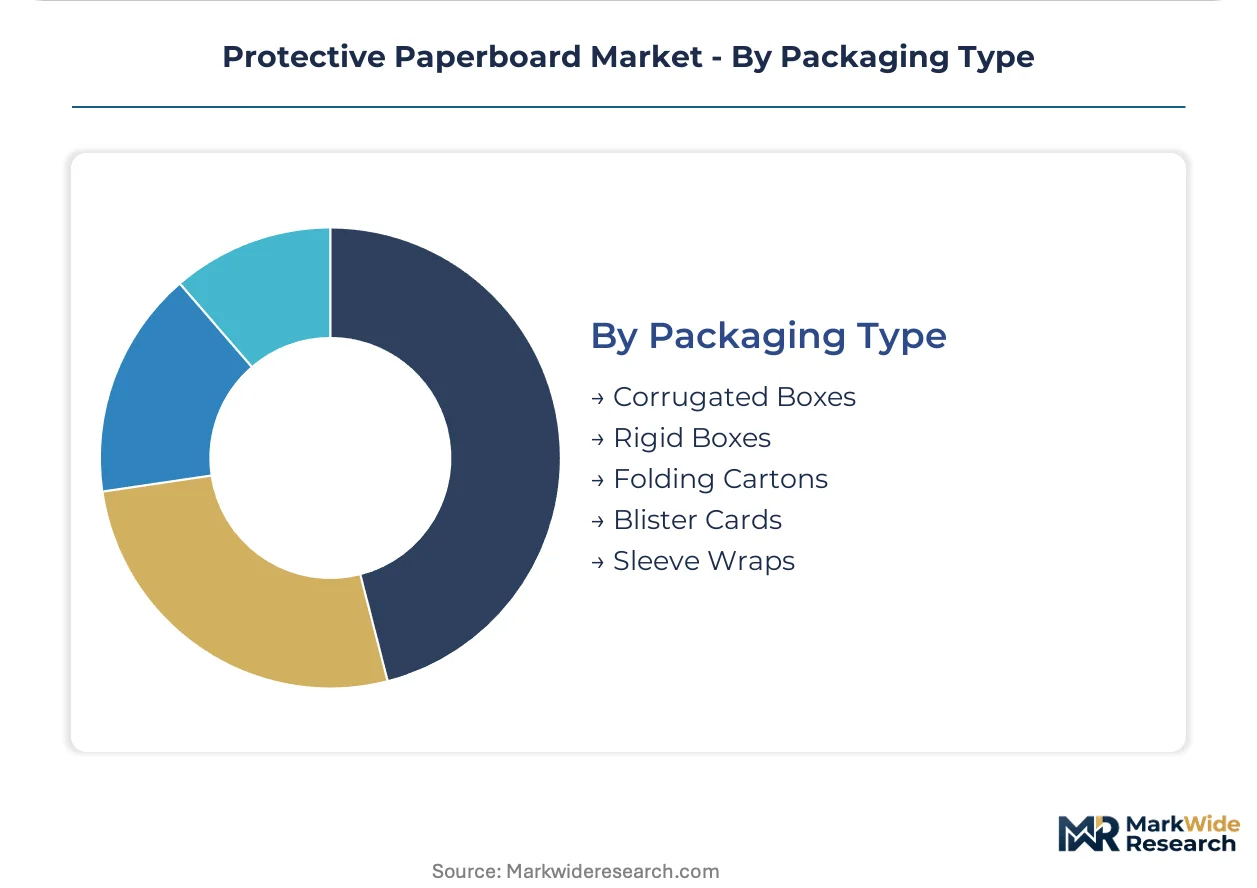
Packaging Type:
Equipment legacy constrains format flexibility, with converting lines built for 2mm corrugated struggling to handle sub-1mm solid board precision.
- Corrugated Boxes:Multi-flute constructions ranging from single-wall to triple-wall provide stack strength for warehouse distribution. E-commerce fulfillment networks favor standardized formats that optimize cube utilization in last-mile delivery.
- Folding Cartons:Die-cut and creased solid board converts to finished containers without additional gluing. Pharmaceutical and food applications in Germany and the Netherlands concentrate demand for high-speed forming lines.
- Rigid Boxes:Wrapped chipboard or paperboard over set-up construction delivers premium presentation for luxury goods.
- Blister Cards:Heat-sealed paperboard backing for product visibility and theft deterrence.
- Sleeve Wraps:Partial enclosures for multi-pack aggregation and promotional messaging.
Corrugated Boxes dominate volume throughput. Folding Cartons is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes protective paperboard differently from other major markets, with automotive just-in-sequence delivery demanding precision-cut dunnage rather than commodity cushioning. Electronics assemblers in Asia-Pacific prioritize molded fiberboard for premium unboxing experiences. Pharmaceutical exporters in India face specification gaps between domestic and EU compliance requirements.
Germany
Automotive clusters near Stuttgart and Wolfsburg concentrate demand for RFID-integrated paperboard dunnage supporting just-in-sequence parts delivery. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that favor fiber-based formats over multi-material alternatives. Packaging engineers at OEM headquarters in Munich and Wolfsburg now hold veto power over sourcing decisions based on sustainability scorecards.
United States
E-commerce fulfillment networks drive standardized corrugated formats optimizing cube utilization in last-mile delivery. EPA recycled content claims enforcement shapes fiber sourcing disclosures across domestic supply chains. Converting operations in the Midwest and Southeast struggle with legacy equipment built for 2mm corrugated when handling sub-1mm solid board precision requirements.
China
Domestic appliance brands invest in unboxing experience upgrades opening specification slots for premium printed paperboard inserts. SAMR packaging standards and dual carbon goals accelerate substitution away from expanded polystyrene cushioning. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta concentrate molded fiberboard thermoforming capacity for electronics exports.
India
Pharmaceutical exporters face specification gaps as CDSCO serialization mandates converge with EU MDR compliance requirements for temperature-sensitive biologics. DGFT export promotion schemes support barrier-coated solid bleached sulfate adoption for international market access. Manufacturing concentration in Maharashtra and Gujarat anchors domestic converting capacity serving regulated export markets.
South Korea
Electronics OEMs in Seoul and Suwon eliminate expanded polystyrene from premium unboxing experiences at volumes exceeding ten million units annually. MFDS pharmaceutical packaging standards align with international harmonization initiatives. Display and semiconductor manufacturing clusters in Gyeonggi Province drive specification innovation for moisture-buffering fiber solutions.
Protective Paperboard Market Competitive Landscape
Capability concentration sits with integrated pulp-to-board specialists; scale advantage sits with global containerboard networks with recycling infrastructure. The market structures around three tiers: multinational integrated producers with captive fiber supply, regional converters with specialized coating and die-cutting equipment, and niche molded fiber specialists serving electronics unboxing segments. Dominant competitive moves include M&A to secure OCC feedstock access and partnerships with chemical recyclers for contaminated post-industrial waste recovery.
Within the integrated producer tier, Smurfit Westrock and Mondi plc represent archetypes of geographic diversification across Europe and the Americas. DS Smith occupies a position exemplifying lightweight corrugated innovation and e-commerce fulfillment specialization. Mayr-Melnhof Karton AG anchors the European coated board segment with pharmaceutical-grade solid bleached sulfate capabilities. These three named entities collectively illustrate how competitive positioning splits between fiber integration depth and converting technology specialization.
| Leading Market Players |
|---|
| Smurfit Westrock |
| DS Smith |
| Sonoco Products Company |
| International Paper |
| Georgia-Pacific |
| Mayr-Melnhof Karton AG |
| Mondi plc |
| VPK Group |
| Cascades |
| Others |
Pricing and Supply Chain Analysis
Old corrugated container feedstock volatility compresses converter margins on fixed-price annual contracts while simultaneously widening spreads between commodity chipboard and barrier-coated specialty grades. OCC price swings with Chinese import quota adjustments force converters to choose between absorbing cost shocks or renegotiating contract terms mid-cycle, reshaping procurement relationships across the value chain.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical and automotive supply relationships, locking in six-month specification windows for barrier-coated solid bleached sulfate while commodity chipboard trades on spot-adjusted monthly terms. Price differentiation hinges on certification grade—EU MDR-compliant pharmaceutical grades command three-to-five-fold premiums over industrial bulk packaging—and volume scale, with e-commerce fulfillment networks extracting discounts through standardized format commitments. Pricing pressure stems from OCC cost compression on fixed-price contracts, eroding converter margins when Chinese import quotas tighten. Industrial buyers exhibit highest price sensitivity, prioritizing landed cost minimization over sustainability certifications, while pharmaceutical producers accept premium positioning for documented fiber provenance and extractable limits.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts recycled fiber trade flows, forcing converters to source OCC from alternative markets at elevated logistics cost. Supply concentrates in Germany, China, and the United States, with German automotive clusters demanding precision-cut dunnage and Chinese manufacturing hubs anchoring molded fiberboard thermoforming capacity for electronics exports. Raw material dependencies center on Nordic kraft pulp—where three integrated producers control sixty percent of European supply—OCC feedstock, and barrier coating chemicals subject to REACH substance disclosure rules. Single-source vulnerability concentrates in Nordic pulp during maintenance turnarounds or energy price spikes. Distribution runs through regional converting networks with specialized die-cutting and coating equipment, feeding just-in-sequence automotive lines and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molded fiberboard thermoforming is collapsing the cost gap with expanded polystyrene, creating an early-cycle expansion opportunity as electronics assemblers eliminate virgin resin cushioning from premium unboxing experiences.
For Market Incumbents: Build captive fiber recovery infrastructure to secure OCC feedstock access against Chinese import quota volatility. Integrate chemical recycling partnerships for contaminated post-industrial waste recovery where mechanical re-pulping fails. Defend against emerging molded fiber specialists by investing in barrier-coated surface capabilities that match injection-molded finish tolerances. For New Entrants and Emerging Players: Build out molded fiber thermoforming capacity serving South Korean and Taiwanese electronics OEMs eliminating expanded polystyrene at volumes exceeding ten million units annually. Target Indian pharmaceutical export manufacturers facing specification gaps between CDSCO serialization mandates and EU MDR compliance requirements. Pursue direct qualification relationships with packaging engineers who now hold veto power over sourcing decisions based on sustainability scorecards. For Investors and Strategic Acquirers: The market sits at a substitution acceleration phase that favors integrated producers with captive pulp supply and regional converters with specialized coating equipment. Long-term viability hinges on extended producer responsibility framework compliance and chemical recycling infrastructure ownership. Acquisition targets should exhibit barrier-coated grade capabilities and established pharmaceutical or electronics certifications. Watch for REACH substance restriction updates accelerating chemical disclosure requirements as the inflection indicator signaling margin pressure on unprepared converters.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis-to-fiber pathways recover margin from contaminated post-industrial waste streams. |
| Barrier Coating R&D Investment | PFAS-free grease and moisture resistance formulations secure FDA food-contact approvals. |
| RFID-Integrated Dunnage Development | Precision-cut paperboard with embedded tracking supports German automotive just-in-sequence delivery. |
| OCC Feedstock Security | Captive recycling infrastructure insulates converters from Chinese import quota volatility. |
| Molded Fiber Thermoforming Scale-Up | South Korean electronics OEMs qualify fiber-based inserts at ten million plus annual volumes. |
Research Methodology
The analysis maps solid bleached sulfate, molded fiberboard, coated paperboard, white lined chipboard, and virgin kraft grades, each validated through procurement directors at electronics assemblers, packaging engineers at German automotive OEMs, regulatory affairs leads at pharmaceutical exporters, and converting plant managers across Europe and Asia-Pacific. Primary interview insights triangulate against secondary sources including EPA recycled content enforcement records, REACH substance restriction updates, EU MDR compliance documentation, FDA food-contact approval filings, and customs trade data on OCC flows. Bottom-up segment sizing and top-down macro validation converge through iterative cross-checking against operating metrics disclosed in SEC filings and industry association reports.
Forecast assumptions hold EU Packaging and Packaging Waste Regulation recyclability targets, Chinese dual carbon goals, and Indian CDSCO serialization mandates as fixed policy conditions while varying electronics substitution rates, pharmaceutical export growth, and automotive production volumes across the projection horizon. Segmentation dimensions include product grade tier, end-use application, packaging format type, and regional regulatory cluster. CAGRs derive from trend extrapolation of specification cycle compression, active material substitution rates, and regulatory compliance automation adoption. Industry-specific inputs incorporate molded fiber thermoforming cost curves, barrier coating chemistry approval timelines, and extended producer responsibility framework implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Nordic pulp producers or accelerated chemical recycling commercialization by specialized waste processors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.