
 Masking Paper Market | 2026-2036
Masking Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Masking Paper Market Foresight
Buyer concentration in the automotive refinishing sector is decoupling from traditional distributor networks as collision repair chains and OEM-certified body shops consolidate purchasing power. 3M leverages its adhesive chemistry portfolio to sustain premium positioning in high-temperature bake cycles. Avery Dennison Corporation anchors North American supply through specialized crepe paper formulations for precision edge masking. Trimaco competes aggressively on contractor-channel accessibility and job-site durability ratings.
Masking paper comprises cellulose-based substrates engineered with controlled porosity, tensile strength between 20-50 N/m, and silicone or rubber-based adhesive coatings designed for clean removal without substrate damage after exposure to paint solvents, thermal baking, or UV curing. Crepe paper dominates volume due to its conformability around complex automotive contours and established cost position in collision repair workflows, while specialty paper commands margin pools in aerospace and electronics applications where residue-free removal under thermal stress is non-negotiable. Coated paper variants are gaining share in waterborne paint systems where bleed-through resistance has become a critical functional parameter.
EPA VOC regulations and OSHA workplace exposure limits shape product formulation requirements in the United States, while REACH compliance in Europe restricts certain adhesive chemistries and drives substitution toward bio-based alternatives. The EU F-Gas Regulation indirectly influences masking paper demand by accelerating transitions in automotive paint shop climate control systems. Stakeholders must monitor evolving coating chemistry roadmaps at major automotive OEMs to align substrate and adhesive development cycles with forthcoming solvent restrictions.
Market Dynamics
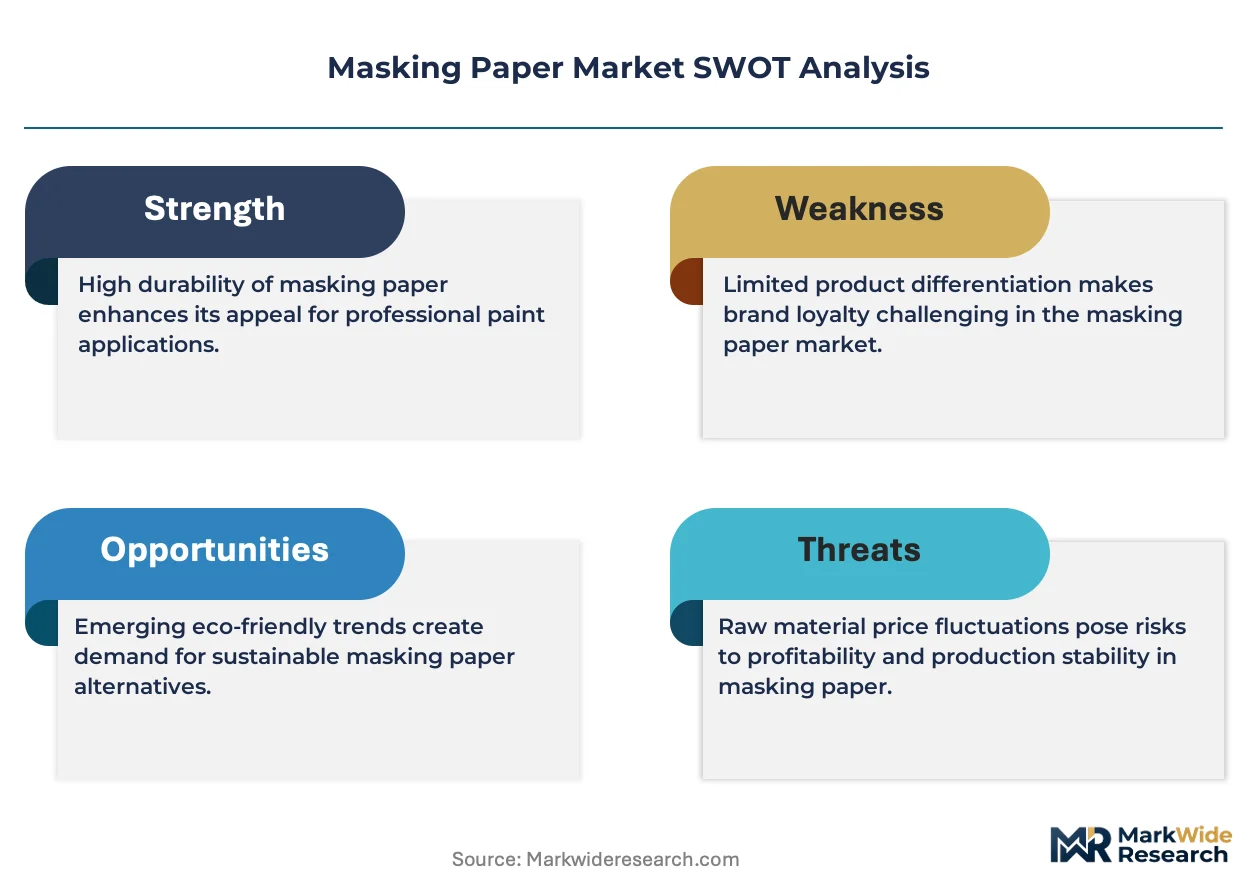
Automotive paint chemistry roadmaps are the dominant structural force reshaping masking paper specifications, as waterborne coating transitions under REACH and EU Green Deal mandates force substrate and adhesive reformulation cycles that outpace traditional product development timelines.
Growth Catalysts
- REACH solvent restrictions:European adhesive chemistry bans are redirecting R&D investment toward bio-based masking substrates compatible with low-VOC paint systems.
- Collision repair consolidation:Multi-shop operator networks in North America are standardizing precision masking procurement across certified body shop chains.
- Stuttgart-Wolfsburg corridor:German automotive OEM capacity expansion is concentrating demand for high-temperature bake-compatible crepe paper formulations.
Market Restraints
- Pulp input volatility:Kraft pulp price swings compress margin stability for cellulose substrate manufacturers serving volume collision repair segments.
- Adhesive chemistry lock-in:Silicone-based coating investments create technical debt that slows waterborne-system compatibility pivots.
- Regional supply concentration:Specialty paper capacity clusters in Central European mills expose buyers to single-source geographic risk.
Strategic Opportunities
- Aerospace thermal masking:Residue-free removal specifications under extreme bake cycles open premium positioning for fluoropolymer-coated substrates.
- EU F-Gas Regulation:Climate control system upgrades in automotive paint shops create retrofit demand for humidity-stable masking materials.
- Direct OEM contracting:Bypassing traditional distributor tiers through certified body shop network partnerships captures specification influence earlier in the value chain.
Industry Challenges
- Formulation-chemistry synchronization:Masking adhesive development cycles must compress to match accelerating automotive OEM paint system roadmaps.
- Cross-regulatory compliance:Simultaneous EPA VOC, OSHA exposure limit, and REACH adhesive restriction navigation strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Masking Paper Market |
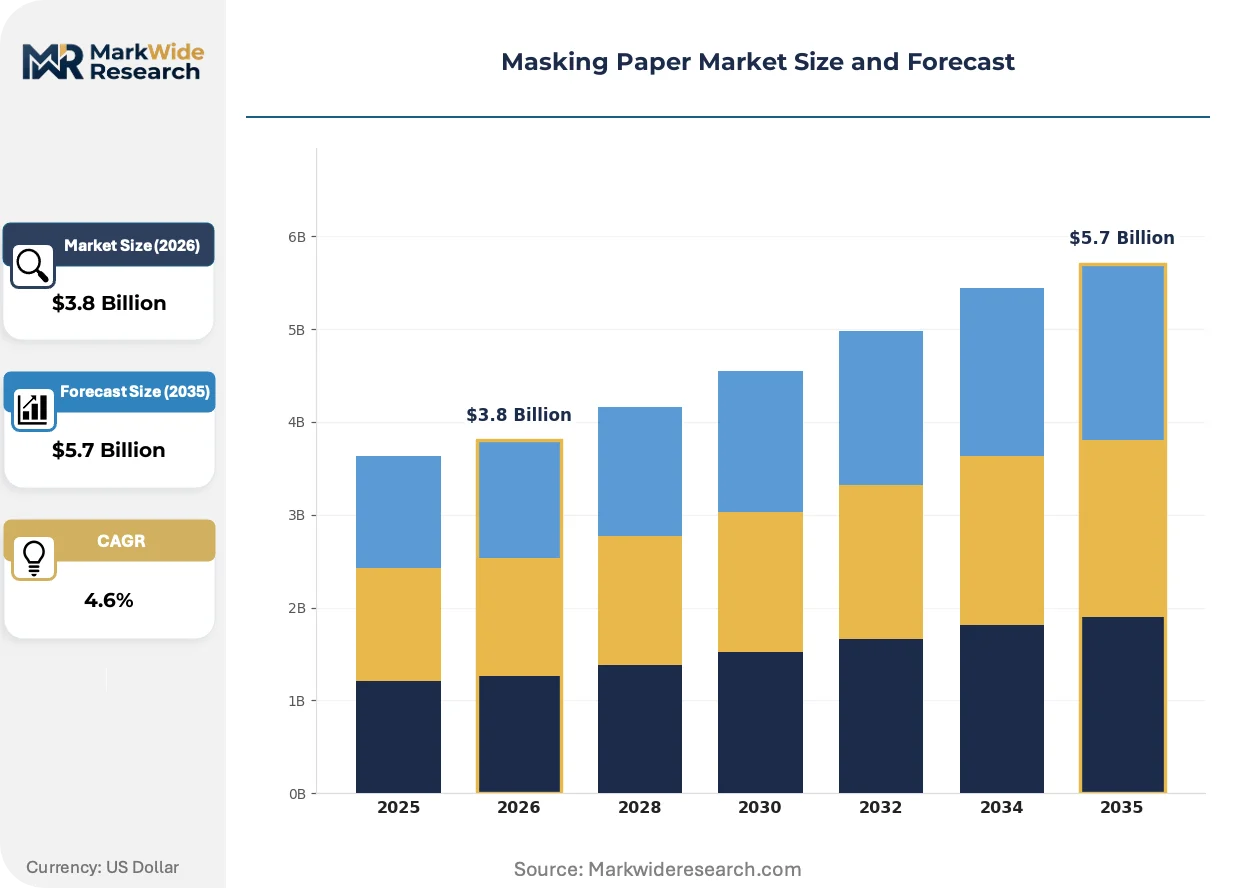
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crepe Paper, Specialty Paper, Coated Paper, Kraft Paper End User: Automotive, Construction, Arts & Crafts, Industrial Application: Surface Protection, Painting, Labeling, DIY Projects Thickness: Lightweight, Medium, Heavyweight, Extra Heavyweight |
| Companies Covered | Avery Dennison Corporation, Trimaco, 3M, Intertape Polymer Group, Berry Global, tesa SE, Nitto Denko Corporation, Saint-Gobain, Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masking Paper Market Shifts & Advancements
Waterborne paint system adoption is forcing concurrent innovation across substrate porosity control, adhesive bleed-through resistance, and thermal stability specifications. Three developments are restructuring competitive requirements.
Silicone-free adhesive chemistries is rewriting the technical baseline for clean-removal performance. Automotive OEM paint shops in Germany and the United States are piloting these formulations at scale for high-temperature bake cycles. The shift is compressing acceptable residue thresholds and disqualifying legacy rubber-based coatings from premium procurement tenders.
EPA VOC regulations and OSHA workplace exposure limits are tightening permissible solvent content in paint shop environments. These rules are mandating substrate-adhesive pairings that eliminate volatile compound transfer during thermal curing. Collision repair chains in California and the Northeast are responding fastest, driving specification changes that propagate through national distributor networks.
Certified body shop networks are consolidating purchasing authority away from traditional jobber channels. Multi-location operators now negotiate direct supply agreements with masking paper manufacturers, unbundling product from legacy distribution markups. This pattern is most pronounced in Texas, Florida, and the Great Lakes automotive repair corridors.
Masking Paper Market Segmentation
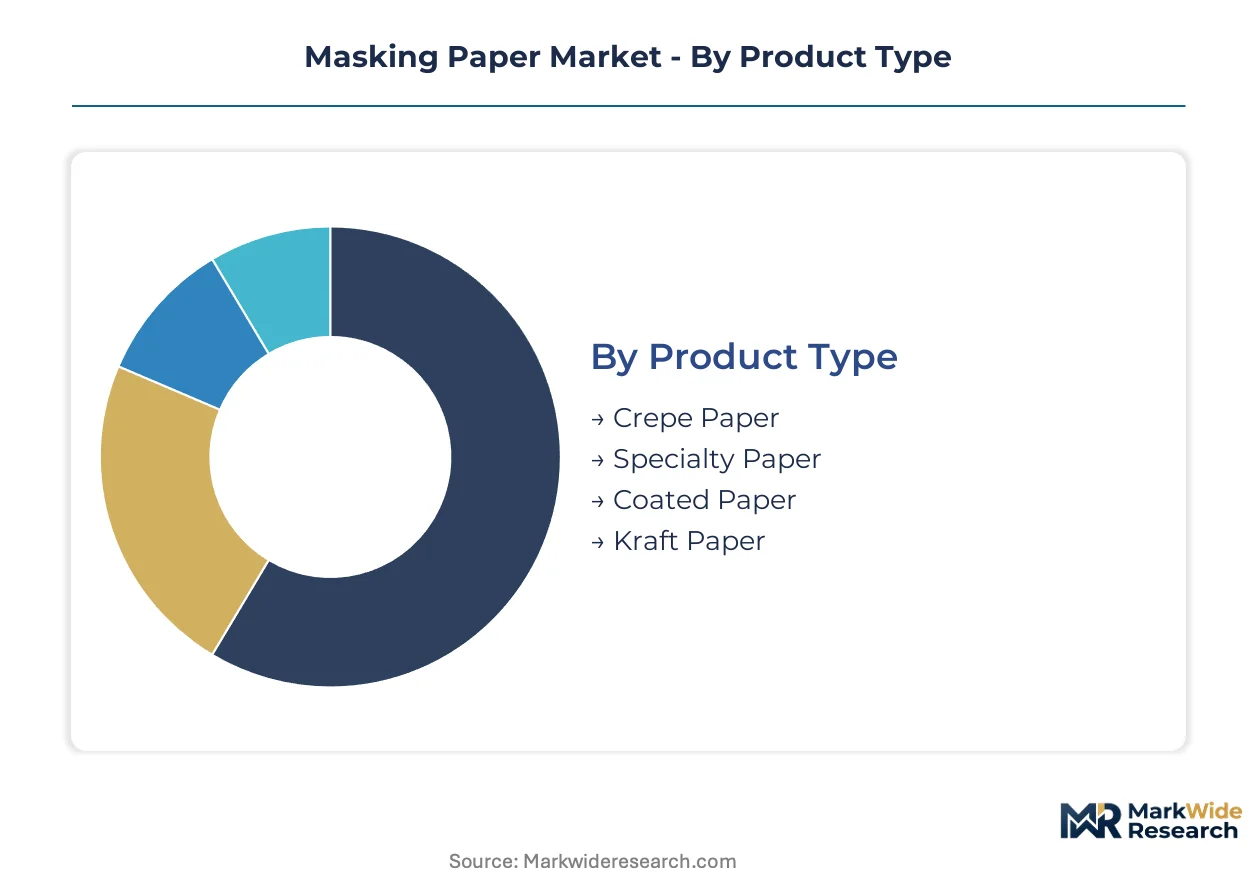
Masking paper procurement diverges sharply across end-use contexts, with automotive bake cycles demanding thermal stability specifications that DIY applications ignore entirely. Understanding these segment boundaries prevents misallocation of R&D investment toward incompatible performance tiers.
Product Type:
The customization-vs-standardization spectrum runs from commodity kraft formulations to engineered crepe structures with calibrated elongation properties.
- Crepe Paper:Micro-corrugated cellulose structure delivers 15-25% elongation for conformability around complex automotive contours. Demand concentrates in Germany's Stuttgart-Wolfsburg corridor where OEM bake cycles above 140°C require silicone-adhesive compatibility.
- Specialty Paper:Fluoropolymer-coated substrates engineered for residue-free removal under extreme thermal stress. Aerospace MRO facilities in France and electronics cleanrooms in Japan drive specification tightening for ultra-low outgassing thresholds.
- Coated Paper:Polyethylene or silicone barrier layers block bleed-through in waterborne paint systems.
- Kraft Paper:Unbleached virgin pulp construction serves cost-sensitive construction masking with minimal adhesive sophistication.
Leading the category by volume: Crepe Paper. Expanding most quickly: Specialty Paper.
End User:
Cost tier separation distinguishes capital-intensive OEM procurement from price-elastic contractor purchasing.
- Automotive:OEM-certified body shops and collision repair chains negotiate direct supply agreements bypassing traditional distributors. REACH solvent restrictions force concurrent reformulation of substrates and adhesives for waterborne system compatibility.
- Construction:General contractors prioritize job-site durability and channel accessibility over thermal performance. Trimaco's distribution density in North American home improvement retail captures this volume.
- Arts & Crafts:Hobbyist demand favors low-tack adhesion and decorative color ranges.
- Industrial:Heavy equipment manufacturers require abrasion resistance during grit blasting and surface preparation.
Dominant by procurement scale: Automotive. Steepest expansion trajectory: Industrial maintenance applications.
Application:
Volume concentration aligns with paint shop workflow intensity rather than project frequency.
- Surface Protection:Temporary coverage during manufacturing and transit. Automotive OEMs in the United States specify UV-resistant formulations for extended outdoor storage of pre-painted components.
- Painting:Precision edge masking dominates value capture. Collision repair consolidation in Texas and Florida drives standardization across multi-shop operator networks.
- Labeling:Writable masking paper substitutes for permanent marking in temporary production sequencing.
- DIY Projects:Consumer-grade adhesion levels prevent substrate damage on delicate residential surfaces.
Highest throughput: Painting. Gaining share fastest: Surface Protection.
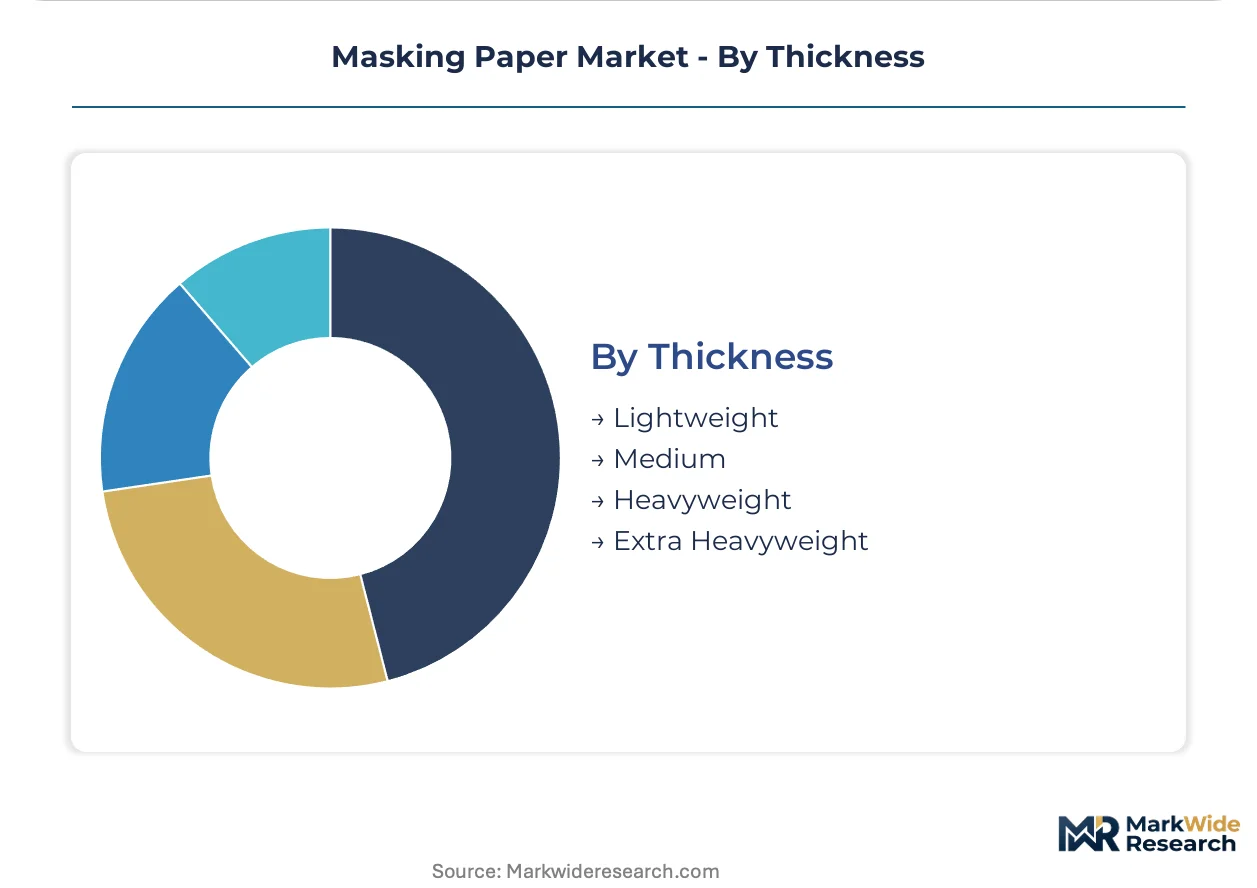
Thickness:
Application severity dictates caliper selection, with thermal mass and solvent exposure as primary determinants.
- Lightweight:Sub-50 gsm construction for temporary hold and delicate substrates. Electronics assembly in Japan favors minimal adhesive transfer during precision component masking.
- Medium:50-80 gsm range balances conformability with structural integrity. German automotive paint shops standardize this grade for general refinishing workflows.
- Heavyweight:80-120 gsm for aggressive solvent systems and extended bake cycles.
- Extra Heavyweight:Above 120 gsm for industrial grit blasting and heavy-duty surface preparation.
Standard procurement default: Medium. Climbing the fastest: Heavyweight specifications for waterborne system compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kraft pulp availability and automotive manufacturing density anchor geographic demand distribution. Germany's Stuttgart-Wolfsburg corridor concentrates high-temperature bake-compatible procurement. North American collision repair consolidation drives distributor bypass strategies in Texas and Florida.
United States
Collision repair chains in Texas and Florida consolidate purchasing through multi-shop operator networks. EPA VOC regulations and OSHA workplace exposure limits mandate substrate-adhesive pairings eliminating volatile compound transfer. California and Northeast paint shops propagate specification changes through national distributor channels fastest.
Germany
Automotive OEM capacity expansion around Stuttgart and Wolfsburg concentrates demand for silicone-adhesive compatible crepe paper. REACH solvent restrictions redirect formulation investments toward bio-based masking substrates. Baden-Württemberg paint shops pilot silicone-free adhesive chemistries at scale for high-temperature bake cycles.
Japan
Electronics cleanrooms and aerospace MRO facilities drive ultra-low outgassing specification tightening. METI industrial standards shape residue-free removal thresholds under extreme thermal stress. Kanto region precision component manufacturers favor lightweight sub-50 gsm construction with minimal adhesive transfer.
China
Automotive paint shop climate control upgrades accelerate demand for humidity-stable masking materials. MEE environmental standards and dual carbon goals pressure solvent-based coating transitions. Yangtze River Delta OEM facilities expand procurement of waterborne-system compatible substrates.
France
Aerospace maintenance facilities in Toulouse and Paris anchor specialty fluoropolymer-coated substrate demand. EU F-Gas Regulation indirectly influences masking paper specifications through paint shop climate control retrofit requirements. Île-de-France industrial zones concentrate precision edge masking procurement for aviation applications.
Masking Paper Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent specialty substrates and regional distributor bypass models. Three to five adhesive chemistry specialists hold premium positioning in high-temperature automotive bake cycles. The vendor base separates into integrated material science conglomerates, regional paper converters, and niche aerospace-electronics specialists. Competitive moves center on direct OEM contracting partnerships and silicone-free adhesive R&D licensing.
Among North American material science conglomerates, 3M and Avery Dennison Corporation exemplify premium-tier positioning through adhesive chemistry depth. Trimaco occupies a distinct archetype focused on contractor-channel accessibility and job-site durability ratings. Tesa SE represents European specialist positioning with crepe paper formulation heritage. These three anchors illustrate how competitive separation follows end-use concentration rather than geographic coverage alone.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Trimaco |
| 3M |
| Intertape Polymer Group |
| Berry Global |
| tesa SE |
| Nitto Denko Corporation |
| Saint-Gobain |
| Shurtape Technologies |
| Others |
Supply & Pricing Matrix
Kraft pulp futures volatility cascades through cellulose substrate manufacturing into three distinct pricing tiers for masking paper, with German automotive OEM procurement commanding premium positioning while North American collision repair chains negotiate volume discounts off distributor list prices. REACH-driven adhesive chemistry reformulation costs concentrate in specialty paper grades serving aerospace MRO facilities, where fluoropolymer-coated substrates sustain margin pools unavailable to commodity kraft formulations.
Pricing Analysis
Service bundling separates premium-tier supply agreements from transactional spot purchasing, with 3M and Avery Dennison Corporation packaging technical specification support and bake-cycle compatibility warranties into multi-year contracts with certified body shop networks. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance certification, with silicone-adhesive compatibility for high-temperature OEM cycles commanding the widest spreads. Pricing pressure stems from pulp input volatility compressing margins at the kraft paper tier, where Trimaco competes on channel accessibility rather than formulation sophistication. Collision repair chains in Texas and Florida exhibit highest price sensitivity through consolidated multi-shop procurement, while aerospace MRO facilities in France show lowest sensitivity due to residue-free removal specifications.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta automotive corridor are redirecting procurement toward locally converted crepe paper substrates, reshaping sourcing patterns for multinational OEM paint shop operations. Specialty paper capacity clusters in Germany, France, and Japan, with Central European mills supplying silicone-adhesive compatible formulations for Stuttgart-Wolfsburg corridor demand. Raw material dependencies center on bleached and unbleached kraft pulp, silicone and rubber-based adhesive chemistries, and fluoropolymer barrier coatings. Single-source geographic risk concentrates in Baden-Württemberg specialty paper production, where REACH compliance investments have consolidated supplier bases. Distribution runs through certified body shop network partnerships bypassing traditional jobber channels fastest in North American collision repair consolidation zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty paper capacity constraints in Central European mills prop pricing power for residue-free removal substrates, as REACH adhesive chemistry restrictions prevent rapid capacity expansion without multi-year reformulation cycles.
For Market Incumbents: Deploy direct OEM contracting partnerships to capture specification influence before waterborne paint system roadmaps finalize. 3M should anchor backward integration into silicone-free adhesive R&D to neutralize bio-based substitute threats from emerging European specialists. Consolidate distributor relationships in Texas and Florida collision repair corridors before multi-shop operator networks complete procurement standardization. For New Entrants and Emerging Players: Industrial maintenance applications present the most penetrable white-space target, with heavy equipment manufacturers in the Great Lakes corridor underserved by incumbent aerospace-automotive focus. Aerospace MRO facilities in Toulouse offer premium positioning entry through fluoropolymer-coated substrate specialization, bypassing saturated automotive volume tiers. Channel partnerships with grit blasting equipment distributors provide faster access than direct OEM certification cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional paper converters with existing REACH compliance infrastructure in Germany, as adhesive chemistry lock-in strands legacy silicone-dependent producers. Long-term viability hinges on synchronization with automotive OEM paint system roadmaps rather than spot market pulp trading. Watch for EPA VOC rulemaking in California and Northeast states as inflection indicator for national specification propagation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Free Adhesive R&D Licensing | Baden-Württemberg paint shop pilots disqualify legacy rubber-based coatings from premium tenders. |
| Direct Body Shop Network Partnerships | Multi-shop operators in Texas and Florida bypass distributor markups through certified supply agreements. |
| Fluoropolymer Coating Capacity Expansion | Toulouse aerospace MRO facilities drive ultra-low outgassing specification tightening. |
| Humidity-Stable Substrate Development | EU F-Gas Regulation climate control retrofits create retrofit demand in automotive paint shops. |
| Bio-Based Substrate Formulation Investment | REACH solvent restrictions redirect R&D toward waterborne-system compatible cellulose engineering. |
Research Methodology
Trade publications, automotive OEM technical specifications, and ECHA REACH substance restriction databases formed the secondary backbone, supplemented by customs records for kraft pulp import flows and SEC 10-K filings from adhesive chemistry specialists. Primary interviews with collision repair chain procurement directors, German automotive paint shop engineers, and aerospace MRO supply managers validated formulation roadmaps and specification timelines. Bottom-up demand modeling across product type, end user, and application segments triangulated against top-down pulp consumption benchmarks from regional paper industry associations.
Historical trendline analysis of automotive paint chemistry transitions informed projection parameters, with segmentation across crepe paper, specialty paper, coated paper, and kraft paper grades matched to end-use thermal performance requirements. Modeled dimensions included automotive OEM versus collision repair procurement channels, waterborne versus solvent-based paint system compatibility, and geographic concentration in Stuttgart-Wolfsburg corridor versus dispersed North American distributor networks. CAGRs derived from production capacity announcements, OEM platform launch schedules, and regulatory compliance deadlines without year-specific anchoring.
Caveats apply where EPA VOC rulemaking acceleration or EU Green Deal solvent restriction tightening could materially shift the outlook toward faster waterborne system adoption than substrate reformulation cycles accommodate. Pulp price volatility, single-source specialty paper mill disruptions, and collision repair chain bankruptcy consolidation represent additional revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Desiccant Paper Market