
 Middle-East and Africa Corrugated Packaging Market | 2026-2036
Middle-East and Africa Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Corrugated Packaging Market Foresight
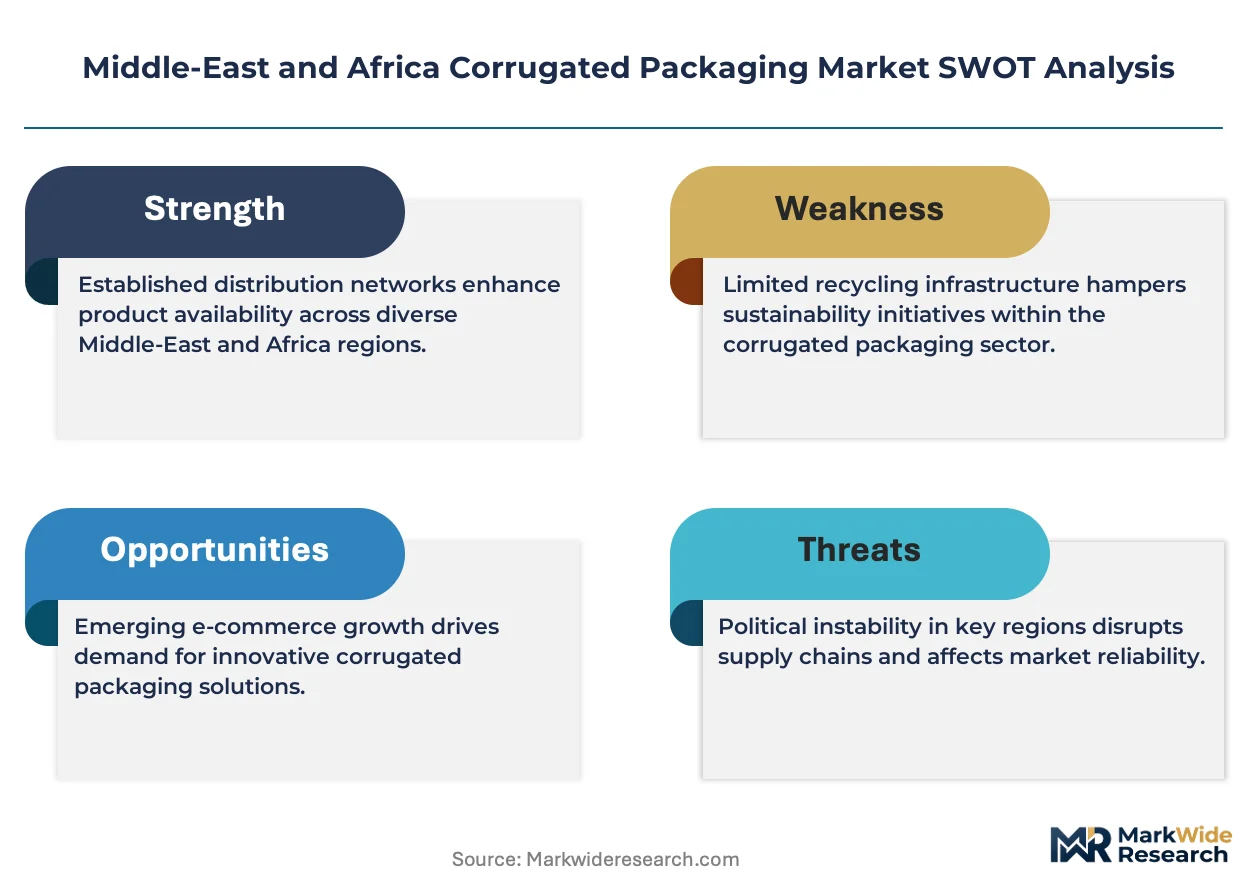
Project finance for recycled pulp mills is fragmenting competitive access across the Middle-East and Africa corrugated packaging landscape. Smurfit Kappa leverages integrated containerboard mills in Morocco to sustain cost advantages for regional box plants. Mondi anchors its position through kraftliner specialization serving agricultural export corridors from Kenya to the UAE. Arabian Packaging Co. LLC competes on proximity to Saudi Arabia's dairy and date processing clusters, shortening delivery lead times for just-in-line supply contracts.
Corrugated packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed from 80-350 grams per square meter paper grades to achieve calibrated burst strength and edge crush resistance for stackable load protection. The material primarily protects goods through distribution shocks, humidity exposure, and palletized compression during multi-modal transit across arid climates and variable port infrastructure. Single wall boards dominate volume in consumer goods and lightweight electronics, while triple wall configurations capture margin pools in heavy machinery and automotive parts shipping. Die-cut formats represent the fastest-growing product type as e-commerce channels demand presentation-ready unboxing experiences without secondary wrapping.
Saudi Food and Drug Authority standards for food-contact packaging materials, UAE's Emirates Authority for Standardization and Metrology labeling mandates, and South Africa's National Regulator for Compulsory Specifications for paperboard recyclability collectively shape product compliance and market access thresholds. These frameworks push converters toward water-based inks and starch adhesives to maintain certification eligibility for regulated end-use segments. Stakeholders must monitor how Gulf Cooperation Council harmonization of packaging waste directives alters recycling infrastructure investments and virgin fiber sourcing obligations.
Market Dynamics
EU Green Deal extraterritoriality is forcing export-oriented converters across Saudi Arabia and South Africa to abandon solvent-based inks and petroleum-derived adhesives, reshaping raw material procurement and certification workflows for corrugated suppliers serving European-bound agricultural shipments.
Growth Catalysts
- SFDA Food-Contact Standards:Saudi Arabia's packaging material regulations mandate temperature-stable corrugated trays for dairy and date processing clusters, accelerating demand for coated linerboards in the Kingdom's industrial corridor.
- E-Commerce Fulfillment Expansion:Die-cut corrugated solutions are capturing volume as Nigeria and South Africa build automated distribution centers requiring presentation-ready unboxing formats without secondary wrapping.
- Recycled Pulp Mill Investment:Project finance fragmentation across Morocco and Kenya is creating captive fiber supply for integrated containerboard producers, lowering input costs for regional box plants.
Market Restraints
- Recovered Paper Supply Concentration:Gulf Cooperation Council nations depend on imported OCC from European sorting facilities, exposing converters to shipping rate volatility and customs delays at Jebel Ali and Durban ports.
- Triple Wall Technical Limitations:Heavy machinery exporters in South Africa report edge crush resistance failures during multi-modal transit across arid climates, restricting adoption for automotive parts exceeding 500 kilograms per pallet.
- UAE ESMA Labeling Friction:Emirates Authority for Standardization and Metrology mandates for Arabic-English bilingual print specifications extend pre-production approval timelines by three to four weeks for first-time suppliers.
Strategic Opportunities
- Kenya Agricultural Export Corridor:Mondi's kraftliner specialization serving flower and fresh produce shipments from Nairobi to Dubai creates white space for moisture-resistant corrugated formats with extended shelf-life properties.
- GCC Packaging Waste Harmonization:Gulf Cooperation Council recycling infrastructure investments will mandate post-consumer recycled content thresholds, rewarding early movers with certified closed-loop supply chains.
- Water-Based Ink and Starch Adhesive Convergence:Compliance-driven formulation shifts are opening technical partnerships between adhesive suppliers and corrugated converters targeting SFDA and ESMA certification eligibility.
Industry Challenges
- Die-Cut Tooling Skill Scarcity:South African and Nigerian converters face shortages of CAD-operating technicians capable of programming high-speed rotary die cutters for e-commerce batch sizes below 500 units.
- Integrated Mill Capex Burden:Smurfit Kappa's Moroccan containerboard complex and similar regional investments require sustained occupancy rates above 85 percent to service project debt, pressuring pricing discipline during demand troughs.
- NRCS Recyclability Certification Timelines:South Africa's National Regulator for Compulsory Specifications testing protocols for paperboard recyclability add four to six months to new product qualification for food-contact applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Corrugated Packaging Market |
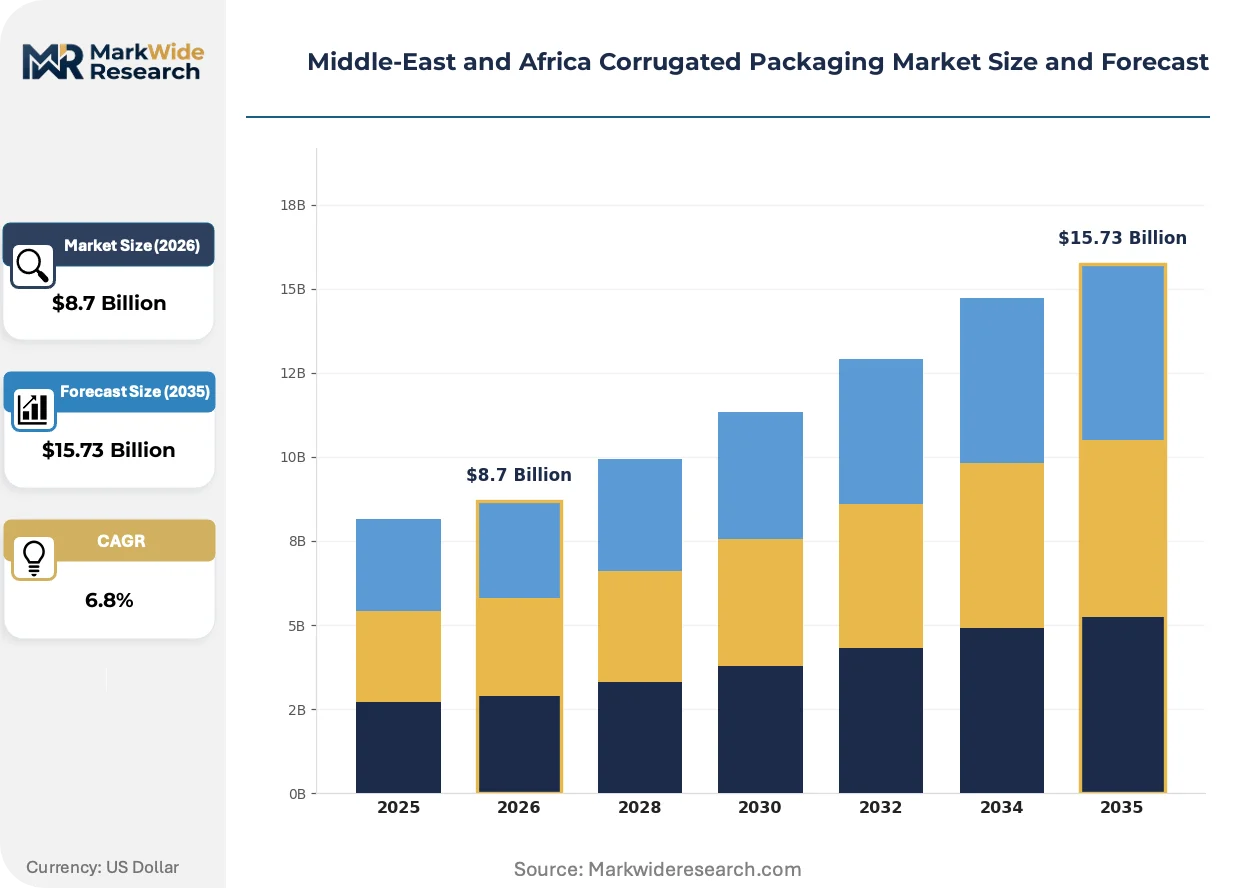
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die-Cut End Use Industry: Food & Beverage, Electronics, Consumer Goods, Healthcare Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales Packaging Type: Boxes, Trays, Sheets, Pallets |
| Companies Covered | International Paper, DS Smith, Smurfit Kappa, Arabian Packaging Co. LLC, United Carton Industries Company, Mondi, WestRock Company, Stora Enso, Napco National, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Corrugated Packaging Market Shifts & Advancements
Corrugated packaging across the Middle-East and Africa is experiencing simultaneous pressure from European regulatory extraterritoriality, e-commerce format fragmentation, and fiber supply chain regionalization. These forces are compressing legacy production workflows while opening technical differentiation pathways.
Digital print technology is migrating from flexographic pre-print for high-volume beverage and consumer goods runs toward late-stage customization for promotional and seasonal packaging. Saudi dairy processors and UAE cosmetics brands are adopting inkjet-enabled corrugated displays for retail-ready shelf presentation. This migration from analog to digital is collapsing minimum order quantities from 10,000 units to 500 units, enabling just-in-time inventory models for perishable distribution.
EU Green Deal carbon border adjustment mechanisms are extending compliance obligations to packaging materials accompanying agricultural exports from Morocco and Egypt. European importers now require lifecycle documentation and recycled content verification for corrugated shipping containers. Kenyan flower exporters and Tunisian date processors are responding by sourcing FSC-certified linerboards and water-based barrier coatings to maintain market access.
Consolidated buying by Jumia and Takealot is compressing supplier rosters and extending payment terms for corrugated box vendors serving fulfillment networks. Tier-two converters in Lagos and Johannesburg are losing share to integrated producers offering die-cut capability, inventory management, and direct-to-DC delivery. This concentration is most visible in South Africa's Gauteng logistics cluster, where three e-commerce platforms now account for the majority of die-cut corrugated procurement.
Middle-East and Africa Corrugated Packaging Market Segmentation
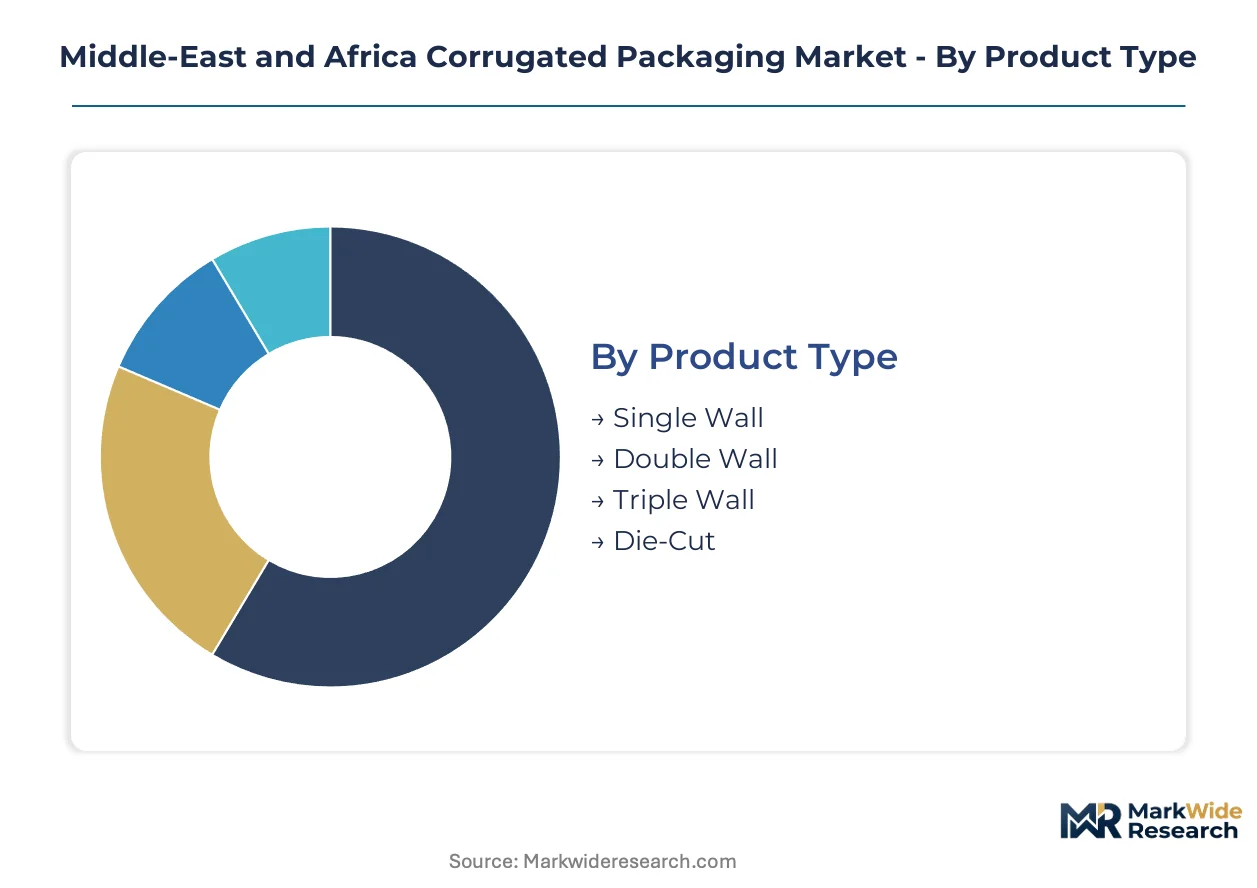
Corrugated packaging segmentation across the Middle-East and Africa reflects divergent cycle times: die-cut formats for e-commerce turn inventory weekly, while triple wall industrial packaging operates on quarterly procurement rhythms. Understanding these velocity differences shapes working capital deployment and converter capacity planning.
Product Type:
Single wall boards rotate through production lines fastest, with typical order-to-delivery cycles of 48-72 hours for established accounts. Triple wall and die-cut formats occupy opposite ends of the velocity spectrum—heavy industrial boards sit in inventory longer due to batch production economics, while precision die-cut tooling extends lead times despite smaller run sizes.
- Single Wall:Fluted medium between two linerboards, typically 80-150 gsm construction, dominates volume for lightweight consumer goods. Nigerian and South African e-commerce fulfillment centers consume this grade for standard shipping cartons under 15 kilograms, driven by Jumia and Takealot procurement consolidation.
- Die-Cut:Precision-cut formats with custom perforations and folding scores enable presentation-ready unboxing without secondary wrapping. Saudi cosmetics brands and UAE electronics retailers specify these for retail-ready shelf presentation, collapsing minimum order quantities from bulk runs to 500-unit promotional batches.
- Double Wall:Two fluted layers between three linerboards provide intermediate protection for appliances and mid-weight machinery. Kenyan agricultural exporters specify this grade for flower shipments to Dubai requiring moisture resistance without triple wall bulk.
- Triple Wall:Three fluted layers between four linerboards achieve burst strength exceeding 1,000 kPa for heavy machinery pallets. South African automotive parts exporters report edge crush resistance failures above 500 kilograms per pallet, limiting adoption despite superior compression performance.
Single wall dominates installed base. Die-cut is where expansion concentrates.
End Use Industry:
Cost tier differentiation separates commodity food packaging from premium healthcare specifications. Food and beverage converters compete on scale and fiber sourcing, while healthcare demands certified barrier properties and traceability documentation at 40-60% price premiums.
- Food & Beverage:Temperature-stable corrugated trays serve Saudi dairy and date processing clusters, with SFDA-mandated coatings for direct food contact. Smurfit Kappa's Moroccan mills supply linerboards with calibrated moisture vapor transmission rates for arid climate distribution.
- Healthcare:Sterile barrier requirements and batch-level traceability drive specification rigor. UAE pharmaceutical distributors demand water-based ink certification and starch adhesive documentation for ESMA compliance, extending qualification timelines but securing multi-year supply contracts.
- Electronics:Anti-static coatings and precise dimensional tolerances protect semiconductors and consumer devices. South African distributors serving African markets specify double wall with VCI (volatile corrosion inhibitor) treatments for humidity-exposed transit.
- Consumer Goods:Brand differentiation through retail-ready graphics and shelf-impact structural design. Saudi personal care brands adopt digital-print corrugated displays for hypermarket placement, bypassing traditional litho-laminated folding carton workflows.
Food and beverage commands volume share. Healthcare delivers margin expansion.
Distribution Channel:
Customer type segmentation separates high-velocity programmatic buyers from relationship-driven direct accounts. E-commerce platforms operate on automated replenishment with 30-day payment terms, while direct sales to industrial clusters negotiate annual frameworks with price-volume bands.
- E-commerce:Consolidated procurement by Jumia, Takealot, and Noon compresses supplier rosters to integrated producers offering die-cut capability, inventory management, and direct-to-DC delivery. Tier-two Lagos and Johannesburg converters lose share without automated order-to-delivery systems.
- Wholesale:Regional distributors aggregate demand from fragmented retail and light industrial accounts. Moroccan and Tunisian wholesalers maintain 45-60 day inventory positions, buffering seasonal agricultural export peaks for European-bound shipments.
- Retail:Hypermarket chains and specialty stores require promotional packaging with rapid graphic changeovers. Saudi Arabia's Panda and UAE's Lulu specify quarterly seasonal designs, favoring converters with digital print capability for short-run flexibility.
- Direct Sales:Large industrial accounts in Saudi Arabia's Jubail industrial city and South Africa's Gauteng logistics cluster negotiate direct mill relationships. Smurfit Kappa and Mondi bypass distribution margins for containerboard supply to captive box plants.
Wholesale retains broadest reach. E-commerce is climbing the fastest.
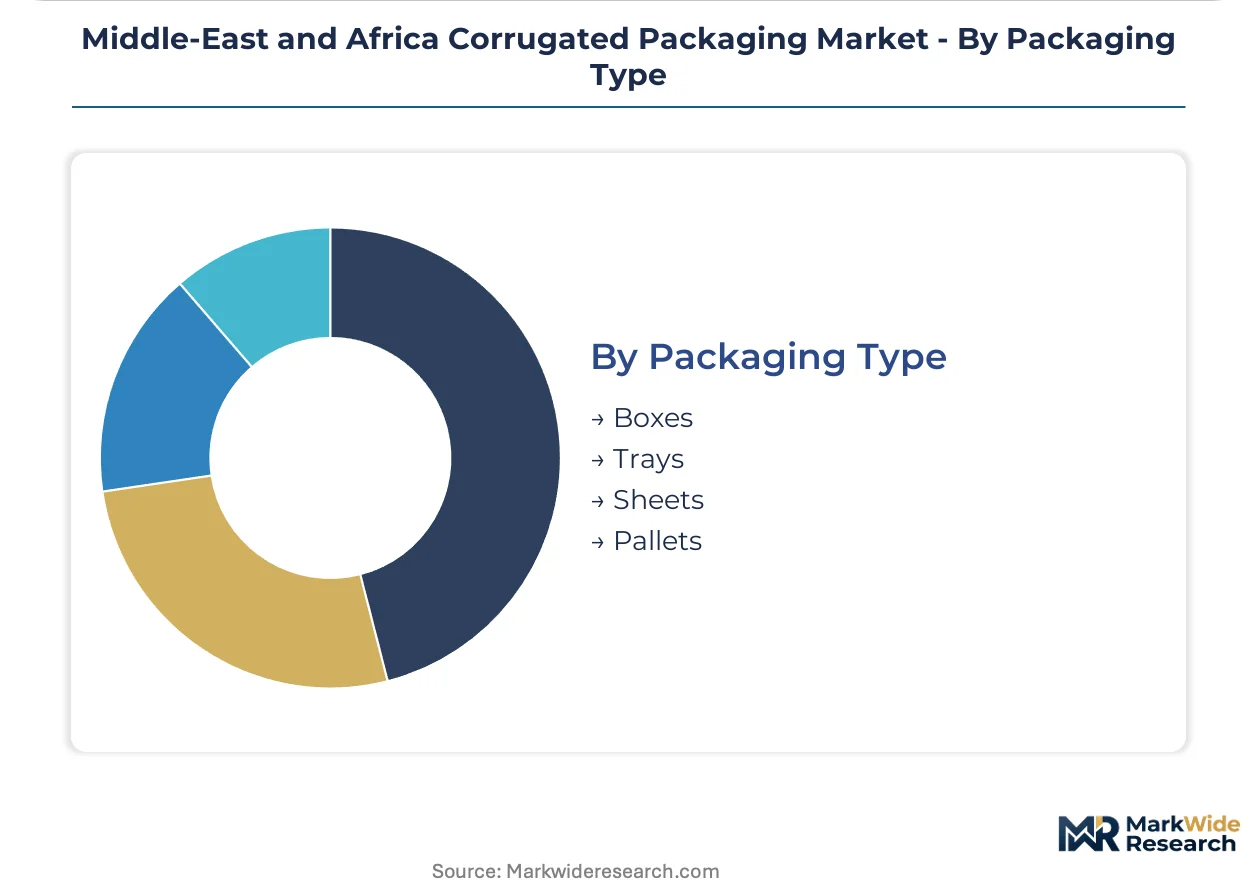
Packaging Type:
Application-driven segmentation maps structural formats to specific handling requirements. Boxes and trays address unitized product protection, while sheets and pallets serve intermediate processing and bulk logistics functions with distinct specification frameworks.
- Boxes:RSC (regular slotted container) and FOL (full overlap) configurations dominate finished goods shipment. Nigerian consumer goods manufacturers specify B-flute single wall for cost optimization, while Saudi dairy processors require coated C-flute for refrigeration compatibility.
- Trays:Open-top formats for display and handling of perishables. SFDA regulations mandate specific tray constructions for date packaging, with ventilation perforations calibrated to moisture release rates during Gulf summer transit.
- Sheets:Unconverted board for downstream fabrication or interlayer protection. Kenyan flower exporters use moisture-resistant kraftliner sheets between pallet layers, sourced from Mondi's specialty production for extended shelf-life properties.
- Pallets:Corrugated substitutes for wood in lightweight, single-use export applications. South African automotive suppliers trial triple wall pallets for European-bound components, navigating EU packaging waste directive compliance through recyclable fiber claims.
Boxes anchor volume throughput. Trays concentrate regulatory-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale food processors and e-commerce fulfillment operators concentrate procurement power across the Middle-East and Africa corrugated packaging landscape. Saudi Arabia's dairy clusters and South Africa's automated distribution centers drive specification intensity. Nigerian logistics platforms and Kenyan agricultural exporters shape demand fragmentation.
Saudi Arabia
SFDA food-contact standards mandate temperature-stable corrugated trays for dairy and date processing clusters. The Kingdom's industrial corridor around Riyadh and Dammam hosts concentrated food manufacturing requiring coated linerboards for perishable distribution. Jubail industrial city anchors heavy industrial packaging demand for petrochemical and automotive parts shipment.
South Africa
Takealot and Jumia fulfillment networks drive die-cut corrugated volume for presentation-ready e-commerce packaging. NRCS paperboard recyclability certification protocols extend product qualification timelines for food-contact applications. Gauteng logistics cluster concentrates automated distribution center procurement, compressing supplier rosters toward integrated producers with direct-to-DC capability.
United Arab Emirates
ESMA Arabic-English bilingual labeling mandates extend pre-production approval timelines for first-time corrugated suppliers. Dubai and Abu Dhabi serve as re-export hubs for European-bound agricultural shipments, exposing converters to EU Green Deal extraterritorial compliance requirements. Jebel Ali port infrastructure shapes logistics-dependent procurement patterns for imported OCC-dependent operations.
Nigeria
E-commerce fulfillment expansion across Lagos and Kano drives adoption of die-cut formats for consumer goods distribution. Port congestion at Apapa and Tin Can Island creates inventory buffer requirements for corrugated sheet and box suppliers. Local converters face technical skill scarcity for CAD-operated rotary die cutter programming below 500-unit batch sizes.
Kenya
Flower and fresh produce export corridors from Nairobi to Dubai create demand for moisture-resistant corrugated formats. Mondi's kraftliner specialization serves extended shelf-life requirements for European-bound agricultural shipments. Mombasa port infrastructure and inland trucking networks shape multi-modal transit packaging specifications for humidity-exposed routes.
Middle-East and Africa Corrugated Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Middle-East and Africa corrugated packaging market. Consolidated procurement by e-commerce platforms and food processors compresses supplier rosters toward integrated producers with captive fiber supply and die-cut capability. Three archetypes dominate: multinational integrated producers with regional mill networks, national converters serving proximity-sensitive industrial clusters, and specialty operators targeting certified food-contact or moisture-resistant specifications. Competitive moves center on backward integration into containerboard production and geographic expansion through mill-level investments in Morocco and Kenya.
Within the multinational integrated tier, Smurfit Kappa and Mondi exemplify scale-driven positioning through regional mill assets and kraftliner specialization. Arabian Packaging Co. LLC occupies a proximity-focused position serving Saudi Arabia's dairy and date processing clusters with shortened delivery lead times. International Paper and DS Smith represent global network players leveraging extraterritorial compliance capabilities for European-bound export shipments. These anchors illustrate how fiber supply security and certification eligibility separate sustainable competitive position from transactional volume capture.
| Leading Market Players |
|---|
| International Paper |
| DS Smith |
| Smurfit Kappa |
| Arabian Packaging Co. LLC |
| United Carton Industries Company |
| Mondi |
| WestRock Company |
| Stora Enso |
| Napco National |
| Others |
Supply & Pricing Matrix
Jebel Ali's containerboard import throughput capacity dynamics translate directly into downstream pricing power for UAE-based corrugated converters serving re-export corridors. Saudi Arabia's integrated mill investments in Rabigh and Yanbu are compressing regional linerboard spot premiums by eliminating Red Sea freight exposure for Gulf Cooperation Council buyers.
Pricing Analysis
Cost-plus contracts indexed to RISI Fastmarkets OCC price assessments dominate procurement between Moroccan containerboard mills and Nigerian box plants. Price differentiation separates SFDA-certified food-contact grades commanding 25-35% premiums from standard industrial board, with volume scale and water-based ink certification as secondary tiering factors. Pricing pressure intensifies in South Africa's Gauteng cluster as Takealot extends payment terms to 60 days while demanding die-cut capability investments. Small-batch e-commerce converters exhibit highest price sensitivity, while Saudi dairy processors prioritize temperature stability over unit cost.
Supply Chain Analysis
Upstream recovered paper feedstock draws from European sorting facilities in Germany, the Netherlands, and the UK for Gulf Cooperation Council containerboard operations. Raw material dependencies center on imported old corrugated containers, starch adhesives, and water-based barrier coatings. Single-source vulnerability concentrates at Jebel Ali and Durban ports where customs delays cascade through just-in-line supply contracts. Distribution runs through direct mill relationships for Saudi industrial corridor accounts and wholesale aggregators for fragmented East African agricultural exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the Middle-East and Africa corrugated packaging landscape creates niche opportunities as e-commerce procurement consolidation simultaneously compresses supplier rosters and strands tier-two converters without die-cut capability.
For Market Incumbents: Harden mill-level cost positions through backward integration into containerboard production at Moroccan and Kenyan sites, insulating against OCC import volatility. Secure ESMA and SFDA certification eligibility ahead of Gulf Cooperation Council harmonization to defend against European-integrated entrants targeting export compliance premiums. For New Entrants and Emerging Players: Pursue moisture-resistant specialty formats for Kenyan flower export corridors where Mondi's kraftliner dominance leaves white space for extended shelf-life tray innovations. Target Nigerian e-commerce fulfillment networks with automated rotary die-cut services, leveraging CAD technician scarcity at incumbent Lagos converters as entry friction. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational paper groups divesting non-core African box plant assets ahead of regional mill consolidation. Mid-cap converters with captive fiber supply and established SFDA relationships offer viable 5-10 year holdings as certification barriers intensify. Watch for EU Green Deal carbon border adjustment implementation as inflection signal for compliance-premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Production | Captive fiber supply at Moroccan mills lowers input cost exposure for Smurfit Kappa's regional box plants. |
| SFDA Certification Investment | Temperature-stable tray qualification opens Saudi dairy and date processing cluster procurement to compliant converters. |
| Digital Print Capability Expansion | Inkjet-enabled corrugated displays serve UAE cosmetics brands collapsing minimum order quantities to 500-unit batches. |
| Die-Cut Tooling Automation | CAD-operated rotary die cutters address South African and Nigerian e-commerce fulfillment center presentation-ready packaging specifications. |
| Closed-Loop Recycling Infrastructure | Post-consumer recycled content certification positions early movers for Gulf Cooperation Council harmonized waste directive compliance. |
Research Methodology
A spread of perspectives from corrugated plant managers, procurement leads at Saudi food processors, e-commerce logistics directors, containerboard mill technical directors, and UAE regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, RISI Fastmarkets pulp and paper price assessments, SEC filings of listed packaging groups, and Gulf Cooperation Council standardization authority documentation. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions spanned product type, end-use industry, distribution channel, and packaging format, with regional regulatory cluster as an additional corrugated-specific tier. CAGRs derived from weighted average of historical trajectory and forward-looking capacity absorption rates. Industry-specific forecast inputs included OCC price volatility assumptions and e-commerce fulfillment center buildout pipelines.
Sensitivities concentrate around EU Green Deal extraterritorial enforcement timing, Gulf Cooperation Council waste directive harmonization schedules, and Kenyan flower export volume fluctuations. Forecasts reflect documented assumptions subject to revision from these triggers. Cross-checking against RISI Fastmarkets containerboard price indices and national customs import data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Corrugated Handle Box Market