
 Glass Balustrade Lamination Market | 2026-2036
Glass Balustrade Lamination Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Balustrade Lamination Market Analysis
Specification-grade SGP interlayer certification is rotating demand toward premium lamination tiers capable of post-breakage integrity. Saint-Gobain leverages its European float-glass backbone to dominate structural balustrade supply. AGC Inc anchors Asia-Pacific project pipelines through dedicated architectural glass divisions. Xinyi Glass Holdings Limited competes on manufacturing scale across tempered-laminate hybrid lines.
Glass balustrade lamination bonds multiple glass plies with polymeric interlayers to create structural barriers that retain fragments upon fracture, typically achieving 1.14mm to 2.28mm nominal interlayer thickness for cantilevered loading. The process employs autoclave or vacuum-bag curing at controlled temperature-pressure cycles to ensure optical clarity and delamination resistance. Laminated glass with SGP interlayers commands the fastest-growing specification tier due to superior stiffness and edge stability versus standard PVB. Residential applications remain the volume anchor, though commercial facades and balcony retrofits concentrate margin pools where engineering liability and wind-load certification requirements escalate.
CE marking under EN 14449 and IBC Chapter 24 in the United States govern impact resistance and structural performance for laminated balustrade assemblies, while China's GB standards enforce interlayer adhesion thresholds for public building applications. Compliance with these frameworks shapes procurement specifications and excludes uncertified suppliers from project bidding. Stakeholders must monitor evolving fire-performance classifications and regional amendments to structural glass codes that could requalify existing product portfolios.
Market Dynamics
Specification-grade SGP interlayer certification is bifurcating procurement tiers across residential and commercial balustrade specifications, compressing margins for uncertified laminators while elevating premium-grade suppliers into structural glass project pipelines.
Growth Catalysts
- EN 14449 and IBC Chapter 24 tightening:Impact resistance thresholds for cantilevered balustrades are accelerating replacement cycles in high-rise retrofits across Singapore and Dubai.
- Facade retrofit mandates:Coastal Chinese provinces are enforcing interlayer adhesion standards that disqualify monolithic glass in public building balcony replacements.
- Toughened-laminate hybrid processes:Heat-soaked tempered substrates bonded with structural interlayers are penetrating luxury villa construction in the UAE.
Market Restraints
- PVB resin cost volatility:Petrochemical feedstock fluctuations squeeze margin stability for standard-interlayer producers.
- Autoclave supply concentration:Curing equipment fabrication centers in Germany and Italy create capacity bottlenecks for Asian laminators scaling specification-grade output.
- Edge delamination in marine environments:Salt-laden coastal atmospheres degrade standard PVB adhesion, limiting warranty terms for untreated installations.
Strategic Opportunities
- Vietnam and Indonesia residential towers:Underpenetrated high-rise construction markets lack certified local lamination capacity, creating import substitution openings.
- Digital specification platforms:Architect and contractor procurement is migrating to BIM-integrated material libraries that filter by certification tier.
- EU Green Deal embodied-carbon tracking:Low-carbon float-glass sourcing is becoming a scored criterion in public tender evaluations.
Industry Challenges
- SGP interlayer processing expertise:Ionoplast laminate fabrication requires temperature-pressure calibration beyond standard PVB autoclave protocols, constraining qualified technician supply.
- Multi-jurisdiction certification timelines:Simultaneous CE marking, IBC compliance, and GB standard testing extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Balustrade Lamination Market |
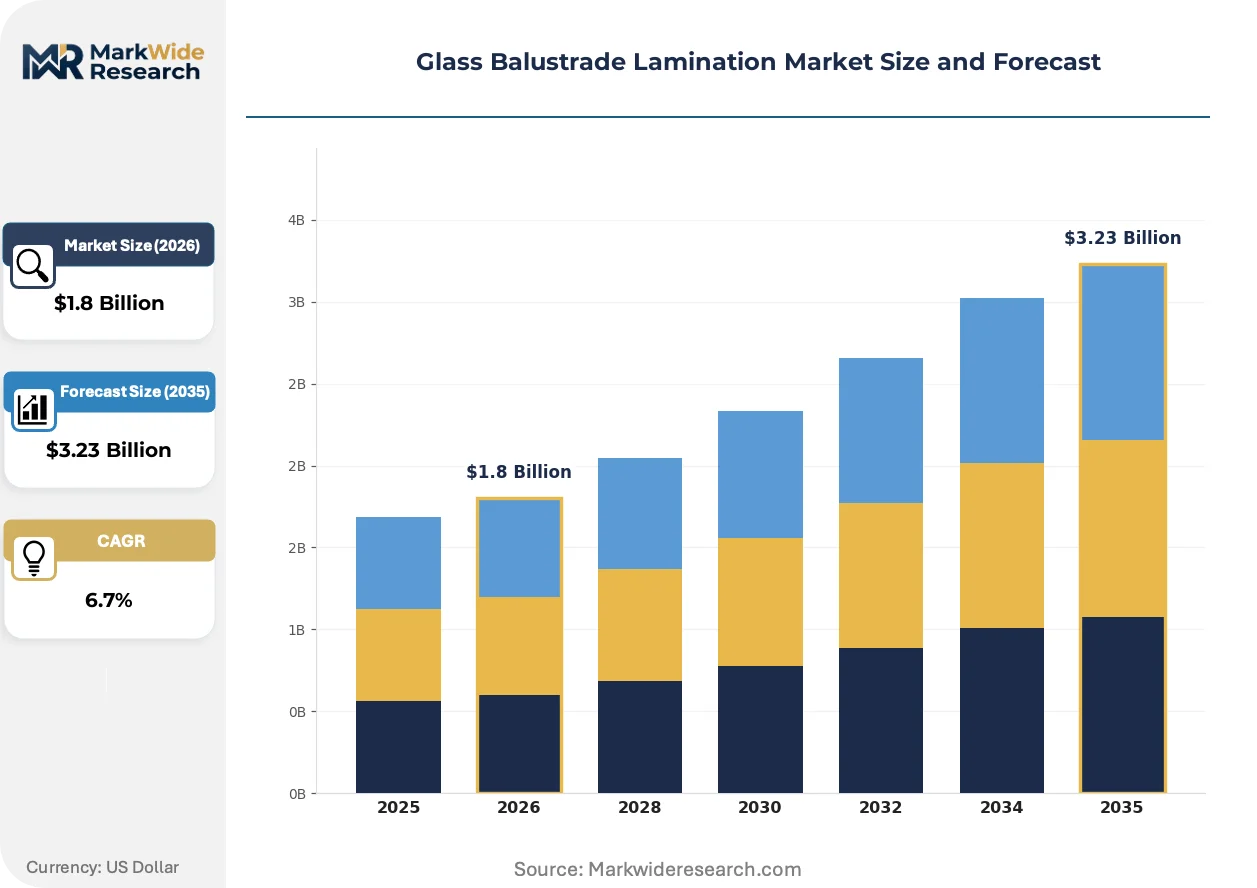
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, PVB, SGP Application: Residential, Commercial, Safety Barriers, Decorative Installation: Indoor, Outdoor, Facade, Balconies End User: Architects, Contractors, Builders, Homeowners |
| Companies Covered | Saint-Gobain, AGC Inc, Xinyi Glass Holdings Limited, Guardian Industries, Fuyao Glass Industry Group Co., Ltd., Schott AG, Vitro, Q-railing, IQ Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Balustrade Lamination Market Emerging Trajectories
Structural glass engineering is converging with digital fabrication and embodied-carbon accounting, reshaping how balustrade specifications are validated, procured, and installed across high-rise developments.
Stiffness-optimized SGP interlayers are displacing conventional PVB in cantilevered balustrade applications where post-breakage integrity determines code compliance. Specifiers in Singapore and Dubai are mandating ionoplast construction for projects above 30 stories, where wind-load deflection tolerances exceed standard laminate capabilities. The specification tier is bifurcating between premium structural grades and commodity safety laminates, compressing mid-tier PVB suppliers into price-competitive residential retrofits.
CE marking under EN 14449 is tightening edge-stability testing protocols for laminated balustrade assemblies exposed to climatic cycling. European notified bodies are now requiring accelerated aging validation for installations within 5 kilometers of saltwater coastlines. Mediterranean and North Sea projects are responding by specifying enhanced-edge-protection treatments, adding processing steps that favor vertically integrated glass processors.
Architect procurement patterns are rotating toward performance-guaranteed supply contracts that bundle lamination, structural engineering certification, and installation liability. General contractors in the UAE and Australia are consolidating vendor panels to single-source structural glass packages, displacing fragmented subcontractor bidding. This concentration is visible in Dubai's high-rise residential pipeline, where developer-led framework agreements now lock in 24-month laminate supply commitments.
Glass Balustrade Lamination Market Segmentation
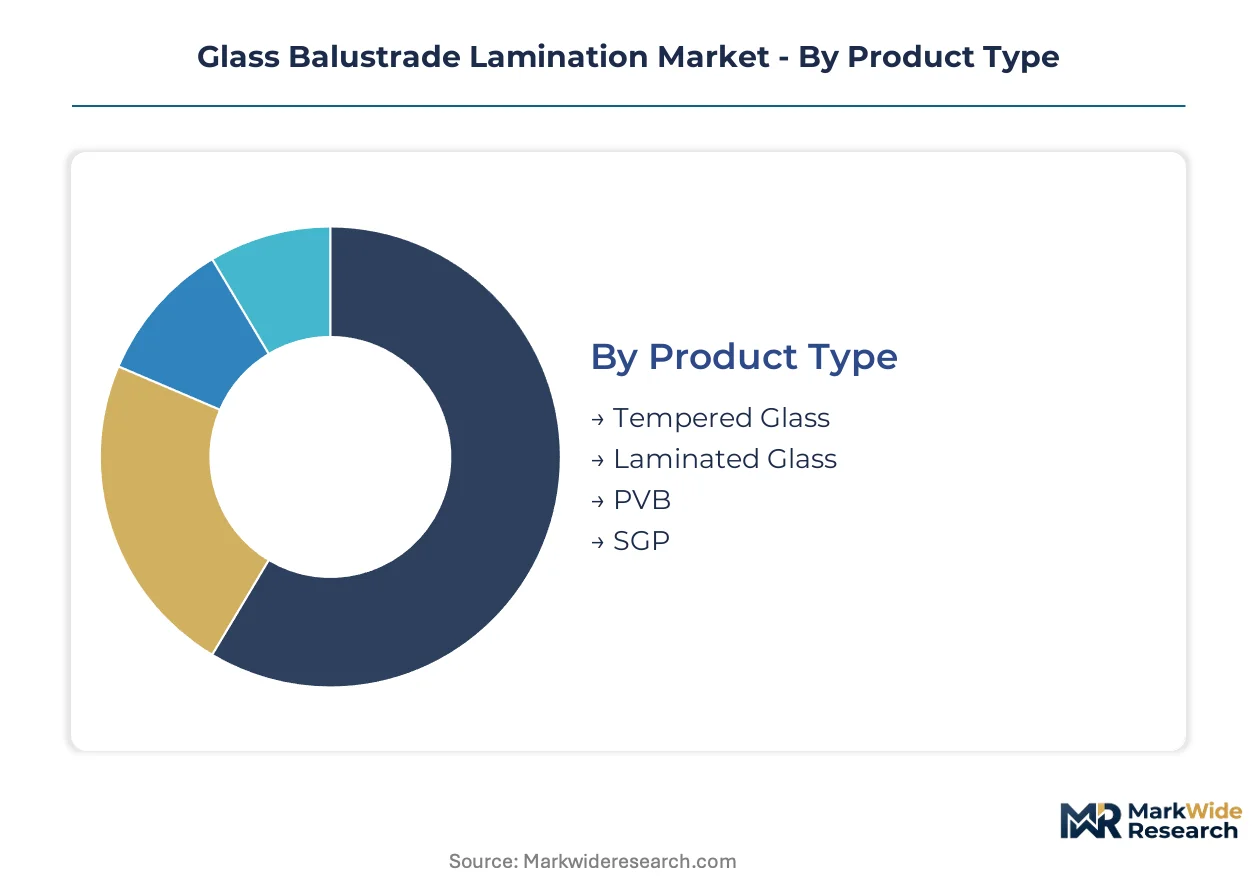
Segmentation in the glass balustrade lamination market reveals how specification-grade certifications, installation environments, and procurement authority reshape competitive positioning across product tiers. Understanding these divisions exposes where margin pools concentrate and which customer types drive technology adoption.
Product Type:
Domestic consumption of tempered and laminated glass concentrates in coastal Chinese provinces and UAE luxury villa construction, while SGP interlayer demand exports primarily to Singapore and Dubai high-rise projects. PVB retains volume anchorage in standard residential retrofits across mature markets.
- Tempered Glass:Heat-soaked substrates undergo controlled thermal treatment to reduce spontaneous breakage risk from nickel sulfide inclusions. Singapore and Dubai specify tempered-laminate hybrids for cantilevered balustrades above 30 stories where wind-load deflection tolerances are stringent. EN 14449 and IBC Chapter 24 heat-soak testing requirements compress supply chains toward certified processors.
- Laminated Glass:Multiple glass plies bond with polymeric interlayers to create structural barriers retaining fragments upon fracture, typically achieving 1.14mm to 2.28mm nominal interlayer thickness. Coastal Chinese provinces enforce facade retrofit mandates that disqualify monolithic glass in public building balcony replacements, concentrating demand in Guangdong and Zhejiang manufacturing clusters.
- PVB:Standard polyvinyl butyral interlayers serve cost-sensitive residential retrofits where post-breakage integrity requirements remain basic. Petrochemical feedstock volatility squeezes margin stability for producers lacking backward integration into resin supply.
- SGP:Ionoplast interlayers command premium positioning through superior stiffness and edge stability versus conventional PVB. Processing requires temperature-pressure calibration beyond standard autoclave protocols, constraining qualified technician supply.
Laminated glass holds the largest share; momentum sits with SGP as specification-grade certification penetrates high-rise structural applications.
Application:
Cost tier differentiation separates premium structural specifications from commodity safety installations, with commercial facades commanding engineering liability premiums and residential volume anchoring baseline production.
- Residential:Volume anchor for standard PVB laminates across single-family homes and low-rise apartment balcony retrofits. Dubai and UAE luxury villa construction specifies toughened-laminate hybrids for pool enclosures and terrace barriers.
- Commercial:Facade and atrium applications concentrate margin pools where wind-load certification and engineering liability escalate. Singapore high-rise towers mandate SGP construction for projects above 30 stories.
- Safety Barriers:Code-mandated installations in public buildings and transportation infrastructure require EN 14449 or IBC Chapter 24 compliance. Coastal Chinese provinces enforce interlayer adhesion standards that accelerate replacement cycles.
- Decorative:Aesthetic-driven specifications in hospitality and retail employ tinted, patterned, or LED-integrated laminates. Lower structural performance thresholds permit mid-tier PVB sourcing.
Residential applications dominate volume; commercial facades capture the steepest expansion trajectory as developer-led framework agreements consolidate vendor panels.
Installation:
Environmental exposure severity dictates interlayer selection and edge protection requirements, with marine atmospheres degrading standard PVB adhesion and accelerating specification migration toward enhanced treatments.
- Indoor:Climate-controlled environments permit standard PVB specifications with reduced delamination risk. Atrium and staircase applications in commercial buildings prioritize optical clarity over extreme weathering resistance.
- Outdoor:UV exposure and thermal cycling demand enhanced interlayer formulations. Salt-laden coastal atmospheres in Mediterranean and North Sea projects now require accelerated aging validation within 5 kilometers of shorelines.
- Facade:Curtain wall integration subjects laminates to multi-directional wind loads and seismic drift. CE marking under EN 14449 tightens edge-stability testing protocols for climatic cycling exposure.
- Balconies:Cantilevered loading configurations represent the most demanding structural application. Dubai and Singapore high-rise residential towers drive specification-grade SGP penetration.
Facade installations command the largest project values; balcony applications are climbing the fastest as retrofit mandates proliferate across coastal jurisdictions.
End User:
Procurement authority concentration shapes vendor selection, with architects and contractors migrating toward BIM-integrated material libraries that filter by certification tier and performance guarantee bundling.
- Architects:Specification authority rotates demand toward performance-guaranteed supply contracts bundling lamination, structural engineering certification, and installation liability. Digital procurement platforms filter selections by CE marking and IBC compliance tiers.
- Contractors:General contractors in UAE and Australia consolidate vendor panels to single-source structural glass packages, displacing fragmented subcontractor bidding. Framework agreements lock in 24-month laminate supply commitments.
- Builders:Production homebuilders prioritize cost-optimized PVB specifications with standardized dimensions. Volume contracting favors suppliers with captive float-glass supply.
- Homeowners:Retail procurement concentrates in renovation-driven replacement cycles with limited technical specification involvement. Warranty terms and aesthetic preferences dominate selection criteria.
Contractors hold the largest procurement volume; architects are gaining share fastest as digital specification platforms elevate certification-based filtering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese manufacturing clusters dominate supply to Southeast Asian and Middle Eastern project sites, while European fabricators serve premium specification-grade demand through intra-regional trade. Import dependency concentrates in Vietnam and Indonesia where certified lamination capacity lags residential tower construction.
China
Guangdong and Zhejiang provinces anchor manufacturing output for tempered-laminate hybrid lines serving domestic facade retrofit mandates. GB standards enforcement on interlayer adhesion thresholds disqualifies monolithic glass in public building balcony replacements across coastal jurisdictions. Shenzhen and Foshan industrial clusters are scaling autoclave capacity to meet specification-grade SGP certification requirements for Singapore and Dubai export orders.
Singapore
High-rise residential towers above 30 stories drive specification-grade ionoplast balustrade penetration where wind-load deflection tolerances exceed standard laminate capabilities. Building and Construction Authority regulations align with EN 14449 impact resistance thresholds for cantilevered installations. Marina Bay and Orchard Road developments are consolidating vendor panels through developer-led framework agreements locking in 24-month supply commitments.
United Arab Emirates
Dubai luxury villa construction specifies toughened-laminate hybrids for pool enclosures and terrace barriers. MOHAP technical regulations govern structural glass performance in high-rise residential applications. Jumeirah and Downtown Dubai project pipelines are accelerating replacement cycles as IBC Chapter 24-equivalent standards tighten safety compliance thresholds.
Germany
Autoclave fabrication centers in Bavaria and North Rhine-Westphalia create equipment supply bottlenecks for Asian laminators scaling specification-grade output. CE marking under EN 14449 tightens edge-stability testing protocols for climatic cycling exposure. Hamburg and Bremen port clusters are shipping curing equipment to Vietnam and Indonesia where underpenetrated markets lack certified local capacity.
Vietnam
Underpenetrated high-rise construction markets in Ho Chi Minh City and Hanoi create import substitution openings for certified laminate supply. National construction codes are adopting interlayer adhesion standards that accelerate replacement of monolithic glass in public building retrofits. Da Nang and Hai Phong industrial zones are attracting foreign joint ventures to establish captive lamination capacity for residential tower pipelines.
Glass Balustrade Lamination Market Vendor Landscape
Listed leaders compete with private specialists across capital access and certification agility, producing a tiered structure where scale-driven float-glass backbones face nimble regional fabricators. Consolidation concentrates around integrated glass processors with captive resin supply and autoclave networks. Three archetypes dominate: European majors with specification-grade certification depth, Asian volume players with tempered-laminate hybrid scale, and regional specialists serving retrofit markets. Competitive moves center on backward integration into PVB and SGP resin supply, plus geographic expansion through equipment licensing to bypass autoclave fabrication bottlenecks.
Within the European-major archetype, Saint-Gobain and Schott AG exemplify certification-depth positioning anchored to EN 14449 compliance frameworks. AGC Inc represents the Asia-Pacific volume vector with dedicated architectural glass divisions serving Singapore and Dubai project pipelines. Among Chinese scale players, Xinyi Glass Holdings Limited occupies a manufacturing-scale position across tempered-laminate hybrid lines competing on output volume rather than premium-tier specification access.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc |
| Xinyi Glass Holdings Limited |
| Guardian Industries |
| Fuyao Glass Industry Group Co., Ltd. |
| Schott AG |
| Vitro |
| Q-railing |
| IQ Glass |
| Others |
Supply Flow & Price Mechanics
Autoclave fabrication capacity in Germany and Italy anchors cost structures for specification-grade lamination, concentrating equipment supply leverage among European fabricators while Asian laminators face 14-18 month certification timelines that compress margin buffers. Scale economies in float-glass production favor vertically integrated processors with captive resin supply, forcing price competition downward for standard PVB tiers while elevating SGP-certified premiums.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing across structural glass packages, with premium-mid-economy pricing differentiation separating SGP-certified ionoplast tiers from standard PVB residential retrofits. Certification grade and volume scale drive price spreads, with bulk framework agreements locking 24-month supply commitments at stabilized rates. Cost compression in commodity PVB intensifies because petrochemical feedstock volatility squeezes non-integrated producers. Production homebuilders exhibit highest price sensitivity, while architect-led procurement prioritizes performance guarantees over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites resin feedstock flows to Guangdong and Zhejiang manufacturing clusters, where Chinese float-glass output feeds tempered-laminate hybrid production for Singapore and Dubai export orders. Supply draws from Germany and Italy for autoclave equipment, Saudi Arabia for petrochemical intermediates, and Belgium for ionoplast interlayer precursors. Single-source vulnerability concentrates in curing equipment fabrication, where Bavarian and North Rhine-Westphalian suppliers control Asian capacity expansion. Distribution runs through developer-led framework agreements consolidating vendor panels into 24-month structural glass packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EN 14449 and IBC Chapter 24 certification creates defensive moats for qualified laminators, as multi-jurisdiction testing timelines exclude rapid-follower competition and lock incumbent relationships with architect-specified procurement platforms.
For Market Incumbents: Fortify specification-grade certification depth through backward integration into SGP resin supply and captive autoclave networks in Shenzhen and Foshan. Emerging Vietnamese joint ventures threaten export positioning; preemptive capacity licensing to Ho Chi Minh City industrial zones extends reach without capital-heavy greenfield investment. Channel control through BIM-integrated material libraries cements architect specification authority. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia residential tower pipelines where certified local lamination capacity lags construction velocity. Da Nang and Hai Phong zones offer import substitution openings before national codes harden interlayer adhesion standards. Go-to-market leverage rests on equipment licensing partnerships with German autoclave fabricators, bypassing 18-month fabrication queues. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specification-grade SGP processors with developer framework agreements spanning 24-month windows. Long-term viability favors integrated glass processors combining float-glass supply, captive interlayer production, and certified lamination capacity. Acquisition targets should demonstrate EN 14449 and IBC Chapter 24 compliance with active pipeline in Singapore or Dubai high-rise residential. The signal to watch is coastal Chinese province adoption of GB standard amendments tightening public building retrofit mandates, which would requalify product portfolios and accelerate replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SGP Resin | Captive ionoplast supply secures margin control against petrochemical volatility and qualified technician scarcity. |
| Autoclave Capacity Licensing | Equipment partnerships with German fabricators unlock Vietnamese and Indonesian market entry without fabrication bottlenecks. |
| CE Marking and IBC Dual Certification | Multi-jurisdiction compliance qualifies processors for Singapore and Dubai developer framework agreements. |
| BIM-Integrated Specification Platforms | Digital procurement filtering by certification tier captures architect specification authority before contractor bidding. |
| Framework Agreement Structuring | 24-month supply commitments with UAE and Australian general contractors displace fragmented subcontractor competition. |
Methodological Framework
Initial hypotheses were tested against primary input from glass processing plant managers, architectural specification consultants, general contractor procurement leads, and structural engineering certifiers, and refined through secondary validation against customs trade data, SEC filings from listed glass manufacturers, EN 14449 notified body disclosure records, and building permit databases from Singapore and Dubai. Bottom-up project pipeline enumeration triangulated with top-down float-glass consumption estimates across coastal Chinese provinces.
Variance decomposition across product type, application tier, installation environment, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by SGP penetration assumptions and retrofit mandate enforcement timelines. Industry-specific inputs incorporated autoclave capacity expansion schedules from Bavarian equipment fabricators and interlayer resin supply commitments from Saudi petrochemical complexes.
Material uncertainties — regulatory amendment timelines for GB standards in China, ionoplast processing technician availability, and petrochemical feedstock price swings — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification adoption curves and coastal retrofit enforcement intensity. Practitioners should keep alternative scenarios live as EN 14449 edge-stability testing protocols evolve and EU Green Deal embodied-carbon scoring penetrates public tender evaluations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Impact Resistant Glass Market
Glass
Glass Manufacturing Market
Glass
Low Iron Glass Market
Glass
Foam Glass Granulate Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Global Glass Tempering System Market
Glass
Crystalware and Glassware Market
Glass
Spherical Silica Market
Glass
Glass Forming Machine Market
Glass
Advanced Glass Market
Glass
Glass Prepreg Market
Glass
Metallic Glass Market
Glass
Fiberglass Window Market
Glass
Glass Mason Jars Market
Glass
North America Glass Insulators Market