
 Soda Feldspar Market | 2026-2036
Soda Feldspar Market Size, Share, and Industry Trends Forecast 2026-2036
Soda Feldspar Market Insights
The EU Green Deal is expanding compliance obligations across ceramics and glass supply chains, compelling raw material suppliers to document carbon intensity and traceability. Imerys Minerals leverages vertical integration from mine to refined product to sustain European market access. The Quartz Corporation anchors North American supply through high-purity deposits in North Carolina. Sibelco Nordic competes on logistics scale across Baltic and North Sea routes.
Soda feldspar is an alkali aluminosilicate mineral with a typical composition of Na2O·Al2O3·6SiO2, characterized by its low iron content and fluxing action that reduces melting temperatures in ceramic and glass batches. Its primary industrial purpose centers on serving as an essential flux in whiteware ceramics, container glass, and fiberglass formulations where thermal behavior and optical clarity matter. Sodium feldspar grades dominate volume flows into glass manufacturing where consistent chemistry preserves furnace efficiency, while micronized feldspar captures premium positioning in paints and coatings demanding controlled particle size distribution. Ceramics applications remain structurally mature with stable offtake from construction-linked tile producers, though electronics-grade specifications for technical ceramics are emerging as a concentrated margin pool.
REACH registration requirements in Europe govern chemical safety documentation for imported feldspar concentrates, while China's GB standards enforce alumina and alkali oxide specifications for domestic ceramic body formulations. The EPA's mining waste regulations in the United States shape permitting timelines and reclamation costs for new extraction projects. Stakeholders must monitor evolving emissions accounting rules under the EU Carbon Border Adjustment Mechanism and assess how dual carbon goals in China redirect domestic feldspar flows from export to internal ceramic and glass consumption.
Market Dynamics
Glass container manufacturers are compressing iron content specifications below 0.1% Fe2O3, forcing soda feldspar suppliers to reconfigure beneficiation circuits and secure low-iron ore reserves.
Growth Catalysts
- EU Green Deal carbon accounting:Ceramic and glass producers now mandate documented carbon intensity from raw material suppliers, creating preferential offtake for low-emission feldspar concentrates.
- China's dual carbon goals:Domestic ceramic body formulations under tightening GB standards are absorbing more high-purity sodium feldspar, redirecting export volumes toward internal consumption.
- Fiberglass reinforcement demand:Wind turbine blade manufacturers are specifying consistent alkali oxide ratios in E-glass formulations, stabilizing long-term contracts for standardized soda feldspar grades.
Market Restraints
- Turkey's Aegean supply concentration:European ceramics dependence on single-region mining output creates vulnerability to export licensing disruptions and currency volatility.
- Energy cost escalation in beneficiation:Wet grinding and magnetic separation circuits consume substantial electricity, compressing margins when grid tariffs spike.
- Nepheline syenite substitution:Alternative alkali aluminosilicate fluxes with lower silica ratios are displacing soda feldspar in some glass batch formulations.
Strategic Opportunities
- Technical ceramics specification gap:Electronics-grade feldspar for multilayer ceramic capacitors remains underpenetrated, with purity thresholds exceeding standard ceramic body requirements.
- North Carolina high-purity deposits:Spruce Pine district pegmatites offer captive supply potential for North American glass and ceramics producers seeking supply chain proximity.
- EU Carbon Border Adjustment Mechanism:Embedded emissions accounting for imported ceramics creates competitive advantage for European-mined feldspar with verified low-carbon extraction.
Industry Challenges
- REACH registration complexity:ECHA chemical safety dossiers for feldspar concentrates require extensive toxicological data, extending market access timelines for new suppliers.
- Legacy furnace chemistry lock-in:Container glass producers face technical risk and requalification costs when switching feldspar sources with varying trace element profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soda Feldspar Market |
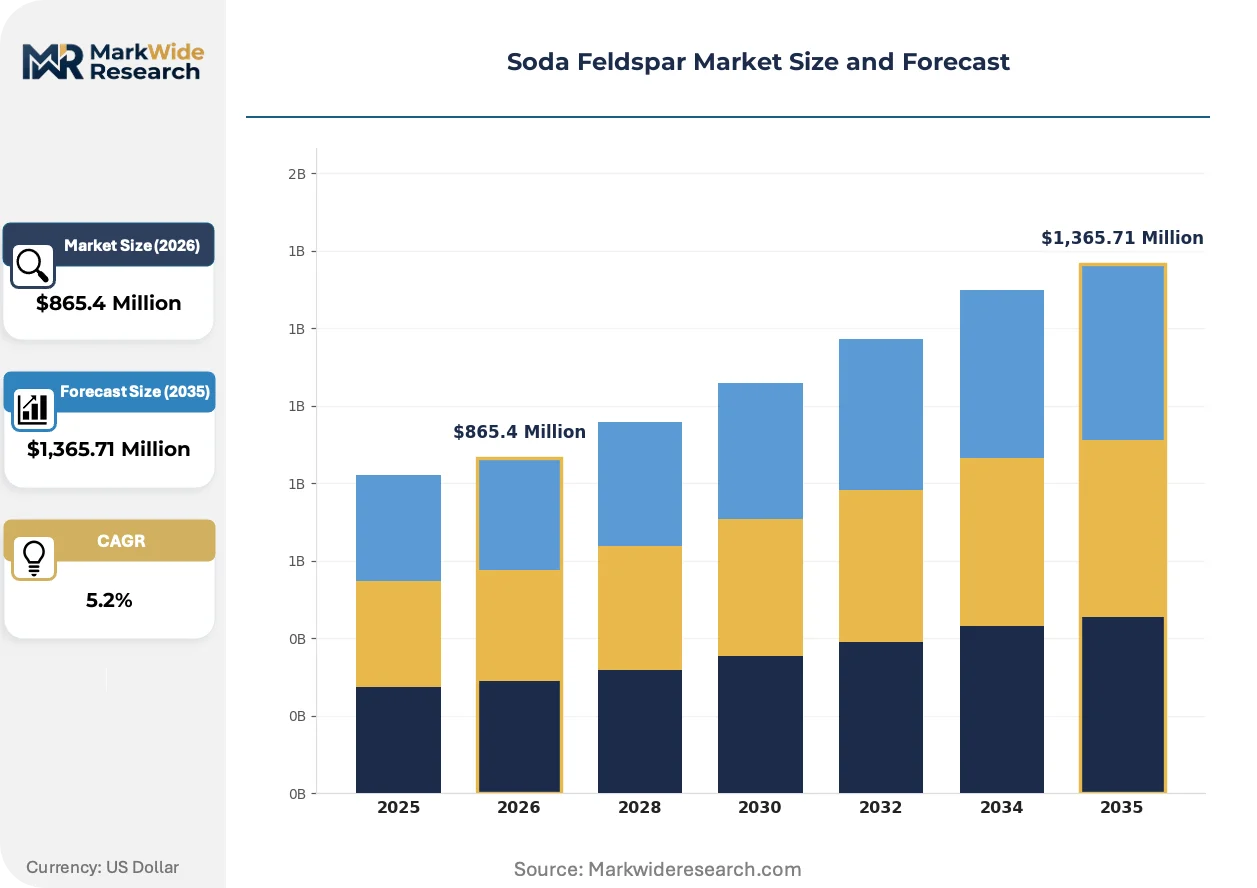
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,365.71 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Feldspar, Sodium Feldspar, Calcium Feldspar, Micronized Feldspar Application: Ceramics, Glass Manufacturing, Paints, Fillers End User: Construction, Automotive Parts, Consumer Goods, Electronics Packaging Type: Bags, Bulk, Drums, Pails |
| Companies Covered | The Quartz Corporation, LB Minerals Ltd., Adolf Gottfried Tonwerke GmbH, Esan, I-Minerals Inc., Imerys Minerals, Quarzwerke GmbH, Micronized Group, Sibelco Nordic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soda Feldspar Market Trends and Innovations
Beneficiation technology and emissions transparency are converging to reshape competitive positioning in soda feldspar supply, with digital traceability systems now as critical as physical purity metrics.
Sensor-based ore sorting is integrating machine vision and X-ray transmission systems to pre-concentrate run-of-mine material before energy-intensive grinding. Glass manufacturers in Germany and Italy are specifying this technology in supplier qualification audits. The structural compression of waste rock disposal volumes is reducing tailings footprint and associated permitting liabilities.
REACH registration requirements under ECHA governance now extend to imported feldspar concentrates entering European customs territory. Industrial consequence includes mandatory safety data sheets and substance volume tracking. Container glass and whiteware ceramics segments are responding by consolidating supplier bases to reduce compliance administration burden.
Long-term offtake contracting is displacing spot market purchases among major ceramics producers. Italian and Spanish tile manufacturers are negotiating three-year supply agreements with fixed volume floors and price adjustment clauses tied to energy indices. This pattern is most visible in Mediterranean basin procurement, where logistics integration and inventory positioning have become competitive differentiators.
Soda Feldspar Market Segmentation
Soda feldspar demand fragments across mineral chemistry, particle size, and purity grades that dictate furnace compatibility and optical performance. Specification mismatches between supplier output and buyer batch chemistry trigger costly reformulation cycles, making segment alignment a procurement priority.
Product Type:
Replacement cycles in glass furnace refractories and ceramic body formulations are accelerating specification upgrades toward higher-purity sodium grades and engineered particle distributions.
- Sodium Feldspar:Dominant alkali aluminosilicate with Na2O content typically 10-11% and iron below 0.1% Fe2O3 for optical-grade glass. Container manufacturers in Germany and Italy are locking in long-term contracts for low-iron sodium feldspar to meet E-glass alkali ratio specifications for wind turbine blade reinforcement.
- Micronized Feldspar:Finely ground to sub-45 micron particle size distribution with tight D50 control for surface coating applications. Paints and coatings producers in France specify micronized grades for gloss retention and scrub resistance in architectural finishes, though energy-intensive grinding compresses supplier margins during electricity price spikes.
- Potassium Feldspar:Higher K2O content suits sanitaryware and some ceramic body formulations where thermal expansion control differs from sodium grades.
- Calcium Feldspar:Anorthite-rich composition serves specialized glass batches requiring modified viscosity curves and lower alkali leaching.
Sodium feldspar sits at the top of the volume ranking, with micronized feldspar climbing the fastest.
Application:
Cost tier differentiation separates commodity flux purchases from premium specifications where purity documentation commands price premiums.
- Glass Manufacturing:Largest consumption segment spanning container glass, flat glass, and fiberglass formulations. E-glass producers require consistent Na2O+K2O totals near 14% with tight variance bands; The Quartz Corporation's North Carolina deposits anchor North American supply for this specification.
- Ceramics:Whiteware, tiles, and sanitaryware bodies depend on feldspar fluxing to reduce firing temperatures. Italian and Spanish tile manufacturers are consolidating supplier bases to reduce REACH compliance administration burden under ECHA governance.
- Paints:Functional filler applications leverage controlled particle size for opacity and durability in architectural coatings.
- Fillers:Lower-specification grades serve plastics and rubber compounding where color consistency matters less than cost.
Glass manufacturing commands the highest volume share, while ceramics applications demonstrate the steepest expansion trajectory in technical specifications.
End User:
Customer type segmentation reveals diverging procurement patterns between project-driven construction offtake and contract-manufacturing electronics demand.
- Construction:Ceramic tile and sanitaryware consumption tracks residential and commercial building cycles. Mediterranean basin tile producers are negotiating three-year supply agreements with fixed volume floors and energy-indexed price adjustment clauses.
- Electronics:Emerging demand center for high-purity feldspar in multilayer ceramic capacitors and technical ceramics. Purity thresholds exceed standard ceramic body requirements, creating a concentrated margin pool for qualified suppliers.
- Automotive Parts:Fiberglass reinforcement for composite components and specialized glass formulations for vehicle glazing.
- Consumer Goods:Container glass for food and beverage packaging, where iron content specifications are compressing below 0.1% Fe2O3.
Construction absorbs the greatest tonnage, with electronics specifications gaining share fastest on value terms.
Packaging Type:
Supply chain proximity and inventory velocity determine packaging selection, with bulk dominating high-volume flows and bags serving dispersed ceramic producers.
- Bulk:Unpackaged material delivered by pneumatic trailer or vessel for integrated glass and ceramics plants with silo storage. Imerys Minerals leverages vertical integration from mine to refined product to sustain European market access for bulk deliveries.
- Bags:25-50kg multi-wall paper or polypropylene sacks for small and mid-size ceramic producers lacking bulk handling infrastructure. Sibelco Nordic competes on logistics scale across Baltic and North Sea routes for bagged material distribution.
- Drums:Steel or fiber containers for specialized micronized grades requiring moisture protection during extended storage.
- Pails:Small-format packaging for laboratory, sampling, and specialty coating applications.
Bulk shipments lead on volume, with bagged formats expanding most quickly in Eastern European ceramic hub development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The soda feldspar industry traces its modern industrial lineage to European ceramic traditions, with Germany and Italy establishing early beneficiation standards that now govern global trade specifications. Regional markets today diverge sharply between mature European compliance frameworks and Asia-Pacific capacity expansion.
China
Domestic glass and ceramics manufacturers are absorbing record volumes of high-purity sodium feldspar as GB standards tighten alumina and alkali oxide thresholds. The country's dual carbon goals redirect export volumes toward internal consumption, compressing international spot availability. Shandong and Jiangsu provinces concentrate beneficiation capacity serving coastal container glass clusters.
Germany
Container glass producers in Bavaria and North Rhine-Westphalia specify sub-0.1% Fe2O3 feldspar grades for optical clarity in premium packaging. ECHA REACH registration requirements govern all imported concentrates, extending market access timelines for non-European suppliers. The Halle-Leipzig chemical corridor anchors beneficiation infrastructure for Central European ceramics supply.
United States
North Carolina's Spruce Pine pegmatite district provides captive high-purity deposits for domestic E-glass and technical ceramics manufacturers. EPA mining waste regulations shape permitting timelines for new extraction projects in Appalachian feldspar belts. Southeastern glass producers leverage rail connectivity to these deposits for furnace feed security.
Turkey
Aegean region mining output concentrates European ceramics supply, though single-region dependence creates vulnerability to export licensing disruptions. Currency volatility compresses margin stability for long-term contract pricing. Izmir and Manisa provinces host integrated beneficiation facilities serving Italian and Spanish tile manufacturers.
Italy
Sassuolo ceramic district tile producers negotiate three-year supply agreements with fixed volume floors and energy-indexed price adjustment clauses. EU Green Deal carbon accounting mandates documented emissions intensity from all raw material suppliers. Emilia-Romagna's whiteware manufacturers are consolidating supplier bases to reduce REACH compliance administration burden.
Soda Feldspar Market Competitive Landscape
Capital-heavy producers with captive mine assets compete with asset-light processors sourcing feedstock from third-party concentrates. The vendor base stratifies across three tiers: integrated miners with beneficiation infrastructure, regional processors leveraging logistics arbitrage, and specialty micronizers serving coatings applications. Dominant competitive moves include backward integration into low-iron ore reserves and long-term offtake contracting with glass manufacturers seeking furnace chemistry stability.
Among North American deposit holders, The Quartz Corporation exemplifies the captive-resource archetype through its Spruce Pine district positioning. Imerys Minerals represents European vertical integration from extraction through refined product delivery. Sibelco Nordic occupies the logistics-scale tier, competing across Baltic and North Sea distribution routes for bagged material flows.
| Leading Market Players |
|---|
| The Quartz Corporation |
| LB Minerals Ltd. |
| Adolf Gottfried Tonwerke GmbH |
| Esan |
| I-Minerals Inc. |
| Imerys Minerals |
| Quarzwerke GmbH |
| Micronized Group |
| Sibelco Nordic |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon accounting gates qualified supply and premium-tier pricing access, compelling soda feldspar suppliers to document emissions intensity and traceability before entering European procurement channels. Glass manufacturers in Germany and Italy now mandate verified low-carbon extraction credentials, bifurcating the market between compliant premium grades and excluded standard material.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates optical-grade low-iron sodium feldspar from standard ceramic body grades and unbeneficiated run-of-mine concentrates. Price differentiation rests on iron content certification below 0.1% Fe2O3 and REACH registration completeness under ECHA governance. Cost compression in standard grades is intensifying because wet grinding circuits consume substantial electricity when grid tariffs spike. Container glass producers show least price sensitivity for furnace-stable chemistry, while small ceramic tile manufacturers in Eastern Europe demonstrate highest sensitivity to bagged material delivered costs.
Supply Chain Analysis
Freight cost differentials between Aegean bulk vessel routes and Baltic bagged distribution determine competitive positioning for European ceramics supply. Geographic concentration centers on Turkey's Izmir-Manisa corridor, China's Shandong-Jiangsu beneficiation clusters, and North Carolina's Spruce Pine pegmatite district. Raw material flows draw from low-iron ore reserves, energy-intensive grinding media, and magnetic separation reagents. Single-region dependence on Turkish Aegean output creates vulnerability to export licensing disruptions and currency volatility. Distribution runs through long-term offtake contracts with fixed volume floors and energy-indexed price adjustment clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soda feldspar market operates as a regulatory compounder where EU Carbon Border Adjustment Mechanism implementation accelerates demand for documented low-emission concentrates. Compliance infrastructure investments now determine market access more than extraction scale.
For Market Incumbents: Hedge against nepheline syenite substitution by securing captive low-iron ore reserves in North Carolina or Turkey's Aegean region. Backward integration into sensor-based ore sorting technology preserves margin structure when electricity prices spike. E-glass alkali ratio specifications for wind turbine blade reinforcement offer contract stability against ceramic body commoditization.
For New Entrants and Emerging Players: Capture the underpenetrated electronics-grade feldspar segment for multilayer ceramic capacitors where purity thresholds exceed standard ceramic requirements. North American technical ceramics manufacturers seek supply chain proximity alternatives to Chinese imports. Qualification partnerships with German container glass producers bypass spot market price volatility.
For Investors and Strategic Acquirers: Roll-up economics work for regional processors with logistics scale across Baltic and North Sea routes because Mediterranean basin tile manufacturers are consolidating supplier bases to reduce REACH compliance administration burden. Five-to-ten year viability favors asset-light processors with established ECHA dossiers over greenfield mining projects facing EPA permitting timelines. The signal to watch is GB standards tightening in China redirecting domestic feldspar flows from export to internal consumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Iron Reserves | The Quartz Corporation's Spruce Pine positioning secures captive supply for E-glass specifications. |
| Long-term Supply Agreement | Italian Sassuolo tile manufacturers negotiate three-year contracts with energy-indexed price clauses. |
| Green Manufacturing Transition | Sensor-based ore sorting reduces tailings footprint and associated permitting liabilities under EPA rules. |
| Joint Venture | Beneficiation partnerships in Turkey's Manisa province serve consolidated European ceramics demand. |
| Capacity Expansion | Shandong province beneficiation capacity scales to absorb redirected export volumes under China's dual carbon goals. |
Research Methodology
Multiple input streams — primary interviews with glass furnace engineers, ceramics plant managers, and ECHA regulatory consultants; secondary validation through customs trade data, SEC mining company filings, and EU emissions registries; plus technical literature on beneficiation chemistry — were reconciled to construct segment-level demand estimates. Bottom-up volume builds from individual plant consumption rates triangulated against top-down trade flow analysis across the analysis window.
Data-stream reconciliation applied product type, application grade, end-user industry, and regional production hub segmentation dimensions throughout the forecast period. CAGRs were derived from slope analysis of historical consumption patterns projected against furnace capacity expansion schedules and GB standards implementation timelines. E-glass alkali ratio specifications and REACH registration completion rates served as industry-specific forecast anchors.
Export licensing disruptions in Turkey, electricity tariff volatility affecting wet grinding economics, and nepheline syenite substitution acceleration are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Coated Solar Control Glass Market
Glass
Technical Glass Market
Glass
Paper Glass Maker Market
Glass
Glass Grade Dolomite Market
Glass
Glass Lens Market
Glass
Solar Reflective Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
Glass Mason Jars Market
Glass
Sapphire Glass Market
Glass
Solar Control Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Optical Glass Market
Glass
UAE Silica Sand Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Advanced Glass Market
Glass
Decorative Glass Market