
 Antibacterial Glass Market | 2026-2036
Antibacterial Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Antibacterial Glass Market Intelligence
Asset-light leasing models for architectural glass installations is reconfiguring competitive entry barriers, allowing smaller fabricators to bid on hospital and transit projects without capital-intensive inventory. Saint-Gobain S.A. leverages its European flat-glass network to sustain project financing partnerships with healthcare developers. AGC Inc. anchors Japanese supply through captive float-glass capacity and direct OEM relationships with electronics manufacturers. Kastus Technologies Limited specializes in photocatalytic surface treatments, competing against ion-exchange incumbents with lower-temperature activation requirements.
Antibacterial glass incorporates silver, copper, or zinc ions into the surface matrix or applies photocatalytic titanium dioxide coatings to destroy microbial colonization upon light exposure; typical specifications require reduction rates exceeding 99% for E. coli and S. aureus within 24 hours under ISO 22196 test protocols. Coated glass commands premium positioning in electronic displays and laboratory equipment where optical clarity must pair with pathogen control. Silver ion technology dominates installed volume across commercial buildings and public transport, while photocatalytic formulations represent the fastest-expanding segment in food processing units seeking residue-free sanitation cycles.
EPA antimicrobial product registrations and EU REACH compliance on biocidal active substances shape which ion technologies gain market access in North America and Europe. Japan's METI enforces JIS Z 2801 standards that Ishizuka Glass and Nippon Sheet Glass already certify against, creating a regulatory moat for domestic exporters. Stakeholders must monitor evolving F-Gas Regulation restrictions on manufacturing process emissions and assess whether copper ion formulations can bypass silver supply concentration risks in antimicrobial glass procurement strategies.
Market Dynamics
Photocatalytic surface activation is collapsing the temperature differential between ion-exchange and coating-based manufacturing, compressing capital requirements for new entrants and fragmenting production geography.
Growth Catalysts
- EU MDR surface-contact mandates:Medical device reprocessing protocols now favor antimicrobial substrates in surgical suites and patient-contact surfaces, expanding specification requirements for coated glass in German and French hospital construction.
- Silver ion integration:Float-glass producers embed ionic silver during the tin bath phase, achieving 99% bacterial reduction without secondary coating lines and lowering unit economics for high-volume architectural orders.
- Japanese electronics OEM demand:Display manufacturers in Osaka and Tokyo prefectures specify antibacterial cover glass for touch panels in medical kiosks and public transit ticketing systems.
Market Restraints
- Silver supply concentration:Refining capacity clusters in Peru and Mexico create input price volatility that compresses margins for ion-exchange fabricators without long-term offtake agreements.
- F-Gas Regulation process restrictions:EU manufacturing emissions limits on fluorinated greenhouse gases constrain coating line expansion and extend permitting timelines for new production facilities.
- Photocatalytic UV-dependence:Titanium dioxide formulations require 365nm activation wavelengths that underperform in interior healthcare settings with LED-only lighting, limiting addressable application scope.
Strategic Opportunities
- Copper-zinc alloy substitution:Non-silver ion matrices bypass precious metal supply risks while meeting JIS Z 2801 standards, opening procurement diversification for Japanese and European healthcare developers.
- Food processing residue-free cycles:Photocatalytic self-cleaning glass eliminates chemical sanitizer residues in dairy and beverage packaging lines, aligning with EU EFSA clean-label manufacturing guidelines.
- Asset-light leasing penetration:Project financing partnerships allow regional fabricators to bid on transit infrastructure without inventory ownership, redistributing competitive access across secondary German and Italian markets.
Industry Challenges
- ISO 22196 certification timelines:Third-party laboratory testing for E. coli and S. aureus reduction rates extends 12-18 months, delaying product launch windows for reformulated coatings.
- Coating-substrate adhesion expertise:Thin-film photocatalytic layer durability requires specialized surface preparation protocols that concentrate technical talent at a handful of European and Japanese research institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibacterial Glass Market |
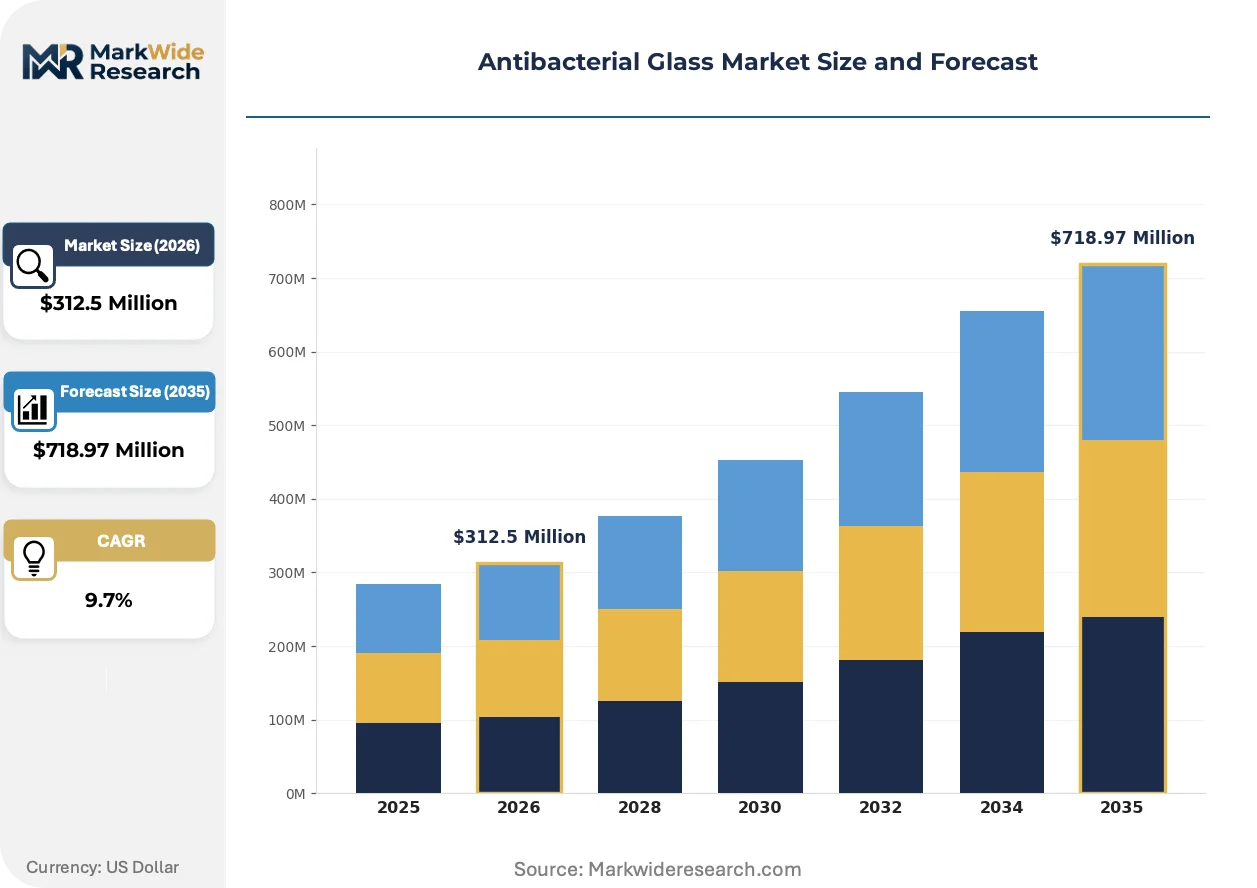
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $718.97 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminated Glass, Tempered Glass, Coated Glass, Float Glass, Heat-Strengthened Glass Technology: Silver Ion, Copper Ion, Zinc Oxide, Titanium Dioxide, Photocatalytic Application: Commercial Buildings, Public Transport, Food Processing Units, Electronic Displays, Laboratory Equipment End User: Architecture Firms, Transportation Providers, Food Safety Inspectors, Electronics Manufacturers, Scientific Research Labs |
| Companies Covered | Ishizuka Glass Co., Ltd., Saint-Gobain S.A., AGC Inc., Kastus Technologies Limited, Guardian Industries, Nippon Sheet Glass Co., Ltd., Corning Incorporated, Morley Glass & Glazing Ltd., Schott AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibacterial Glass Market Strategic Shifts & Innovations
Manufacturing process convergence is eroding the historical separation between commodity float-glass production and functional surface engineering, enabling mid-scale fabricators to compete on specification rather than volume.
Photocatalytic titanium dioxide doping is collapsing the capital barrier between architectural glass and antimicrobial specialty products. Food processing equipment manufacturers in the Netherlands and Denmark now specify self-activating surfaces for clean-in-place systems. This technology compression is enabling regional coating houses to bypass captive float-glass capacity and bid directly on industrial equipment contracts.
REACH biocidal active substance authorization timelines are extending market access friction for new ion-exchange formulations. Silver-based submissions face cumulative toxicity data requirements that favor incumbent registrants with decade-long dossier histories. European healthcare procurement teams are responding by dual-sourcing from established REACH-compliant suppliers while awaiting novel active substance approvals.
Specification-driven tendering is fragmenting traditional distributor relationships in hospital construction. German and Austrian healthcare developers now issue performance-based surface hygiene contracts that bundle glass supply with 10-year antimicrobial efficacy guarantees. This bundling compresses the role of independent distributors and shifts margin capture toward integrated coating-glass-fabrication entities with in-house ISO 22196 testing capabilities.
Antibacterial Glass Market Segmentation
Antibacterial glass procurement splits across substrate durability requirements, antimicrobial activation mechanisms, and regulatory compliance intensity. Specification divergence between architectural volume contracts and precision electronics orders creates distinct margin profiles within each segment axis.
Product Type:
Mature float-glass infrastructure dominates high-volume architectural supply while emerging specialty laminates capture premium healthcare specifications.
- Laminated Glass:Multi-layer construction with interleaved antimicrobial films withstands impact stress in hospital corridors and transit platforms. German healthcare developers specify laminated configurations for surgical suite partitions where breakage containment intersects with pathogen control mandates under EU MDR surface-contact protocols.
- Coated Glass:Thin-film surface treatments apply silver or photocatalytic layers post-manufacture, preserving optical clarity for electronic displays and laboratory viewports. Japanese electronics OEMs in Osaka prefecture drive coated glass procurement for medical kiosk touch panels requiring 99% bacterial reduction per JIS Z 2801 standards.
- Tempered Glass:Thermal strengthening creates surface compression layers that enhance durability in high-traffic public transport installations.
- Float Glass:Standard flat-glass substrate receives ionic silver integration during tin bath production for cost-efficient commercial building facades.
- Heat-Strengthened Glass:Intermediate thermal treatment delivers 2x mechanical resistance of annealed glass for mid-rise architectural applications.
Float glass retains volume leadership; coated glass holds the steepest expansion curve.
Technology:
Cost tier stratification separates precious metal ion exchange from lower-temperature photocatalytic alternatives.
- Silver Ion:Ionic silver embedded during float-glass production achieves 99% E. coli and S. aureus reduction without secondary coating capital. EU REACH biocidal active substance authorization timelines extend market access for new silver formulations, favoring incumbent registrants with decade-long dossier histories.
- Photocatalytic:Titanium dioxide coatings activate under 365nm UV exposure to generate reactive oxygen species for residue-free microbial destruction. Food processing equipment manufacturers in the Netherlands specify photocatalytic surfaces for clean-in-place systems eliminating chemical sanitizer residues under EFSA clean-label guidelines.
- Copper Ion:Non-precious metal alternative bypasses silver supply concentration risks while meeting equivalent ISO 22196 test protocols.
- Zinc Oxide:Broad-spectrum antimicrobial with lower material cost than silver, deployed in secondary commercial building specifications.
- Titanium Dioxide:Standalone photocatalytic formulation requiring UV activation, constrained by underperformance in LED-only interior healthcare settings.
Silver ion technology commands installed base dominance; photocatalytic formulations are expanding most quickly in food safety applications.
Application:
Customer type intensity varies from specification-driven tendering in healthcare to price-sensitive volume procurement in commercial construction.
- Commercial Buildings:High-volume facade and interior surface contracts prioritize unit economics over activation speed. Asset-light leasing models enable regional fabricators to bid on German hospital construction without capital-intensive inventory ownership.
- Electronic Displays:Precision optical requirements pair with antimicrobial functionality for medical kiosks and transit ticketing interfaces. Japanese display manufacturers anchor demand through direct OEM relationships with captive float-glass suppliers.
- Food Processing Units:Residue-free sanitation cycles drive photocatalytic specification for dairy and beverage packaging lines.
- Public Transport:High-touch surface durability requirements in rail and bus infrastructure favor ion-exchange tempered configurations.
- Laboratory Equipment:Optical clarity mandates restrict viable technologies to coated glass with minimal haze coefficients.
Commercial buildings retain volume leadership; food processing units hold the steepest expansion curve.
End User:
Supply concentration aligns with geography-specific regulatory moats and technical certification capabilities.
- Architecture Firms:German and Austrian healthcare developers issue performance-based surface hygiene contracts bundling glass supply with 10-year antimicrobial efficacy guarantees, compressing independent distributor roles.
- Electronics Manufacturers:Japanese OEMs in Tokyo prefecture specify antibacterial cover glass for touch panels, leveraging domestic supply chains anchored by Ishizuka Glass and Nippon Sheet Glass.
- Food Safety Inspectors:EU EFSA compliance verification drives specification toward photocatalytic self-cleaning surfaces in Netherlands and Denmark processing facilities.
- Transportation Providers:Transit infrastructure procurement favors ion-exchange technologies with proven durability under mechanical stress.
- Scientific Research Labs:ISO 22196 certification requirements concentrate supplier selection among entities with in-house testing capabilities.
Architecture firms retain volume leadership; food safety inspectors hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in antibacterial glass tilt toward net-importing markets in Western Europe and East Asia, where healthcare infrastructure investment outpaces domestic float-glass capacity. Manufacturing concentration in Japan and Germany creates supply corridors radiating into deficit markets across Southeast Asia and Southern Europe.
Germany
Healthcare facility construction in Bavaria and North Rhine-Westphalia is expanding procurement of coated architectural surfaces for surgical suites and patient-contact areas. EU MDR surface-contact mandates and F-Gas Regulation emissions limits tighten compliance requirements for imported glass while favoring established domestic fabricators with REACH-authorized biocidal dossiers. Stuttgart-based project developers now bundle glass supply with decade-long antimicrobial efficacy guarantees.
Japan
Electronics OEMs in Tokyo and Osaka prefectures specify antibacterial cover glass for medical kiosk touch panels and public transit ticketing systems. METI enforces JIS Z 2801 standards that domestic suppliers already certify against, creating regulatory moats for exporters from Ishizuka and Nippon Sheet Glass supply chains. Kanto region display manufacturers anchor demand through direct relationships with captive float-glass producers.
United States
EPA antimicrobial product registrations shape which ion technologies gain market access for healthcare and food processing applications. Silver ion formulations dominate commercial building specifications, though photocatalytic alternatives are penetrating dairy packaging lines seeking residue-free sanitation. Midwest and Southeast hospital construction favors ion-exchange tempered configurations for high-traffic corridor installations.
Netherlands
Food processing equipment manufacturers in the Randstad region specify photocatalytic self-cleaning surfaces for clean-in-place systems eliminating chemical sanitizer residues. EU EFSA clean-label manufacturing guidelines accelerate specification toward titanium dioxide coatings that activate under UV exposure. Eindhoven-area coating houses bypass captive float-glass capacity to bid directly on industrial equipment contracts.
China
Commercial building facade procurement in the Yangtze River Delta and Pearl River Delta prioritizes unit economics over activation speed, favoring silver ion-integrated float glass. GB standards and dual carbon goals constrain coating line expansion while extending permitting timelines for new production facilities. Shenzhen and Shanghai developers increasingly source from domestic fabricators with captive tin-bath ion-exchange capability.
Antibacterial Glass Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on activation chemistry and surface preparation protocols. Market structure consolidates around three to five vertically integrated float-glass producers with captive antimicrobial capacity, while regional coating houses fragment the specialty laminate segment. Strategic archetypes separate ion-exchange incumbents with tin-bath integration from photocatalytic specialists with lower-temperature process requirements. Dominant competitive moves include project financing partnerships with healthcare developers and technology licensing agreements that bypass capital-intensive capacity expansion.
Among Japanese supply chains, Ishizuka Glass Co., Ltd. and Nippon Sheet Glass Co., Ltd. occupy positions within the captive float-glass tier, leveraging domestic regulatory alignment to anchor electronics OEM relationships. Saint-Gobain S.A. exemplifies the European platform integrator archetype, sustaining project financing partnerships across German and French hospital construction markets. Kastus Technologies Limited represents the photocatalytic specialist segment, competing with ion-exchange incumbents through lower-temperature activation requirements that compress capital barriers for regional fabricators.
| Leading Market Players |
|---|
| Ishizuka Glass Co., Ltd. |
| Saint-Gobain S.A. |
| AGC Inc. |
| Kastus Technologies Limited |
| Guardian Industries |
| Nippon Sheet Glass Co., Ltd. |
| Corning Incorporated |
| Morley Glass & Glazing Ltd. |
| Schott AG |
| Others |
Cost & Logistics Intelligence
Stuttgart's healthcare construction cluster concentrates specification-driven procurement power, compressing margins for non-integrated coating houses while amplifying pricing leverage for captive float-glass producers with REACH-authorized biocidal dossiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade premiums for JIS Z 2801 and ISO 22196 compliance, while economy tiers compete on silver-ion unit economics for commercial facade volume. Cost compression in photocatalytic formulations is intensifying because lower-temperature activation requirements erode ion-exchange capital barriers. Electronics manufacturers in Osaka prefecture exhibit lowest price sensitivity due to optical clarity mandates; German transit infrastructure buyers demonstrate highest sensitivity to per-square-meter procurement costs.
Supply Chain Analysis
EU F-Gas Regulation restrictions on fluorinated greenhouse gas emissions constrain coating line technology transfers into non-EEA markets, fragmenting equipment sourcing geography. Manufacturing concentrates in Japan, Germany, and China, with raw material dependencies on Peruvian silver refining, titanium dioxide feedstock from Chinese sulfate-process plants, and German specialty chemical surface preparation agents. Single-source vulnerability runs through silver concentrate offtake agreements with Latin American refiners. Distribution runs through project-financing partnerships that bundle glass supply with decade-long efficacy guarantees, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photocatalytic UV-activation breakthroughs are collapsing capital barriers between commodity float-glass and antimicrobial specialty production, triggering rapid competitive fragmentation as regional coating houses bypass legacy ion-exchange infrastructure.
For Market Incumbents: Pre-empt copper-zinc alloy formulation patent filings to defend against silver supply concentration risks while METI accelerates JIS Z 2801 revision timelines. Deepen backward integration into captive tin-bath ion-exchange capacity at German and Japanese production hubs. Secure decade-long offtake agreements with Peruvian and Mexican refiners to lock input cost visibility.
For New Entrants and Emerging Players: Establish a beachhead in Netherlands food processing equipment specifications where EFSA clean-label mandates drive photocatalytic demand without legacy ion-exchange capital requirements. Target clean-in-place system retrofits for dairy and beverage packaging lines. Lead with residue-free sanitation cycle guarantees that bypass chemical sanitizer compatibility testing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating-glass-fabrication entities with in-house ISO 22196 testing capabilities and bundled efficacy guarantee contracts. Long-term viability hinges on regulatory moat sustainability across REACH biocidal active substance authorization timelines. Monitor F-Gas Regulation amendment proposals as the critical inflection signal for coating line expansion permissioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Float-Glass Capacity | Eliminates coating-substrate margin stacking for German healthcare developers bidding on EU MDR-mandated surgical suite projects. |
| Photocatalytic Formulation Patent Expansion | Secures lower-temperature process moats against ion-exchange incumbents in food processing applications under EFSA guidelines. |
| Project Financing Partnership Structuring | Enables asset-light regional fabricators to compete for transit infrastructure without inventory ownership burdens. |
| REACH Biocidal Active Substance Dossier Investment | Accelerates market access timelines for novel copper-zinc matrices while silver submissions face cumulative toxicity data requirements. |
| In-House ISO 22196 Certification Capability | Compresses 12-18 month third-party testing delays that currently stall product launch windows for reformulated coatings. |
Research Approach
Cross-validation between primary interviews with float-glass plant managers, healthcare procurement directors, coating R&D leads, and electronics OEM supply chain officers anchors the qualitative findings against secondary validation from EU ECHA biocidal active substance registration databases, Japanese METI industrial production surveys, SEC 10-K filings of listed glass manufacturers, and German hospital construction tender databases. Bottom-up demand modeling triangulates against top-down production capacity assessments across the analysis window.
Calibration incorporates segment-level growth differentials across substrate type, activation technology, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs derive from slope-consistent trajectory fitting against historical volume inflection points. Key inputs include silver spot price volatility bands, F-Gas Regulation permitting velocity assumptions, and JIS Z 2801 certification renewal frequency patterns.
Stress conditions across silver concentrate supply disruption, REACH authorization timeline extension, and photocatalytic UV-activation efficiency variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory stability and input cost trajectories. Material shifts in EU MDR surface-contact mandate enforcement intensity or METI standards revision scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Scratch Resistant Glass Market
Glass
Optical Glass Market
Glass
Coated Glass Market
Glass
Global Glassware Market
Glass
Solar Control Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
Glass Block Market
Glass
Foam Glass Market
Glass
Technical Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Glazing Gel Market
Glass
Low-E Glass Market
Glass
Solar Reflective Glass Market
Glass
Glass Vials Market
Glass
Glass Reactors Market