
 Global Printed Cartons Market | 2026-2036
Global Printed Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printed Cartons Market Foresight
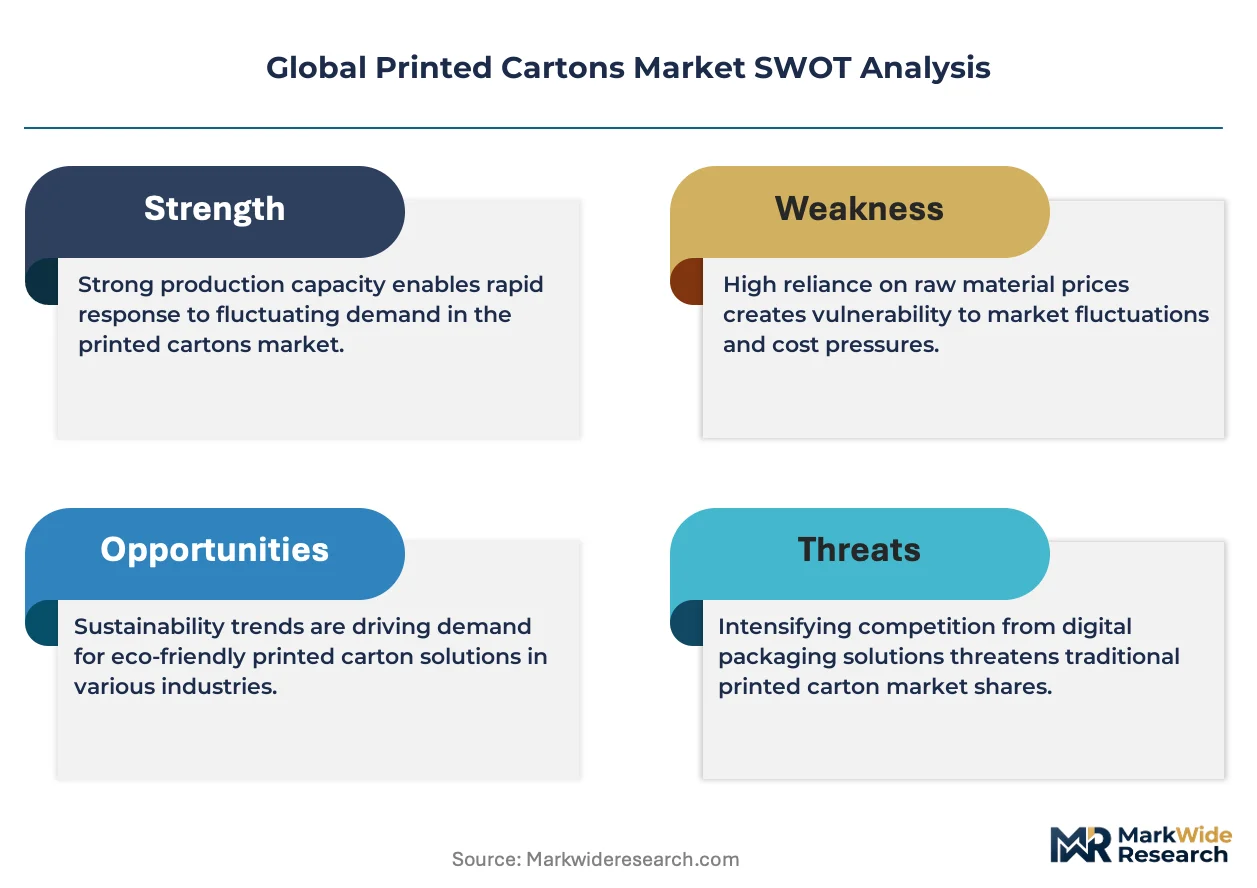
Prepress technician shortages across European and North American converting hubs is unwinding capacity expansion timelines for complex multi-color carton runs. WestRock Company leverages its integrated pulp-to-box network to sustain supply security for pharmaceutical and food-grade printed cartons across the southeastern United States. Huhtamaki Oyj anchors its competitive position through specialized barrier-coated carton technologies serving dairy and ready-meal segments in Northern Europe. Mondi PLC differentiates via lightweight kraft-based folding carton innovations that reduce material intensity without compromising print fidelity.
Printed cartons are paper-based packaging substrates manufactured from bleached or unbleached paperboard, typically ranging from 200 to 400 gsm, that receive surface graphics through offset lithography, flexography, or digital printing processes before die-cutting and creasing into three-dimensional containers. These structures serve primary functions of product protection, brand communication, tamper evidence, and regulatory information display across consumer goods supply chains. Folding cartons dominate volume throughput due to their flat-pack shipping efficiency and automated filling-line compatibility, while rigid boxes command premium margin pools in cosmetics and luxury gift applications. Digital printing represents the fastest-expanding technology segment, enabling short-run personalization and versioned graphics that lithography cannot economically match for sub-ten-thousand-unit orders.
FDA food contact notification requirements, EU Packaging and Packaging Waste Regulation, and China's GB standards for printing ink heavy-metal limits collectively shape material selection, ink chemistry, and recyclability claims accessible to carton producers serving regulated end-uses. REACH compliance on Substances of Very High Concern restricts certain optical brighteners and fluorinated treatments previously common in premium cosmetic cartons, redirecting formulation investments toward bio-based coating alternatives. Stakeholders must monitor evolving extended producer responsibility fee structures and substrate-specific recycling targets that will determine which material-printing technology combinations retain cost competitiveness across key export markets.
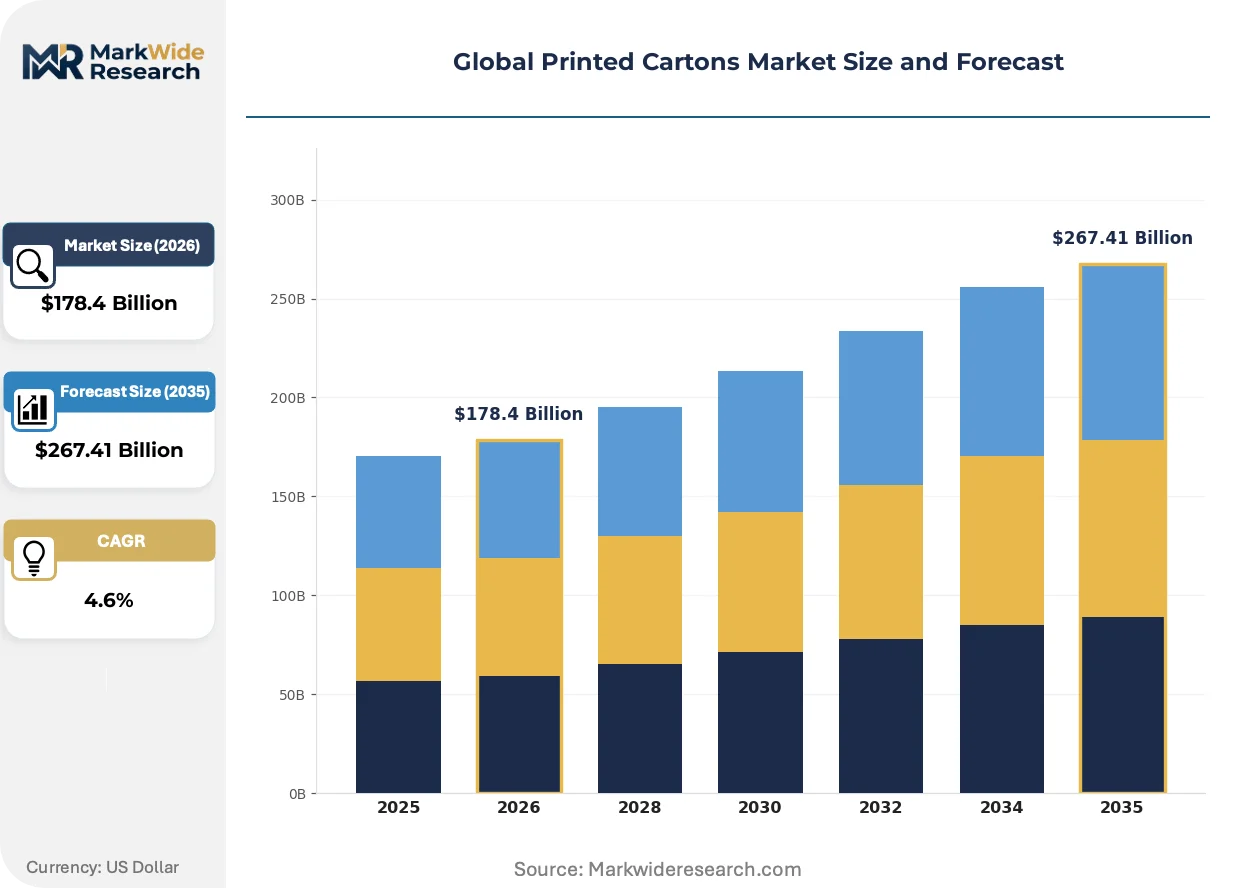
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive and FDA DSCSA are forcing carton converters to reengineer production lines for track-and-trace integration, compressing margins for unprepared suppliers while rewarding early compliance investments.
Growth Catalysts
- EU Falsified Medicines Directive:Mandatory serialization requirements across European pharmaceutical supply chains drive demand for authentication-ready carton substrates with integrated QR codes and tamper-evident features.
- India's pharmaceutical packaging expansion:Domestic API and formulation manufacturing growth concentrates demand for high-barrier carton formats serving temperature-sensitive drug exports to regulated markets.
- Digital printing adoption:Short-run personalization capabilities enable versioned graphics for clinical trial materials and regionalized pharmaceutical launches without plate-changeover delays.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft supply constraints from Scandinavian mill maintenance cycles create input cost unpredictability for food-grade and pharmaceutical carton board.
- Prepress technician scarcity:European and North American converting hubs face unwinding capacity timelines for complex multi-color runs due to skilled labor pipeline gaps.
- REACH Substances of Very High Concern restrictions:Banned optical brighteners and fluorinated treatments redirect formulation investments toward unproven bio-based coating alternatives with uncertain performance profiles.
Strategic Opportunities
- China's pharmaceutical export growth:Domestic innovators expanding into US and EU markets seek DSCSA- and FMD-compliant carton suppliers with established serialization partnerships.
- Extended producer responsibility fee structures:EU Packaging and Packaging Waste Regulation revisions create first-mover advantages for converters with verified fiber sourcing and closed-loop recycling certifications.
- Barrier-coated dairy and ready-meal segments:Oxygen and moisture barrier technologies converge with fiber-based substrates to displace plastic trays in Northern European retail channels.
Industry Challenges
- Prepress skill gap:Color management and trapping expertise for pharmaceutical serialization graphics remains concentrated among aging technician cohorts in German and Italian converting clusters.
- Multi-standard compliance capex:Simultaneous FDA food contact notification, EU REACH, and China GB heavy-metal limit certifications require redundant testing protocols and specialized ink inventory segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printed Cartons Market |
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $267.41 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Rigid Boxes, Corrugated Boxes, Paperboard Containers End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Material: Carton Board, Kraft Paper, Coated Paper, Recycled Paper Printing Technology: Flexography, Digital Printing, Lithography, Gravure |
| Companies Covered | Mayr-Melnhof Karton AG, Huhtamaki Oyj, WestRock Company, Mondi PLC, Amcor PLC, Graphic Packaging Holding Company, Smurfit Kappa Group, Rengo Co., Ltd., International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printed Cartons Market Shifts & Advancements
Digital printing architectures are fragmenting traditional lithography dominance while regulatory serialization mandates and sustainability-driven material substitutions reshape converter investment priorities across pharmaceutical and food contact applications.
Digital printing is bifurcating the carton production landscape between high-volume lithographic runs and sub-ten-thousand-unit personalized orders. Pharmaceutical contract packagers and clinical trial material suppliers adopt inkjet and toner-based systems for versioned patient information leaflets and region-specific regulatory text. This technology split compresses minimum efficient scale thresholds for specialized converters while creating margin pressure on mid-volume generalists caught between competing process economics.
REACH compliance on Substances of Very High Concern is eliminating legacy optical brighteners and perfluorinated grease barriers from premium cosmetic and food cartons. ECHA enforcement timelines force converters toward bio-based coating alternatives including polysaccharide and protein-derived barrier layers with unproven shelf-life performance. Northern European cosmetic brands and dairy processors face the steepest reformulation curves as existing inventory exhausts and replacement substrates undergo extended migration testing.
Brand-owners in regulated pharmaceutical and food sectors now mandate chain-of-custody documentation and carbon footprint verification as standard tender requirements. Large multinational drug manufacturers consolidate supplier panels to converters with integrated pulp-to-box networks and third-certified fiber sourcing. This procurement consolidation concentrates volume among vertically integrated players while excluding regional specialists lacking capital for certification infrastructure, with the strictest qualification protocols visible in German and Swiss pharmaceutical packaging tenders.
Global Printed Cartons Market Segmentation
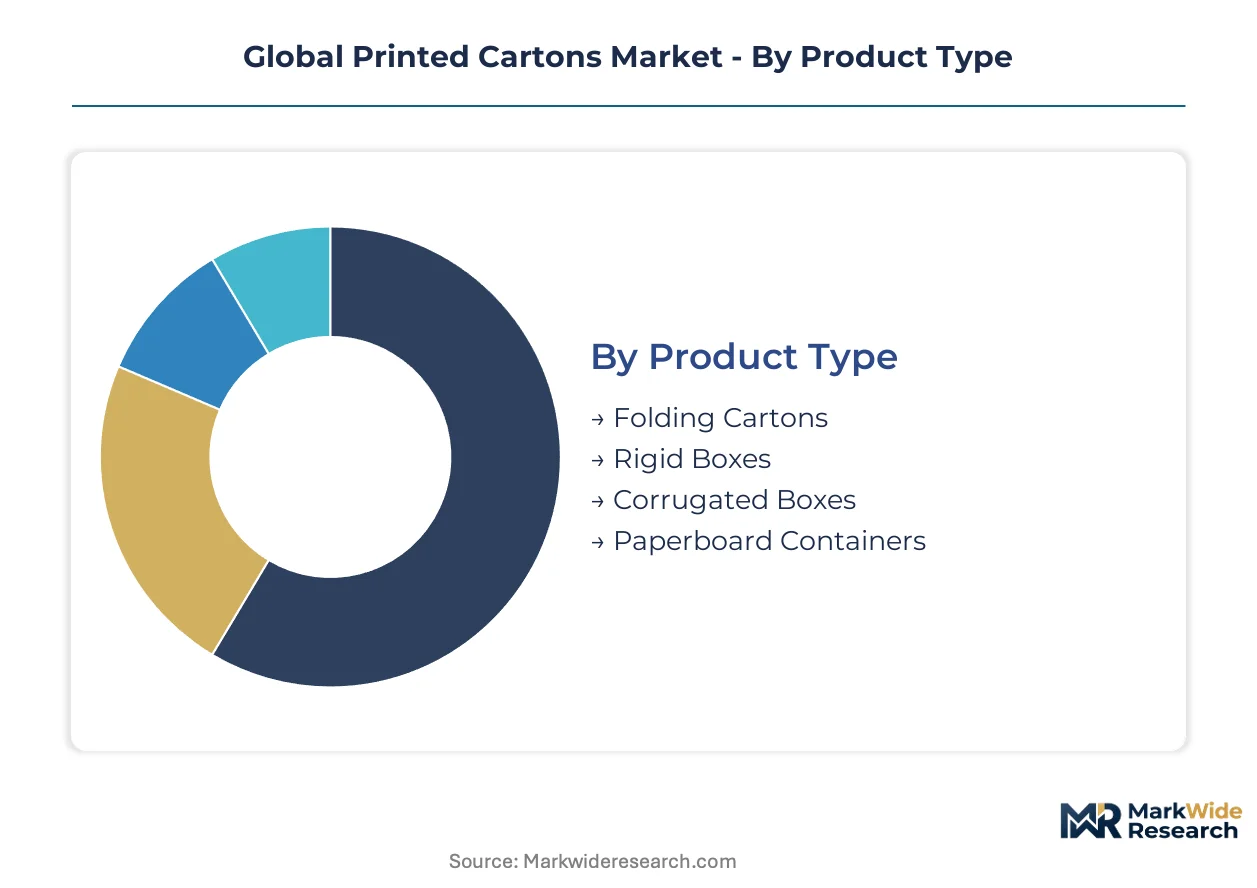
Regulatory fragmentation across FDA, EMA, and China's NMPA jurisdictions forces carton converters to maintain parallel substrate inventories and ink chemistries. Segmentation strategy determines which material-printing combinations qualify for pharmaceutical serialization versus food contact applications.
Product Type:
FDA DSCSA and EU Falsified Medicines Directive requirements diverge sharply across structural formats, with serialization-ready designs commanding premium positioning.
- Folding Cartons:Flat-pack paperboard structures between 250-400 gsm with pre-creased fold lines enable automated erecting and filling at pharmaceutical packaging lines. Demand concentrates in German and Swiss contract manufacturing facilities serving EU serialized drug distribution, where tamper-evident flap designs integrate with track-and-trace infrastructure.
- Rigid Boxes:Thick-set-up boards wrapped with printed outer papers provide structural integrity for high-value cosmetics and luxury goods. Japanese and South Korean beauty brands drive specification tightening around magnetic closure precision and surface finish consistency.
- Corrugated Boxes:Fluted medium sandwiched between linerboards supports heavier loads in secondary pharmaceutical distribution and temperature-controlled food logistics.
- Paperboard Containers:Single-wall formed structures serve ready-meal and dairy applications requiring direct food contact compliance under EU 10/2011 migration limits.
Folding cartons handle the majority of throughput; rigid boxes are expanding most quickly in premium personal care applications.
End User:
Customer procurement consolidation reflects diverging compliance burdens, with pharmaceutical tenders demanding integrated serialization partnerships that food brands rarely require.
- Food & Beverage:Dairy processors and ready-meal manufacturers in Northern Europe specify barrier-coated carton board to displace plastic trays under extended producer responsibility fee structures. Swedish and Finnish retailers now mandate carbon footprint verification at the SKU level.
- Personal Care:Cosmetic houses face REACH Substances of Very High Concern deadlines eliminating optical brighteners from premium packaging. French and Italian luxury brands accelerate reformulation timelines ahead of ECHA enforcement.
- Pharmaceuticals:Temperature-sensitive biologics and oncology formulations require high-barrier substrates with integrated authentication features. Indian API exporters concentrate demand for DSCSA-compliant cartons serving US distribution.
- Electronics:Anti-static coatings and moisture barrier layers protect semiconductor components and consumer devices through multi-modal shipping.
Pharmaceuticals generates the steepest margin premiums; food and beverage delivers the largest absolute volume base.
Material:
Raw material sourcing certification now gates participation in multinational pharmaceutical and food supply chains, with fiber provenance documentation mandatory in German and Swiss tenders.
- Carton Board:Bleached chemical pulp substrates provide the print fidelity and dimensional stability required for pharmaceutical serialization graphics. Scandinavian mill maintenance cycles create periodic supply tightness for northern bleached softwood kraft grades.
- Kraft Paper:Unbleached virgin fiber offers tear resistance and natural aesthetic positioning for organic food and sustainable personal care lines.
- Coated Paper:Mineral or synthetic surface treatments enhance ink holdout and gloss uniformity for high-end cosmetic applications.
- Recycled Paper:Post-consumer fiber content satisfies EU Packaging and Packaging Waste Regulation targets but faces heavy-metal limit constraints under China's GB standards for food contact.
Carton board dominates pharmaceutical and food-grade specifications; recycled paper is gaining share fastest in non-food consumer goods segments.
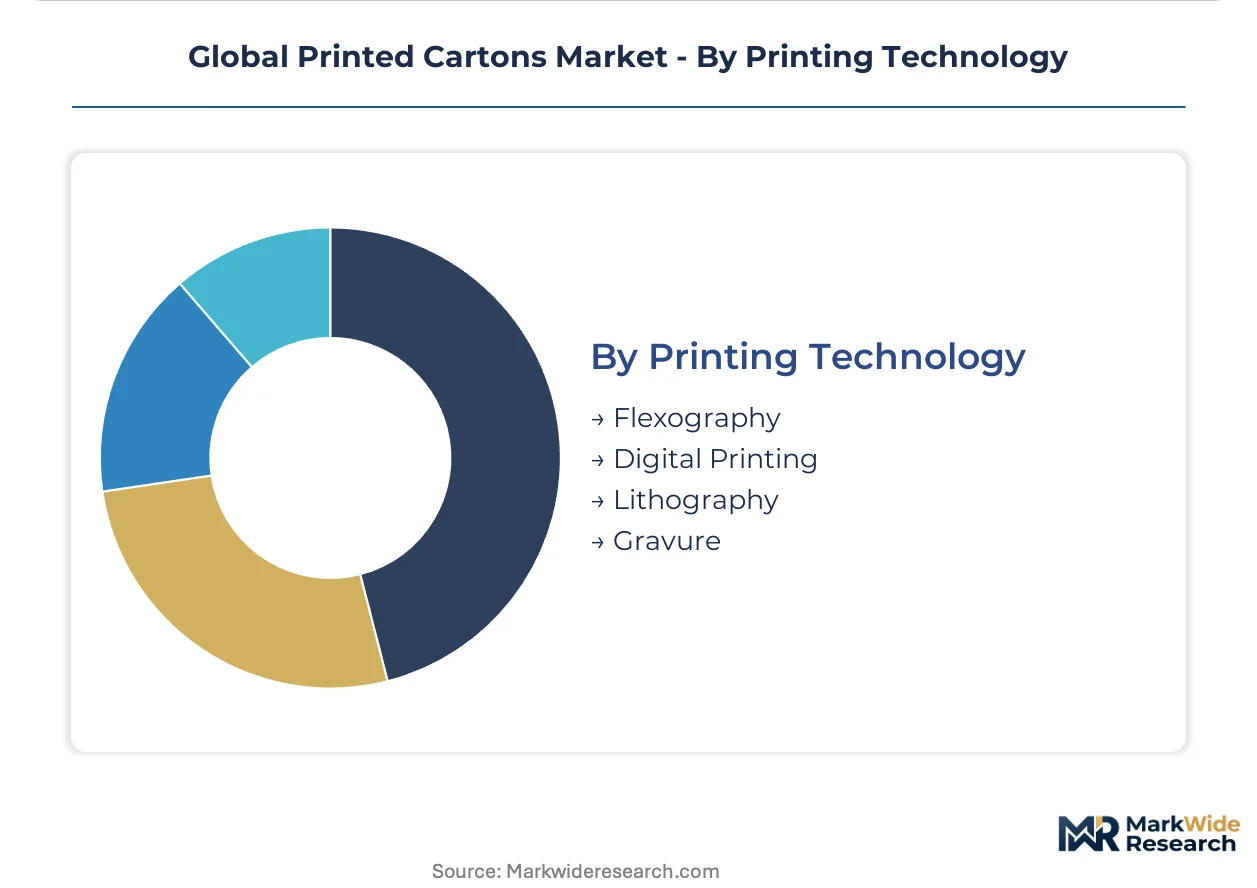
Printing Technology:
Capital deployment splits between high-volume lithographic infrastructure and agile digital systems, with prepress technician scarcity constraining complex multi-color execution.
- Flexography:Rotary relief printing with photopolymer plates delivers cost efficiency for long-run food and beverage cartons at 10,000+ unit scale. Water-based ink formulations dominate dairy applications to meet EU food contact requirements.
- Digital Printing:Inkjet and electrophotographic systems eliminate plate costs and enable versioned graphics for clinical trial materials and regionalized pharmaceutical launches. Contract packagers in New Jersey and North Carolina deploy these systems for DSCSA-compliant short runs.
- Lithography:Planographic offset remains the default for premium cosmetic and pharmaceutical cartons demanding precise color matching and fine-screen halftone reproduction.
- Gravure:Intaglio cylinder engraving produces consistent ink density for high-volume tobacco and confectionery packaging with metallic decorative effects.
Lithography retains the largest installed base; digital printing shows the steepest expansion trajectory as pharmaceutical serialization drives shorter run lengths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates anchor North American demand, while EU Falsified Medicines Directive enforcement and Asia-Pacific pharmaceutical export growth reshape converter investment priorities across three continents.
United States
DSCSA compliance deadlines drive pharmaceutical contract packagers toward track-and-trace-ready carton suppliers. FDA food contact notification requirements filter substrate selection for dairy and ready-meal applications. New Jersey and North Carolina converting clusters concentrate digital printing capacity for clinical trial materials and short-run serialized orders.
Germany
EU Falsified Medicines Directive enforcement compresses margins for unprepared converters while rewarding early serialization investments. ECHA REACH restrictions on optical brighteners redirect cosmetic carton formulations toward bio-based alternatives. The Rhine-Ruhr and Baden-Württemberg industrial corridors host specialized pharmaceutical packaging facilities serving continental distribution networks.
China
Domestic API and formulation manufacturing expansion concentrates demand for high-barrier carton formats with integrated authentication features. NMPA alignment with international serialization standards accelerates as domestic innovators target US and EU export markets. The Yangtze River Delta pharmaceutical packaging sector scales DSCSA- and FMD-compliant production for temperature-sensitive drug exports.
India
API and generic formulation manufacturing growth drives specification tightening for export-grade pharmaceutical cartons. CDSCO harmonization with FDA and EMA standards shapes converter qualification protocols for regulated market access. Gujarat and Maharashtra packaging corridors expand high-barrier substrate capacity serving European and North American drug distribution.
Switzerland
Swissmedic serialization requirements and premium cosmetic brand demand sustain margin premiums for specialized converters. Carbon footprint verification and chain-of-custody documentation now gate participation in multinational pharmaceutical tenders. The Basel-Zürich corridor concentrates precision folding carton capacity for biologics and oncology formulations requiring temperature-stable packaging.
Global Printed Cartons Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp-to-box networks commanding procurement consolidation from multinational pharmaceutical manufacturers. The middle tier fragments across regional converters lacking capital for certification infrastructure. Three archetypes dominate: vertically integrated fiber-to-carton operators, specialized barrier-coating technologists, and agile digital-first contract packagers. Competitive moves center on serialization partnership formation and verified fiber sourcing certification.
Among integrated operators, WestRock Company and Mondi PLC exemplify the pulp-to-box archetype with captive fiber supply and multi-continent converting footprints. Huhtamaki Oyj occupies a specialist position within barrier-coated dairy and ready-meal segments. These three entities represent divergent strategic paths: network scale, substrate innovation, and application-specific technology leadership.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton AG |
| Huhtamaki Oyj |
| WestRock Company |
| Mondi PLC |
| Amcor PLC |
| Graphic Packaging Holding Company |
| Smurfit Kappa Group |
| Rengo Co., Ltd. |
| International Paper Company |
| Others |
Supply & Pricing Matrix
FDA DSCSA and EU Falsified Medicines Directive compliance gates both supplier qualification and price differentiation simultaneously, separating serialization-ready converters from commodity carton producers. Certification investments create tiered pricing power for track-and-trace-capable suppliers while squeezing margins among generalists lacking authentication infrastructure.
Pricing Analysis
European folding cartons for pharmaceutical serialization command substantial premiums over standard food-grade equivalents in North American markets. Three-tier pricing structure across premium authentication-enabled, standard compliant, and economy non-serialized levels reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because pulp price volatility and prepress technician scarcity squeeze converter margins. Contract pharmaceutical packagers show least price sensitivity due to regulatory non-negotiability, while mass-market food brands drive hardest bargain terms.
Supply Chain Analysis
Scandinavian mill maintenance cycles on northern bleached softwood kraft create periodic chokepoints for pharmaceutical-grade carton board supply. Geographic supply concentrates in Sweden, Finland, and Germany for virgin fiber substrates, while China and India expand coated paperboard capacity for export markets. Raw material dependencies span bleached chemical pulp, barrier coating polymers, and food-contact-approved ink systems. Single-source vulnerability runs through concentrated Scandinavian pulp production. Distribution runs through regional converting hubs serving pharmaceutical contract packagers and dairy processors with just-in-time replenishment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible plastic packaging and fiber-based alternative substrates threaten printed carton incumbents across ready-meal and personal care segments, demanding active substitution defense through barrier technology investment and sustainability certification.
For Market Incumbents: Fortify serialization partnership depth with pharmaceutical contract packagers in New Jersey and North Carolina clusters to lock out regional competitors. Secure backward integration into bleached kraft pulp supply through long-term offtake agreements with Scandinavian mills, neutralizing input cost volatility that erodes margin stability against flexible packaging substitutes.
For New Entrants and Emerging Players: Differentiate on digital printing agility for clinical trial materials and regionalized pharmaceutical launches below ten-thousand-unit thresholds where lithography fails economically. Target India's Gujarat and Maharashtra packaging corridors where API export growth concentrates demand for DSCSA-compliant cartons among mid-tier converters lacking authentication infrastructure.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation revisions reshape the acquisition landscape toward converters with verified fiber sourcing and closed-loop recycling certifications. Five-to-ten-year viability favors integrated pulp-to-box operators over standalone converters facing procurement consolidation. Watch ECHA enforcement timelines on Substances of Very High Concern as inflection indicator for bio-based coating substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Partnership Formation | Track-and-trace integration with FDA DSCSA-compliant pharmaceutical packagers secures premium contract access. |
| Barrier Coating Technology Investment | Oxygen and moisture barriers displace plastic trays in Swedish and Finnish dairy retail channels. |
| Verified Fiber Sourcing Certification | Chain-of-custody documentation gates participation in German and Swiss multinational pharmaceutical tenders. |
| Digital Printing Capacity Expansion | Short-run personalization capabilities capture clinical trial material demand from New Jersey contract packagers. |
| Bio-Based Coating Reformulation | Polysaccharide and protein-derived alternatives replace banned optical brighteners under ECHA REACH enforcement. |
Research Methodology
Desk research of FDA DSCSA guidance documents, EU Falsified Medicines Directive implementation reports, and ECHA REACH substance restriction databases preceded structured interviews with pharmaceutical packaging procurement managers, carton converting plant engineers, prepress technicians, and barrier coating R&D directors. Secondary validation drew from customs trade data on paperboard imports, SEC filings of integrated packaging companies, and Scandinavian pulp mill production disclosures. Bottom-up volume estimates from converter capacity utilization triangulated against top-down pharmaceutical shipment value allocations across the analysis window.
Variance decomposition across product type, end-use sector, material grade, and printing technology dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro pharmaceutical packaging expenditure trends. Forecast inputs incorporated serialization mandate compliance timelines, pulp price cycle assumptions, and digital printing adoption curves specific to pharmaceutical contract packaging.
Material uncertainties — pulp supply disruption from Scandinavian mill maintenance, ECHA enforcement acceleration on optical brighteners, and NMPA serialization alignment pace — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory implementation consistency and substitution elasticity between fiber-based and flexible plastic formats. Practitioners should keep alternative scenarios live as extended producer responsibility fee structures and substrate-specific recycling targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pizza Cartons Market
Cartons
Folding Carton in Healthcare Market
Cartons
Mono Carton Market
Cartons
Japan Corrugated Boxes Market
Cartons
Fully Enclosed Cartons Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Global Cartonboard Market
Cartons
Carton Liners Market
Cartons
XXL Packaging Market
Cartons
Metallized PET Cartons Market
Cartons
Liquid Packaging Cartons Market
Cartons
Cardboard Crates Market
Cartons
Carton Sealer Machine Market
Cartons
Tablet Cartons Market
Cartons
Indonesia Folding Carton Packaging Market