
 Microwaveable Carton Market | 2026-2036
Microwaveable Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Microwaveable Carton Market Analytics
The EU Packaging and Packaging Waste Regulation is rebalancing the cost-of-entry calculus for converters serving European food manufacturers. Huhtamaki Oyj leverages its broad coating technology portfolio to sustain compliance leadership across multiple member states. Mondi Group anchors its competitive position through integrated paperboard sourcing and in-house barrier development. Sealed Air Corporation differentiates via advanced seal integrity systems that extend shelf stability for ready meal applications.
Microwaveable cartons are fiber-based containers engineered with susceptor layers or barrier coatings to withstand microwave energy distribution while maintaining food temperature and moisture profiles, typically constructed from bleached or unbleached paperboard with polyethylene or PET laminate interfaces. Their primary commercial purpose is to enable safe, single-step heating of pre-packaged foods without container transfer. Single-Serve formats dominate volume due to portion-control trends and solo dining patterns in urban markets. Composites lead material value pools because multi-layer barrier engineering commands premium pricing against commodity paperboard. Ready Meals anchors application demand as frozen and chilled prepared food producers shift from plastic trays to fiber alternatives.
The US FDA maintains specific migration limits for substances in microwave food-contact materials under 21 CFR 176.170, while the EU EFSA evaluates coating safety through its food contact materials panel. Japan's Ministry of Health, Labour and Welfare enforces positive list requirements for synthetic resins used in food containers that directly affect import carton specifications. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York alongside EU harmonized standards to determine regional production footprints and certification investments.
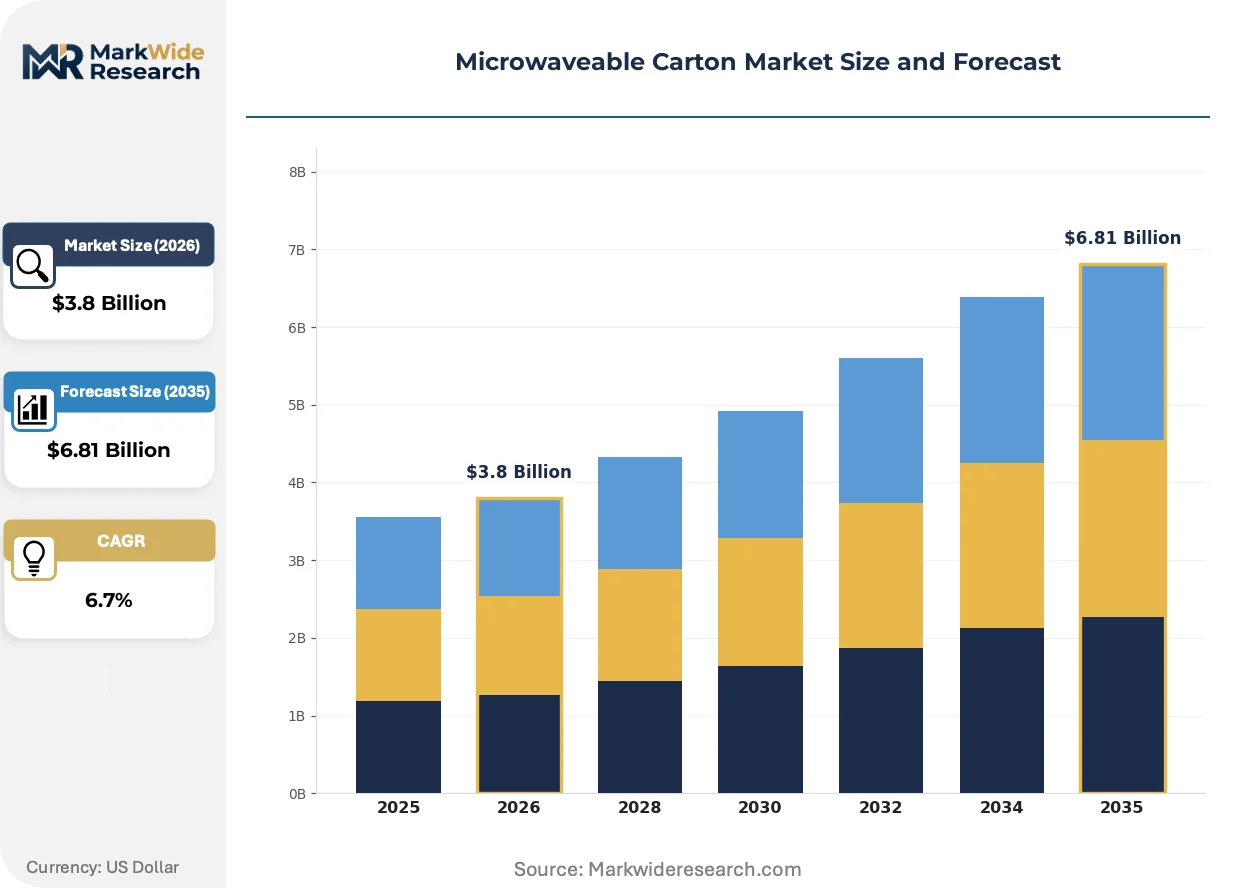
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins while simultaneously accelerating fiber-format adoption among ready meal producers seeking plastic-alternative compliance pathways.
Growth Catalysts
- Single-Serve format expansion:Solo dining patterns in urban Germany and Japan are pulling portion-controlled microwaveable cartons into frozen and chilled ready meal lines.
- REACH-compliant barrier coatings:European converters deploying polyethylene-free susceptor layers are capturing shelf space from legacy plastic tray suppliers under tightened migration limits.
- Japan's positive list enforcement:Synthetic resin specifications for food-contact materials are filtering import carton quality tiers, advantaging certified regional producers.
Market Restraints
- Pulp price volatility:Bleached kraft paperboard input costs swing with Nordic supply disruptions, compressing converter margins on fixed-price annual contracts.
- Barrier coating technical ceiling:Current polyethylene and PET laminates face performance gaps against retort-grade plastic for high-moisture extended-shelf-life applications.
- California EPR law friction:State-level extended producer responsibility compliance adds certification overhead distinct from federal FDA migration requirements.
Strategic Opportunities
- India convenience food penetration:Organized retail expansion in Mumbai and Delhi is creating first-mover openings for microwaveable carton formats in frozen snack segments.
- CSRD-aligned packaging disclosure:Corporate sustainability reporting mandates are incentivizing ready meal brands to specify fiber-based containers with traceable supply chains.
- Smart susceptor integration:Convergence of RFID temperature tracking with microwave-responsive coatings enables premium positioning in healthcare meal delivery channels.
Industry Challenges
- Multi-layer adhesion expertise gap:Converters lack sufficient polymer chemists to optimize susceptor-to-paperboard bonding under accelerated production timelines.
- Dual certification complexity:Simultaneous FDA 21 CFR 176.170 and EFSA food contact panel approvals extend product launch cycles by 8-14 months.
- Legacy sealing equipment incompatibility:Fiber-based carton formats require heat-seal retrofit investments incompatible with existing plastic tray line configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwaveable Carton Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve, Family Size, Multi-Packs, Specialty Shapes Material: Paperboard, Plastic, Composites, Coatings End User: Food Manufacturers, Retailers, Restaurants, Catering Services Application: Ready Meals, Snacks, Beverages, Frozen Foods |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global Inc., Huhtamaki Oyj, Mondi Group, Sonoco Products Company, Graphic Packaging International, WestRock Company, Coveris Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwaveable Carton Market Evolving Landscape
Barrier coating chemistry and susceptor layer engineering are converging to redefine performance benchmarks for microwave food contact materials across frozen and chilled applications.
Polyethylene-free barrier coatings are electrifying the technical frontier for microwaveable cartons. These water-based or bio-derived sealant layers eliminate fossil-derived laminates while maintaining moisture retention during microwave energy distribution. Frozen vegetable and rice bowl producers in Germany and the United States are piloting these formats at commercial scale. The technology is electrifying competitive positioning by collapsing the sustainability premium previously commanded by plastic-alternative packaging.
REACH substance restrictions are tightening the allowable chemical space for food-contact coatings across European manufacturing. The regulation's evolving candidate list is forcing converters to reformulate susceptor adhesives and barrier polymers ahead of sunset dates. Ready meal exporters serving EU retail chains are responding by dual-sourcing compliant coating supply from certified Nordic and Benelux chemical suppliers.
Direct-to-retailer procurement consolidation is compressing distributor intermediaries in North American supply chains. Large frozen food brands are negotiating master supply agreements directly with integrated paperboard converters, bypassing traditional packaging distributors. The shift is most pronounced in the United States, where Walmart and Kroger private-label ready meal lines are consolidating carton sourcing under single-supplier frameworks with dedicated capacity allocation.
Microwaveable Carton Market Segmentation
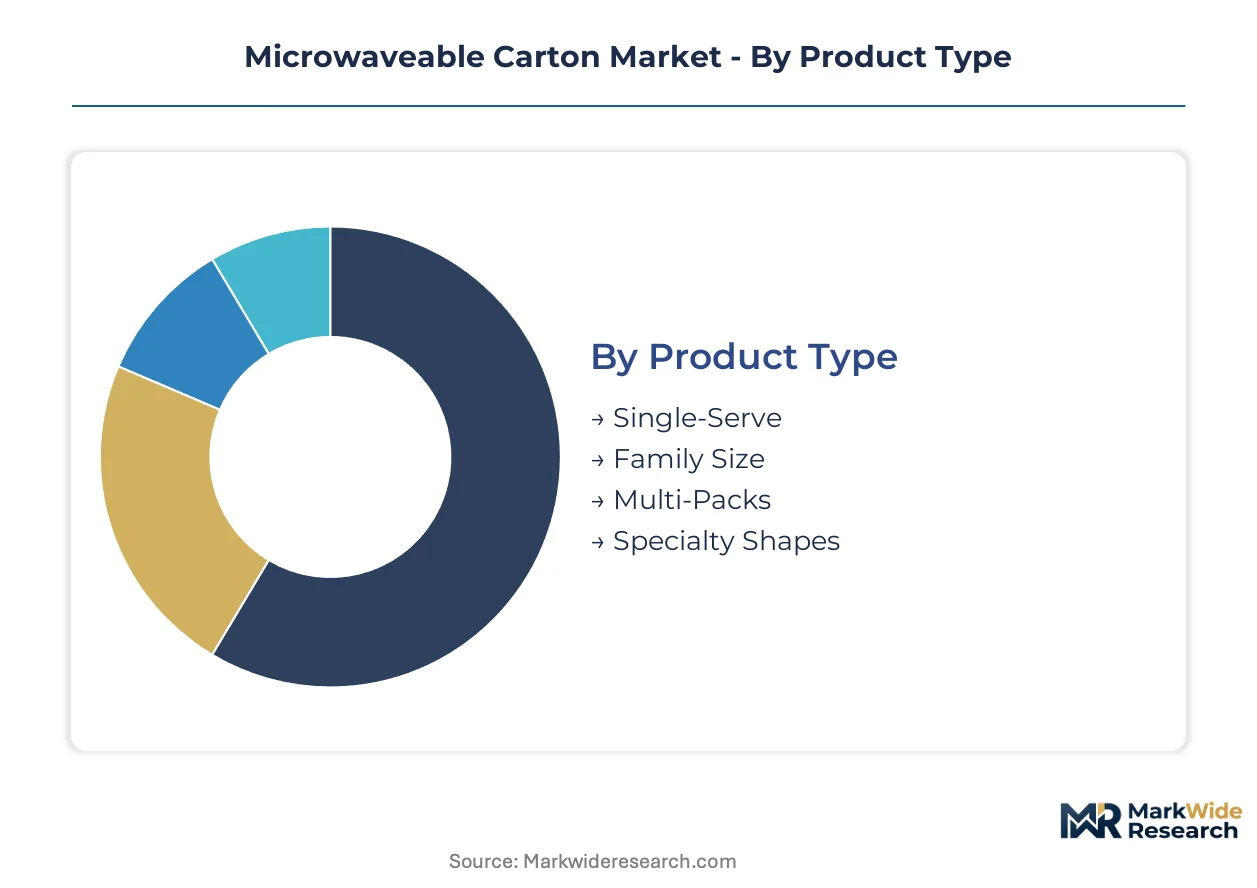
Microwaveable carton segmentation reveals how format engineering, barrier chemistry, and channel specifications fragment addressable demand across frozen and chilled food supply chains. Understanding these splits enables converters to align coating R&D investments with the precise thermal and moisture requirements of each use case.
Product Type:
Single-Serve formats command volume leadership through portion-control alignment with solo dining patterns, while Family Size and Multi-Packs capture premium positioning through structural reinforcement requirements.
- Single-Serve:Individual-portion cartons constructed from 300-400 gsm paperboard with integrated susceptor patches for uniform heating. Urban Germany and Japan pull these formats into frozen ready meal lines as convenience retailers expand chilled private-label offerings. Solo household penetration in Tokyo and Berlin accelerates format standardization.
- Family Size:Multi-portion containers requiring reinforced corner structures and expanded barrier surface area to prevent moisture loss across longer heating cycles. US frozen dinner brands specify these for value-positioned product tiers targeting suburban household replenishment trips.
- Multi-Packs:Retail-ready outer cartons containing 4-6 individually wrapped single-serve units with tear-apart perforations.
- Specialty Shapes:Non-rectangular formats including bowl, tray, and wedge configurations for differentiated shelf presence.
Today's leader: Single-Serve. Tomorrow's challenger: Family Size.
Material:
Composites dominate value capture through multi-layer barrier engineering, while uncoated paperboard serves cost-sensitive applications with limited moisture exposure.
- Paperboard:Bleached or unbleached kraft substrates ranging from 250-500 gsm providing structural rigidity. Nordic pulp supply disruptions periodically compress converter margins on fixed-price annual contracts for standard-grade cartons.
- Plastic:Polypropylene and PET tray alternatives with microwave-safe additives for high-moisture extended-shelf-life applications where fiber barriers face technical ceilings.
- Composites:Multi-layer constructions combining paperboard substrates with aluminum susceptor films and polymer sealant layers. REACH-compliant polyethylene-free variants are climbing fastest as European ready meal producers seek plastic-alternative compliance pathways under tightened migration limits.
- Coatings:Water-based and bio-derived barrier sealants applied via extrusion or lamination processes.
Composites anchor current revenue. Polyethylene-free coating variants are expanding most quickly.
End User:
Food Manufacturers concentrate procurement scale, while Retailers and Restaurants fragment demand through format customization requirements.
- Food Manufacturers:Frozen and chilled ready meal producers specifying carton formats at production-line scale. Direct-to-manufacturer procurement consolidation in the United States bypasses traditional packaging distributors as Walmart and Kroger private-label lines consolidate sourcing under single-supplier frameworks.
- Retailers:Private-label buyers requiring format differentiation for shelf positioning. German and US convenience chains specify customized printing and opening features for chilled meal sections.
- Restaurants:Foodservice operators sourcing take-home and delivery-optimized microwaveable containers.
- Catering Services:Institutional meal providers with batch-heating requirements and portion-control specifications.
Food Manufacturers drive volume scale. Retailers are gaining procurement leverage fastest.
Application:
Ready Meals anchor technology investment through barrier performance demands, while Snacks and Beverages extend format adoption into adjacent convenience categories.
- Ready Meals:Frozen and chilled prepared foods requiring moisture retention, fat barrier, and susceptor-mediated browning. EU Packaging and Packaging Waste Regulation acceleration of fiber-format adoption positions microwaveable cartons to displace legacy plastic trays across European retail chains.
- Snacks:Popcorn, savory bites, and sweet goods with lighter barrier requirements. Indian organized retail expansion in Mumbai and Delhi creates first-mover openings for carton formats in frozen snack segments.
- Beverages:Hot drink cups and soup containers with liquid-tight seal requirements.
- Frozen Foods:Vegetable, rice, and protein formats with extended cold-chain stability needs.
Ready Meals command R&D priority. Snacks represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microwaveable carton manufacturing originated in post-war Japan and spread through German and US food packaging industries during the 1970s frozen food boom. Today production clusters concentrate where pulp supply, coating chemistry expertise, and ready meal consumption intersect.
United States
Frozen ready meal producers in Chicago and Omaha drive carton specification at scale. FDA 21 CFR 176.170 migration limits govern coating compliance, while California's extended producer responsibility law adds state-level certification overhead. Walmart and Kroger private-label consolidation in Bentonville and Cincinnati reshapes procurement toward direct manufacturer relationships.
Germany
Solo household penetration in Berlin and Munich accelerates single-serve format standardization across chilled meal lines. EU Packaging and Packaging Waste Regulation tightens material compliance timelines, advantaging converters with REACH-certified polyethylene-free barrier coatings. The Ruhr industrial corridor hosts integrated paperboard-susceptor manufacturing complexes serving pan-European retail chains.
Japan
Tokyo and Osaka convenience retailers expand chilled private-label offerings requiring portion-controlled microwaveable formats. METI and the Ministry of Health, Labour and Welfare enforce positive list requirements for synthetic resins in food-contact materials, filtering import carton quality tiers. Domestic producers in Kanto and Kansai regions leverage certification advantages for healthcare and senior meal delivery channels.
India
Organized retail expansion in Mumbai and Delhi creates first-mover openings for microwaveable cartons in frozen snack segments. FSSAI food-contact material standards are tightening parallel to import substitution policies under the PLI scheme. Gujarat and Maharashtra industrial corridors attract coating chemistry investments targeting South Asian convenience food penetration.
United Kingdom
London and Southeast England retail chains specify customized printing and opening features for chilled meal differentiation. Post-Brexit alignment friction between UK food contact regulations and EU REACH standards complicates cross-border carton sourcing for ready meal exporters. Midlands packaging clusters adapt susceptor bonding processes for hybrid EU-UK compliance pathways.
Microwaveable Carton Market Competitive Landscape
The competitive structure tilts toward integrated paperboard converters with captive barrier coating capabilities. Tier-one players combine pulp sourcing control with in-house susceptor development, while mid-scale specialists compete on format customization speed. Three archetypes dominate: Nordic-Baltic integrated pulp-to-coating conglomerates, North American scale-driven food packaging platforms, and European sustainability-focused barrier innovators. Capacity expansion and REACH-compliant coating reformulation represent the dominant competitive moves across all tiers.
Among integrated Nordic-Baltic players, Huhtamaki Oyj and Mondi Group exemplify the pulp-sourcing-plus-barrier-development archetype that European regulation increasingly favors. Sealed Air Corporation anchors the North American scale platform model. These three names from the raw data occupy positions spanning the geographic and capability spectrum without exhausting the competitive field.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Mondi Group |
| Sonoco Products Company |
| Graphic Packaging International |
| WestRock Company |
| Coveris Holdings |
| Others |
Value Network & Pricing Analysis
REACH-compliant coating certification bifurcation separates premium converters from commodity suppliers across European and North American supply chains, compressing margins for uncertified players while rewarding integrated coating developers with pricing power anchored in regulatory compliance and captive pulp sourcing.
Pricing Analysis
Bundled coating-plus-certification services command substantial premiums over unbundled commodity carton supply. Three-tier pricing structure across premium REACH-certified, standard FDA-compliant, and economy non-certified levels tracks migration testing investment and dual-approval overhead. Pricing pressure stems from pulp cost volatility under Nordic supply disruptions, compressing fixed-contract margins. Food manufacturers with direct procurement scale exhibit lowest price sensitivity, while fragmented foodservice distributors face acute cost pressure.
Supply Chain Analysis
Polymer chemist scarcity across Germany, the United States, and Japan constrains susceptor-to-paperboard bonding optimization under accelerated production timelines. Bleached kraft paperboard, aluminum susceptor films, and water-based barrier sealants constitute critical input dependencies. Single-source vulnerability concentrates in Nordic pulp supply corridors disrupted by seasonal logistics constraints. Distribution runs through direct-to-manufacturer frameworks consolidated by large frozen food brands bypassing traditional packaging intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in polyethylene-free barrier coating transitions, where regulatory compliance premiums offset input cost volatility through differentiated positioning in European ready meal supply chains.
For Market Incumbents: Anchor competitive position through captive coating chemistry development and integrated pulp sourcing across Nordic-Baltic supply corridors. Defend against emerging Asia-Pacific converters by accelerating REACH-compliant susceptor layer deployment ahead of sunset dates. Prioritize dual-certification capacity investments spanning FDA and EFSA approval pathways to compress rival launch timelines. For New Entrants and Emerging Players: Begin with frozen snack segments in Indian organized retail corridors where first-mover carton adoption remains underdeveloped. Penetrate through polyethylene-free coating partnerships with certified Nordic chemical suppliers rather than capital-intensive in-house barrier development. Leverage FSSAI compliance alignment with PLI scheme incentives to secure domestic manufacturing footholds. For Investors and Strategic Acquirers: Consolidation pressure builds where coating chemistry expertise concentrates in mid-scale European specialists lacking pulp integration. Frame long-term viability around REACH-compliant barrier development capability as the primary value anchor. Target acquisition archetypes combining certified coating R&D with underutilized paperboard capacity. Monitor EU Packaging and Packaging Waste Regulation enforcement intensity as inflection signal for fiber-format acceleration against plastic tray displacement.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | European converters capture shelf space from legacy plastic tray suppliers under tightened migration limits. |
| Integrated Pulp-to-Coating Capacity Expansion | Nordic-Baltic producers secure margin defense against pulp price volatility through captive supply control. |
| Direct-to-Manufacturer Procurement Consolidation | Walmart and Kroger private-label lines reshape North American distribution by bypassing traditional intermediaries. |
| Dual-Certification Investment (FDA/EFSA) | Converters compress rival launch timelines by maintaining parallel approval capacity across regulatory jurisdictions. |
| Smart Susceptor-RFID Integration | Healthcare meal delivery channels enable premium positioning through temperature-tracking convergence with microwave-responsive coatings. |
Research Methodology
Multiple input streams — primary interviews with coating R&D directors, frozen food procurement managers, and regulatory compliance officers; secondary validation through EFSA food contact panel opinions, FDA 21 CFR guidance documents, and EU Packaging and Packaging Waste Regulation impact assessments; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product type, material composition, barrier chemistry tier, and end-user procurement scale dimensions informed analytical framework construction over the projection horizon. CAGRs were derived from segment-level volume trajectories calibrated against regulatory compliance timelines and ready meal format substitution elasticity. Industry-specific forecast inputs incorporated pulp supply disruption patterns and dual-certification approval cycle durations.
Several conditions sit outside the modeled scope, including speculative bio-based susceptor technologies not yet at commercial scale and hypothetical retort-grade fiber barrier breakthroughs. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and frozen food consumption elasticity. Material deviation in EU Packaging and Packaging Waste Regulation implementation schedules, Nordic pulp supply stability, or California EPR law friction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Reverse Tuck Cartons Market
Cartons
Liquid Packaging Cartons Market
Cartons
Braille Cartons Packaging Market
Cartons
Interlocking Boxes Market
Cartons
Pizza Cartons Market
Cartons
Global Cartonboard Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
XXL Packaging Market
Cartons
Metallized Folding Cartons Market
Cartons
Tetrahedron Carton Market
Cartons
Carton Display Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Mono Carton Market
Cartons
Cardboard Crates Market
Cartons
Luxury Folding Carton Market
Cartons
Shaped Liquid Cartons Market