
 Asia Pacific Folding Carton Market | 2026-2036
Asia Pacific Folding Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Folding Carton Market Outlook
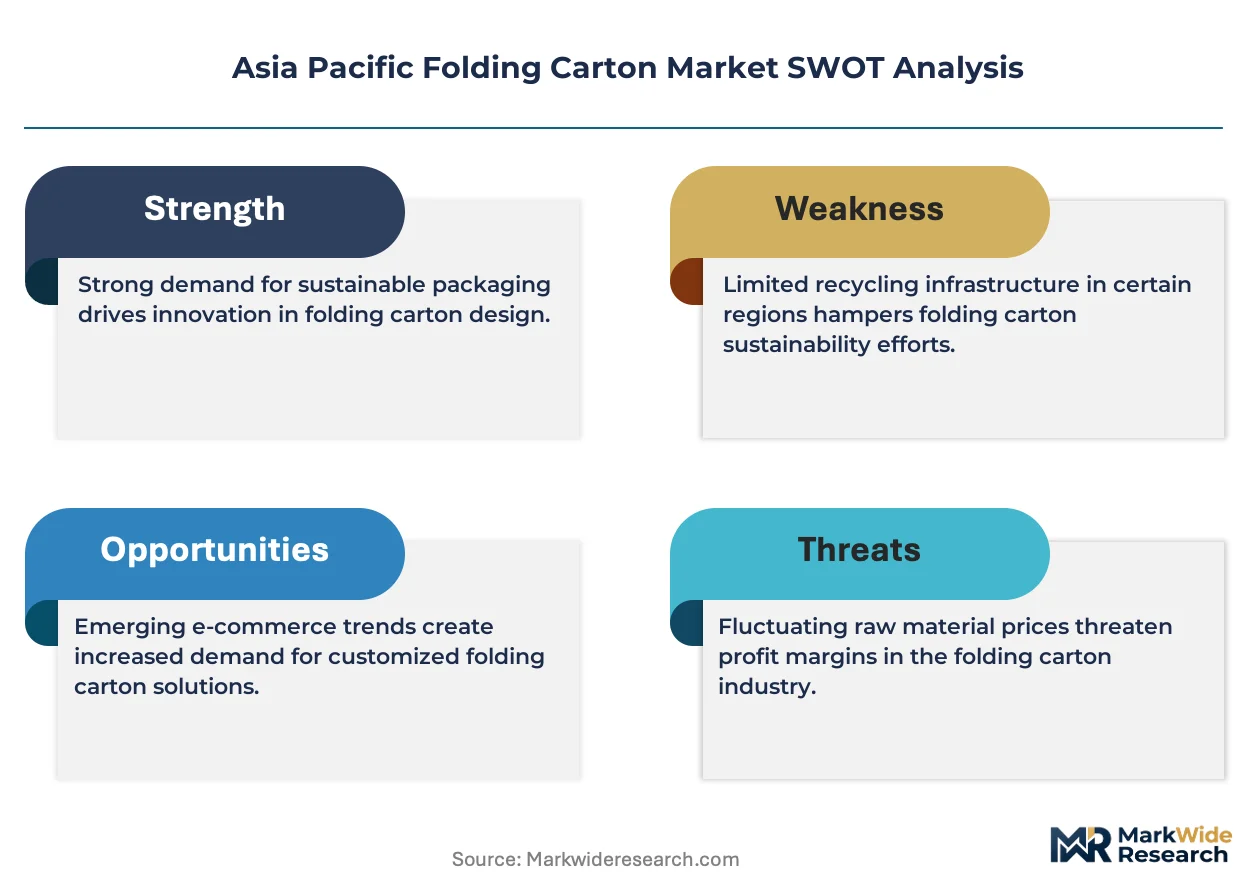
FSC chain-of-custody certification is unwinding competitive access across the Asia Pacific folding carton supply base, filtering out uncertified regional converters from pharmaceutical and premium food contracts. Oji Holdings Corporation leverages its integrated pulp-to-boxboard operations across Japan and Southeast Asia to sustain cost advantages in virgin fiber grades. Rengo Co. Ltd. anchors its position through deep relationships with Japanese beverage and cosmetics brands requiring high-definition printing on coated cartons.
Asia Pacific folding carton denotes paper-based packaging structures manufactured from calendered paperboard, typically ranging from 200 to 400 gsm, that fold flat for shipping and assemble without adhesives at the point of filling. These structures serve primary containment, shelf display, and brand communication functions for consumer packaged goods across retail and pharmacy channels. Printed cartons command the widest application footprint but face margin compression from overcapacity in standard formats, while specialty cartons incorporating holographic substrates and tamper-evident closures capture disproportionate value in pharmaceutical and luxury personal care segments. Recycled paperboard volumes are expanding fastest among material categories as brand owners in Australia and Japan enforce post-consumer content minimums in supplier scorecards.
Japan's Ministry of Economy, Trade and Industry (METI) enforces container and packaging recycling quotas that obligate manufacturers to fund collection infrastructure, directly elevating demand for recyclable mono-material carton designs. China's Ministry of Ecology and Environment (MEE) implements dual carbon compliance timelines that restrict virgin pulp imports and incentivize domestic recycled fiber processing capacity. India's Bureau of Indian Standards (BIS) mandates specific grammage and burst strength parameters for food-contact paperboard, creating technical barriers for informal converters serving unorganized retail. Stakeholders must monitor how divergent national recycling infrastructure maturity shapes material specification decisions across multi-country supply contracts.
Market Dynamics
China's dual carbon compliance timelines are forcing converters to reconfigure fiber sourcing, while FSC chain-of-custody certification filters out uncertified suppliers from pharmaceutical contracts. This regulatory-material intersection is compressing margins for non-integrated players and rewarding pulp-to-boxboard operators.
Growth Catalysts
- Pharmaceutical serialization mandates:India's CDSCO and China's NMPA require tamper-evident packaging with track-and-trace capabilities, pulling demand toward specialty cartons with holographic closures and integrated RFID.
- Japan's METI recycling quotas:Container and packaging recycling obligations obligate manufacturers to fund collection infrastructure, elevating demand for mono-material recyclable carton designs that simplify end-of-life processing.
- Recycled fiber processing investments:China's Ministry of Ecology and Environment restricts virgin pulp imports while incentivizing domestic recycled fiber capacity, redirecting capital toward deinking and repulping infrastructure in Shandong and Jiangsu provinces.
Market Restraints
- Virgin fiber cost volatility:Bleached kraft pulp prices swing with Indonesian and Malaysian supply disruptions, squeezing converters lacking long-term supply contracts or captive pulp operations.
- Converter concentration in western India:Demand clustering around Mumbai and Pune creates logistics bottlenecks for brands requiring just-in-time delivery to northern and eastern manufacturing zones.
- Flexible packaging substitution:Stand-up pouches and flow wraps capture shelf-stable food and personal care volumes where barrier properties and lightweight shipping economics outweigh carton rigidity.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Folding carton consumption per capita lags China and Japan by substantial margins, offering first-mover positioning as modern retail formats expand in Ho Chi Minh City and Jakarta.
- Cosmetics e-commerce unboxing requirements:Premium beauty brands operating through Tmall and Lazada specify rigid cartons with magnetic closures and soft-touch laminations that survive last-mile handling.
- Australia's post-consumer content mandates:Brand owner scorecards enforce minimum recycled content thresholds, creating premium pricing windows for converters with verified fiber provenance systems.
Industry Challenges
- High-definition print technician scarcity:Coated carton production for Japanese beverage and cosmetics brands requires operators skilled in UV offset and cold-foil stamping, with training pipelines failing to match retirement rates.
- FSC certification timeline compression:Pharmaceutical and premium food contracts now require valid chain-of-custody documentation, forcing uncertified regional converters through 12-18 month audit cycles or exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Folding Carton Market |
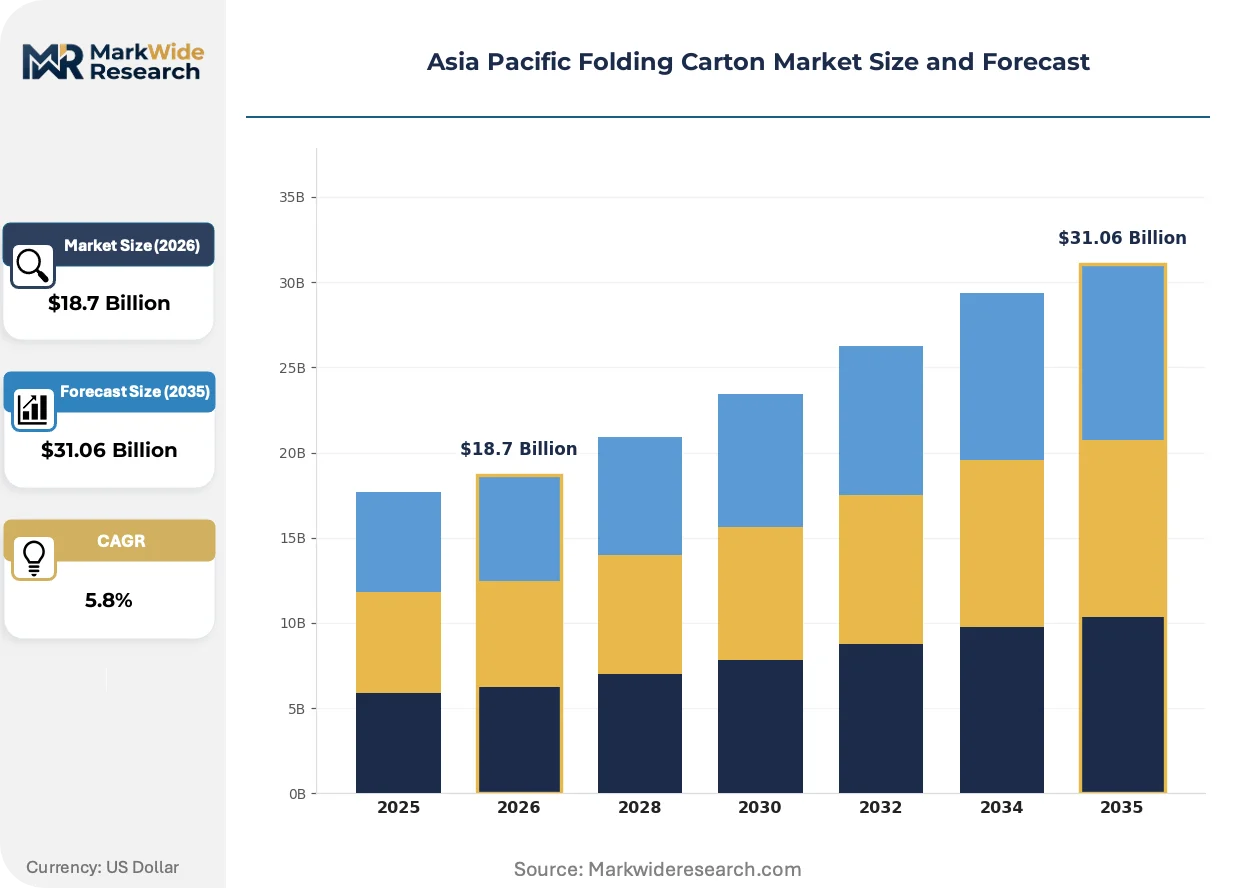
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printed Cartons, Unprinted Cartons, Coated Cartons, Specialty Cartons End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Material: Recycled Paperboard, Virgin Paperboard, Solid Bleached Board, Folding Boxboard Packaging Type: Standard Boxes, Display Boxes, Custom Shapes, Window Boxes |
| Companies Covered | Oji Holdings Corporation, Rengo Co. Ltd., SCG Packaging, Smurfit Kappa Group, WestRock Company, Graphic Packaging International, DS Smith, Amcor Plc, Huhtamaki Oyj, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Folding Carton Market Strategic Shifts
Digital printing and smart packaging technologies are reshaping production economics and brand-consumer interaction models. These shifts intersect with regulatory pressure on recyclability and traceability, creating divergent capability requirements across buyer segments.
Water-based barrier coatings are bifurcating the coated carton segment. These formulations replace polyethylene extrusion layers to maintain moisture and grease resistance while preserving repulpability. Japanese beverage brands and Australian food exporters are specifying these coatings at accelerating rates. The technology is bifurcating converter economics: integrated operators with in-house coating lines capture pharmaceutical and export contracts, while commodity players face margin compression in standard formats.
China's dual carbon goals under MEE oversight restrict virgin pulp imports and mandate domestic recycled fiber processing expansion. This policy elevates capital requirements for compliance and disadvantages converters dependent on imported bleached kraft. Pharmaceutical and luxury personal care segments respond by tightening supplier scorecards around verified carbon accounting, favoring integrated pulp-to-boxboard operators with transparent Scope 3 data.
Brand owner consolidation in ASEAN cosmetics and OTC pharmaceuticals concentrates purchasing power among fewer procurement teams. These buyers unbundle specification-setting from manufacturing execution, engaging design agencies directly while tendering production to lowest-compliant bidders. The shift is most visible in Singapore and Thailand, where regional headquarters functions centralize sourcing decisions across Southeast Asian affiliate markets.
Asia Pacific Folding Carton Market Segmentation
Segmentation in the Asia Pacific folding carton market reveals how regulatory pressure and end-use requirements fragment converter capabilities across material grades and finishing complexity. Pharmaceutical serialization mandates and cosmetics e-commerce specifications are concentrating demand in coated and specialty formats while compressing margins in commodity segments.
Product Type:
Domestic consumption across Japan, China, and India absorbs the majority of printed and coated volumes, while specialty cartons serve export-oriented pharmaceutical and luxury personal care production.
- Printed Cartons:These structures carry multi-color offset or flexographic decoration for shelf differentiation in retail environments. Demand clusters around Mumbai and Pune for Indian domestic food brands, though overcapacity in standard formats squeezes converter margins.
- Specialty Cartons:Incorporating holographic substrates, tamper-evident closures, and cold-foil stamping for authentication requirements. Japanese cosmetics brands and pharmaceutical exporters in Shanghai specify these formats for Tmall and Lazada distribution channels.
- Coated Cartons:Clay-coated or polymer-treated surfaces enable high-definition reproduction for beverage and personal care applications.
- Unprinted Cartons:Plain kraft or white-top structures for secondary shipping containment and industrial end-uses.
Printed cartons hold the largest share; momentum sits with specialty cartons.
End User:
Cost tier stratification separates premium pharmaceutical and cosmetics specifications from commodity food and electronics volumes.
- Pharmaceuticals:CDSCO and NMPA serialization mandates require integrated track-and-trace capabilities with tamper-evident features. Australian exporters and Japanese domestic producers specify mono-material designs to satisfy METI recycling quotas.
- Personal Care:Premium beauty brands operating through regional e-commerce platforms demand rigid cartons with magnetic closures and soft-touch laminations that survive last-mile handling in Ho Chi Minh City and Jakarta.
- Food & Beverage:Water-based barrier coatings are replacing polyethylene extrusion layers for Australian export and Japanese beverage applications.
- Electronics:Anti-static and cushioning specifications for consumer device protection in transit.
Food and beverage commands volume leadership; personal care delivers the steepest expansion trajectory.
Material:
Supply concentration around Shandong and Jiangsu provinces is redirecting fiber flows as MEE restrictions on virgin pulp imports reshape converter sourcing patterns.
- Recycled Paperboard:Post-consumer fiber processed through deinking and repulping infrastructure. Australian brand owner scorecards enforce minimum content thresholds, creating premium pricing windows for verified provenance systems.
- Solid Bleached Board:Virgin fiber construction with pharmaceutical-grade purity and grease resistance. Japanese and Australian pharmaceutical packaging absorbs the majority of regional SBB output.
- Virgin Paperboard:Bleached kraft pulp grades subject to Indonesian and Malaysian supply disruption volatility.
- Folding Boxboard:Multi-ply construction with recycled core and bleached surface layers for cost-performance balance.
Folding boxboard maintains the largest installed base; recycled paperboard is climbing the fastest.
Packaging Type:
Application requirements separate standardized production formats from value-added display and custom configurations.
- Display Boxes:Shelf-ready designs with tear-away panels and stacking features for modern retail formats. Expansion in Vietnamese and Indonesian convenience store chains drives specification adoption.
- Custom Shapes:Die-cut and windowed structures for cosmetics unboxing experiences and pharmaceutical compliance packaging. Singapore and Thailand regional headquarters centralize sourcing decisions for Southeast Asian affiliate markets.
- Standard Boxes:Rectangular formats for high-volume food and electronics applications with minimal finishing.
- Window Boxes:Aperture designs with film or open viewing panels for product visibility at point of sale.
Standard boxes hold the largest share; display boxes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement teams and premium cosmetics brands concentrate purchasing power in specific manufacturing belts, creating divergent capability requirements across national markets.
China
Shanghai and Jiangsu province host pharmaceutical exporters requiring track-and-trace packaging for NMPA compliance. MEE dual carbon restrictions on virgin pulp imports are redirecting converter investment toward Shandong's recycled fiber processing infrastructure.
Japan
Kanto region beverage and cosmetics brands specify high-definition coated cartons with UV offset finishing. METI recycling quotas obligate manufacturers to fund collection infrastructure, elevating mono-material carton specifications for domestic and export channels.
India
CDSCO serialization mandates pull demand toward tamper-evident specialty cartons for pharmaceutical distribution. Converter capacity clusters around Mumbai and Pune in the western manufacturing belt, creating logistics constraints for brands requiring just-in-time delivery to northern and eastern zones.
Australia
Brand owner scorecards enforce post-consumer content minimums for food-contact paperboard, creating premium pricing windows for converters with verified fiber provenance. Water-based barrier coatings are replacing polyethylene extrusion layers for export-oriented food applications.
Vietnam
Folding carton consumption per capita lags regional benchmarks as modern retail formats expand in Ho Chi Minh City. First-mover positioning opportunities exist for converters capable of pharmaceutical-grade serialization and cosmetics e-commerce specifications.
Asia Pacific Folding Carton Market Competitive Environment
Player mix skews toward integrated pulp-to-boxboard operators and regional specialists with deep buyer relationships. Consolidation pressure favors operators with captive fiber supply and in-house coating capabilities. Two strategic archetypes dominate: vertically integrated Japanese conglomerates with cost advantages in virgin fiber grades, and Southeast Asian specialists leveraging proximity to emerging demand centers. Competitive moves concentrate on capacity expansion in recycled fiber processing and strategic partnerships for digital printing technology access.
Within the integrated operator tier, Oji Holdings Corporation and Rengo Co. Ltd. exemplify the Japanese conglomerate model with pulp-to-boxboard operations spanning multiple Asian markets. SCG Packaging represents the Southeast Asian specialist archetype with regional manufacturing footprint. These three anchors illustrate how fiber integration depth and geographic positioning separate premium-tier suppliers from commodity competitors facing margin compression.
| Leading Market Players |
|---|
| Oji Holdings Corporation |
| Rengo Co. Ltd. |
| SCG Packaging |
| Smurfit Kappa Group |
| WestRock Company |
| Graphic Packaging International |
| DS Smith |
| Amcor Plc |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day order-to-delivery windows for coated pharmaceutical cartons concentrate pricing power with integrated operators in Japan and China, while spot-market converters absorb volatility in recycled fiber grades. This lead-time stratification rewards pulp-to-boxboard players with captive fiber supply and squeezes margin for non-integrated regional suppliers serving commodity food segments.
Pricing Analysis
Cost-plus contracts indexed to Shanghai pulp futures dominate pharmaceutical and cosmetics segments, with FSC-certified grades commanding premium-mid-economy pricing differentiation based on chain-of-custody verification and carbon accounting transparency. Price erosion runs through standard printed carton tiers as overcapacity in Mumbai-Pune clusters intensifies bidding pressure for domestic food brand volumes. Brand owners in Australia and Japan exhibit lowest price sensitivity where post-consumer content mandates and METI recycling quotas prioritize compliance over unit cost.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo elevates inbound logistics costs for Indonesian bleached kraft pulp, forcing converters to absorb demurrage or pass through container availability premiums. Raw material flows center on Shandong and Jiangsu recycled fiber processing, Japanese virgin pulp imports, and Malaysian-Indonesian bleached kraft grades. Single-source vulnerability concentrates in pharmaceutical-grade solid bleached board where Japanese integrated operators control regional output. Distribution runs through converter-direct relationships with pharmaceutical and cosmetics brand owners, bypassing traditional packaging distributors for specification-sensitive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific folding carton market sits in early-cycle expansion as pharmaceutical serialization mandates and cosmetics e-commerce specifications accelerate specialty carton adoption beyond historical penetration rates in Vietnam and Indonesia.
For Market Incumbents: Shield core pharmaceutical contracts through accelerated FSC certification completion and captive recycled fiber processing investments in Shandong or Jiangsu provinces. Flexible packaging substitution in shelf-stable food segments and emerging digital printing competitors from Southeast Asia threaten commodity tier margins, making backward integration into deinking infrastructure the priority defensive lever. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade serialization capabilities and water-based barrier coating expertise to capture share in Vietnam's underpenetrated modern retail expansion. Ho Chi Minh City and Jakarta present the most penetrable demand clusters where first-mover positioning in cosmetics e-commerce specifications and NMPA-compliant export packaging enables bypass of entrenched incumbent relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance timelines and capital requirements for dual carbon alignment are filtering out uncertified regional converters. Target mid-cap specialists with verified fiber provenance systems and in-house coating lines. Watch CDSCO and NMPA enforcement intensity as the signal for inflection in specialty carton pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Fiber Processing Capacity Expansion | MEE dual carbon restrictions on virgin pulp imports redirect capital toward Shandong and Jiangsu deinking infrastructure. |
| FSC Chain-of-Custody Certification Acceleration | Pharmaceutical and premium food contracts now exclude uncertified suppliers, compressing 12-18 month audit timelines. |
| Water-Based Barrier Coating Line Installation | Japanese beverage brands and Australian food exporters specify repulpable coatings replacing polyethylene extrusion layers. |
| Digital Printing Technology Partnership | Cosmetics e-commerce unboxing requirements and pharmaceutical serialization favor short-run, variable-data production economics. |
| Vietnam-Indonesia Manufacturing Footprint Establishment | Per capita consumption gaps in Ho Chi Minh City and Jakarta create first-mover positioning in modern retail expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement directors at pharmaceutical and cosmetics brand owners, plant managers at integrated pulp-to-boxboard facilities, and technical directors at specialty coating operations. Secondary validation drew from CDSCO and NMPA regulatory filings, METI recycling quota documentation, MEE dual carbon policy releases, and customs trade data for bleached kraft pulp flows. Bottom-up capacity assessments across Shandong, Jiangsu, and western India manufacturing belts were triangulated against top-down demand modeling from pharmaceutical serialization mandate timelines.
Across the analysis window, volume and value outputs were constructed through segmentation modeling across material grade, end-use application, and geographic production cluster dimensions. CAGRs were derived from regression analysis against pharmaceutical packaging adoption curves and recycled fiber processing capacity buildout schedules. Forecast inputs incorporated NMPA and CDSCO enforcement intensity assumptions, METI recycling infrastructure funding obligations, and brand owner scorecard evolution for post-consumer content thresholds.
Decision-makers should treat outputs as directional under base assumptions of sustained dual carbon policy implementation and stable pharmaceutical serialization mandate enforcement; material deviation in regulatory timelines or pulp supply disruption severity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Metallized Folding Cartons Market
Cartons
Mono Carton Market
Cartons
Twist Opening Cartons Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Carton Serialization Machine Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Japan Corrugated Boxes Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Carton Sealer Machine Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Liquid Packaging Cartons Market
Cartons
Luxury Folding Carton Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Pick and Place Carton Packers Market
Cartons
Carton Liners Market
Cartons
Mailers Market