
 GCC Corrugated Box Packaging Market | 2026-2036
GCC Corrugated Box Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Corrugated Box Packaging Market Insights
E-commerce fulfillment operators are bifurcating demand away from traditional retail distribution as the dominant buyer archetype in the GCC corrugated box packaging landscape. Falcon Pack leverages its integrated paper mill and converting assets across the UAE to secure supply chain continuity for regional e-commerce platforms. United Carton Industries Company anchors its position through large-format regular slotted container production serving Saudi Arabia's food export sector. Napco National differentiates via specialty die-cut designs for electronics and pharmaceutical cold-chain requirements.
Corrugated box packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed from kraft or recycled pulp with burst strengths ranging from 150 to 400 psi depending on wall configuration. The primary industrial purpose centers on protective containment, stackable transport, and brand-visible retail presentation for consumer and industrial goods moving through GCC free zones and last-mile networks. Single wall material dominates volume shipments into food and beverage applications where cost-per-unit containment governs procurement decisions. Digital printing technology captures the fastest expansion as brand owners in the UAE and Saudi Arabia shorten run lengths for seasonal promotional campaigns and private-label introductions.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE Emirates Authority for Standardization and Metrology (ESMA) packaging mandates shape board grammage, food-contact safety, and labeling compliance across Gulf markets. The EU Green Deal's extraterritorial influence on GCC export-oriented manufacturers is accelerating adoption of FSC-certified linerboards and water-based inks to maintain European market access. Stakeholders must monitor how Saudi Arabia's Local Content Requirement Program and evolving extended producer responsibility frameworks in the UAE reshape supplier qualification criteria and capital allocation toward circular material flows.
Market Dynamics
E-commerce fulfillment operators have displaced traditional retail distribution as the dominant demand source across GCC corrugated box markets, redirecting volume requirements toward die-cut specifications and shorter production runs that favor digital printing investments.
Growth Catalysts
- Saudi Vision 2030 localization mandates:Domestic content requirements are redirecting procurement toward regional converters with integrated paper mill assets, creating captive supply advantages for compliant suppliers.
- UAE circular economy frameworks:Extended producer responsibility policies are accelerating recycled-content board adoption, with ESMA packaging mandates specifying minimum post-consumer fiber thresholds for food-contact applications.
- Kuwait logistics corridor expansion:Mega-warehouse clusters along the Riyadh-Jeddah axis are consolidating demand for high-volume regular slotted containers with automated palletization compatibility.
Market Restraints
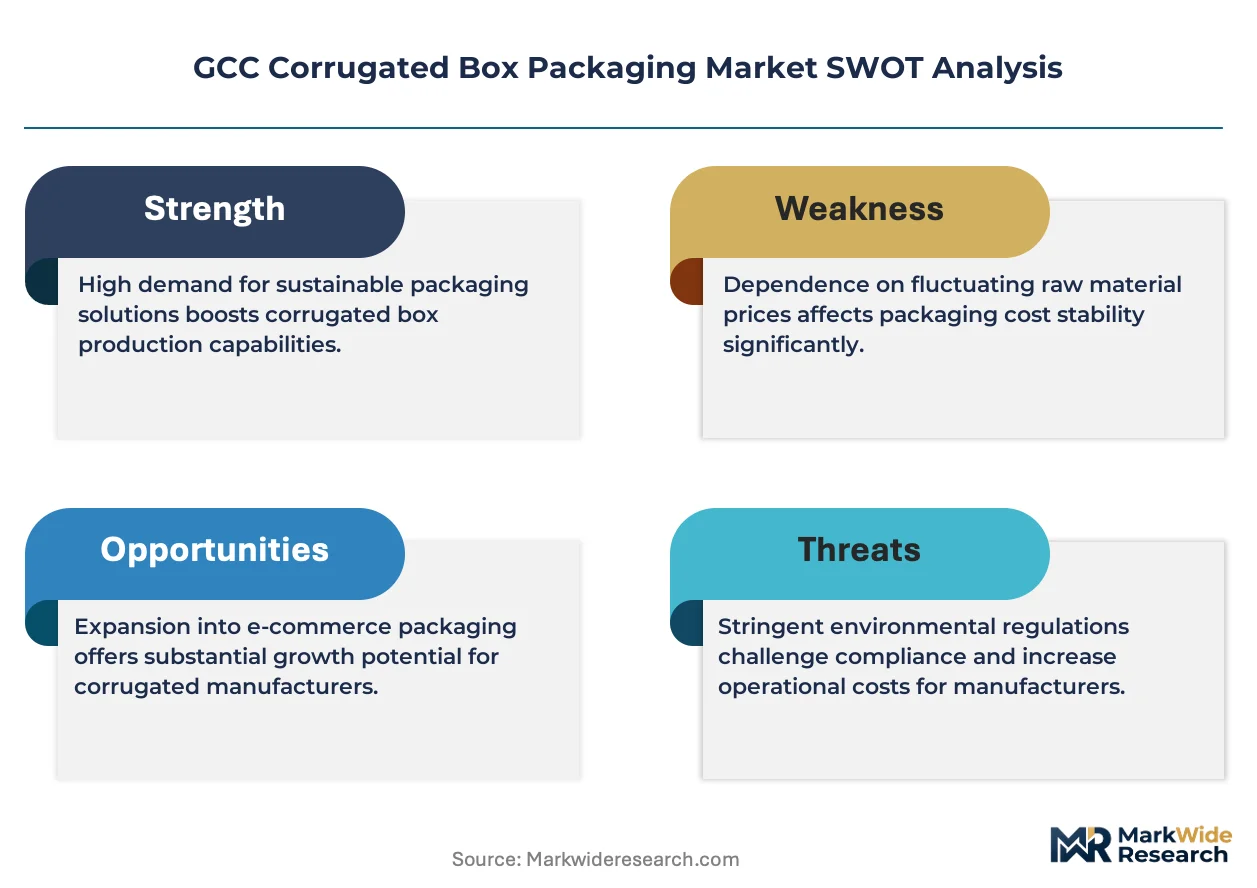
- Kraft pulp price volatility:GCC converters remain import-dependent for virgin linerboard feedstock, exposing margins to global pulp commodity swings and freight rate fluctuations from European and Southeast Asian suppliers.
- Recycled fiber supply concentration:Local OCC recovery infrastructure is underdeveloped across Oman and Bahrain, forcing reliance on imported recycled pulp with inconsistent quality specifications.
- Water-based ink curing limitations:High ambient temperatures in Gulf summer months extend drying cycles for sustainable ink formulations, constraining throughput speeds versus solvent-based alternatives.
Strategic Opportunities
- Qatar cold-chain pharmaceutical packaging:Temperature-controlled die-cut designs for biologics distribution represent underpenetrated white space as Doha expands its regional pharma hub status.
- Digital printing-converting convergence:Integration of inkjet systems with inline die-cutting enables lot-size-one production for private-label food introductions, compressing campaign launch timelines from weeks to days.
- SASO biodegradable certification pathway:Early compliance with emerging Saudi compostability standards positions converters for preferential procurement from export-oriented food processors targeting EU market access.
Industry Challenges
- Prepress automation skill scarcity:Digital workflow management and color consistency calibration require specialized technicians that regional technical institutes are not yet producing at sufficient scale.
- Legacy corrugator reconfiguration costs:Retrofitting existing flute-forming lines for lightweight micro-flute production demands capital outlays that mid-scale converters struggle to justify against payback uncertainties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Corrugated Box Packaging Market |
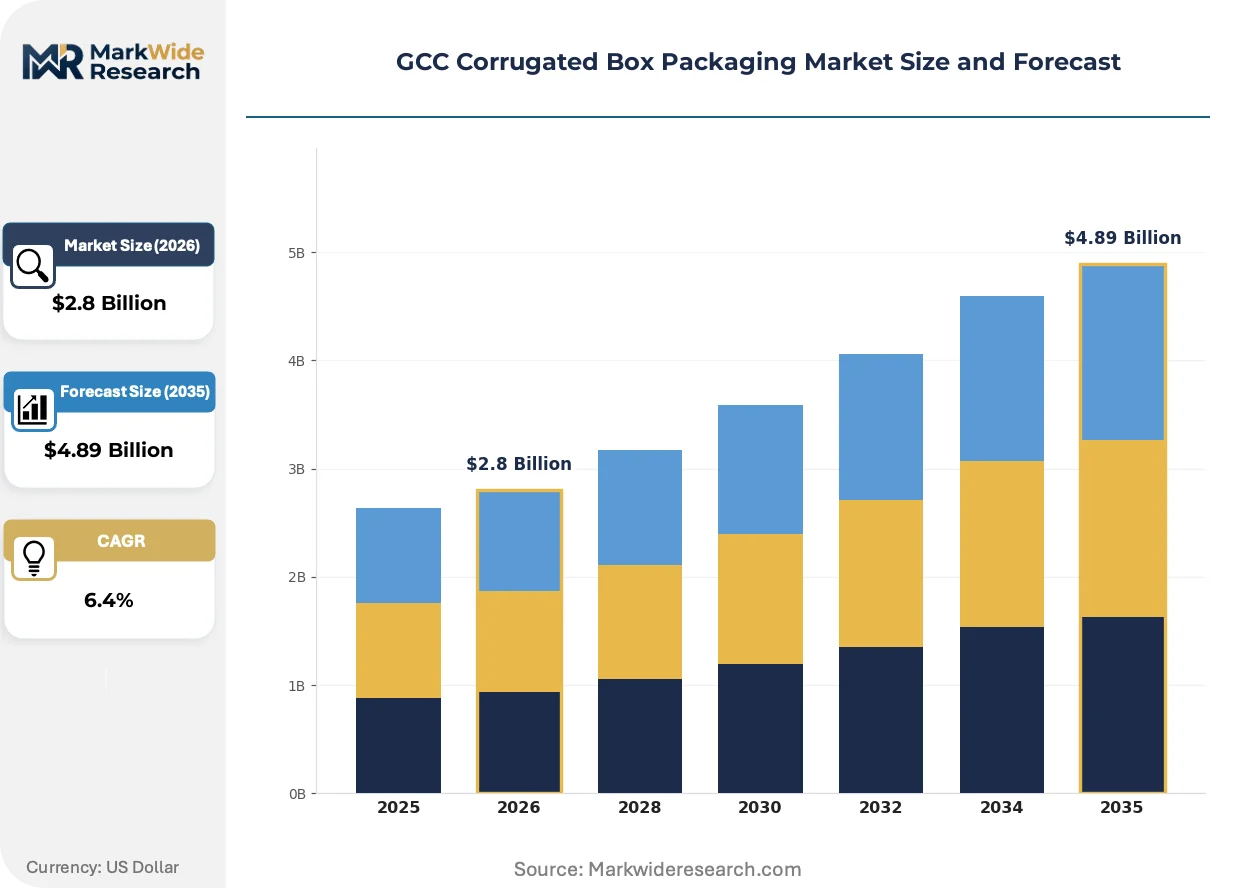
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Die-Cut Box, Folding Carton, Set-Up Box Material: Single Wall, Double Wall, Triple Wall, Recycled Paper End User: Food & Beverage, Electronics, Consumer Goods, Pharmaceuticals Printing Technology: Flexographic Printing, Digital Printing, Lithographic Printing, Offset Printing |
| Companies Covered | Falcon Pack, United Carton Industries Company (UCIC), Stora Enso Oyj, Arabian Packaging Co. LLC, Universal Carton Industries Group, Al Rumanah Packaging, Napco National, Queenex Corrugated Carton Factory, Cepack Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Corrugated Box Packaging Market Trends and Innovations
Digital production technologies and sustainability compliance frameworks are converging to reshape converter economics, compressing minimum order quantities while elevating specification complexity across food, electronics, and pharmaceutical end-uses.
High-speed single-pass inkjet printing is fragmenting the traditional offset lithography dominance in corrugated preprint applications. E-commerce fulfillment operators in the UAE and Saudi Arabia are adopting variable-data print runs for seasonal promotional campaigns, enabling SKU-specific branding without plate changeover delays. This capability is fragmenting volume concentration among large-format offset specialists and redistributing orders toward agile digital converters with quick-turn capabilities.
EU Green Deal extraterritorial requirements are reshaping GCC export supply chains. Food-contact board specifications for European market access now mandate FSC-certified liner sourcing and heavy-metal-free ink chemistries, compelling Saudi and UAE converters to requalify supplier bases. Electronics exporters shipping through Jebel Ali Free Zone are accelerating water-based ink adoption to maintain CE-marking compliance pathways.
Buyer consolidation among regional e-commerce platforms is compressing procurement cycles and unbundling specification-setting from traditional distributor intermediaries. Direct commercial relationships between fulfillment operators and Tier-1 converters in Riyadh and Dubai are displacing wholesale channel purchasing, concentrating volume among suppliers with integrated design-to-delivery capabilities. This pattern is most visible in Saudi Arabia's grocery delivery segment, where platform-owned dark stores dictate box dimensions optimized for automated sortation systems.
GCC Corrugated Box Packaging Market Segmentation
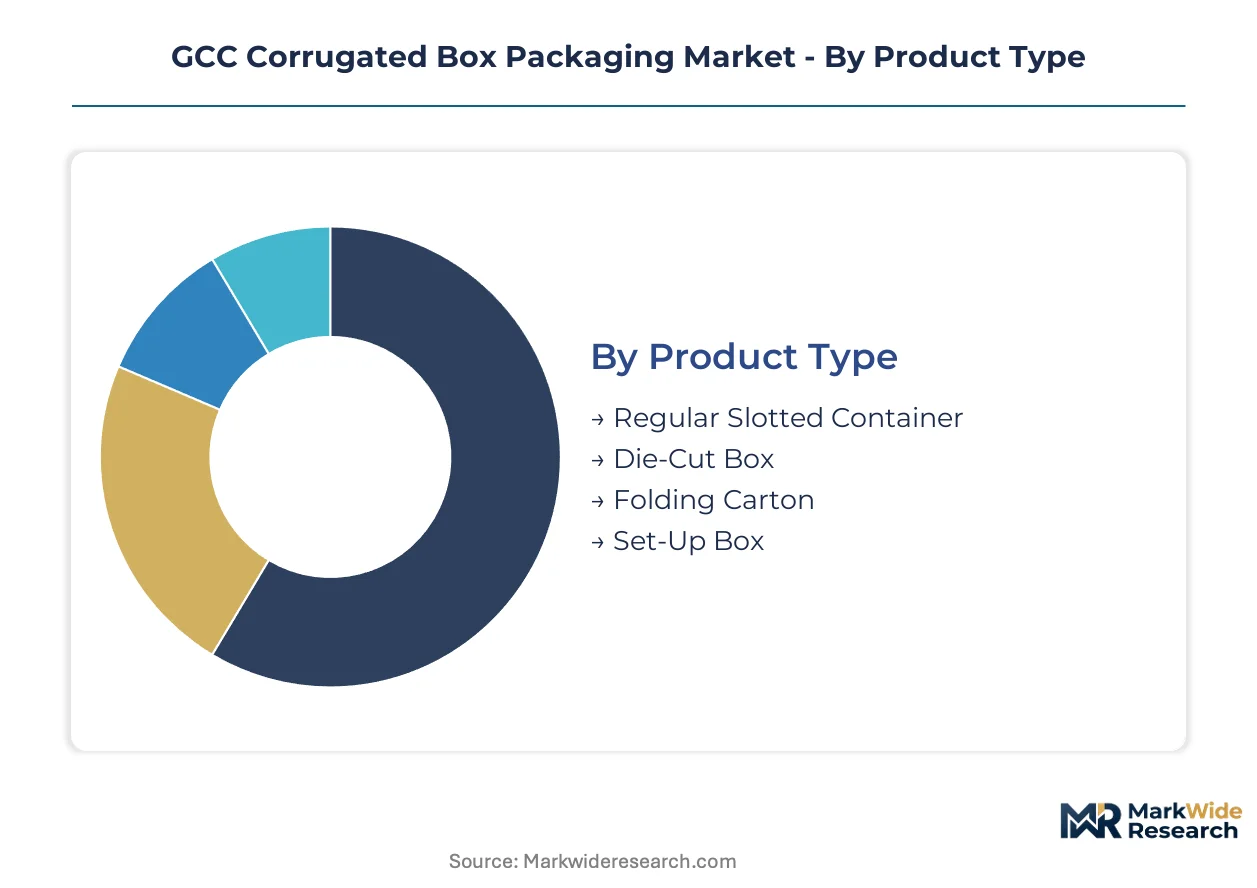
Segmentation in the GCC corrugated box packaging market reveals how regulatory frameworks and supply chain configurations create distinct procurement corridors across product specifications, material grades, and end-use applications. Understanding these divisions enables converters to align capital allocation with the diverging technical requirements of Saudi food exporters, UAE e-commerce platforms, and Qatar pharmaceutical distributors.
Product Type:
SASO technical regulations and ESMA packaging mandates create divergent compliance pathways for structural box designs, with food-contact safety certifications and dimensional tolerances varying by container format across Saudi Arabia and the UAE.
- Regular Slotted Container:Standard four-flap design with manufacturer’s joint construction dominates bulk shipments into Saudi Arabia's Riyadh-Jeddah logistics corridor. Mega-warehouse clusters and automated palletization systems in this corridor specify burst strengths between 200-350 psi for stackable transport of processed foods and consumer goods.
- Die-Cut Box:Custom-cut designs with integrated handles or display windows command premium positioning in UAE electronics and pharmaceutical cold-chain applications. ESMA mandates for food-contact safety and SASO biodegradability pathways are accelerating qualification requirements for converters serving Doha's expanding biologics distribution hub.
- Folding Carton:Pre-glued flat blanks suit high-speed forming lines in Kuwait's retail consolidation centers.
- Set-Up Box:Rigid construction targets luxury cosmetics and gift packaging in Dubai's duty-free retail zones.
Established volume favors Regular Slotted Container; emerging adoption favors Die-Cut Box.
Material:
Cost tier differentiation separates commodity procurement from performance-specified applications, with virgin kraft linerboard commanding premium positioning against recycled-content alternatives subject to ESMA minimum post-consumer fiber thresholds.
- Single Wall:One fluted medium between two linerboards delivers the lowest cost-per-unit containment for high-volume food and beverage applications. Procurement decisions in Saudi Arabia's grocery delivery segment prioritize this grade for dark store operations optimized for automated sortation systems.
- Double Wall:Two fluted layers laminated between three linerboards provide enhanced stacking strength for electronics exporters shipping through Jebel Ali Free Zone. EU Green Deal extraterritorial requirements are compelling FSC-certified liner sourcing for this grade to maintain CE-marking compliance pathways.
- Triple Wall:Heavy-duty construction serves industrial machinery and automotive parts moving through GCC free zones.
- Recycled Paper:Post-consumer fiber content is climbing fastest under UAE circular economy frameworks, though local OCC recovery infrastructure gaps in Oman and Bahrain force import dependency.
Single Wall captures the dominant procurement share; Recycled Paper is climbing the fastest on sustainability mandates.
End User:
Application-specific requirements fragment demand across temperature tolerance, print quality, and regulatory documentation needs, with each vertical imposing distinct qualification protocols on converter capabilities.
- Food & Beverage:The largest volume destination requires moisture-resistant coatings and SASO-compliant food-contact safety certifications for processed meat, dairy, and date exports from Saudi Arabia. Platform-owned dark stores are unbundling specification-setting from traditional distributor intermediaries, concentrating orders among suppliers with integrated design-to-delivery capabilities.
- Pharmaceuticals:Temperature-controlled die-cut designs for biologics distribution represent underpenetrated white space as Doha expands its regional pharma hub status. Cold-chain validation protocols and lot-level traceability requirements favor converters with inline digital printing and serialization capabilities.
- Electronics:Anti-static coatings and precision-fit cushioning specifications dominate shipments from UAE assembly operations.
- Consumer Goods:Seasonal promotional campaigns and private-label introductions are compressing minimum order quantities toward lot-size-one production.
Food & Beverage anchors procurement volume; Pharmaceuticals offers the steepest expansion trajectory on cold-chain infrastructure investment.
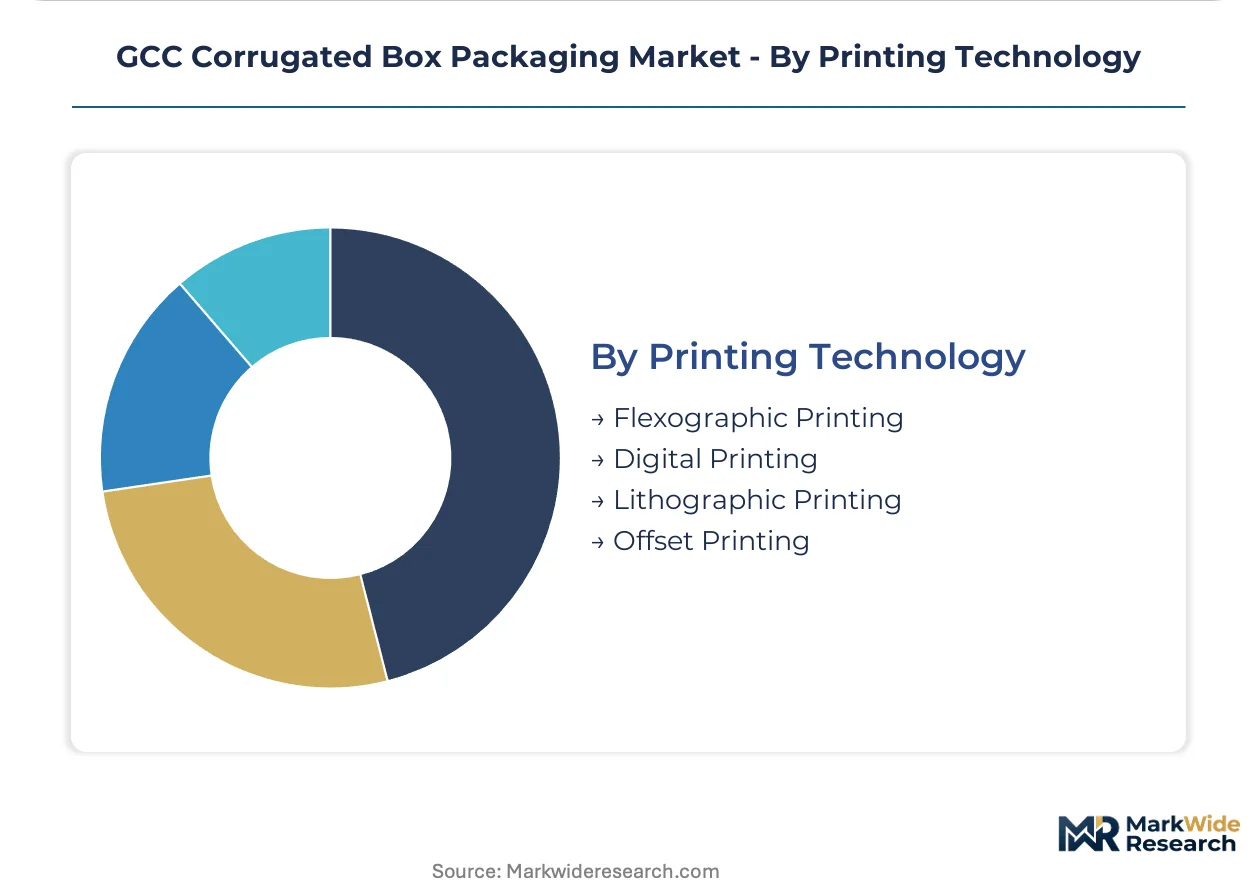
Printing Technology:
Customer type differentiation separates high-volume brand owners from agile promotional marketers, with run length economics and color consistency requirements determining technology selection.
- Digital Printing:Single-pass inkjet systems enable variable-data print runs without plate changeover delays, fragmenting volume concentration among large-format offset specialists. E-commerce fulfillment operators in the UAE and Saudi Arabia are adopting this capability for SKU-specific branding on compressed campaign launch timelines.
- Flexographic Printing:Rotary relief printing with photopolymer plates dominates long-run production of regular slotted containers for Saudi food exporters. Water-based ink curing limitations in Gulf summer months extend drying cycles, constraining throughput speeds versus solvent-based alternatives.
- Lithographic Printing:Preprint applications on linerboard prior to corrugation serve premium retail-ready packaging.
- Offset Printing:Sheet-fed processes retain position in high-fidelity cosmetic and pharmaceutical carton work.
Flexographic Printing retains established volume leadership; Digital Printing is gaining share fastest on e-commerce procurement pattern shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment operators have displaced traditional retail distribution as the dominant buyer archetype across GCC corrugated box markets. Procurement now concentrates in logistics corridors where mega-warehouse clusters and food processing zones require high-volume box supply.
Saudi Arabia
Dark store operations for grocery delivery platforms and processed food exports drive die-cut and regular slotted container demand. SASO technical regulations mandate food-contact safety certifications and biodegradability standards. The Riyadh-Jeddah logistics corridor anchors mega-warehouse clusters requiring automated palletization-compatible packaging.
United Arab Emirates
Electronics exporters through Jebel Ali Free Zone and e-commerce platforms require FSC-certified linerboards for EU market access. ESMA packaging mandates specify minimum post-consumer fiber thresholds under circular economy frameworks. Dubai's duty-free retail zones generate demand for premium set-up boxes in luxury cosmetics packaging.
Kuwait
Retail consolidation centers and food import distribution networks sustain folding carton procurement for high-speed forming lines. The national standardization body enforces packaging quality specifications for imported consumer goods. Warehouse clusters along logistics corridors are consolidating demand for stackable transport containers.
Qatar
Temperature-controlled die-cut designs for biologics distribution represent emerging demand as Doha expands its regional pharmaceutical hub. The national health regulator enforces cold-chain validation protocols for medical packaging. Industrial zones near Hamad Port are attracting converters with serialization and inline digital printing capabilities.
Oman
Food processing zones and fisheries exports generate single-wall container demand for cost-per-unit containment. Local OCC recovery infrastructure gaps force reliance on imported recycled pulp with inconsistent quality. Port-centric industrial clusters near Sohar are developing corrugated supply capacity for regional re-export trade.
GCC Corrugated Box Packaging Market Competitive Landscape
Player mix skews toward integrated paper mill operators and independent converters with digital printing assets. The competitive structure concentrates volume among suppliers with captive linerboard supply and quick-turn capabilities. Two strategic archetypes dominate: vertically integrated regional champions with mill-to-box operations, and agile digital specialists serving promotional campaign cycles. Competitive moves center on capacity expansion in Riyadh and Dubai logistics corridors, plus technology licensing for single-pass inkjet integration.
Among UAE-based integrated operators, Falcon Pack exemplifies the mill-owning archetype with supply chain continuity advantages. United Carton Industries Company anchors the Saudi production base through large-format regular slotted container capacity. Napco National occupies a position within the specialty die-cut tier, serving electronics and pharmaceutical cold-chain requirements. These three represent the structural segmentation between commodity volume, integrated supply security, and specification-driven premium positioning.
| Leading Market Players |
|---|
| Falcon Pack |
| United Carton Industries Company (UCIC) |
| Stora Enso Oyj |
| Arabian Packaging Co. LLC |
| Universal Carton Industries Group |
| Al Rumanah Packaging |
| Napco National |
| Queenex Corrugated Carton Factory |
| Cepack Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with kraft pulp suppliers lock in linerboard access and price visibility for GCC converters, insulating procurement costs from spot-market volatility while committing buyers to minimum volume thresholds across the forecast period. These arrangements concentrate pricing power among integrated mill operators in Saudi Arabia and the UAE, who leverage captive pulp supply to offer fixed-price regular slotted container contracts to e-commerce fulfillment platforms.
Pricing Analysis
Cost-plus contracts indexed to European pulp commodity benchmarks dominate procurement between GCC converters and virgin linerboard suppliers. Price differentiation separates FSC-certified premium grades for EU-export electronics from standard recycled-content boards serving domestic food applications. Pricing pressure stems from kraft pulp import dependency and freight rate fluctuations from Southeast Asian suppliers. Food and beverage buyers exhibit highest price sensitivity due to cost-per-unit containment mandates, while pharmaceutical cold-chain specifications tolerate premium positioning for temperature-validated die-cut designs.
Supply Chain Analysis
Strategic stockpiling of linerboard inventory prevails among Saudi integrated operators, while UAE converters favor just-in-time replenishment to minimize working capital exposure. Raw material sourcing draws from European and Southeast Asian virgin pulp producers, with recycled fiber imports filling gaps in Omani and Bahraini OCC recovery infrastructure. Supply chain risk centers on single-source vulnerability for high-grade kraft linerboard and Red Sea logistics chokepoints affecting Jebel Ali inbound flows. Distribution runs through direct commercial relationships between Tier-1 converters and platform-owned dark stores, displacing traditional wholesale channel purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against flexible plastic pouches and reusable totes encroaching on dry food and apparel fulfillment applications. Incumbents must demonstrate corrugated's superior stackability and automated sortation compatibility to preserve volume share.
For Market Incumbents: Shield market position through backward integration into recycled pulp processing to reduce import dependency and capture circular economy premiums under ESMA mandates. Invest in single-pass inkjet printing capacity to compress promotional campaign turnaround times for Saudi grocery delivery platforms. Counter flexible packaging substitution by emphasizing corrugated's automated palletization advantages in Riyadh-Jeddah mega-warehouse clusters.
For New Entrants and Emerging Players: Differentiate on cold-chain validation capabilities for Qatar's biologics distribution hub, where temperature-controlled die-cut specifications remain underpenetrated. Target pharmaceutical serialization requirements with inline digital printing and lot-level traceability systems. Pursue white-label design-to-delivery partnerships with mid-size UAE electronics exporters seeking FSC-certified packaging for EU market access.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated converters with captive linerboard supply and established SASO compliance pathways, positioned to capture Saudi localization mandate benefits. Long-term viability hinges on circular material flow investments aligning with emerging extended producer responsibility frameworks. Watch for inflection when biodegradable certification requirements under SASO technical regulations cross enforcement thresholds and reshape supplier qualification criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Printing Integration | Single-pass inkjet adoption compresses SKU-specific campaign timelines for UAE e-commerce platforms. |
| Recycled Pulp Processing Capacity | Backward integration into OCC recovery reduces import dependency under ESMA post-consumer fiber mandates. |
| Cold-Chain Validation Certification | Temperature-controlled die-cut qualification opens Qatar pharmaceutical hub procurement to compliant converters. |
| Biodegradable Board Development | Early SASO compostability compliance secures preferential positioning with Saudi food exporters targeting EU access. |
| Direct Platform Relationships |
Research Methodology
Operator-level perspectives from corrugated plant managers, e-commerce platform procurement leads, food export logistics coordinators, and pharmaceutical cold-chain specialists anchored the qualitative base. These primary insights combined with secondary validation from SASO technical regulations, ESMA packaging mandates, GCC customs trade data, and integrated paper mill SEC disclosures. Bottom-up volume modeling across product types, material grades, end-use applications, and printing technologies triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast outputs against variable kraft pulp price scenarios and logistics corridor disruption assumptions across the projection horizon. Segmentation dimensions modeled include container format, wall construction, end-use vertical, and printing technology adoption patterns. CAGRs derived from historical shipment trajectories and projected demand elasticity for e-commerce fulfillment, food export, and pharmaceutical cold-chain applications. Industry-specific inputs incorporated mega-warehouse cluster expansion timelines and circular economy policy implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce penetration rates and stable pulp commodity trading ranges would require recalibration. Forecasts reflect documented assumptions regarding Saudi localization enforcement intensity and UAE extended producer responsibility rollout pace. Revision becomes warranted when biodegradable certification adoption crosses threshold levels among export-oriented food processors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Shaped Liquid Cartons Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Horizontal Cartoning Machines Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Global Hand Carton Sealers Market
Cartons
Tetrahedron Carton Market
Cartons
Europe Corrugated Box Market
Cartons
Reverse Tuck Cartons Market
Cartons
Carton Bottle Market
Cartons
Digital Folding Cartons Market
Cartons
MET-PET Cartons Market
Cartons
Microwaveable Carton Market
Cartons
Beverage Cartoners Market
Cartons
Luxury Folding Carton Market