
 Fluid Power Cylinder Market | 2026-2036
Fluid Power Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Power Cylinder Market Foresight
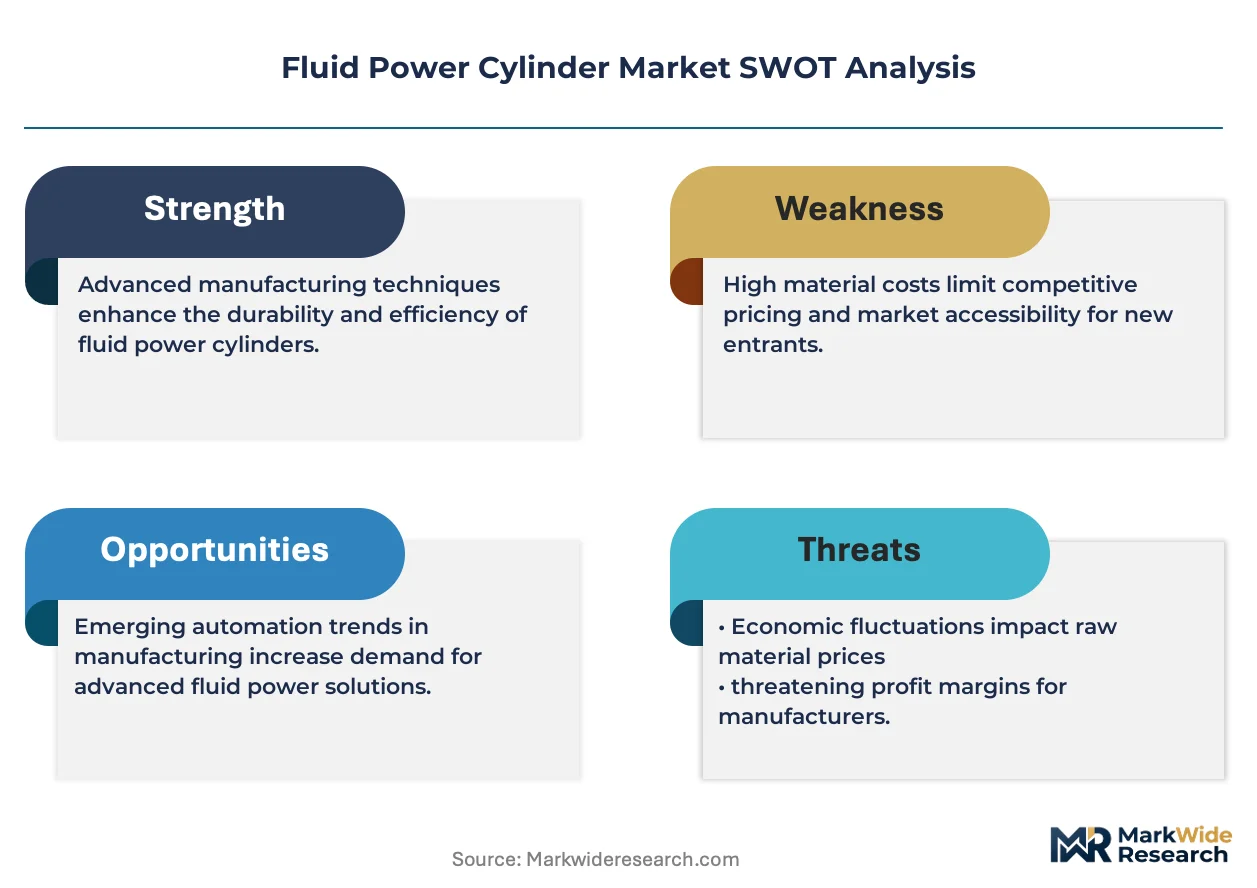
A widening capital-intensity gap between large-scale integrators and component specialists is bifurcating competitive dynamics in the fluid power cylinder landscape. Bosch Rexroth Corporation leverages captive foundry and machining capacity to control cost structures across hydraulic actuator lines. Parker Hannifin Corp anchors its position through extensive distribution networks spanning North American industrial corridors. Festo SE & Co. KG differentiates via pneumatic cylinder specialization for clean-room automation environments.
Fluid power cylinders are mechanical actuators that convert pressurized fluid energy into linear or rotary motion, typically operating at hydraulic pressures up to 350 bar or pneumatic pressures near 10 bar, with bore diameters ranging from 8 mm to over 1,000 mm depending on load requirements. These devices serve as the primary force-transmission elements in heavy machinery, automation systems, and mobile equipment where high power density and precise motion control are essential. Double acting cylinders command the largest product-type position due to their bidirectional force capability in construction and material handling applications. Hydraulic technology leads the technology split by installed base, though electrohydraulic variants are gaining traction in factory automation settings where position feedback and energy recovery matter. Mining operations and defense systems within the end-user dimension represent concentrated margin pools because of specification intensity and qualification barriers.
ISO 4413 and ISO 4414 govern hydraulic and pneumatic system safety across EU member states, while the EU Machinery Directive mandates risk assessment and CE conformity for cylinder-integrated equipment sold in Europe. The US OSHA machinery guarding standards and EPA spill-prevention rules shape product design and containment requirements for hydraulic systems deployed in American industrial and mobile applications. Stakeholders must track how regional carbon-border adjustments and energy-efficiency codes recalibrate the total-cost equation between hydraulic and electrified actuation alternatives.
Market Dynamics
Electrohydraulic actuator architectures are bifurcating competitive positioning in factory automation, forcing established hydraulic specialists to recalibrate R&D allocation between traditional fluid power and servo-electric hybrids.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE conformity requirements for risk assessment in cylinder-integrated equipment are accelerating replacement cycles across German and Italian OEM supply chains.
- Construction machinery electrification:Hybrid excavators and wheel loaders in China's eastern manufacturing corridor demand compact electrohydraulic cylinders with integrated position feedback.
- ISO 4413 energy-efficiency standards:Leakage-rate specifications and test protocols are pushing hydraulic system redesigns toward sealed actuator technologies in EU member states.
Market Restraints
- Steel and nodular cast iron cost volatility:Cylinder barrel and piston rod input materials face price swings tied to scrap metal arbitrage and Chinese export duties.
- Seal compound supply concentration:Fluorocarbon and polyurethane elastomer formulations for high-pressure hydraulic applications depend on a limited German and Japanese supplier base.
- Servo-electric substitution threat:Ball screw and linear motor actuators are capturing position-critical applications below 50 kN force requirements in clean-room automation.
Strategic Opportunities
- India's PLI scheme for construction equipment:Domestic production incentives are drawing cylinder manufacturers toward joint ventures with local OEMs for excavator and backhoe loader supply.
- Remanufacturing and refurbishment channels:Mining operators in Australia and Canada are formalizing core exchange programs to extend cylinder service life and reduce total cost of ownership.
- Condition monitoring convergence:Integration of pressure transducers, IoT telemetry modules, and predictive analytics platforms creates recurring revenue streams in fleet-managed mobile equipment.
Industry Challenges
- Hydraulic fluid contamination control expertise:OEMs and integrators face acute shortages of technicians trained in ISO 4406 cleanliness code implementation and filtration system specification.
- Multi-standard certification timelines:Simultaneous pursuit of CE marking, OSHA compliance, and China Compulsory Certification for unified product platforms extends qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Power Cylinder Market |
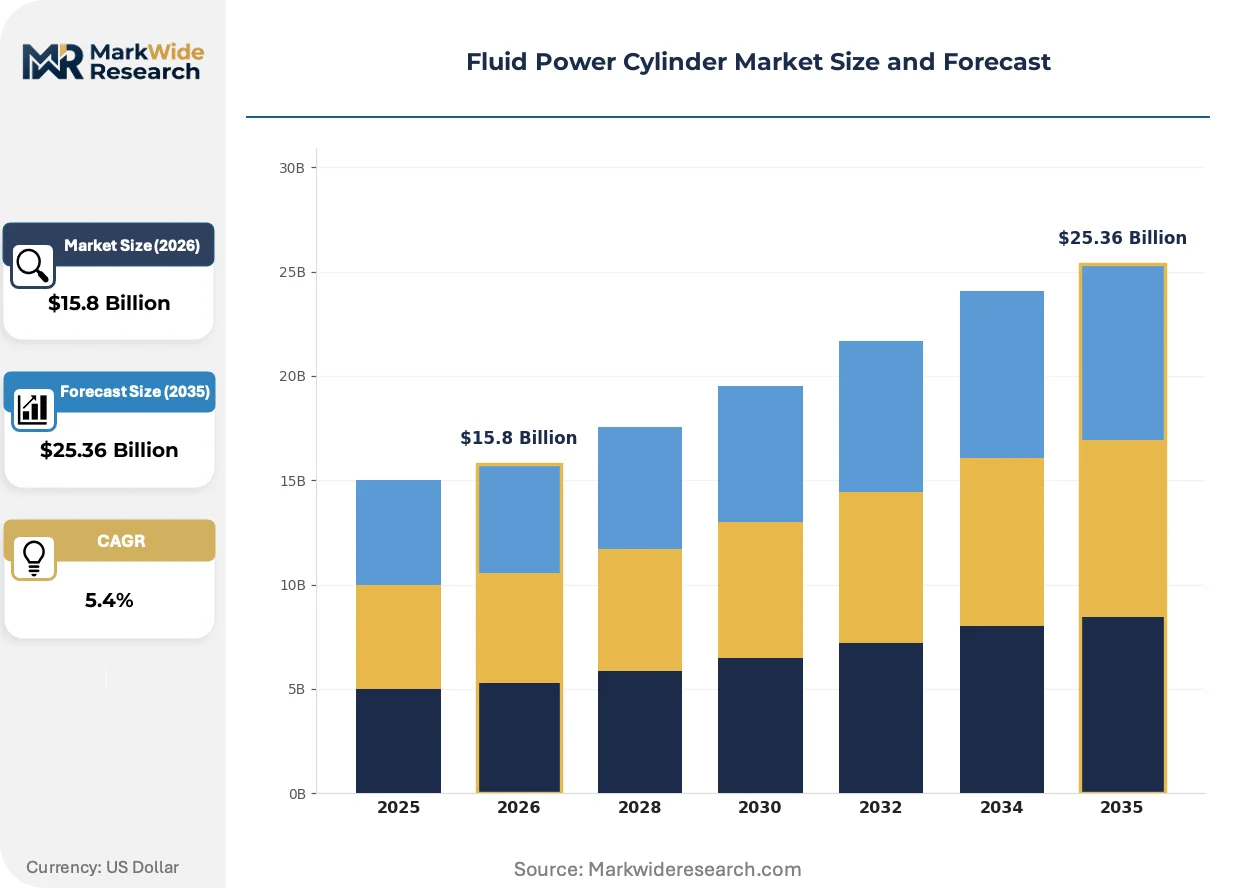
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting Cylinder, Double Acting Cylinder, Telescopic Cylinder, Tandem Cylinder, Rotary Cylinder Technology: Hydraulic, Pneumatic, Electrohydraulic, Electro-pneumatic, Magnetic Application: Construction Equipment, Material Handling Equipment, Agricultural Machinery, Marine Equipment, Automation Systems End User: Mining Operations, Factory Automation, Defense Systems, Packaging Plants, Food Processing Units |
| Companies Covered | Bosch Rexroth Corporation, Parker Hannifin Corp, Eaton Corporation, Festo SE & Co. KG, Danfoss A/S, SMC Corporation, HYDAC International GmbH, Caterpillar Inc., KYB Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Power Cylinder Market Shifts & Advancements
Digital hydraulics and electrified actuation architectures are compressing the traditional boundary between fluid power and motion control electronics, forcing component suppliers to acquire software competencies.
Electrohydraulic servo cylinders with integrated servo valves and linear encoders are displacing conventional valve-controlled systems in precision metal forming and injection molding applications. Automotive tier-one suppliers in Germany and Japan are specifying these packages for press synchronization tasks. The displacement is compressing margins for standalone valve manufacturers while rewarding actuator integrators with captive electronics capability.
REACH restrictions on perfluorinated compounds and EU F-Gas Regulation phase-down schedules are restricting hydraulic fluid formulations with high global warming potential. Equipment builders serving European markets are reformulating to bio-based esters and re-engineering seal compatibility. The regulatory pressure is most acute in mobile machinery exported from China and Turkey into EU member states.
After-sales service unbundling is fragmenting traditional distributor relationships in North American industrial corridors. End-users are sourcing replacement cylinders directly from manufacturer e-commerce portals while delegating installation and commissioning to regional hydraulic service shops. The channel shift is most visible among mid-sized plastic processing and packaging machinery operators seeking to compress MRO procurement cycles.
Fluid Power Cylinder Market Segmentation
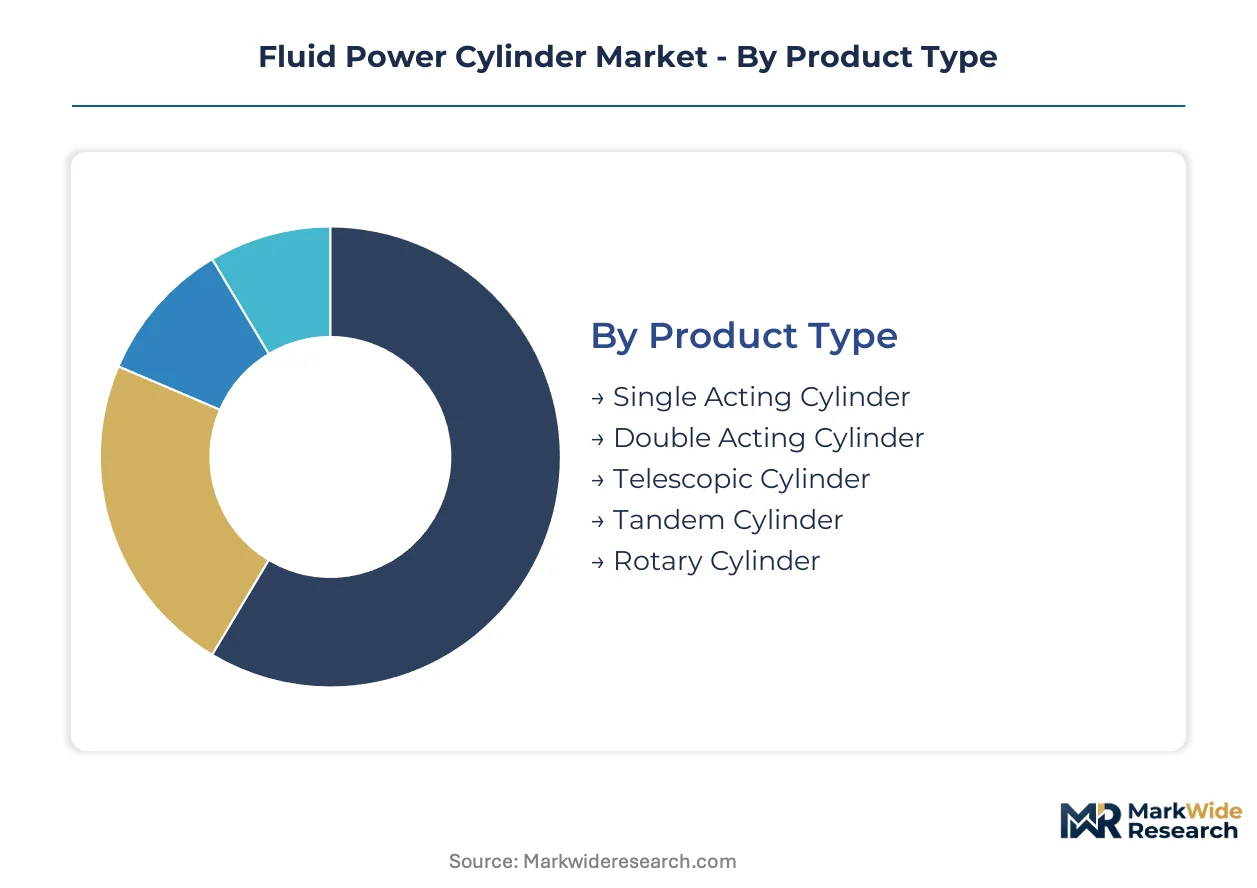
Fluid power cylinder procurement patterns diverge sharply across product architectures, actuation technologies, and end-use environments. Specification intensity varies by application risk profile and regulatory jurisdiction, creating distinct margin tiers within each segment category.
Product Type:
CE marking requirements under the EU Machinery Directive differentiate cylinder categories by safety-critical application scope and force-directionality characteristics.
- Double Acting Cylinder:Bidirectional force capability enables push-pull operation in excavator booms and injection molding presses. Construction OEMs in China's eastern manufacturing corridor specify these for hybrid wheel loader implementations where regenerative energy capture matters.
- Single Acting Cylinder:Unidirectional force output with spring-return or gravity-retraction mechanisms suits clamping and lifting tasks. Material handling equipment builders in Germany favor these for palletizing systems where cost minimization outweighs motion complexity requirements.
- Telescopic Cylinder:Nested multi-stage barrels deliver extended stroke from compact retracted lengths. Dump truck hoist mechanisms and aerial work platforms specify these for mobile equipment space constraints.
- Tandem Cylinder:Dual-piston configurations multiply force output without increasing bore diameter. Heavy press applications in automotive stamping plants deploy these for synchronized force distribution.
- Rotary Cylinder:Rack-and-pinion or vane mechanisms convert linear fluid pressure into rotary motion. Indexing tables and valve actuation systems in process industries integrate these for quarter-turn positioning tasks.
Established volume favors Double Acting Cylinder; emerging adoption favors Telescopic Cylinder.
Technology:
Cost tier stratification separates mature fluid power from electrified actuation alternatives, with capital intensity and energy efficiency as the primary dividing lines.
- Hydraulic:Mineral oil-based systems operating up to 350 bar dominate heavy-load applications. Mining operations in Australia specify these for hydraulic shovels where power density requirements exceed electrified alternatives.
- Electrohydraulic:Integrated servo valves and position feedback enable precise motion control. Factory automation buyers in Germany are expanding orders for these actuators to meet ISO 4413 energy-efficiency standards.
- Pneumatic:Compressed air systems near 10 bar serve clean-room and food-grade environments. Packaging plants deploy these where oil-free operation and rapid cycling speed take priority over force output.
- Electro-pneumatic:Proportional valve control bridges pneumatic simplicity with electronic positioning. Assembly line automation in Japan integrates these for adaptive gripping force adjustment.
- Magnetic:Magnetostrictive or solenoid-based actuation eliminates fluid media entirely. Semiconductor wafer handling systems specify these for contamination-sensitive environments.
Installed base concentration favors Hydraulic; steepest expansion trajectory favors Electrohydraulic.
Application:
Customer type differentiation separates mobile equipment OEMs from stationary industrial integrators, with aftermarket service intensity as the key structural variable.
- Construction Equipment:Excavators, wheel loaders, and cranes demand high-pressure cylinders with corrosion-resistant rod coatings. OEMs in China's eastern manufacturing corridor are localizing production to serve domestic infrastructure investment cycles.
- Automation Systems:Precision motion control for robotics and assembly lines requires integrated sensor feedback. German automotive tier-one suppliers specify electrohydraulic packages for press synchronization tasks.
- Material Handling Equipment:Forklifts and conveyor systems prioritize cycle speed and maintenance accessibility. Distribution centers in the US specify these for warehouse automation retrofits.
- Agricultural Machinery:Tractor implements and harvesters expose cylinders to dust, moisture, and chemical contaminants. Brazilian equipment builders source these for sugarcane harvester hydraulic systems.
- Marine Equipment:Offshore platforms and shipboard systems require corrosion-resistant materials and subsea sealing competence. Norwegian oilfield service companies qualify these for subsea BOP control systems.
Aftermarket revenue concentration favors Construction Equipment; specification upgrade intensity favors Automation Systems.
End User:
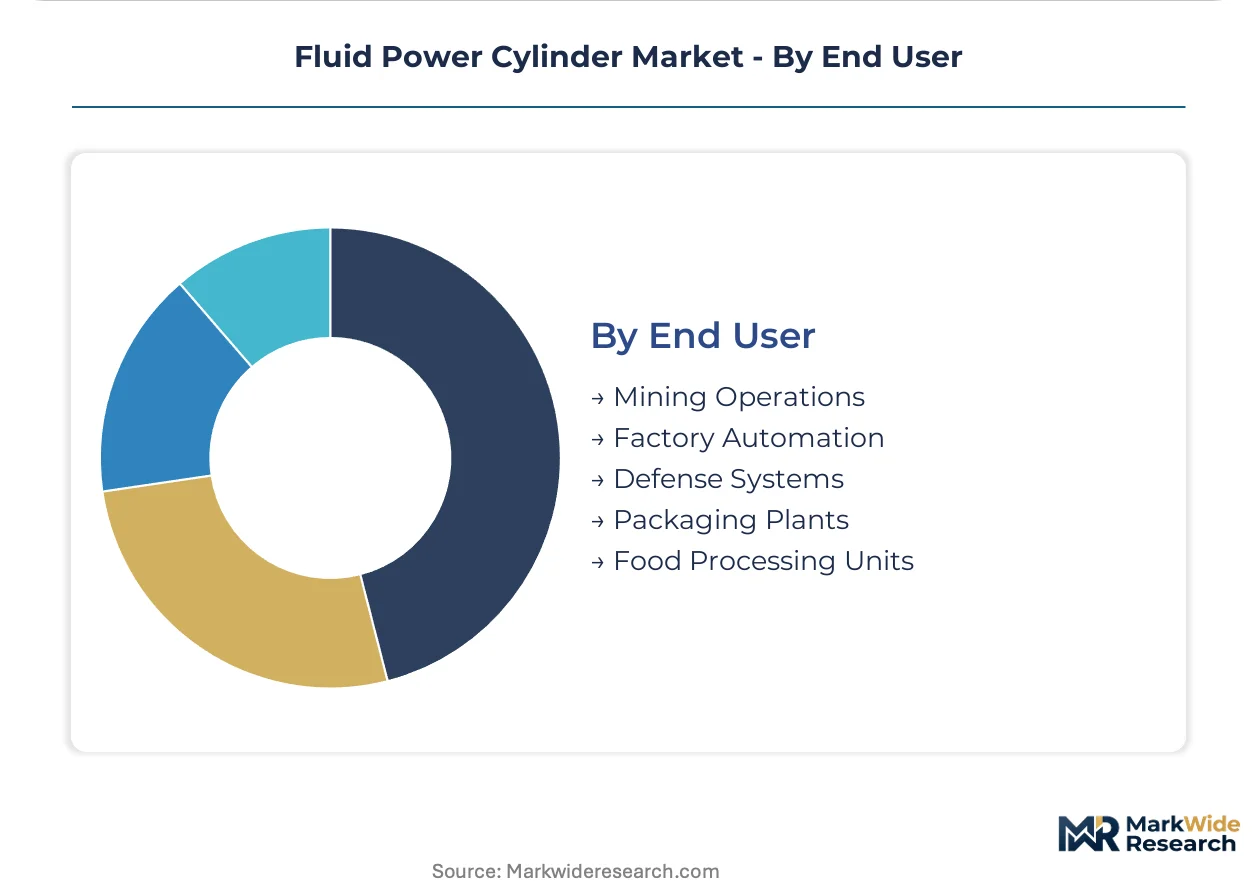
Margin structure varies by qualification barrier height and contract duration, with defense and mining offering the most defensible pricing power.
- Mining Operations:Underground and open-pit extraction equipment subjects cylinders to abrasive contamination and shock loading. Australian operators formalize core exchange programs to extend cylinder service life and reduce total cost of ownership.
- Defense Systems:Armored vehicle suspension and weapon positioning systems demand MIL-spec qualification and traceability. These applications carry extended certification timelines and captive supplier relationships.
- Factory Automation:Clean-room and precision assembly environments specify low-friction seals and stainless steel construction. Japanese electronics manufacturers integrate these for flat-panel display production lines.
- Packaging Plants:High-speed filling and sealing machinery requires rapid-cycle pneumatic actuation. US food and beverage processors source these for line speed upgrades.
- Food Processing Units:USDA and FDA compliance mandates sanitary design with clean-in-place capability. Poultry and dairy processors specify these for washdown environments.
Contract duration stability favors Defense Systems; condition monitoring penetration favors Mining Operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing specification premiums for ISO 4413-compliant electrohydraulic systems. Chinese construction OEMs operate at the opposite extreme, driving localization mandates to compress landed costs.
Germany
Factory automation buyers in Stuttgart and Munich are expanding orders for electrohydraulic actuators with integrated position feedback. The EU Machinery Directive mandates CE conformity and risk assessment for cylinder-integrated equipment sold across EU member states. Bosch Rexroth Corporation leverages captive foundry capacity in Lohr am Main to control cost structures across hydraulic actuator lines.
China
OEMs in the eastern manufacturing corridor around Shanghai and Suzhou are localizing cylinder production for hybrid excavators and wheel loaders. The country's dual carbon goals and MIIT energy-efficiency codes are recalibrating procurement criteria toward electrified actuation alternatives. Construction machinery electrification is concentrating demand for compact electrohydraulic cylinders with regenerative energy capture.
United States
Distribution centers in Chicago and Dallas specify material handling cylinders for warehouse automation retrofits. OSHA machinery guarding standards and EPA spill-prevention rules shape product design and containment requirements for hydraulic systems. Parker Hannifin Corp anchors its position through extensive distribution networks spanning North American industrial corridors.
Japan
Automotive tier-one suppliers in Nagoya and Toyota City specify electrohydraulic servo cylinders for press synchronization tasks. METI industrial efficiency guidelines and JIS standards govern pneumatic system performance in clean-room automation environments. SMC Corporation exemplifies pneumatic specialization for electronics manufacturing and flat-panel display production lines.
Australia
Mining operators in Western Australia's Pilbara region formalize core exchange programs to extend cylinder service life. The country's national mining safety regulator enforces equipment qualification protocols for hydraulic shovels in open-pit extraction. HYDAC International GmbH occupies a position among specialists serving contamination control and filtration system requirements.
Fluid Power Cylinder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the fluid power cylinder landscape. The upper tier commands cost advantages through captive foundry operations and machining capacity, while mid-scale fabricators compete on application-specific engineering. Three archetypes dominate: diversified industrial conglomerates with fluid power divisions, dedicated pneumatic or hydraulic specialists, and construction equipment OEMs with verticalized actuator production. Competitive moves center on geographic expansion through joint ventures and technology licensing for electrohydraulic integration.
Among Germany-based diversified industrial groups, Bosch Rexroth Corporation and Festo SE & Co. KG exemplify contrasting specialization strategies—one anchored in hydraulic system integration, the other in pneumatic automation for clean-room environments. Eaton Corporation represents the North American industrial conglomerate archetype with broad energy management and hydraulics exposure. These three occupy positions that illustrate how geographic origin and historical capability bases shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Bosch Rexroth Corporation |
| Parker Hannifin Corp |
| Eaton Corporation |
| Festo SE & Co. KG |
| Danfoss A/S |
| SMC Corporation |
| HYDAC International GmbH |
| Caterpillar Inc. |
| KYB Corporation |
| Others |
Supply & Pricing Matrix
CE marking requirements under the EU Machinery Directive gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant fabricators while rewarding integrated manufacturers with captive certification expertise. Factory automation buyers in Germany absorb specification premiums for ISO 4413-compliant electrohydraulic systems, whereas construction OEMs in China's eastern manufacturing corridor drive localization mandates to compress landed costs.
Pricing Analysis
After-sales revenue tiers spanning replacement cylinders, seal kits, and field service contracts drive lifetime value across the installed base. Pricing stratifies across premium certified, standard industrial, and economy unbranded tiers, with CE marking and MIL-spec qualification as the primary differentiation levers. Cost compression in economy-grade hydraulic cylinders intensifies because Chinese OEMs are internalizing production for hybrid excavator programs. Mining operations in Australia demonstrate the lowest price sensitivity due to specification intensity and downtime costs, while packaging plants in the US exhibit acute sensitivity to per-unit procurement cycles.
Supply Chain Analysis
Strait of Malacca transit routes and Shanghai port congestion expose cylinder supply chains to logistics chokepoint vulnerability. Manufacturing concentrates in Germany, China, and Japan, with nodular cast iron bar stock and fluorocarbon seal compounds as critical input dependencies. Steel scrap arbitrage and Chinese export duties on ferrous raw materials introduce commodity price volatility that feeds through to cylinder barrel costs. Distribution runs through manufacturer-direct e-commerce portals and regional hydraulic service shops, fragmenting traditional distributor relationships in North American industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrohydraulic actuator architectures fragment competitive positioning, creating niches for specialists with captive electronics integration and software competencies.
For Market Incumbents: Compound defensive positioning through backward integration into seal compound formulation and captive foundry capacity expansion in Germany. Servo-electric substitution threats below 50 kN force requirements demand accelerated R&D allocation toward hybrid electrohydraulic systems. Certification investment in simultaneous CE marking, OSHA compliance, and China Compulsory Certification defends margin pools in defense and mining end-use segments. For New Entrants and Emerging Players: Differentiate on condition monitoring convergence by integrating pressure transducers and IoT telemetry modules for fleet-managed mobile equipment. India's PLI scheme for construction equipment presents the most penetrable geography, with joint venture structures as the optimal go-to-market angle for excavator and backhoe loader supply. Remanufacturing and refurbishment channels in Australian mining operations offer white-space revenue streams with lower qualification barriers than OEM supply. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules and REACH restrictions on perfluorinated compounds reshape the acquisition landscape toward targets with bio-based hydraulic fluid compatibility and re-engineered seal portfolios. Long-term viability centers on electrohydraulic integration capability and software-defined motion control competencies. Vertically integrated mid-cap specialists with captive machining capacity represent the priority acquisition archetype. The signal to watch is OEM procurement shifts toward unified product platforms requiring multi-standard certification.| Strategic Initiative | Industry Significance |
|---|---|
| Electrohydraulic Integration Investment | Automotive tier-one suppliers in Germany specify servo cylinders with integrated linear encoders for press synchronization. |
| Remanufacturing Channel Development | Australian mining operators formalize core exchange programs to extend cylinder service life and reduce ownership costs. |
| Joint Venture Localization | India's PLI scheme draws cylinder manufacturers toward partnerships with domestic OEMs for construction equipment supply. |
| Condition Monitoring Platform Launch | Integration of predictive analytics creates recurring revenue streams in fleet-managed mobile equipment across mining corridors. |
| Bio-Based Fluid Compatibility Program | REACH restrictions force reformulation to ester-based hydraulic fluids for mobile machinery exported into EU member states. |
Research Methodology
Operator-level perspectives from maintenance directors at mining operations, plant engineers at automotive stamping facilities, OEM procurement teams at construction equipment manufacturers, and aftermarket service heads at hydraulic distributors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data, ISO certification registries, and EU Machinery Directive compliance databases. Bottom-up demand modeling and top-down supply capacity estimates underwent cross-triangulation to resolve segmentation boundaries.
Sensitivity analysis across steel price scenarios, electrification adoption curves, and regulatory enforcement timelines tested forecast robustness throughout the projection horizon. Segmentation dimensions modeled include product architecture, actuation technology, application environment, and end-user risk profile. CAGRs derived from installed base turnover rates, replacement cycle compression, and technology substitution elasticity. Forecast inputs incorporated OEM localization mandates in China, India's PLI scheme uptake, and EU carbon-border adjustment implementation.
Material uncertainties — steel and nodular cast iron cost volatility, seal compound supply concentration, and servo-electric substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding ISO 4413 enforcement consistency, MIIT energy-efficiency code adoption in China, and mining capital expenditure cycles. Practitioners should keep alternative scenarios live as electrohydraulic technology cost curves and regional carbon-border adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Air Heated Vaporizer Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Actuators and Valves Market
Valves
Rising Stem Ball Valve Market
Valves
North America Butterfly Valve Market
Valves
Motorized Valves Market
Valves
Subsea Control System Market
Valves
Global Valves in Chemical Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Pressure Reducing Valve Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Global Globe Valve Market
Valves
Global Plug Valve Market
Valves
Global Marine Actuators and Valves Market
Valves
Aerospace Valves Market
Valves
Refrigeration Valves Market