
 Subsea Control System Market | 2026-2036
Subsea Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Control System Market Analysis
Higher-integrity hydraulic and all-electric specification tiers is unwinding legacy procurement patterns across offshore developments. TechnipFMC leverages integrated system design to anchor its position in deepwater project awards. Baker Hughes sustains technology leadership through all-electric actuation R&D. Aker Solutions specializes in modular control architectures for harsh-environment fields.
A subsea control system comprises distributed hydraulic and electric power units, umbilical terminations, and master control stations operating at depths exceeding 3,000 meters to direct subsea production equipment. These systems manage wellhead chokes, subsea manifolds, and chemical injection skids through multiplexed electro-hydraulic signals. Umbilical Systems and Control Modules together represent the core revenue pool, with integrated umbilical lines capturing premium pricing due to combined power, signal, and chemical conveyance requirements. Deepwater Solutions within the Technology dimension are outpacing shallow-water alternatives as operators push into frontier basins with pressure ratings above 15,000 psi.
API standards and NORSOK U-001 frameworks govern hardware qualification and functional safety for subsea control equipment in the US and Norwegian sectors. Brazil's national petroleum regulator enforces local content requirements that shape supplier selection for pre-salt developments. Stakeholders must weigh all-electric transition timelines against the installed base of electro-hydraulic infrastructure when committing capital to next-generation control architectures.
Market Dynamics
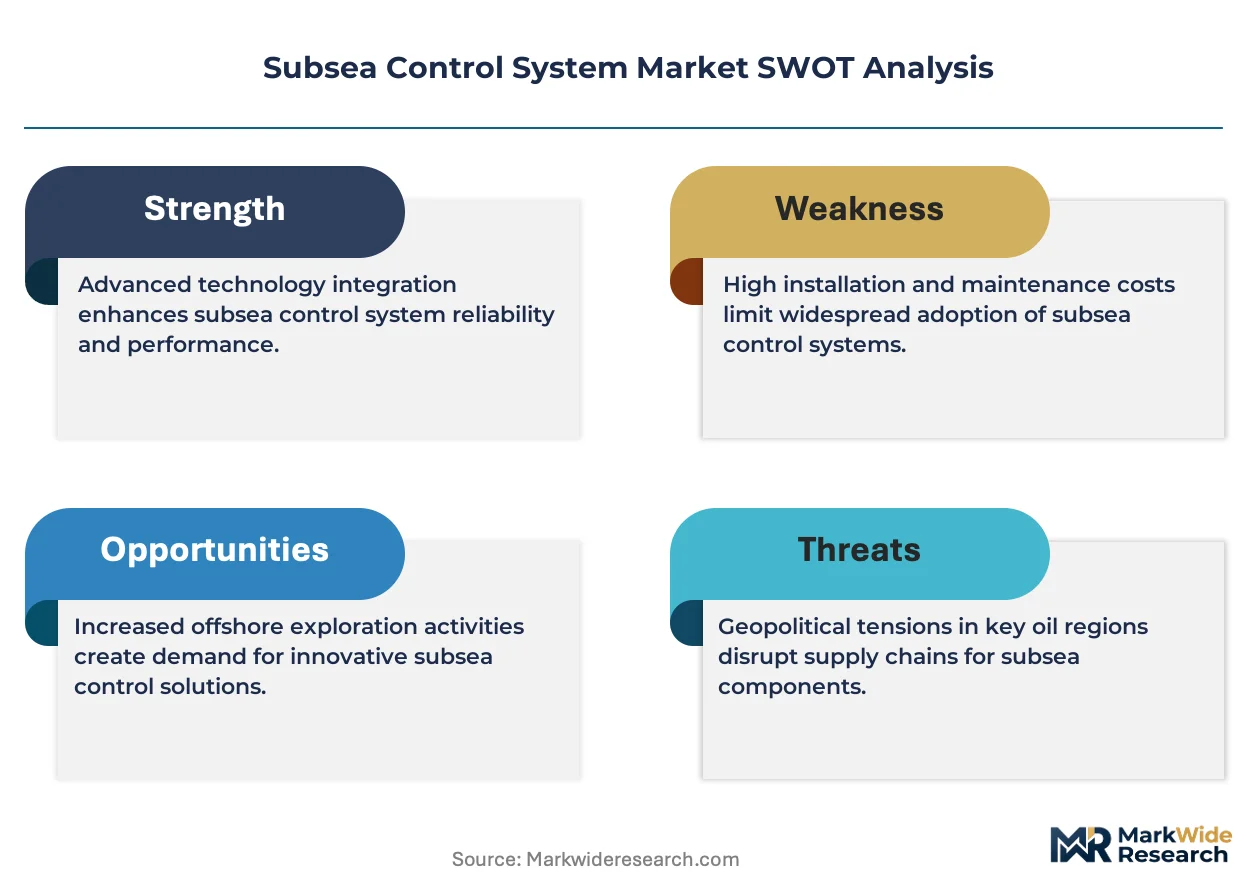
The transition from electro-hydraulic to all-electric subsea architectures is compressing qualification timelines while forcing suppliers to maintain dual-capability production lines. API 17F and ISO 13628-6 certification upgrades are redrawing competitive barriers as operators in Brazil's pre-salt basins demand higher-integrity specifications.
Growth Catalysts
- Pre-salt basin expansion:Brazil's national petroleum regulator enforces stringent local content rules that accelerate integrated control system deployment in ultra-deepwater fields off the country's southeastern coast.
- API 17F certification tightening:Hardware qualification protocols are elevating specification tiers across Gulf of Mexico developments, pushing operators toward higher-reliability umbilical and control module configurations.
- NORSOK U-001 adoption:Norwegian North Sea operators are mandating functional safety frameworks that favor modular, redundant control architectures in harsh-environment installations.
Market Restraints
- Specialized alloy supply concentration:High-performance nickel-based alloys for deepwater pressure vessels concentrate among a limited supplier base, creating input cost volatility and lead time uncertainty.
- Electro-hydraulic installed base lock-in:Decades of capital deployment in existing subsea infrastructure create technical and economic barriers to all-electric retrofit at producing fields.
- Brazilian local content thresholds:ANP-mandated domestic sourcing requirements extend project timelines and limit supplier flexibility for international system integrators.
Strategic Opportunities
- West African frontier basins:Underexplored deepwater provinces off Angola and Nigeria present first-mover advantages for integrated control system providers with pre-salt project experience.
- All-electric and digital twin convergence:Real-time asset monitoring combined with electric actuation enables predictive maintenance models that reduce subsea intervention frequency.
- Lease-operate contracting models:Equipment-as-service arrangements are emerging in Norwegian sector developments, transferring capital burden from operators to system suppliers.
Industry Challenges
- Multidisciplinary engineering talent scarcity:Deepwater control system design requires simultaneous expertise in high-pressure hydraulics, subsea electronics, and functional safety engineering.
- ISO 13628-6 recertification complexity:Updated hardware qualification standards demand extensive retesting of existing product lines, compressing R&D bandwidth for next-generation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Control System Market |
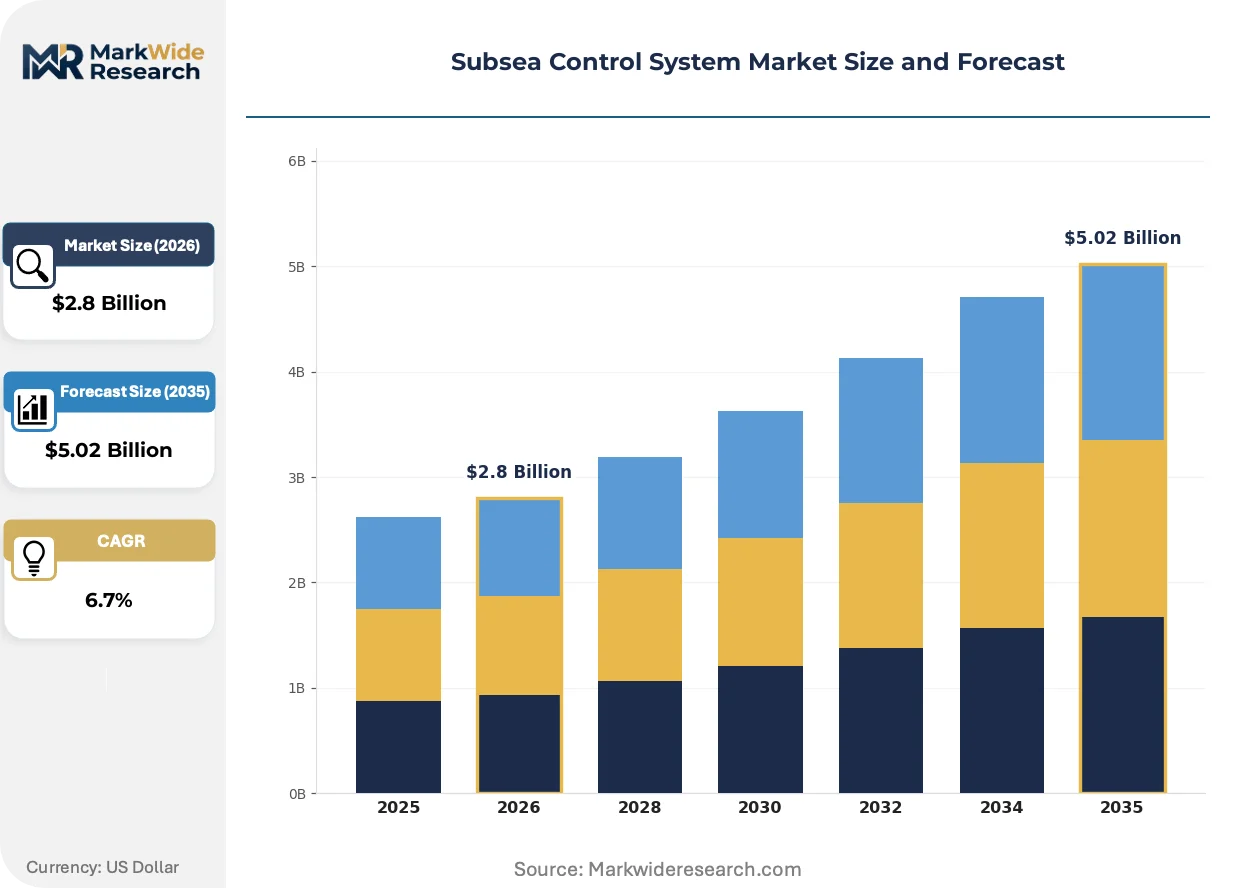
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Umbilical Systems, Control Modules, Subsea Hardware, Sensors End User: Oil & Gas Producers, Subsea Contractors, Engineering Firms, Service Providers Deployment Model: Onshore Facilities, Offshore Platforms, Floating Vessels, Remote Locations Technology: Deepwater Solutions, Integrated Systems, Communication Protocols, Monitoring Tools |
| Companies Covered | Baker Hughes, Oceaneering International, TechnipFMC, Proserv, Dril-Quip, Aker Solutions, Halliburton, Weatherford International, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Control System Market Emerging Trajectories
Subsea control technology is splitting into parallel development tracks as operator risk appetites diverge between frontier basin exploration and mature field optimization. Hardware innovation, regulatory stringency, and contracting model evolution are simultaneously reshaping competitive positioning.
All-electric subsea actuation is bifurcating the installed base between greenfield developments specifying fully electric architectures and brownfield assets locked into electro-hydraulic infrastructure. Norwegian operators in the Johan Sverdrup cluster are deploying all-electric trees at scale, while Gulf of Mexico independents prioritize incremental electro-hydraulic upgrades. The technology divergence is compressing supplier margins as dual product lines strain engineering resources and manufacturing flexibility.
ISO 13628-6 and API 17F harmonization efforts are tightening functional safety requirements for subsea control equipment across North Atlantic and South Atlantic basins. Hardware qualification protocols now demand extended pressure cycling tests and accelerated corrosion assessments that extend product development timelines. Deepwater projects in Brazil and Norway are absorbing these compliance costs through integrated contracting structures that bundle certification responsibility with system suppliers.
Integrated service contracts are displacing discrete equipment procurement as national oil companies consolidate vendor relationships. Petrobras and Equinor are bundling umbilical supply, installation, and twenty-year maintenance into single-source agreements that favor vertically capable system integrators. This concentration is most visible in Brazil's pre-salt developments, where local content rules compound the preference for full-scope suppliers with established domestic engineering presence.
Subsea Control System Market Segmentation
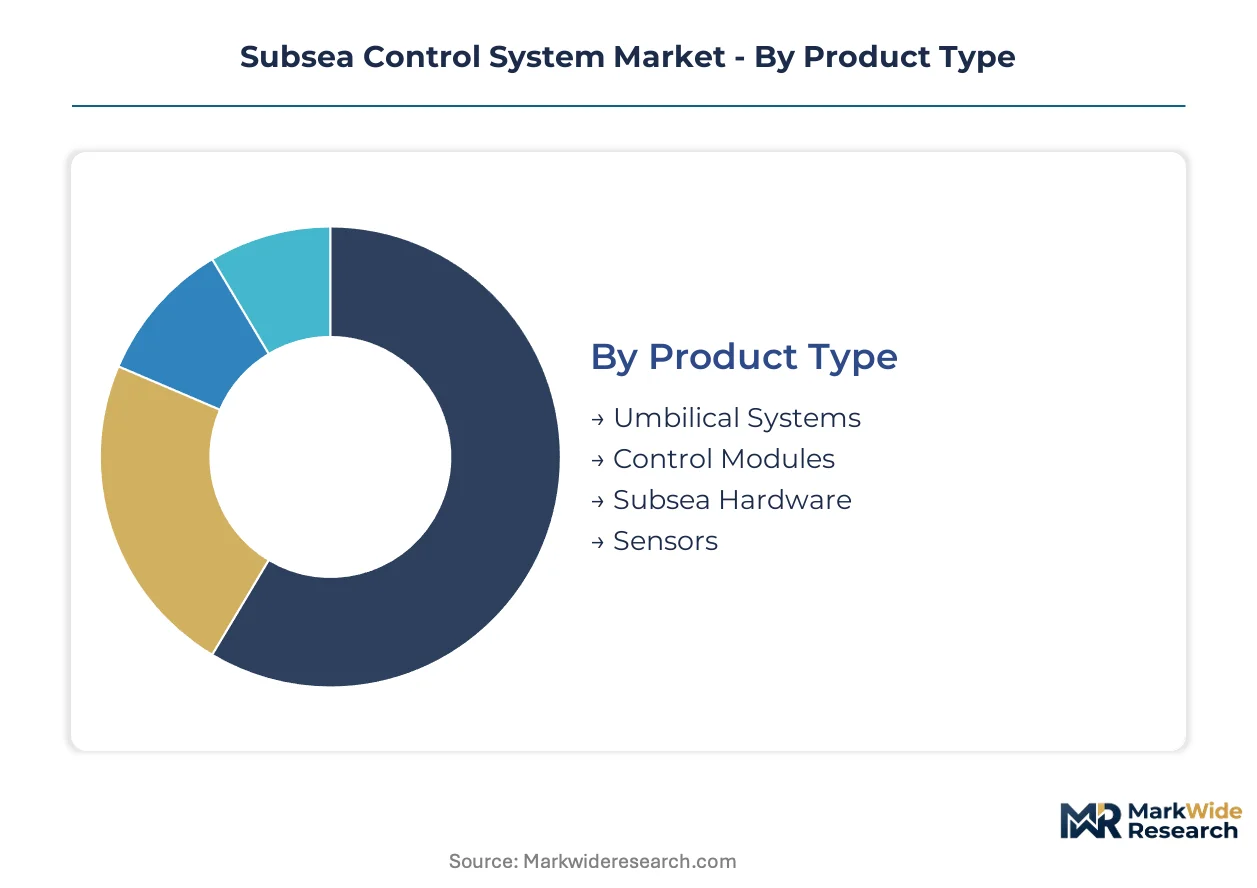
Subsea control system procurement splits across hardware specifications, operator risk profiles, and deployment complexity tiers. Regulatory frameworks in Brazil, Norway, and the Gulf of Mexico impose divergent certification requirements that reshape segment prioritization for integrated suppliers.
Product Type:
API 17F and ISO 13628-6 certification tiers differentiate hardware qualification pathways, with pressure-rated umbilical assemblies facing the most stringent testing protocols.
- Umbilical Systems:Bundled power, signal, and chemical conveyance lines rated for 15,000 psi-plus operating environments. Demand clusters around Brazil's pre-salt developments where combined hydraulic-electric umbilicals anchor integrated field architectures.
- Control Modules:Distributed electro-hydraulic and all-electric valve actuation units operating at depths exceeding 3,000 meters. Norwegian North Sea operators specify redundant modular configurations under NORSOK U-001 functional safety mandates.
- Subsea Hardware:Pressure vessels, connectors, and distribution assemblies fabricated from nickel-based alloys for ultra-deepwater service.
- Sensors:Temperature, pressure, and flow monitoring devices multiplexed through subsea control networks.
Established volume favors Umbilical Systems; emerging adoption favors Control Modules as all-electric architectures displace legacy electro-hydraulic infrastructure.
End User:
Capital commitment scale and technical integration risk determine procurement authority distribution across the value chain.
- Oil & Gas Producers:National oil companies and international majors specifying integrated control architectures for greenfield developments. Petrobras bundles twenty-year service contracts with equipment procurement, compressing supplier margins while locking in maintenance revenue streams.
- Subsea Contractors:Installation and commissioning specialists absorbing hardware qualification liability through integrated project delivery. Gulf of Mexico independents rely on contractor-managed procurement to navigate API 17F recertification complexity.
- Engineering Firms:Front-end design consultants shaping control system specifications during field development planning.
- Service Providers:Maintenance and intervention contractors operating leased equipment under equipment-as-service arrangements.
Contracting concentration favors Oil & Gas Producers; margin expansion favors Subsea Contractors as integrated service models transfer operational risk.
Deployment Model:
Logistics complexity and intervention accessibility drive specification divergence between fixed and mobile production infrastructure.
- Offshore Platforms:Fixed installations with direct surface access for control system maintenance and umbilical termination. Norwegian Johan Sverdrup cluster deployments favor platform-tied architectures with simplified intervention logistics.
- Floating Vessels:FPSO and drillship-mounted production systems requiring dynamic umbilical management and motion-compensated control interfaces. Brazil's pre-salt fields anchor demand for vessel-integrated control systems with twenty-year service horizons.
- Onshore Facilities:Master control stations and hydraulic power units positioned at coastal bases.
- Remote Locations:Satellite well tiebacks and subsea boosting installations with minimal surface presence.
Investment scale favors Offshore Platforms; frontier expansion favors Floating Vessels as operators push into ultra-deepwater provinces off West Africa.
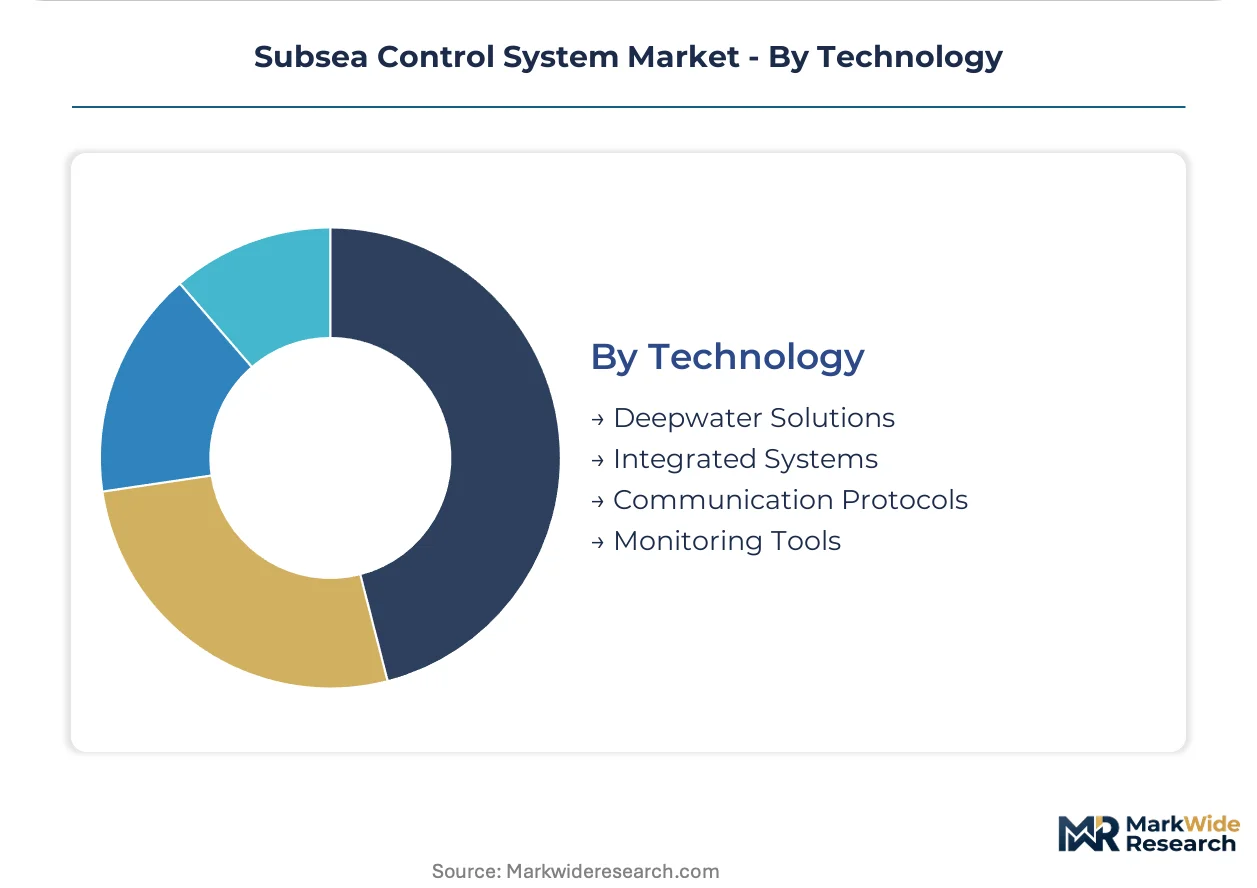
Technology:
Architecture selection locks in decades of operational constraints, forcing operators to weigh all-electric transition timelines against installed base compatibility.
- Deepwater Solutions:Pressure-rated control equipment specified for 3,000-meter-plus water depths and 15,000 psi wellhead pressures. Brazil's pre-salt basins absorb premium pricing for deepwater-qualified hardware as ANP local content rules compound specification complexity.
- Integrated Systems:Unified hydraulic, electric, and communication architectures delivered through single-source contracting. Norwegian operators mandate integrated configurations to streamline NORSOK U-001 compliance and reduce interface risk.
- Communication Protocols:Multiplexed electro-hydraulic signal standards and emerging all-electric data transmission specifications.
- Monitoring Tools:Real-time asset performance tracking enabling predictive maintenance and subsea intervention optimization.
Revenue concentration favors Deepwater Solutions; technology transition favors Integrated Systems as operators consolidate vendor relationships under bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian operators absorb the steepest price premiums for deepwater-qualified hardware, while Gulf of Mexico independents negotiate hardest on electro-hydraulic retrofits. Norwegian buyers prioritize functional safety over unit cost. West African frontier developments trade specification certainty for supplier flexibility.
United States
Gulf of Mexico independents drive demand for API 17F recertification services as aging infrastructure requires hardware upgrades. The Bureau of Safety and Environmental Enforcement enforces tightened well control standards following post-Macondo regulatory reforms. Houston anchors the supplier ecosystem, with engineering clusters concentrated along the Ship Channel corridor.
Brazil
Pre-salt basin expansion absorbs integrated control architectures rated for 15,000 psi wellhead pressures. ANP-mandated local content thresholds reshape procurement timelines, forcing international suppliers to establish domestic engineering presence. The Santos Basin cluster off São Paulo's coast concentrates deployment activity for ultra-deepwater FPSO tiebacks.
Norway
Johan Sverdrup cluster operators specify all-electric subsea trees at commercial scale, validating electric actuation for harsh-environment North Sea installations. NORSOK U-001 functional safety frameworks mandate redundant modular configurations. Stavanger and Bergen harbor subsea engineering centers directing specification standards across the Norwegian Continental Shelf.
United Kingdom
North Sea decommissioning schedules compress maintenance windows for legacy electro-hydraulic infrastructure. The Health and Safety Executive enforces updated subsea safety case requirements for aging platform-tied developments. Aberdeen maintains its position as the primary subsea contracting hub despite field maturity pressures.
Nigeria
Deepwater frontier exploration off the Niger Delta delta creates first-mover opportunities for integrated system providers with pre-salt project credentials. The national petroleum regulator has issued draft local content guidelines modeled on Brazilian ANP frameworks. Lagos serves as the commercial coordination point for offshore developments in adjacent Angolan and Ghanaian waters.
Subsea Control System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated system designers commanding premium positioning against modular component specialists. The market structure concentrates around full-scope suppliers capable of bundling umbilical supply, installation, and long-term maintenance under single-source contracts. Three archetypes dominate: vertically integrated energy technology conglomerates, pure-play subsea engineering specialists, and diversified oilfield services operators with subsea divisions. Competitive moves center on integrated service contract capture and electric actuation R&D acceleration.
Among diversified energy technology providers, Baker Hughes and Schlumberger occupy positions spanning multiple oilfield service verticals including subsea control hardware. TechnipFMC exemplifies the integrated subsea specialist archetype, with corporate lineage reflecting merged engineering and manufacturing capabilities. Aker Solutions represents the Nordic engineering specialist model, with Oslo-rooted heritage in modular control architectures for harsh-environment applications.
| Leading Market Players |
|---|
| Baker Hughes |
| Oceaneering International |
| TechnipFMC |
| Proserv |
| Dril-Quip |
| Aker Solutions |
| Halliburton |
| Weatherford International |
| Schlumberger |
| Others |
Supply Flow & Price Mechanics
All-electric actuation substitution for legacy electro-hydraulic architectures is redrawing supply geography toward Norwegian engineering clusters while compressing pricing premiums for integrated system bundles. API 17F and ISO 13628-6 recertification costs simultaneously inflate qualification expenditures and filter supplier participation, tightening pricing power among vertically capable incumbents.
Pricing Analysis
Twenty-year maintenance and intervention service contracts capture lifetime value exceeding original equipment sale prices by substantial multiples. Pricing stratifies across API 17F certification tiers, with ultra-deepwater qualified hardware commanding substantial premiums over shallow-water alternatives, while volume scale and local content compliance in Brazil further differentiate transaction economics. Cost compression in electro-hydraulic retrofits is intensifying because Gulf of Mexico independents prioritize incremental upgrades over greenfield electric specifications. Subsea contractors demonstrate highest price sensitivity due to compressed margins on installation and commissioning scopes, whereas Petrobras and Equinor absorb premium pricing for integrated single-source arrangements.
Supply Chain Analysis
Norway and the United Kingdom anchor high-pressure connector and subsea electronics fabrication, while Brazil concentrates umbilical assembly capacity under ANP-mandated domestic sourcing rules. Nickel-based alloy pressure vessels draw from specialized foundries in Germany and Japan, with multiplexed control electronics sourcing from semiconductor suppliers in the United States and Taiwan. Single-source vulnerability concentrates around super-duplex stainless steel forging capacity for 15,000 psi-rated components. Distribution runs through integrated project delivery structures where TechnipFMC and Aker Solutions bundle manufacturing, installation, and long-term service under unified contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
All-electric subsea architecture adoption constitutes a high-growth disruption validated by NORSOK U-001 functional safety mandates accelerating electric tree deployment across the Johan Sverdrup cluster. Regulatory stringency is compressing qualification timelines while elevating capital barriers for supplier participation.
For Market Incumbents: Secure API 17F and ISO 13628-6 certification leadership through accelerated pressure cycling test investments, insulating against emerging all-electric specialists capturing Norwegian greenfield awards. Backward integration into nickel-based alloy supply and captive hydraulic power unit manufacturing defends margin position against input cost volatility from concentrated super-duplex forging suppliers. For New Entrants and Emerging Players: Predictive maintenance analytics and digital twin integration services represent underserved layers where incumbents under-serve brownfield optimization demand. West African frontier basins off Angola and Nigeria offer the most penetrable geography for integrated control system providers lacking established Brazilian engineering presence. Equipment-as-service contracting models provide the optimal go-to-market angle for transferring capital burden from NOCs to technology suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed subsea engineering specialists holding pre-salt project credentials but lacking all-electric R&D scale. Long-term viability centers on electric actuation transition completion and integrated service contract capture across the Norwegian and Brazilian contract pipelines. The signal to watch is ANP local content threshold relaxation permitting international supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| All-Electric Actuation R&D Acceleration | Validates electric tree deployment under NORSOK U-001 harsh-environment specifications. |
| Integrated Service Contract Capture | Bundles umbilical supply, installation, and twenty-year maintenance under single-source Petrobras arrangements. |
| API 17F Certification Investment | Elevates hardware qualification tiers for Gulf of Mexico recertification service demand. |
| Backward Integration into Alloy Supply | Captures nickel-based pressure vessel fabrication reducing exposure to German-Japanese foundry concentration. |
| Digital Twin Platform Development | Enables predictive maintenance models reducing subsea intervention frequency for FPSO operators. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings on certification timeline compression and local content enforcement patterns. Subsea project engineers at Petrobras and Equinor, control system procurement leads at Gulf of Mexico independents, and technical directors at integrated suppliers provided operational perspective. API 17F revision documentation, ANP local content rulings, NORSOK U-001 standards, and SEC filings from listed subsea service providers furnished secondary validation. Bottom-up project pipeline assessment and top-down equipment spend allocation were reconciled through iterative triangulation.
Sensitivity analysis tested forecast outputs against variation in pre-salt development cadence, all-electric adoption speed, and local content threshold stringency across the projection horizon. Segmentation dimensions modeled include product type, end user contracting authority, deployment model logistics complexity, and technology architecture selection. CAGRs were derived from equipment procurement schedules tied to sanctioned deepwater projects, with pressure rating tiers and water depth specifications serving as industry-specific volume drivers.
Underlying assumptions cover sustained oil price bands supporting ultra-deepwater sanctioning, with deviation risk concentrated in Brazilian regulatory enforcement intensity and alloy supply disruption. Forecasts reflect these documented conditions with acknowledged sensitivity to electric-hydraulic technology transition velocity. Recalibration cycles align with material shifts in ANP local content rulings and NORSOK standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Pipeline Safety Market
Valves
Battery Safety Valve Market
Valves
Emergency Shutdown Valves Market
Valves
Global Globe Valve Market
Valves
Aerospace Valves Market
Valves
Insulation Flanges Market
Valves
Global Gate Valve Market
Valves
Hybrid Valve Market
Valves
Vacuum Insulated Pipe Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Sanitary Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
Float Traps Market
Valves
Transmission Overload Protectors Market
Valves
Fluid Power Cylinder Market