
 Modified Soya Flour Market | 2026-2036
Modified Soya Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Soya Flour Market Outlook
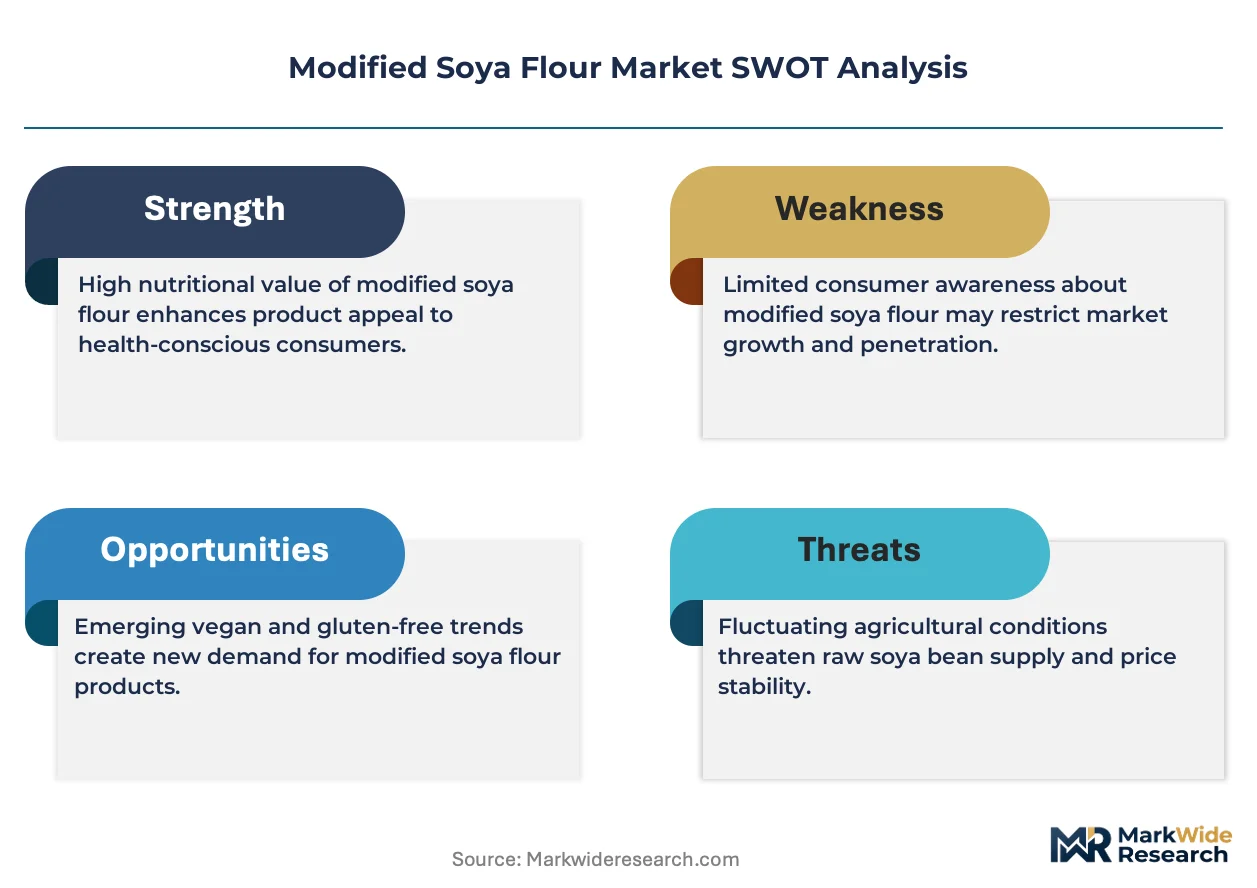
India is rewriting competitive dynamics in modified soya flour as domestic crushing capacity expands and local processors capture value that previously flowed to import channels. Archer Daniels Midland Company leverages its integrated oilseed crushing network across Gujarat and Maharashtra to secure cost-advantaged feedstock for flour modification. Cargill Incorporated sustains a differentiated position through specialized extrusion technology that produces textured soya flour with consistent hydration profiles for meat alternative applications. Bunge Limited anchors supply security through backward integration into Indian soya origination, giving it volume flexibility that traders without crush assets cannot match.
Modified soya flour consists of heat-treated, enzyme-modified, or extruded soy flour with adjusted protein dispersibility indices, fat content typically below 1%, and particle sizes calibrated to specific end-use rheology requirements; processors achieve functional modification through controlled thermal denaturation, enzymatic hydrolysis, or mechanical shear to impart emulsification, water binding, or texturizing properties in food systems. Textured and instant product types command the widest application breadth, with textured grades dominating volume in meat alternative formulations where chew structure replication determines product acceptance, while instant variants are gaining fastest in beverage and dairy alternative segments where cold-water dispersibility eliminates pre-hydration steps. Food grade specifications absorb the dominant share of value given stringent allergen management and identity preservation requirements, though feed grade volumes remain substantial as aquaculture and poultry sectors adopt soya protein concentrates.
The FDA enforces allergen labeling under FALCPA and preventive controls under FSMA, compelling modified soya flour processors to maintain validated sanitation protocols and lot traceability systems that add compliance cost but also create barriers against uncertified imports. India's FSSAI mandates fortification standards and contaminant limits for processed soya products sold into institutional feeding programs, channeling demand toward licensed manufacturers with laboratory testing capabilities. ISO 22000 and HACCP certifications function as baseline market access credentials across export-oriented supply chains, with buyers in Europe additionally requiring compliance with EFSA thresholds for pesticide residues and GMO adventitious presence. Stakeholders must monitor evolving thresholds for soya protein content claims and emerging regulatory scrutiny of novel texturizing processes that fall outside existing food additive classifications.
Market Dynamics
Modified soya flour supply chains are compressing around certified origination networks as FDA allergen enforcement and FSSAI fortification mandates force processors to document every transformation stage, eliminating spot-market arbitrage opportunities that previously sustained smaller traders.
Growth Catalysts
- FSMA Preventive Controls:The FDA's mandatory hazard analysis pushes food manufacturers toward validated suppliers with documented sanitation protocols, locking in volume commitments with certified processors.
- Enzymatic Hydrolysis Advancement:Controlled protease treatments now yield protein dispersibility indices calibrated for specific meat alternative textures, opening formulation flexibility that heat-modified flour cannot match.
- India:Government-backed school feeding programs and packaged food fortification mandates are pulling modified soya flour into institutional channels at volumes that justify dedicated crush-to-flour lines.
Market Restraints
- Soybean Price Volatility:Crush margin compression during drought cycles in Argentina and Brazil transmits directly to modified flour input costs, eroding processor pricing power.
- Allergen Labeling Friction:FALCPA mandates and EFSA precautionary thresholds force reformulation costs onto bakery and beverage brands, slowing adoption in label-sensitive categories.
- Pulse Protein Substitution:Pea and fava concentrates with cleaner allergen profiles are capturing share in premium meat alternative formulations where soya carries stigma.
Strategic Opportunities
- Indonesia:Nascent soya processing infrastructure and expanding instant noodle fortification programs create first-mover positioning for extrusion-capable suppliers.
- Cold-Water Dispersible Instant Grades:Beverage manufacturers seek flour that hydrates without pre-blending, eliminating equipment steps that currently constrain formulation trials.
- EU Green Deal Protein Strategy:Domestic protein crop incentives and import substitution targets favor European crush assets with modification capabilities over transatlantic suppliers.
Industry Challenges
- Identity Preservation Systems:Maintaining non-GMO and organic chain of custody through multiple thermal and mechanical processing stages demands capital-intensive segregation infrastructure.
- Extrusion Operator Shortage:Specialized knowledge of screw configuration, barrel temperature profiling, and die design for textured flour production concentrates among retiring technical cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Soya Flour Market |
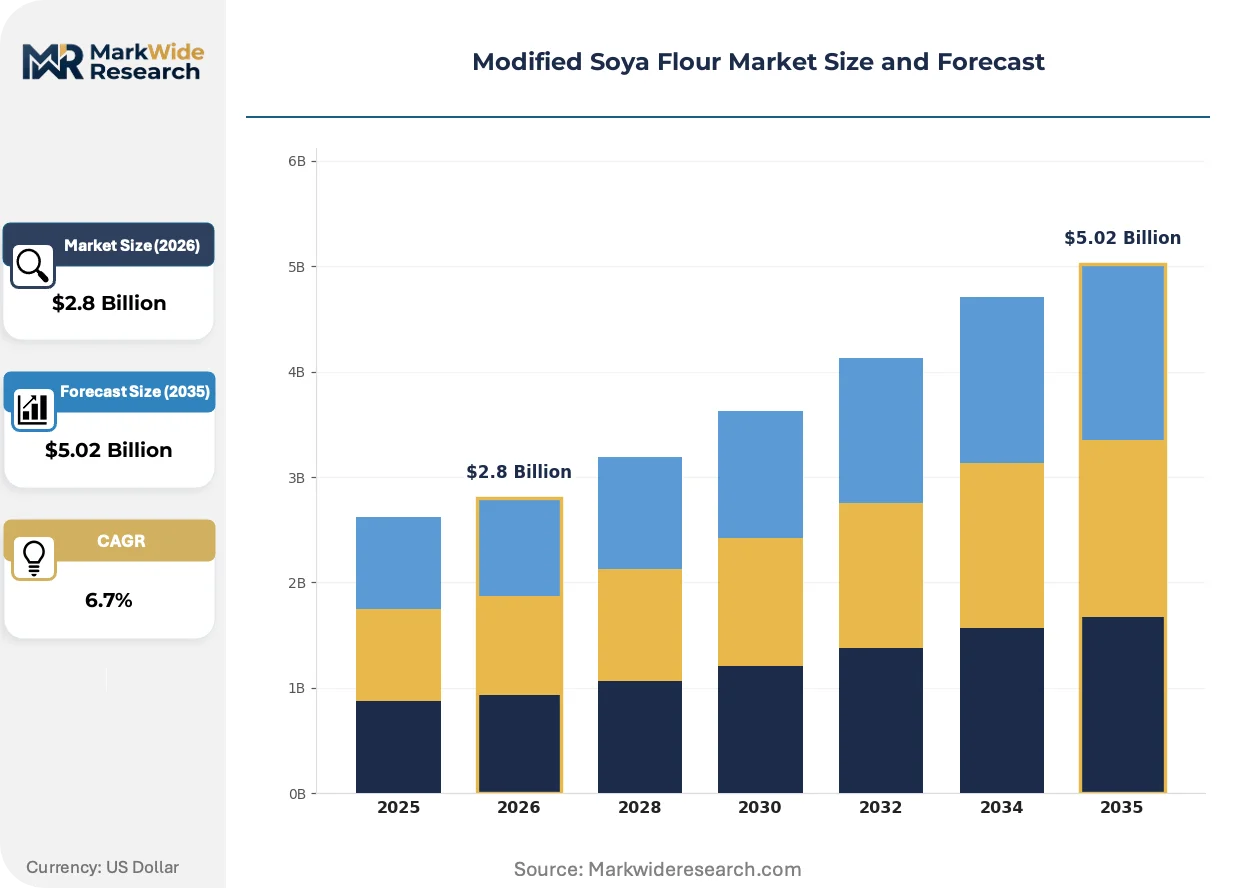
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured, Instant, Non-Textured, Fortified End Use: Baking, Snacks, Meat Alternatives, Dairy Alternatives Grade: Food Grade, Feed Grade, Industrial Grade, Premium Grade Packaging Type: Bulk Bags, Retail Packs, Pallets, Sachets |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, The Scoular Company, Associated British Foods, The Hain Celestial Group, Parrish and Heimbecker, Bunge Limited, ITC Limited, The Caremoli Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Soya Flour Market Strategic Shifts
Processing technology is converging with digital traceability systems to transform how modified soya flour is specified, audited, and priced across fragmented buyer bases.
Extrusion control systems are digitizing real-time monitoring of specific mechanical energy input and barrel temperature gradients, enabling batch-to-batch consistency that commodity flour cannot achieve. Meat alternative manufacturers in Germany and the Netherlands are specifying these digitally certified lots for premium product lines. The technology is digitizing quality assurance workflows, compressing the verification timeline from days to minutes and reducing rejected shipments.
REACH registration requirements for novel enzymatic processing aids are tightening substance authorization timelines for European modified flour producers. Manufacturers must now submit full toxicological dossiers for protease treatments that previously operated under generic food enzyme approvals. Small and mid-scale processors without regulatory affairs capacity are outsourcing compliance to specialized consultancies, adding cost layers that favor larger integrated suppliers.
Ingredient buyers are consolidating supplier panels around dual-certified vendors holding both ISO 22000 and FSSAI licenses, eliminating single-certification processors from consideration. Bakery and dairy alternative formulators in India are shifting from spot purchases to annual volume agreements with traceability guarantees. This concentration is most visible in Maharashtra and Gujarat, where crush-to-flour integrated assets can offer locked-in pricing against volatile soybean futures.
Modified Soya Flour Market Segmentation
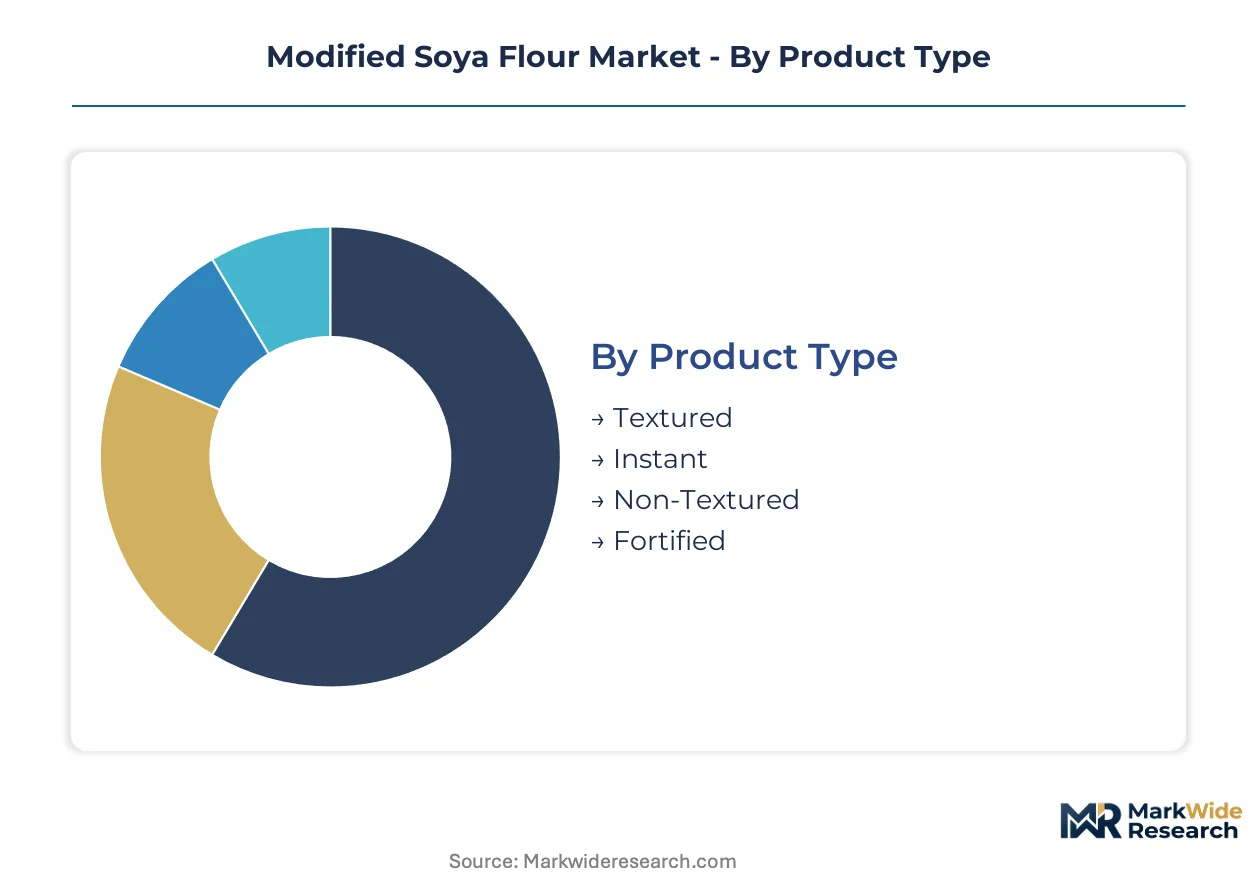
Modified soya flour specifications diverge sharply across application requirements, with protein dispersibility indices and particle size distributions determining suitability for specific food systems. Formulators select grades based on thermal stability needs, hydration kinetics, and allergen management protocols that vary by end-use channel.
Product Type:
Use-case spectrum spans chew-structure replication in meat alternatives through instant cold-water dispersibility in beverage applications.
- Textured:Extruded flour with calibrated density and fibrous structure replicates meat chew profiles in plant-based patties and nuggets. Meat alternative manufacturers in Germany and the Netherlands specify digitally certified lots with documented specific mechanical energy input for premium product lines.
- Instant:Enzyme-modified grades achieve cold-water dispersibility without pre-hydration, eliminating equipment steps in dairy alternative formulation. Beverage manufacturers seeking streamlined production are pulling these volumes into trial programs.
- Non-Textured:Standard heat-treated flour serves bakery dough conditioning and protein fortification at lower unit economics than specialized grades.
- Fortified:Micronutrient-enriched variants target government feeding programs with mandated iron, folic acid, and vitamin specifications.
Established volume favors Textured; emerging adoption favors Instant.
End Use:
Application margins track protein claim intensity and formulation complexity across commercial and artisan production channels.
- Baking:Dough conditioning and protein fortification in commercial pan bread and artisan loaves absorbs the largest volume share, with FDA FSMA preventive controls pushing manufacturers toward certified supply chains with documented sanitation protocols.
- Meat Alternatives:Textured flour with calibrated hydration profiles commands formulation flexibility premiums as extrusion technology advances enable precise chew structure replication.
- Snacks:Extruded puffs and protein-fortified crackers utilize modified flour for texture and shelf stability.
- Dairy Alternatives:Instant dispersible grades are gaining formulation trials in beverage applications where cold-water solubility eliminates pre-blending steps.
Volume concentrates in Baking; value expansion concentrates in Meat Alternatives.
Grade:
Certification tiers separate identity-preserved supply chains from commodity volumes in procurement decisions.
- Food Grade:Stringent allergen management and lot traceability systems satisfy FDA FALCPA labeling mandates and FSSAI fortification standards for institutional feeding programs.
- Feed Grade:Aquaculture and poultry sectors adopt soya protein concentrates as fish meal and antibiotic replacement strategies advance.
- Industrial Grade:Non-food applications in adhesives and paper sizing utilize lower-purity modified flour at reduced specification thresholds.
- Premium Grade:Organic and non-GMO identity preservation through multiple processing stages commands dedicated segregation infrastructure and documentation premiums.
Procurement panels are consolidating around dual-certified Food Grade suppliers with both ISO 22000 and FSSAI licenses.
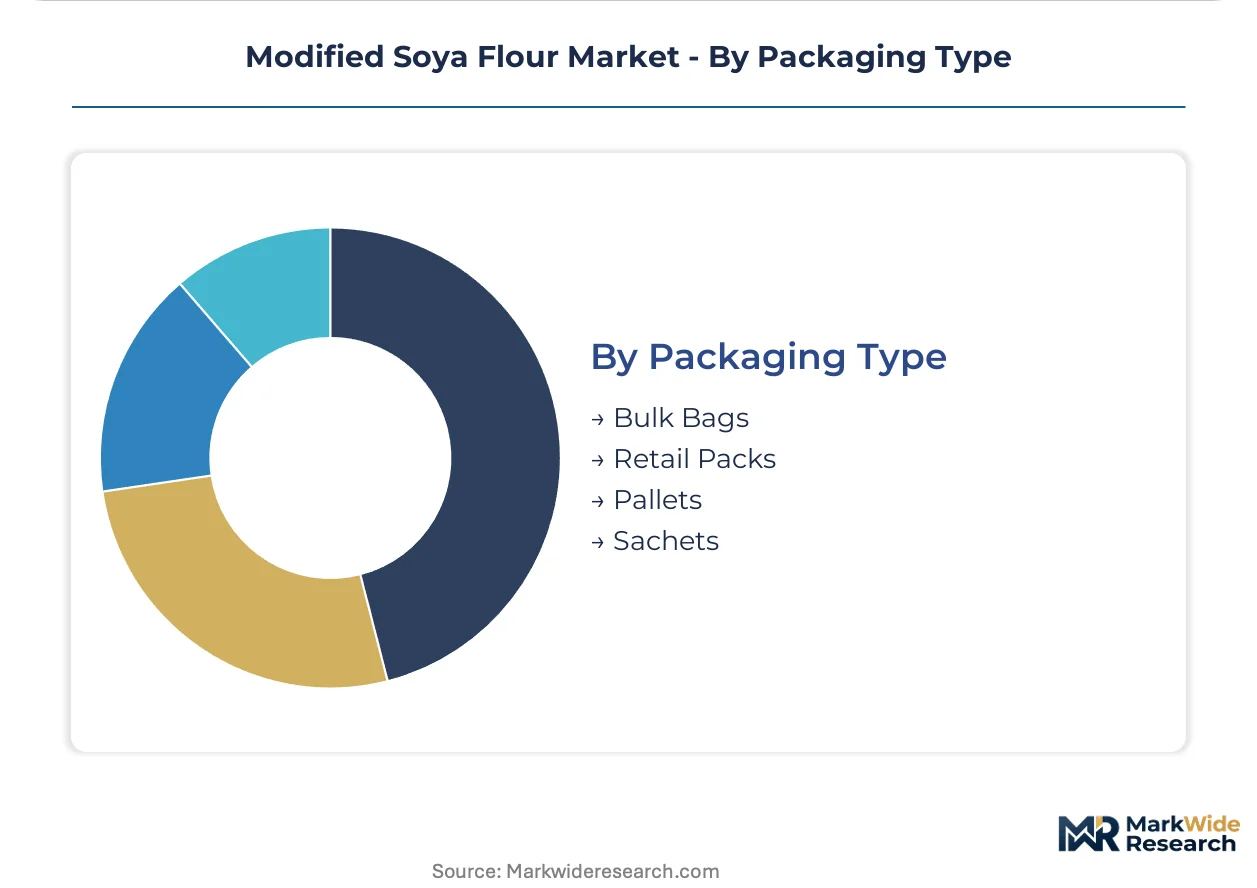
Packaging Type:
Distribution economics favor scale in industrial channels and convenience in foodservice and retail penetration.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate crush-to-flour integrated supply chains serving commercial bakeries and meat alternative manufacturers.
- Retail Packs:Consumer-facing pouches target home baking and specialty diet segments with recipe-ready portioning.
- Pallets:Unitized loads optimize logistics for high-volume institutional buyers with dedicated warehousing capacity.
- Sachets:Single-serve formats penetrate foodservice trial programs and airline catering where portion control and waste reduction drive specification.
Industrial procurement favors Bulk Bags; emerging channel development favors Sachets for trial conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mundra Port container terminal on Gujarat's western coast anchors India's modified soya flour export capacity, processing bulk shipments to Southeast Asian and Middle Eastern markets. This infrastructure asset underwrites the subcontinent's emerging role as a regional supplier hub.
India
Government-mandated school feeding programs and packaged food fortification initiatives drive institutional procurement volumes. The FSSAI enforces contaminant limits and fortification standards that channel demand toward licensed manufacturers with laboratory testing capabilities. Crush-to-flour integrated assets in Maharashtra and Gujarat offer locked-in pricing against volatile soybean futures, consolidating procurement around dual-certified suppliers.
United States
Commercial bakeries and meat alternative manufacturers absorb the largest volume share across North American channels. The FDA's FSMA preventive controls mandate documented sanitation protocols and lot traceability systems, locking in volume commitments with certified processors. Soybean processing clusters in Illinois and Iowa leverage rail connectivity to Gulf Coast export terminals for international shipment.
Germany
Meat alternative formulators in Berlin and Hamburg specify digitally certified textured flour lots with documented specific mechanical energy input for premium product lines. The EU Green Deal Protein Strategy favors domestic protein crop incentives and import substitution targets. REACH registration requirements for novel enzymatic processing aids tighten substance authorization timelines for modified flour producers.
Brazil
Drought cycles in soybean-producing regions transmit crush margin compression directly to modified flour input costs, eroding processor pricing power during supply contractions. ANVISA allergen labeling requirements align with international standards but add compliance documentation burdens. Processing assets in São Paulo and Paraná states concentrate value-added modification capacity near origination zones.
Indonesia
Nascent soya processing infrastructure and expanding instant noodle fortification programs create first-mover positioning opportunities for extrusion-capable suppliers. The country's national food safety regulator mandates fortification compliance for institutional feeding channels. Java-based processing zones are attracting investment in crush-to-flour lines to serve domestic packaged food manufacturers.
Modified Soya Flour Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the modified soya flour supply chain. The vendor base compresses around certified origination networks as regulatory documentation requirements eliminate spot-market arbitrage opportunities. Three archetypes dominate: integrated oilseed crushers with captive modification capacity, specialized extrusion technology providers, and regional processors serving institutional feeding programs. Competitive moves concentrate on backward integration into origination assets and technology licensing agreements for enzymatic hydrolysis capabilities.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill Incorporated exemplify the integrated platform archetype, while Bunge Limited occupies a position representing global trading houses with crush asset footprints. These three entities anchor the competitive structure through their control over origination-to-modification supply chains, with their geographic naming conventions indicating headquarters concentration in the United States. The Scoular Company and Associated British Foods represent mid-scale specialists competing on certification depth and regional market access rather than vertical scope.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| The Scoular Company |
| Associated British Foods |
| The Hain Celestial Group |
| Parrish and Heimbecker |
| Bunge Limited |
| ITC Limited |
| The Caremoli Group |
| Others |
Value Chain & Pricing Dynamics
Crush-to-flour capacity utilization in Maharashtra and Gujarat oscillates between 65-85%, creating alternating periods of spot-market surplus and contract-premium scarcity that force processors to toggle between volume-clearing discounts and identity-preservation premiums.
Pricing Analysis
FDA FSMA preventive controls dictate the pricing tier structure across food-grade modified soya flour, separating dual-certified suppliers with ISO 22000 and FSSAI licenses from single-certification competitors. Three-tier pricing structure across premium, standard, and economy levels tracks protein dispersibility index precision and lot-traceability documentation depth. Cost compression in standard grades is intensifying because Argentine drought cycles transmit crush-margin pressure directly to input costs. Commercial bakeries exhibit highest price sensitivity due to thin formulation margins, while meat alternative manufacturers absorb premium tiers for digitally certified extrusion lots.
Supply Chain Analysis
Soybean origination draws from Argentina, Brazil, and the United States Midwest, with Indian domestic crushing expanding to capture value previously flowing through import channels. Critical inputs encompass identity-preserved non-GMO seed stock, protease enzymes for hydrolysis modification, and extrusion screw configurations calibrated for specific mechanical energy targets. Single-source vulnerability concentrates in Argentine drought-exposed origination zones that transmit price volatility through crush-margin compression. Distribution runs through Mundra Port container terminals for Southeast Asian export, with bulk flexible intermediate bulk containers dominating commercial bakery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified soya flour markets are cycling through a recovery phase anchored to Indian government fortification program expansion, which institutionalizes volume commitments that insulate processors from commodity spot volatility.
For Market Incumbents: Pre-empt pulse protein substitution threats by accelerating enzymatic hydrolysis R&D to achieve protein dispersibility indices that pea and fava concentrates cannot replicate. Lock in backward integration into Maharashtra and Gujarat crush assets to secure feedstock cost advantages during Argentine supply contractions. Deepen FSSAI laboratory certification investments to capture institutional feeding program volumes competitors cannot access. For New Entrants and Emerging Players: Pursue Indonesia's nascent instant noodle fortification channel where extrusion-capable supply remains undersupplied relative to government mandate expansion. Target cold-water dispersible instant grade formulation trials with beverage manufacturers seeking to eliminate pre-hydration equipment steps. Lead with enzymatic modification technology licensing rather than capital-intensive crush asset construction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic hydrolysis modification lines as REACH registration requirements for novel protease treatments demand dedicated regulatory affairs infrastructure. Long-term viability favors integrated crush-to-flour platforms with dual-certification depth over single-stage processors exposed to margin compression. Monitor FSSAI license issuance velocity as the inflection signal for institutional channel access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crush Assets | Maharashtra and Gujarat origination control secures cost-advantaged feedstock during Argentine drought cycles. |
| Enzymatic Hydrolysis Technology Licensing | Protease treatment capabilities unlock protein dispersibility indices that heat-modified flour cannot achieve. |
| FSSAI Dual-Certification Investment | Laboratory testing capabilities open institutional feeding program channels with mandated fortification compliance. |
| Digital Extrusion Certification Systems | Real-time specific mechanical energy monitoring commands premium pricing from German meat alternative formulators. |
| Indonesia Crush-to-Flour Capacity Buildout | First-mover positioning captures instant noodle fortification program volumes before domestic competition consolidates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FSSAI fortification compliance records, FDA FSMA inspection data, and crush-margin trade publications. Plant managers at Maharashtra and Gujarat processing facilities, procurement leads at commercial bakeries and meat alternative manufacturers, and distribution channel partners across Mundra Port logistics networks provided operational validation. SEC filings of integrated agribusiness conglomerates, customs export records from Gujarat maritime authorities, and ISO 22000 certification databases supplied secondary triangulation. Bottom-up volume modeling and top-down value reconciliation converged on segment-level outputs.
Forecast inputs incorporate protein dispersibility index calibration trajectories, enzymatic hydrolysis adoption curves, and government fortification program expansion schedules across the analysis window. Segmentation dimensions span product type, end-use application, certification grade, and packaging format against regional processing hub concentration. CAGRs derive from compound trajectory modeling of crush capacity utilization, regulatory compliance cost inflation, and substitution elasticity between soya and pulse proteins. Soybean futures volatility bands and FSSAI license issuance rates inform scenario-weighted projections.
Sensitivities concentrate around Argentine drought frequency, REACH registration timeline delays for novel enzymes, and Indian government feeding program budget allocations. Forecasts reflect documented assumptions regarding crush-margin transmission elasticity and certification cost pass-through rates. Cross-checking against USDA soybean supply estimates and FSSAI quarterly fortification compliance reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Lime Seed Oils Market
Ingredients
Sunflower Lecithin Market
Ingredients
Malted Wheat Flour Market
Ingredients
Corn Oil Market
Ingredients
Lentils Flour Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Asia-Pacific Protein Market
Ingredients
Jasmine Extract Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Modified Flour Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Carob Protein Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Licorice Root Market
Ingredients
Global Malt Ingredients Market
Ingredients
Vegetable Concentrates Market