
 Modified Lecithin Market | 2026-2036
Modified Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Lecithin Market Foresight
Pharmaceutical formulators are redrawing demand patterns across the modified lecithin landscape, pulling volume toward high-purity phosphatidylcholine grades for liposomal drug delivery. Cargill leverages its integrated oilseed processing network to secure consistent crude lecithin feedstock across multiple continents. DuPont de Nemours differentiates through advanced fractionation technology that yields custom phospholipid ratios for injectable applications. Wilmar International anchors Asian supply chains with palm and soybean origination strength in Southeast Asia.
Modified lecithin comprises chemically or enzymatically altered phospholipid mixtures, typically containing 20-90% phosphatidylcholine by weight, produced through acetone fractionation, chromatographic purification, or enzymatic hydrolysis to achieve specific HLB values and emulsification performance for industrial applications. Soy lecithin dominates volume flows due to established crushing infrastructure and cost structures, though sunflower lecithin captures premium positioning as non-allergenic and non-GMO alternatives gain formulation share in European cosmetics and infant nutrition. Powder and granule forms command higher unit economics than liquid counterparts due to handling advantages and extended shelf stability in pharmaceutical cleanroom environments.
FDA pharmaceutical excipient guidelines and EMA Good Manufacturing Practice standards govern modified lecithin purity thresholds for drug delivery applications, while REACH registration requirements in Europe enforce full supply chain transparency on phospholipid sourcing and solvent residues. Stakeholders must monitor evolving EFSA novel food opinions on enzymatically modified phospholipids and assess whether captive fractionation investments or specialist outsourcing partnerships better secure specification-grade supply.
Market Dynamics
Pharmaceutical-grade phospholipid fractionation is compressing supply timelines as liposomal drug developers demand custom HLB specifications and solvent residue thresholds below 50 ppm.
Growth Catalysts
- Liposomal Drug Delivery Expansion:Injectable nanomedicine developers are pulling high-purity phosphatidylcholine into oncology and vaccine formulations, creating specification-grade volume commitments that stabilize producer margins.
- EU Green Deal Substitution Mandates:REACH-registered sunflower lecithin is displacing soy-derived alternatives in German and French cosmetic clean-label portfolios, driven by allergen disclosure requirements and non-GMO certification premiums.
- Enzymatic Hydrolysis Advancement:Phospholipase A2 modification is enabling water-dispersible lecithin grades for instant beverage applications, opening formulation flexibility in functional nutrition.
Market Restraints
- Crude Oilseed Price Volatility:Soybean and sunflower seed crush margins fluctuate with Black Sea export disruptions, transmitting cost instability to refined lecithin quotations.
- Acetone Solvent Regulatory Scrutiny:ECHA classification reviews of residual ketone limits in food-contact materials are extending compliance timelines for traditional fractionation operators.
- Egg Yolk Phospholipid Substitution:Premium cosmetics formulators are piloting phosphatidylcholine from avian sources for claimed skin-penetration advantages, threatening plant-based positioning.
Strategic Opportunities
- Indian Nutraceutical White Space:FSSAI novel food approval pathways for enzymatically modified phospholipids remain underutilized, offering first-mover positioning in ayurvedic-compatible delivery systems.
- Cell Culture Media Integration:Serum-free bioproduction protocols are specifying hydrogenated lecithin as lipid micelle stabilizers, creating pull from contract development organizations.
- CSRD Supply Chain Disclosure:Corporate sustainability reporting requirements are rewarding phospholipid suppliers with certified deforestation-free oilseed traceability, enabling premium tier access.
Industry Challenges
- Phospholipid Analytical Talent Scarcity:HPLC and mass-spec method development for molecular species quantification exceeds current technical training pipeline output, extending R&D cycle times.
- Multi-Pharmacopeia Harmonization:Reconciling USP-NF, EP, and JP monograph variations for injectable-grade lecithin requires parallel dossier investments that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Lecithin Market |
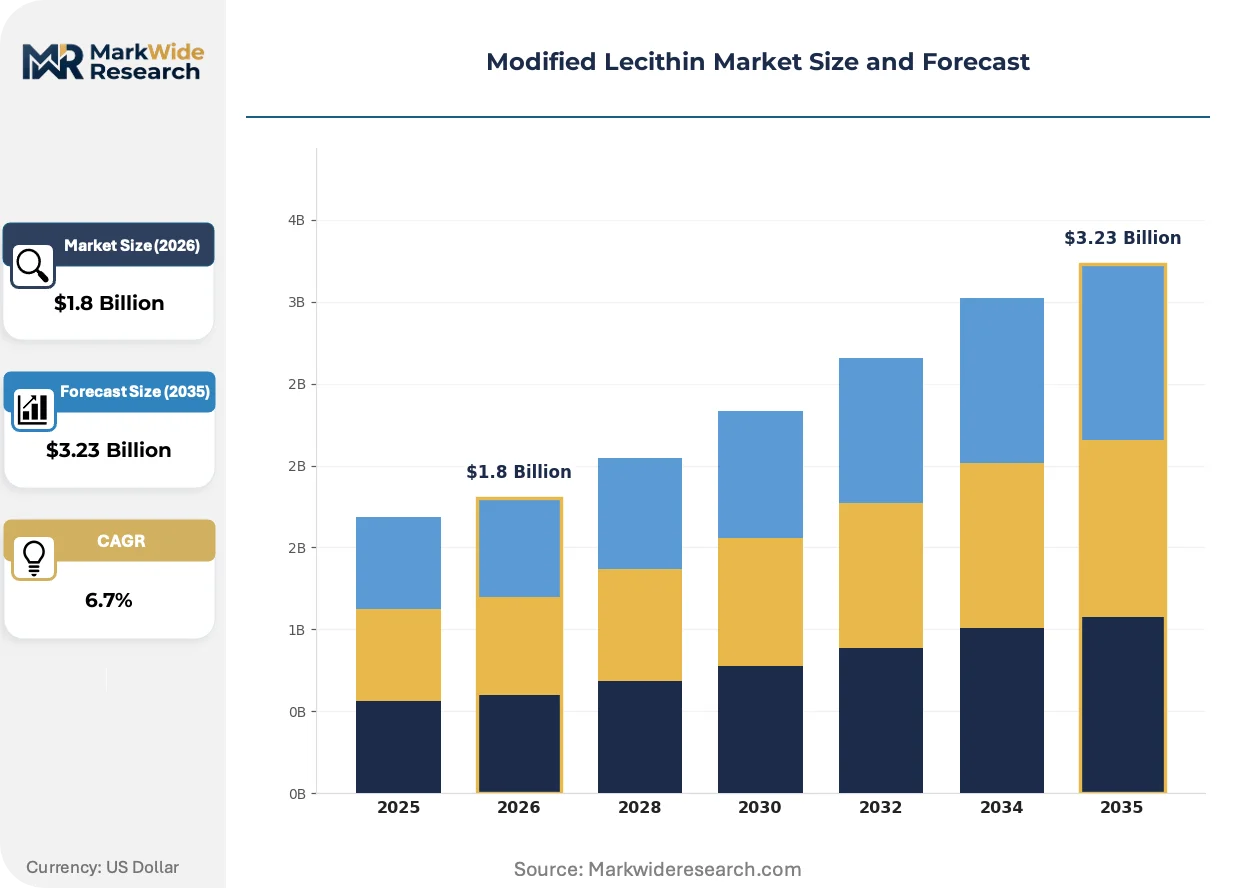
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunflower Lecithin, Soy Lecithin, Egg Lecithin, Phosphatidylcholine End Use Industry: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Liquid, Powder, Granules, Emulsifier Application: Baking, Confectionery, Dairy Products, Animal Feed |
| Companies Covered | Cargill, Archer Daniels Midland Company, DuPont de Nemours, American Lecithin Company, Bunge, LECICO GmbH, Wilmar International, Lipoid GmbH, Sonic Biochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Lecithin Market Shifts & Advancements
Continuous processing and modular purification systems are replacing batch fractionation, compressing capital recovery periods while enabling rapid specification switches between pharmaceutical and food-grade outputs.
Membrane filtration is miniaturizing phospholipid purification footprints. German equipment suppliers are deploying ceramic microfiltration skids for acetone-free degumming, enabling on-site crude lecithin upgrading at oilseed crushing facilities. This distributed processing model is compressing logistics costs for remote soybean origination points while maintaining pharmaceutical-grade output consistency.
EMA Good Manufacturing Practice Annex 1 revisions on sterile manufacturing are tightening excipient bioburden limits. Liposomal drug sponsors now require endotoxin testing below 10 EU/g for parenteral phospholipids, forcing fractionators to implement closed-system processing and single-use contact surfaces. Contract manufacturers in Switzerland and the Netherlands are investing in isolator technology to secure specification compliance.
Ingredient co-development partnerships are displacing transactional procurement in infant nutrition. Brands are embedding phospholipid suppliers into early-stage formulation teams, locking in exclusive phosphatidylserine ratios for cognitive health positioning. This collaboration model concentrates volume with integrated oilseed processors capable of custom enzymatic modification, visible in Dutch and German maternal nutrition clusters.
Modified Lecithin Market Segmentation
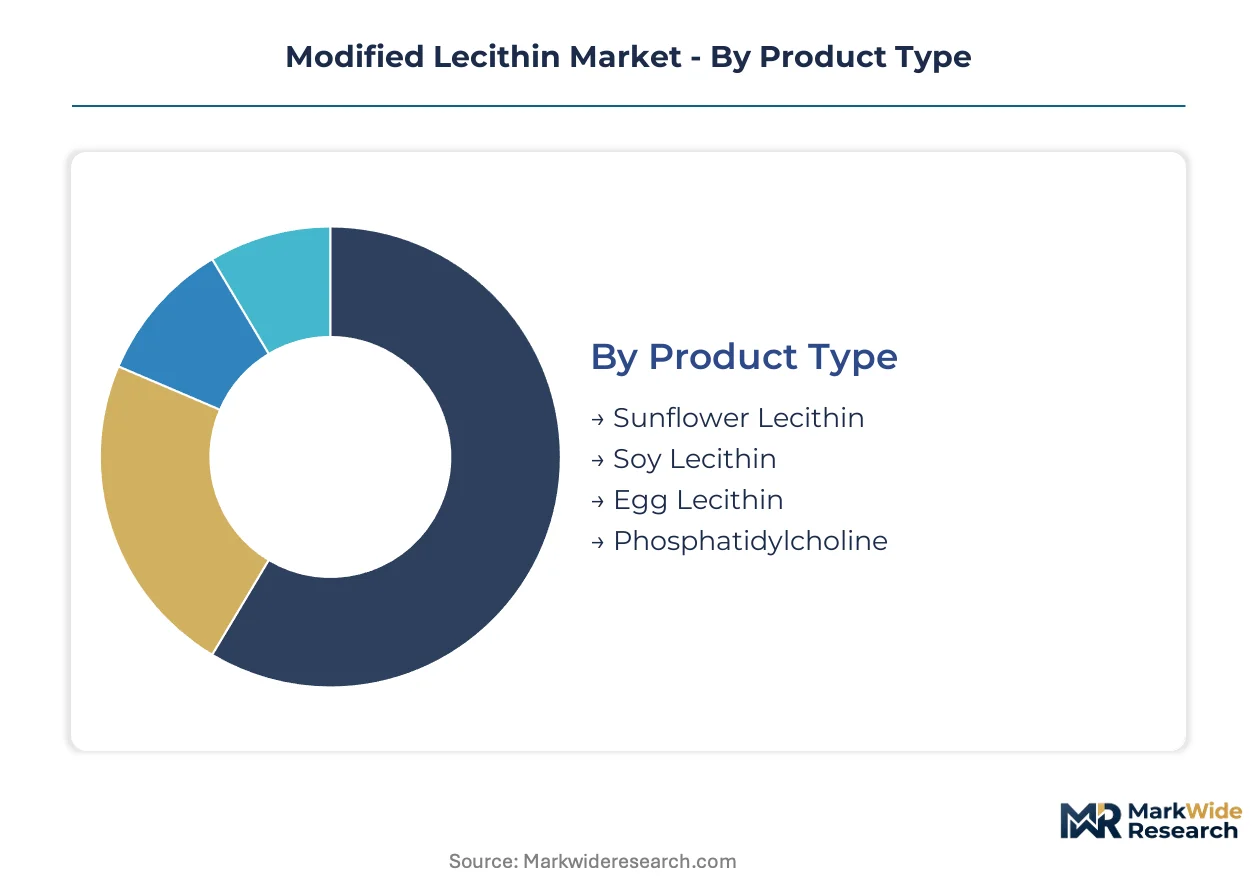
Modified lecithin segmentation reveals divergent margin structures across source materials and purification grades. Pharmaceutical-grade phosphatidylcholine commands specification premiums while commodity liquid lecithin faces margin compression from solvent residue compliance costs.
Product Type:
Sunflower lecithin faces the most acute substitution pressure as EU allergen disclosure mandates and non-GMO certification requirements accelerate displacement of soy-derived alternatives in German and French cosmetic formulations.
- Sunflower Lecithin:Non-allergenic phospholipid mixture with 20-60% phosphatidylcholine content, produced through cold-press degumming and acetone fractionation. REACH-registered supply chains in Germany concentrate demand from clean-label infant nutrition brands seeking EFSA-compliant novel food status. EU Green Deal sustainability scoring rewards deforestation-free Ukrainian and Russian origination, though Black Sea logistics disruptions strain crush margin stability.
- Soy Lecithin:Established volume leader containing 15-35% phosphatidylcholine, extracted from solvent-crushed soybean flakes. Argentine and Brazilian crushing infrastructure anchors global supply, with US Gulf Coast refineries serving pharmaceutical excipient markets under FDA pharmaceutical guidelines. Genetic modification disclosure requirements in European cosmetics are eroding formulation share despite cost advantages in bulk food emulsification.
- Egg Lecithin:Phosphatidylcholine-rich extract from avian yolk sources, prized for superior skin-penetration properties in premium dermocosmetics.
- Phosphatidylcholine:Highly purified fraction exceeding 90% phosphatidylcholine by weight, essential for liposomal drug delivery systems.
Soy lecithin anchors the volume base while phosphatidylcholine gains share at the steepest rate.
End Use Industry:
Margin stratification follows application purity requirements, with parenteral pharmaceutical specifications enabling 3-5x unit economics over standard food-grade emulsification.
- Pharmaceuticals:Injectable-grade phospholipids for liposomal oncology and vaccine delivery, requiring endotoxin levels below 10 EU/g and solvent residues under 50 ppm per EMA Good Manufacturing Practice Annex 1. Swiss and Dutch contract manufacturers invest in isolator technology to secure specification compliance for liposomal drug sponsors.
- Food & Beverages:Emulsification workhorse applications spanning chocolate viscosity modification, instant beverage dispersibility, and bakery shelf-life extension. Enzymatic hydrolysis using phospholipase A2 enables water-dispersible grades for functional nutrition, though FSSAI novel food pathways in India remain underutilized for modified phospholipid approval.
- Cosmetics:Skin-conditioning phospholipids in premium dermocosmetics, with egg-derived alternatives threatening plant-based positioning for claimed penetration advantages.
- Nutraceuticals:Cognitive health phosphatidylserine formulations and sports nutrition lipid micelle delivery systems.
Food and beverages anchors the volume base while pharmaceuticals climbs the fastest on specification-grade pull.
Form:
Handling economics and shelf stability requirements drive format selection across cleanroom and standard industrial environments.
- Powder:Spray-dried or roller-dried particulate with extended shelf stability and dust-free handling characteristics for pharmaceutical cleanroom environments. German and Dutch maternal nutrition clusters specify powder formats for infant formula phospholipid fortification, with exclusive phosphatidylserine ratios locked through early-stage supplier collaboration.
- Liquid:Standard crude or refined lecithin in fluid state, dominating volume flows through cost-efficient bulk handling at oilseed crushing facilities. Ceramic microfiltration skids enable on-site upgrading at remote soybean origination points, compressing logistics costs while maintaining output consistency.
- Granules:Agglomerated free-flowing particles balancing handling convenience with rapid dispersibility in high-shear mixing applications.
- Emulsifier:Pre-hydrated or compound formulations optimized for specific HLB requirements in industrial processing.
Liquid anchors the volume base while powder expands most quickly on pharmaceutical cleanroom demand.
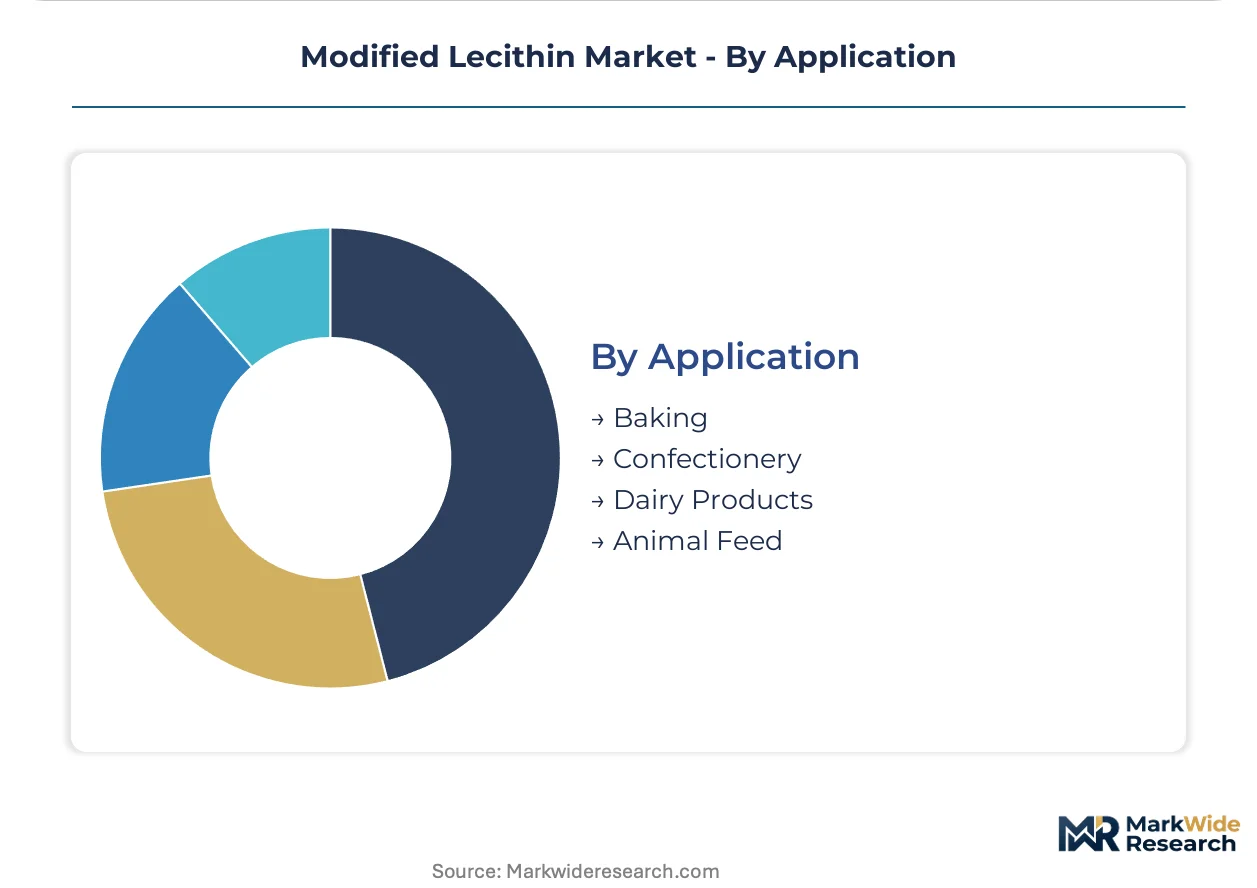
Application:
Processing temperature tolerance and emulsion stability requirements differentiate technical specifications across thermal processing intensity.
- Dairy Products:Phospholipid-stabilized fat emulsions in processed cheese, infant formula, and cream liqueurs requiring heat stability through UHT processing. Indian ayurvedic-compatible delivery systems present white-space opportunity for enzymatically modified phospholipids with FSSAI novel food approval.
- Baking:Dough conditioning and crumb softening through phospholipid interaction with gluten and starch networks.
- Confectionery:Chocolate viscosity reduction and fat bloom inhibition through phospholipid crystal modification.
- Animal Feed:Pellet binding and lipid digestibility enhancement in aquaculture and livestock nutrition.
Dairy products anchors the volume base while baking gains share on clean-label emulsifier substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's vegetable oil terminal infrastructure underwrites Europe's phospholipid import and fractionation capacity, connecting Black Sea sunflower seed flows to German downstream processing clusters.
Germany
Pharmaceutical-grade phospholipid demand concentrates around Ludwigshafen and Hamburg, where EMA Good Manufacturing Practice Annex 1 compliance drives investment in isolator technology for liposomal drug production. REACH registration requirements enforce full supply chain transparency on solvent residues. The Lipoid GmbH and LECICO GmbH production clusters in these regions anchor specialized fractionation capacity for injectable-grade specifications.
United States
FDA pharmaceutical excipient guidelines govern modified lecithin purity thresholds for oncology and vaccine delivery systems, with Gulf Coast refineries processing Argentine and Brazilian soybean crush outputs. The Chicago Board of Trade soybean futures curve transmits Black Sea export volatility directly to lecithin quotation stability. Cargill's integrated oilseed processing network maintains consistent crude feedstock access across multiple continental origination points.
India
FSSAI novel food approval pathways for enzymatically modified phospholipids remain underutilized, creating first-mover positioning opportunities in ayurvedic-compatible delivery systems. The country's national food regulator has yet to establish clear enzymatic modification standards, extending compliance timelines for international suppliers. Maharashtra and Gujarat oilseed crushing infrastructure processes domestic soybean and imported palm outputs for regional emulsifier markets.
Switzerland
Swissmedic oversight of sterile manufacturing standards attracts liposomal drug sponsors requiring endotoxin testing below 10 EU/g for parenteral phospholipids. Contract manufacturers in Basel and Zurich invest in closed-system processing and single-use contact surfaces to secure specification compliance. The country's pharmaceutical excipient import dependencies create premium positioning for GMP-certified European fractionators.
Netherlands
Ingredient co-development partnerships concentrate in Dutch maternal nutrition clusters, with brands embedding phospholipid suppliers into early-stage formulation teams for cognitive health positioning. EFSA novel food opinions on enzymatically modified phospholipids shape regulatory timelines for clean-label infant nutrition launches. Rotterdam's vegetable oil terminal infrastructure enables direct crude lecithin upgrading through ceramic microfiltration skids deployed at remote crushing facilities.
Modified Lecithin Market Competitive Landscape
Concentration sits with integrated oilseed processors and specialized phospholipid fractionators. The vendor base splits between multinational agribusiness conglomerates with crushing infrastructure and mid-scale European specialists with pharmaceutical-grade purification capabilities. Three archetypes dominate: volume-driven commodity suppliers, specification-grade pharmaceutical fractionators, and enzymatic modification specialists. Competitive moves center on captive fractionation investments versus specialist outsourcing partnerships, plus geographic expansion into underregulated nutraceutical white spaces.
Among integrated agribusiness conglomerates, Cargill, Archer Daniels Midland Company, and Bunge occupy positions defined by upstream oilseed origination strength and downstream refining integration. These entities exemplify the volume-driven archetype through established crushing infrastructure across multiple continents. Specialized European fractionators Lipoid GmbH and LECICO GmbH represent the specification-grade tier, anchoring pharmaceutical-cluster proximity in Germany. DuPont de Nemours sits within the technology-differentiated segment, with de Nemours suffix signaling advanced fractionation capabilities for custom phospholipid ratios.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| DuPont de Nemours |
| American Lecithin Company |
| Bunge |
| LECICO GmbH |
| Wilmar International |
| Lipoid GmbH |
| Sonic Biochem |
| Others |
Supply & Pricing Matrix
Crushing capacity utilization at German and Dutch oilseed facilities shapes both supply concentration and price floors for pharmaceutical-grade phospholipids. Scale economies in acetone fractionation and chromatographic purification anchor premium tier pricing power, while commodity liquid lecithin faces margin compression from solvent residue compliance investments.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels reflects purification intensity and certification thresholds. Price differentiation centers on endotoxin testing below 10 EU/g for parenteral applications and REACH registration status for EU cosmetic formulations. Cost compression in standard food-grade tiers is intensifying because acetone solvent regulatory scrutiny extends compliance timelines. Contract manufacturers in pharmaceutical clusters show least price sensitivity, while bulk food emulsifier buyers negotiate aggressively on volume.
Supply Chain Analysis
Port congestion at Rotterdam and Black Sea export disruptions strain inbound logistics costs for sunflower seed flows to German fractionators. Supply concentrates in Argentina, Brazil, and Germany, with Ukrainian origination facing intermittent chokepoints. Raw material dependencies rest on soybean and sunflower seed crush outputs, phospholipase A2 enzymes, and acetone solvents. Single-source vulnerability runs through Black Sea sunflower corridors. Distribution runs through Rotterdam's vegetable oil terminals connecting to Ludwigshafen and Hamburg processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modified lecithin market is entering a cyclical recovery phase as liposomal drug delivery investment rebounds from pandemic-era volatility. Injectable nanomedicine development cycles drive specification-grade volume commitments that stabilize producer margins across the forecast window.
For Market Incumbents: Compound fractionation capacity utilization through captive enzyme modification investments and exclusive phospholipid ratio partnerships with infant nutrition brands. Egg yolk phospholipid substitution in premium cosmetics threatens plant-based positioning, demanding accelerated sunflower lecithin non-GMO certification penetration in German and French markets. Backward integration into oilseed crushing secures crude feedstock access against Black Sea supply volatility. For New Entrants and Emerging Players: Custom HLB specification services for liposomal drug developers represent an under-served niche where incumbents prioritize scale over agility. Target Indian nutraceutical white space through FSSAI novel food approval navigation for enzymatically modified phospholipids in ayurvedic-compatible delivery systems. Lead with technical service capabilities and rapid specification turnaround rather than commodity volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade fractionators with locked liposomal drug sponsor relationships and multi-year endotoxin testing contracts. Five-to-ten year viability favors specialists with EMA Good Manufacturing Practice Annex 1 compliance infrastructure over commodity liquid lecithin processors. Watch for EFSA novel food opinion finalization on enzymatically modified phospholipids as inflection signal for infant nutrition formulation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Acetone-Free Fractionation Investment | Ceramic microfiltration deployment at Rotterdam terminals eliminates solvent residue compliance risks for EU cosmetic supply. |
| Enzymatic Modification Capability Buildout | Phospholipase A2 processing lines capture water-dispersible lecithin demand in functional nutrition applications. |
| Isolator Technology Implementation | Closed-system processing secures endotoxin specifications below 10 EU/g for Swiss and Dutch parenteral drug manufacturers. |
| Exclusive Supplier Partnerships | Early-stage infant nutrition formulation embedding locks phosphatidylserine ratios for cognitive health positioning. |
| Deforestation-Free Certification Program | CSRD-aligned traceability enables premium tier access in EU Green Deal-scored cosmetic clean-label portfolios. |
Research Methodology
Desk research of EMA regulatory filings, FSSAI novel food registers, and oilseed trade customs data preceded structured interviews with pharmaceutical formulation scientists, cosmetic R&D directors, and oilseed procurement managers. Primary fieldwork with German fractionation plant operators and Dutch maternal nutrition brand technologists validated secondary estimates. Bottom-up volume modeling across source material, purification grade, and end-use segments triangulated against top-down oilseed crush capacity analysis.
Variance decomposition across the projection horizon isolates price, volume, and mix effects within each segmentation dimension. The analytical framework models phospholipid source material, purification tier, end-use industry, geographic production cluster, and format type. CAGRs derive from segment-level growth rate synthesis anchored to liposomal drug pipeline advancement and EU regulatory substitution mandates. Key inputs include EMA sterile manufacturing guideline revision timelines and FSSAI enzymatic modification approval pathway developments.
Forecasts assume regulatory continuity in REACH, EMA Good Manufacturing Practice, and FSSAI frameworks; material policy shifts would require re-modeling. Black Sea logistics stability and EFSA novel food opinion timing represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Lemon Oil Market