
 Europe Vanilla Beans and Extract Market | 2026-2036
Europe Vanilla Beans and Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vanilla Beans and Extract Market Foresight
Multi-source procurement from Madagascar, Uganda, and Papua New Guinea is repositioning European vanilla supply chains away from single-origin dependence. Eurovanille leverages its direct farmer partnerships in the Indian Ocean region to sustain consistent bean quality. Givaudan anchors its competitive stance through captive extraction capabilities in France and Switzerland. Symrise competes by specializing in tailored vanilla profiles for premium ice cream and confectionery clients.
Vanilla beans and extract comprise the cured seed pods and derived aromatic compounds of Vanilla planifolia and Vanilla tahitensis, with vanillin concentrations in pure extract typically ranging from one to three percent by volume and primary application as a natural flavoring and fragrance agent. Extracts and paste variants command the deepest margin pools due to their indispensability in industrial food formulation, while whole beans retain premium positioning among artisanal bakers and chocolatiers. The food and beverage application segment dominates volume throughput, though cosmetic and pharmaceutical uses of vanilla-derived oleoresins are gaining formulation share in clean-label personal care lines.
EMA food additive safety assessments, EFSA flavoring substance evaluations, and the EU Deforestation Regulation collectively constrain market access for non-compliant sourcing while elevating certified sustainable vanilla premiums. REACH chemical registration requirements further govern synthetic vanillin alternatives, indirectly reinforcing demand for botanical extracts. Stakeholders must monitor enforcement timelines for deforestation-linked due diligence and calibrate inventory positions against evolving certification standards.
Market Dynamics
The EU Deforestation Regulation is forcing European vanilla buyers to reconstruct traceable supply chains from origin to extraction facility, eliminating opaque intermediary layers that historically obscured bean provenance.
Growth Catalysts
- Clean-label confectionery reformulation:Belgian and French chocolate makers are replacing synthetic vanillin with Madagascar-sourced natural extract to meet EFSA clean-label guidance.
- EU Deforestation Regulation:Mandatory due diligence requirements are accelerating certified sustainable vanilla premiums as compliance becomes a market access condition.
- Papua New Guinea:Emerging curing infrastructure in this origin is diversifying European procurement beyond Indian Ocean dependence.
Market Restraints
- Madagascar supply concentration:Overreliance on a single origin exposes European extractors to cyclone-driven harvest volatility and price spikes.
- REACH registration burden:Synthetic vanillin alternatives face escalating compliance costs that indirectly inflate natural extract premiums.
- Substitution pressure:Ethyl vanillin and other nature-identical compounds compete on cost in mass-market ice cream applications.
Strategic Opportunities
- Uganda origin development:Underdeveloped curing capacity in this East African source offers first-mover advantages for direct farmer partnerships.
- Cosmetic oleoresin applications:Clean-label personal care lines in France and Germany are absorbing vanilla-derived aromatic compounds for fragrance formulations.
- Blockchain traceability integration:Distributed ledger systems are enabling premium pricing for batch-verified deforestation-free beans.
Industry Challenges
- Certification timeline compression:EU Deforestation Regulation enforcement deadlines are outpacing supplier audit capacity.
- Curing expertise scarcity:Traditional Bourbon curing knowledge concentrates in aging farmer populations across the Indian Ocean region.
- Inventory reconfiguration costs:Segregated supply chains for compliant and non-compliant beans demand redundant warehousing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vanilla Beans and Extract Market |
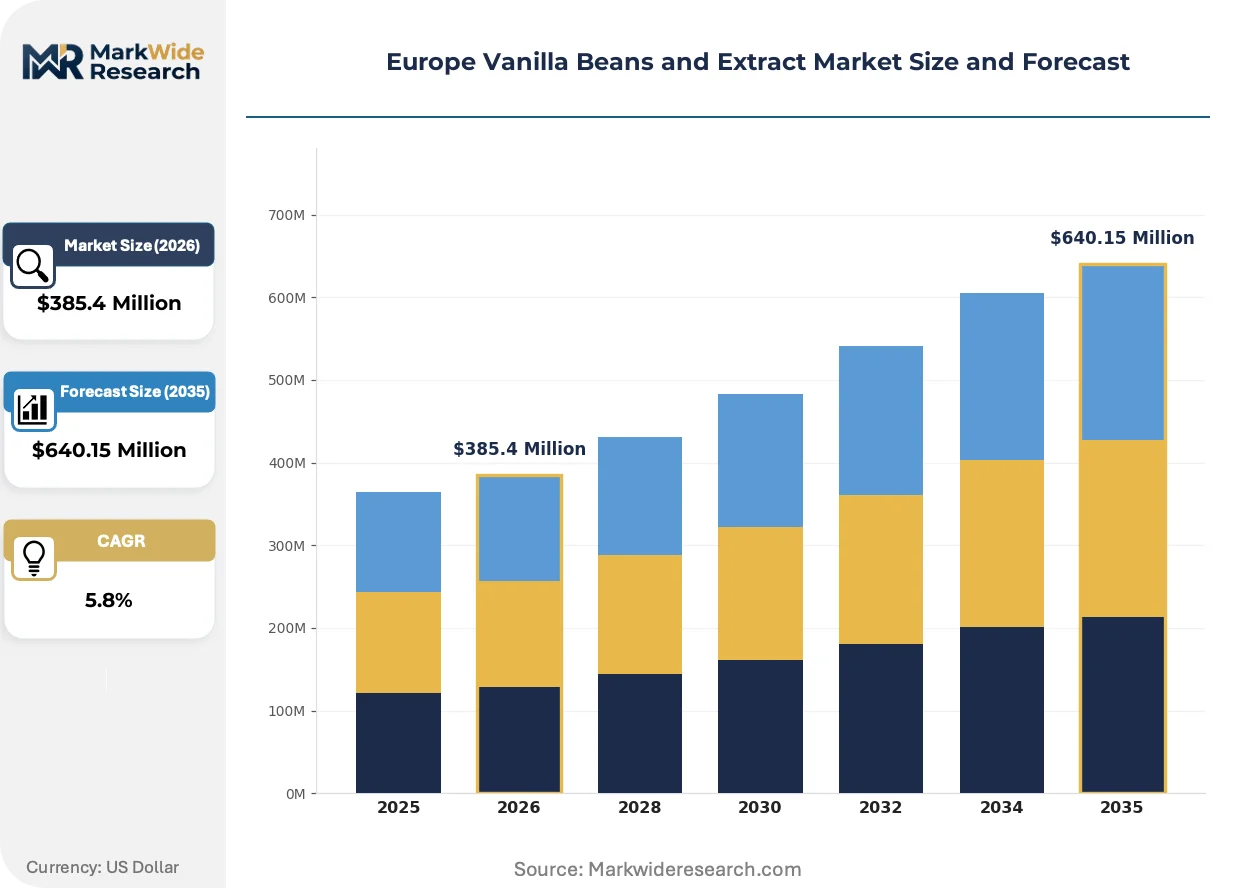
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Extracts, Powder, Paste Form: Liquid, Dry, Concentrate, Crystals Application: Food & Beverage, Cosmetic, Pharmaceutical, Aroma Customer Type: Retail, Wholesale, Food Service, Manufacturers |
| Companies Covered | Nielsen-Massey Vanillas, Eurovanille, Givaudan, Firmenich, Kerry, Symrise, McCormick & Company, Borregaard, International Flavors & Fragrances (IFF), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vanilla Beans and Extract Market Shifts & Advancements
European vanilla markets are experiencing simultaneous pressure from regulatory traceability mandates and artisanal demand for single-origin provenance, compressing the viable middle ground for commodity-grade supply.
Blockchain-enabled origin verification is consolidating audit functions previously performed by fragmented third-party certifiers. French and Swiss extraction facilities are deploying these systems to satisfy EUDR documentation requirements. The technology is consolidating intermediary roles by embedding compliance directly into procurement workflows.
EMA food additive safety assessments are tightening purity thresholds for vanilla extracts used in pharmaceutical applications. This regulatory friction is diverting higher-grade beans toward medical flavoring markets and away from standard food formulations. Swissmedic and ANSM are aligning national enforcement with these elevated standards.
Direct-origin contracting is displacing spot-market purchasing among premium Belgian chocolatiers. These buyers are establishing multi-year offtake agreements with Madagascar and Uganda cooperatives, bypassing traditional Amsterdam and Hamburg trading houses. The shift is most visible in Antwerp's specialty chocolate cluster, where traceability commands measurable price premiums.
Europe Vanilla Beans and Extract Market Segmentation
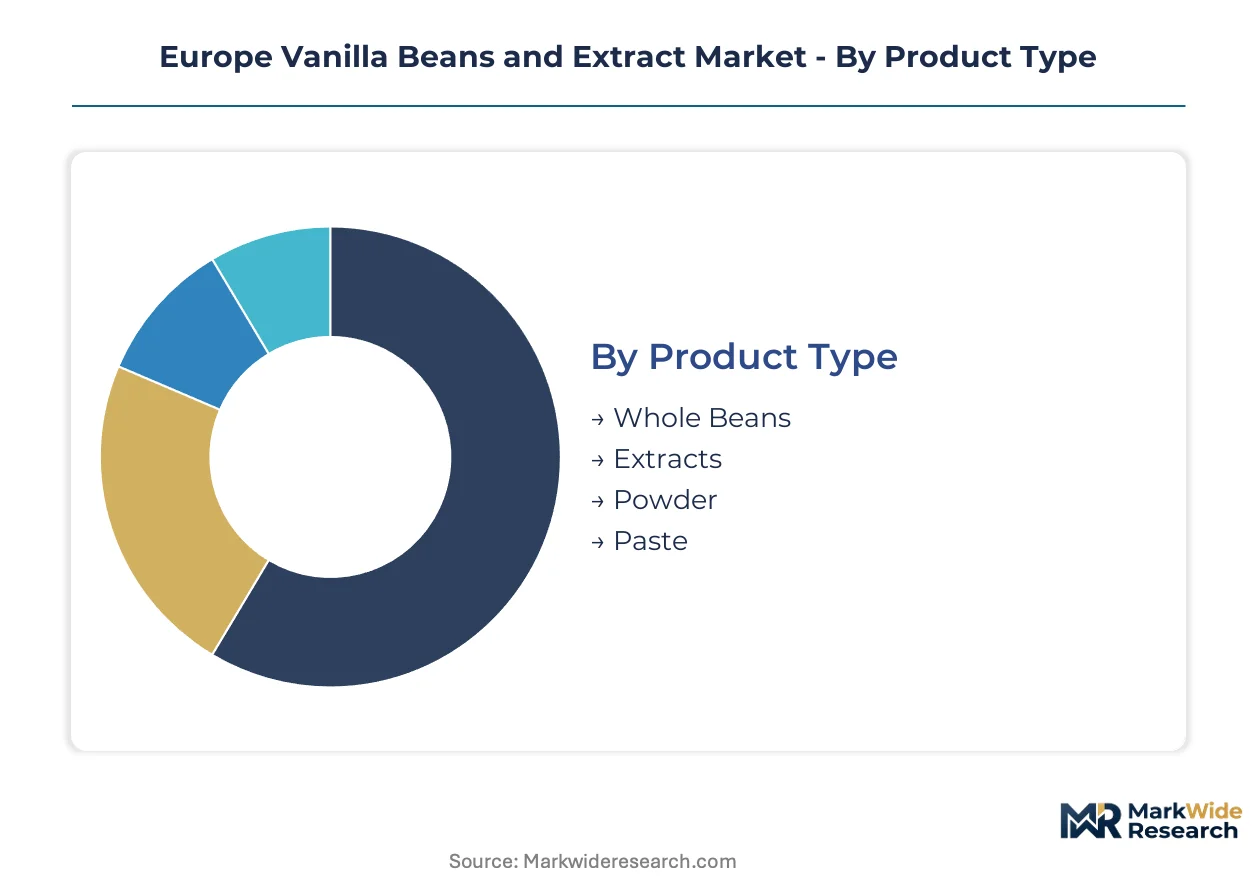
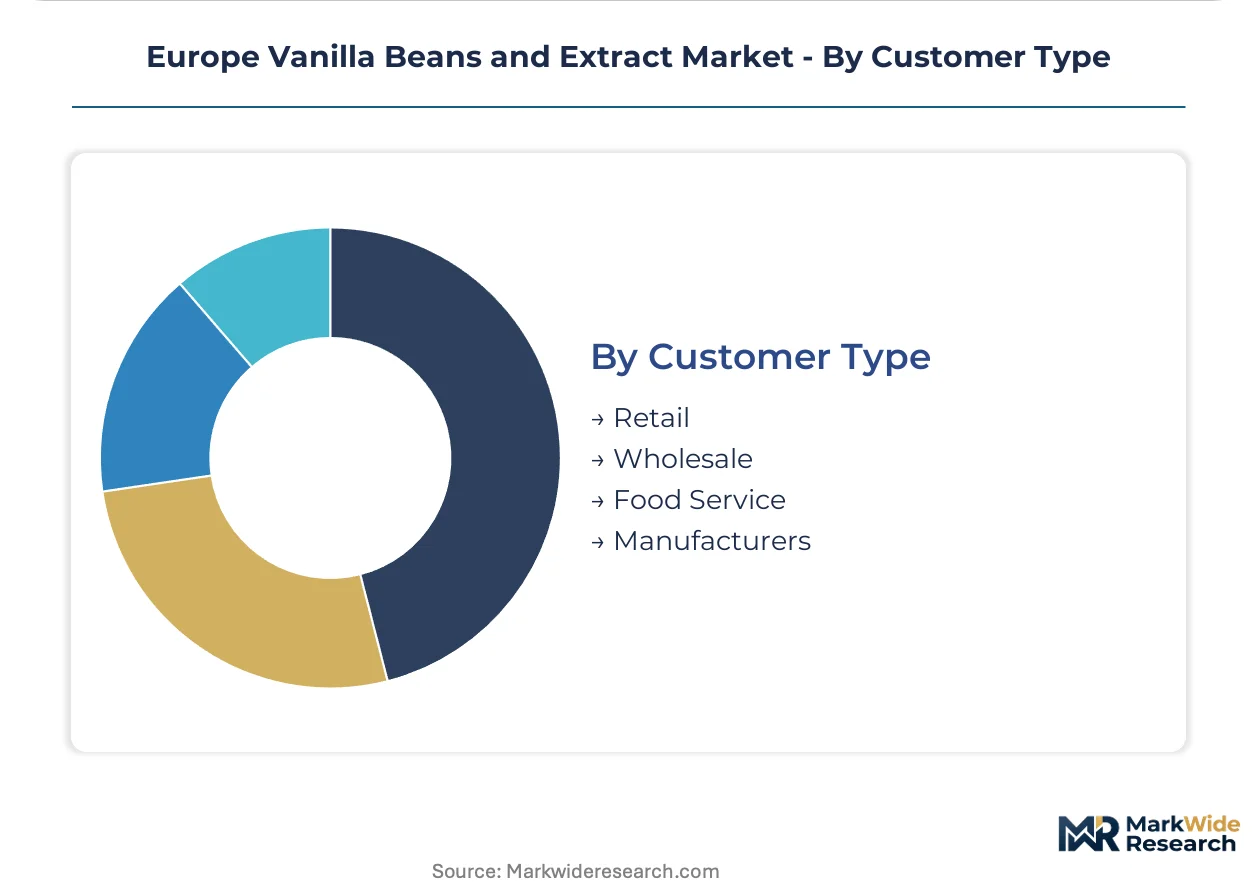
Vanilla procurement in Europe fragments across four distinct dimensions that determine compliance burden, margin capture, and supply chain architecture. Buyers prioritize different specifications depending on whether they serve industrial formulation, artisanal production, or retail distribution channels.
Product Type:
Industrial buyers and artisanal users diverge sharply in their quality specifications and volume commitments across these categories.
- Whole Beans:Cured seed pods retaining full aromatic complexity with vanillin content varying by origin and curing method. Belgian and French chocolatiers absorb premium Madagascar-sourced whole beans for single-origin provenance claims under tightening EUDR documentation requirements.
- Extracts:Alcohol-based solutions containing one to three percent vanillin by volume, standardized for consistent industrial dosing. France's patisserie and dairy sectors concentrate demand here, with extractors in Grasse and Hamburg serving as primary supply nodes for continental formulation houses.
- Powder:Spray-dried vanilla derivatives offering extended shelf stability and simplified logistics for dry-mix applications. German baking premix manufacturers represent the core customer base.
- Paste:Concentrated suspensions combining extract with ground bean matter for visual and aromatic intensity. Artisan ice cream producers in Italy and Spain favor this format for premium positioning.
Extracts lead volumes today; paste is gaining share fastest among specialty food service channels.
Form:
Logistics economics and formulation compatibility drive selection between physical states, with liquid formats dominating throughput but dry alternatives expanding in clean-label applications.
- Liquid:Standard alcohol or glycerin-based solutions permitting precise volumetric dosing in continuous production. Industrial chocolate and confectionery operations across Belgium, France, and Switzerland anchor procurement volumes.
- Dry:Encapsulated or spray-dried formats eliminating solvent residues for label-conscious positioning. German natural cosmetics brands are absorbing expanding volumes of dry vanilla preparations.
- Concentrate:High-potency reduced-volume formats minimizing transport costs and storage footprint. Remote extraction facilities in the Indian Ocean region favor concentrate shipments to European ports.
- Crystals:Purified vanillin isolates for pharmaceutical and high-precision fragrance applications. Swissmedic-registered facilities in Basel and Geneva represent the primary demand concentration.
Liquid forms retain the largest share; dry formats are climbing the fastest as clean-label cosmetic lines proliferate.
Application:
End-use sectors impose divergent purity thresholds, with pharmaceutical and cosmetic applications capturing premium-grade supply while food and beverage absorbs volume.
- Food & Beverage:Flavoring for chocolate, ice cream, baked goods, and dairy products across industrial and artisanal tiers. EFSA flavoring substance evaluations govern permissible concentrations and labeling claims.
- Cosmetic:Fragrance formulations and natural preservative systems in personal care lines. French clean-label skincare brands in Paris and Lyon are expanding oleoresin absorption.
- Pharmaceutical:Masking agents for pediatric and geriatric drug formulations with elevated purity requirements. ANSM and Swissmedic alignment on EMA safety assessments is tightening bean grading standards.
- Aroma:Fine fragrance and home scent applications requiring specific aromatic profiles. Swiss and French perfumery houses in Geneva and Grasse specify Tahitensis-derived materials for distinctive floral notes.
Food and beverage dominates current volumes; cosmetic applications show the steepest expansion trajectory.
Customer Type:
Channel structure determines contract terms, with manufacturers locking in multi-year supply while retail and food service operate on shorter procurement cycles.
- Retail:Packaged vanilla products for supermarket and specialty store shelves. French and German retail chains are expanding private-label natural extract offerings.
- Wholesale:Bulk distribution to intermediate processors and regional traders. Amsterdam and Hamburg trading houses remain central nodes despite direct-origin contracting trends.
- Food Service:Restaurants, bakeries, and hospitality operations requiring consistent quality at scale. Belgium's hotel and restaurant sector represents concentrated demand.
- Manufacturers:Industrial formulation houses producing finished consumer goods. Swiss chocolate manufacturers and French dairy processors anchor long-term contracting activity.
Manufacturers command the largest volume share; food service is expanding most quickly as premium dessert culture spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's chocolate belt generates concentrated demand for traceable Madagascar vanilla, with Antwerp specialty makers locking in multi-year offtake agreements to satisfy EUDR documentation requirements.
France
French patisserie and dairy sectors absorb the deepest extract volumes, with Grasse-based extraction facilities serving continental formulation houses. ANSM alignment with EMA purity thresholds diverts premium-grade beans toward pharmaceutical masking applications. Parisian clean-label skincare brands are expanding oleoresin procurement for fragrance formulations.
Germany
German baking premix manufacturers anchor powder-format demand, while Hamburg trading houses retain intermediary roles despite direct-origin contracting trends. REACH registration requirements for synthetic alternatives indirectly reinforce natural extract premiums. Berlin-based natural cosmetics brands are absorbing expanding dry vanilla preparation volumes.
Switzerland
Swiss chocolate manufacturers and fragrance houses in Geneva specify Tahitensis-derived materials for distinctive floral aromatic profiles. Swissmedic-registered Basel facilities represent the primary demand concentration for crystalline vanillin isolates in pharmaceutical applications. Captive extraction capabilities anchor competitive positioning for major flavor houses operating across the Alpine corridor.
Italy
Italian artisan ice cream producers favor paste-format vanilla for premium positioning in gelato and dessert applications. Food service channels are expanding most quickly as premium dessert culture spreads through Milan and Rome hospitality clusters. EFSA flavoring substance evaluations govern permissible concentrations across industrial and artisanal tiers.
Spain
Spanish food service and hospitality operations require consistent quality at scale, with Barcelona and Madrid representing concentrated demand nodes. The country's national food safety authority aligns enforcement with EUDR traceability timelines. Direct farmer partnerships in Papua New Guinea are diversifying procurement portfolios for Spanish distributors.
Europe Vanilla Beans and Extract Market Competitive Landscape
Global majors compete with regional champions across extraction capabilities and origin relationships, producing a tiered structure where captive processing assets determine margin capture. The vendor base clusters around three strategic archetypes: integrated flavor houses with in-house extraction, specialized vanilla traders with direct farmer partnerships, and diversified ingredient conglomerates with portfolio breadth. Competitive moves concentrate on multi-year origin contracting and blockchain-enabled traceability integration to satisfy EUDR compliance requirements.
Within the integrated flavor house tier, Givaudan and Symrise exemplify archetypes anchored by captive European extraction infrastructure. Eurovanille occupies a position representing specialized traders with direct Indian Ocean farmer partnerships. Nielsen-Massey Vanillas sits within the premium artisanal supplier segment, serving Belgian and French chocolatiers with single-origin provenance claims. These three anchors illustrate how competitive positioning diverges between scale-driven formulation supply and traceability-premium artisanal channels.
| Leading Market Players |
|---|
| Nielsen-Massey Vanillas |
| Eurovanille |
| Givaudan |
| Firmenich |
| Kerry |
| Symrise |
| McCormick & Company |
| Borregaard |
| International Flavors & Fragrances (IFF) |
| Others |
Supply & Pricing Matrix
Family-owned curing cooperatives across Madagascar and the Comoros anchor supply-side discipline, passing through cyclone-driven harvest volatility into extract premiums that Belgian and French chocolatiers absorb for EUDR-compliant traceability.
Pricing Analysis
Input-cost pass-through from Madagascar bean prices dominates European extract pricing, with contract-based long-term offtake agreements locking in volume commitments from Swiss and French manufacturers. Price differentiation hinges on certification grade — EUDR-compliant beans command substantial premiums over conventional supply — and volume scale, with industrial formulation houses securing favorable terms through multi-year commitments. Cost compression in mass-market ice cream tiers is intensifying because ethyl vanillin substitutes undercut natural extract on unit economics. Food service channels exhibit highest price sensitivity, while pharmaceutical-grade crystalline isolates face minimal elasticity due to Swissmedic purity mandates.
Supply Chain Analysis
European vanilla supply rests on Madagascar, Uganda, and Papua New Guinea as primary curing origins, with bean quality and vanillin concentration varying sharply across these sources. Raw material dependencies include mature Vanilla planifolia vines, traditional Bourbon curing expertise concentrated in aging farmer populations, and specialized extraction solvents governed by REACH registration. Single-source vulnerability in Madagascar exposes the entire chain to tropical cyclone disruption and subsequent price spikes. Distribution runs through Hamburg and Amsterdam trading houses for spot-market volumes, while direct-origin contracting bypasses intermediaries for premium Belgian and French artisanal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe vanilla market functions as a geographic-arbitrage play between Indian Ocean curing costs and Alpine extraction premiums, with EUDR compliance costs widening the spread between compliant and conventional supply tiers.
For Market Incumbents: Deploy blockchain traceability infrastructure to defend premium positioning against emerging direct-origin competitors. Incumbents should consolidate backward integration into Ugandan curing capacity before first-mover advantages dissipate, while simultaneously investing in segregated warehousing to manage compliant and non-compliant inventory streams under tightening EU Deforestation Regulation enforcement timelines. For New Entrants and Emerging Players: The EU Deforestation Regulation in Europe opens a window for certified-sustainable vanilla specialists to capture share from legacy traders lacking origin documentation. New entrants should target Spanish and Italian food service channels where EUDR awareness lags behind Belgian and French compliance maturity, leveraging direct farmer partnerships in Papua New Guinea as a differentiated sourcing narrative. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap extractors with underdeveloped traceability infrastructure but established Grasse or Hamburg processing assets. Long-term viability favors targets with captive curing relationships across multiple origins, with the signal to watch being accelerated consolidation among Amsterdam trading houses unable to fund compliance system investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ugandan Curing | First-mover positioning in underdeveloped East African origin secures EUDR-compliant supply ahead of competitors. |
| Blockchain Traceability Deployment | Grasse and Swiss extraction facilities embed compliance documentation directly into procurement workflows. |
| Multi-Year Farmer Partnership Agreements | Antwerp chocolatiers lock in Madagascar bean supply with deforestation-free batch verification for premium positioning. |
| Dry Format Capacity Expansion | German cosmetics brands absorb spray-dried vanilla preparations as clean-label personal care lines proliferate. |
| Pharmaceutical-Grade Isolation Investment | Swissmedic-registered Basel facilities capture crystalline vanillin demand for pediatric drug masking applications. |
Research Methodology
Direct dialogue with vanilla extraction facility managers, Madagascar cooperative leadership, Belgian chocolatier procurement directors, EUDR compliance officers at French dairy processors, and Hamburg trading house operators grounded qualitative findings. Secondary validation drew from customs and trade data, EFSA flavoring substance evaluations, EU Deforestation Regulation implementation guidance, and REACH chemical registration databases. Bottom-up bean volume estimates from origin countries triangulated against top-down extract consumption patterns across European formulation houses.
Bottom-up modeling of curing capacity and extraction throughput across the projection horizon anchored volume forecasts, while value projections incorporated tiered pricing by certification status and application purity requirements. Segmentation dimensions spanned product type, physical form, end-use sector, and customer channel, with CAGRs derived from historical volatility patterns in Madagascar harvest cycles and forward regulatory compliance cost trajectories. Forecast inputs included cyclone frequency assumptions and EUDR enforcement timeline acceleration scenarios.
Revisions become necessary when Madagascar harvest disruption exceeds historical cyclone patterns, when EUDR enforcement timelines compress faster than supplier audit capacity, or when synthetic vanillin alternatives achieve cost parity through process innovation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein Glycomacropeptide Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
US Choline Bitartrate Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Global Amaranth Oil Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Plant Based Premix Market
Ingredients
Cold Pressed Oil Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Glucuronolactone Market