
 Pet Food Premix Market | 2026-2036
Pet Food Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Premix Market Insights
Buyer concentration among contract manufacturers and co-packers is rebalancing as direct-to-consumer pet food brands fragment the customer base. dsm-firmenich leverages its human-nutrition micronutrient heritage to dominate high-potency vitamin premixes for premium positioning. Cargill anchors North American supply through backward integration into amino acid and vitamin manufacturing. Alltech competes on yeast-derived bioactive platforms that differentiate natural-positioned brands from synthetic premix alternatives.
Pet food premix denotes a precisely blended concentrate of vitamins, minerals, amino acids, enzymes, or probiotics, typically dosed at 0.5% to 3.0% of finished feed weight, manufactured via multi-stage micro-dosing and homogeneous mixing to ensure nutrient uniformity across production batches. Its commercial purpose centers on enabling pet food manufacturers to achieve target nutritional profiles without managing dozens of individual raw material supply chains. Vitamin premixes occupy the largest value share due to heat-labile actives requiring stabilization expertise, while probiotic premixes represent the fastest-expanding margin pool as live-microbe shelf-life technology matures. Mineral premixes sustain steady volume through cost-sensitive mainstream kibble formulations where calcium, phosphorus, and trace element compliance drives baseline demand.
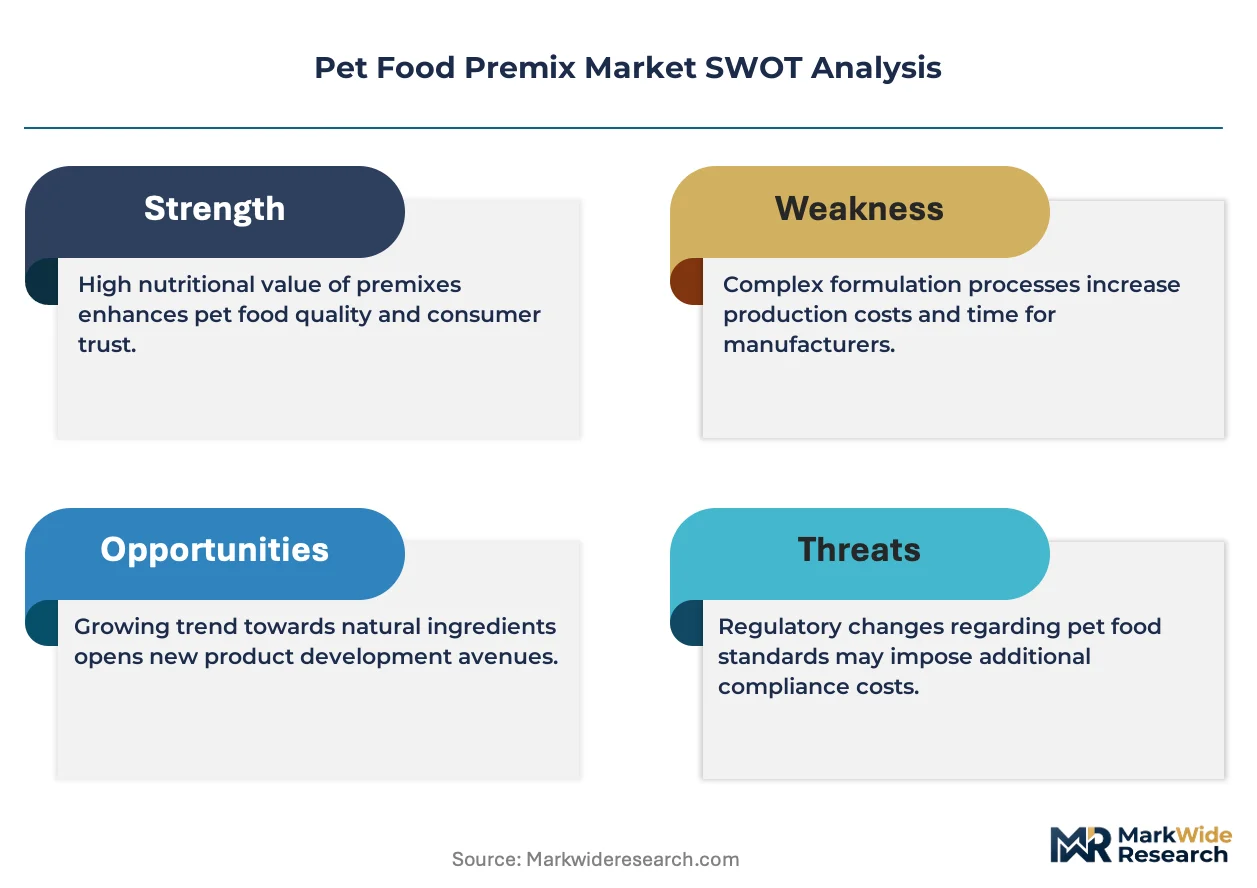
FDA Center for Veterinary Medicine oversight of pet food labeling and ingredient safety, combined with AAFCO nutrient profile standards and state-level feed regulatory programs, elevates compliance costs for premix suppliers while creating barriers against unverified imports. The National Animal Supplement Council's quality seal and ISO 22000 certification requirements further shape customer procurement criteria. Stakeholders must monitor how evolving clean-label demands interact with regulatory nutrient minimums, since reformulation for shorter ingredient decks risks falling below mandated vitamin and mineral thresholds.
Market Dynamics
Pet food premix formulation is undergoing forced recalibration as the FDA Center for Veterinary Medicine tightens ingredient verification protocols and AAFCO updates nutrient adequacy profiles, compelling manufacturers to reformulate for compliance while preserving clean-label positioning.
Growth Catalysts
- AAFCO Nutrient Profile Updates:Revised canine and feline nutritional standards are driving reformulation cycles, expanding demand for precision-blended vitamin and mineral premixes that guarantee compliance across production batches.
- Pet Humanization Trajectory:Companion animal owners now apply human-grade nutritional expectations to pet diets, elevating procurement of bioactive-enriched premixes by super-premium kibble and fresh food producers.
- Probiotic Shelf-Life Technology:Advances in live-microbe stabilization and encapsulation are unlocking viable probiotic premix formats, creating new margin pools as natural-positioned brands seek differentiation from synthetic alternatives.
Market Restraints
- Vitamin Raw Material Concentration:China dominates bulk vitamin B and D3 manufacturing, exposing premix suppliers to supply disruption risks and input cost volatility from tariff and logistics fluctuations.
- Heat-Labile Nutrient Degradation:Vitamin A, thiamine, and certain probiotics suffer substantial activity loss during extrusion and retort processing, requiring expensive stabilization technologies that compress margins.
- State-Level Feed Regulatory Fragmentation:Individual state feed control programs impose non-uniform registration and labeling requirements, multiplying compliance burden for premix suppliers serving national pet food manufacturers.
Strategic Opportunities
- Insect Protein Premix Integration:Novel protein sources from black soldier fly and mealworm operations are creating demand for customized amino acid premixes to balance novel protein nutritional profiles.
- Veterinary Therapeutic Diets:Prescription pet food channels are expanding, requiring condition-specific premix formulations for renal, diabetic, and gastrointestinal therapeutic segments.
- Direct-to-Consumer Brand Proliferation:Subscription-based fresh pet food startups are bypassing contract manufacturers, creating direct premix procurement relationships with smaller order quantities but premium pricing tolerance.
Industry Challenges
- Micro-Dosing Precision Engineering:Achieving homogeneous distribution of trace minerals at 0.5-3.0% inclusion rates demands capital-intensive multi-stage mixing equipment and rigorous quality control protocols.
- Dual Certification Burden:Premix suppliers must simultaneously maintain ISO 22000 food safety certification and National Animal Supplement Council quality seals, extending validation timelines and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Premix Market |
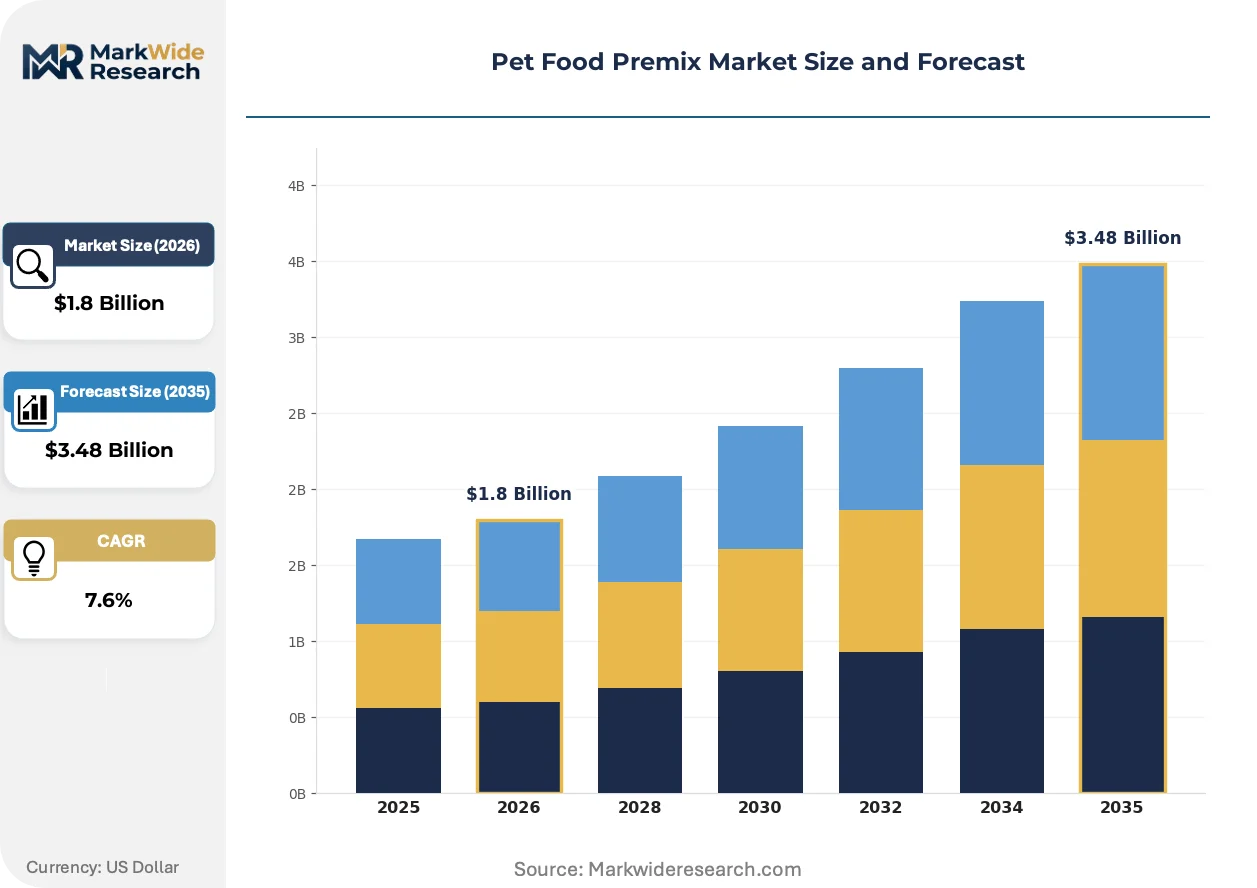
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Premixes, Mineral Premixes, Amino Acid Premixes, Enzyme Premixes, Probiotic Premixes Application: Dog Food, Cat Food, Fish Food, Bird Feed, Small Mammal Feed End User: Pet Food Manufacturers, Specialty Feed Producers, Veterinary Clinics, Animal Breeders Packaging Type: Bagged, Boxed, Bulk Containers, Sachets, Drums |
| Companies Covered | Archer Daniels Midland, dsm-firmenich, Cargill, BASF, Alltech, Kemin Industries, Zinpro, Adisseo, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Premix Market Trends and Innovations
Digital formulation platforms and precision fermentation are converging to reshape premix specification workflows, while regulatory transparency mandates and shifting buyer procurement models are reconfiguring commercial relationships across the value chain.
Precision fermentation-derived nutrients are decentralizing premix supply structures by enabling regional production of bio-identical vitamins and amino acids previously concentrated in petrochemical-based manufacturing hubs. Mid-sized pet food brands in the United States and Western Europe are adopting these fermentation inputs to shorten supply chains and secure clean-label positioning. This distributed production model is compressing historical reliance on Asian bulk vitamin imports.
EFSA transparency requirements and FDA ingredient verification mandates are forcing premix suppliers to maintain comprehensive raw material traceability documentation from source to finished blend. The regulatory burden falls heaviest on vitamin premix categories where heat-labile actives require complex stabilization and sourcing records. European suppliers are responding by investing in blockchain-enabled supply chain tracking systems.
Buyer concentration among legacy contract manufacturers is fragmenting as direct-to-consumer pet food brands build in-house formulation capabilities and establish direct premix procurement relationships. Fresh and raw pet food startups in urban coastal markets are displacing volume-driven kibble procurement models with smaller-batch, higher-frequency premix orders. This channel shift is most pronounced in the United States where subscription pet food services concentrate in metropolitan corridors.
Pet Food Premix Market Segmentation
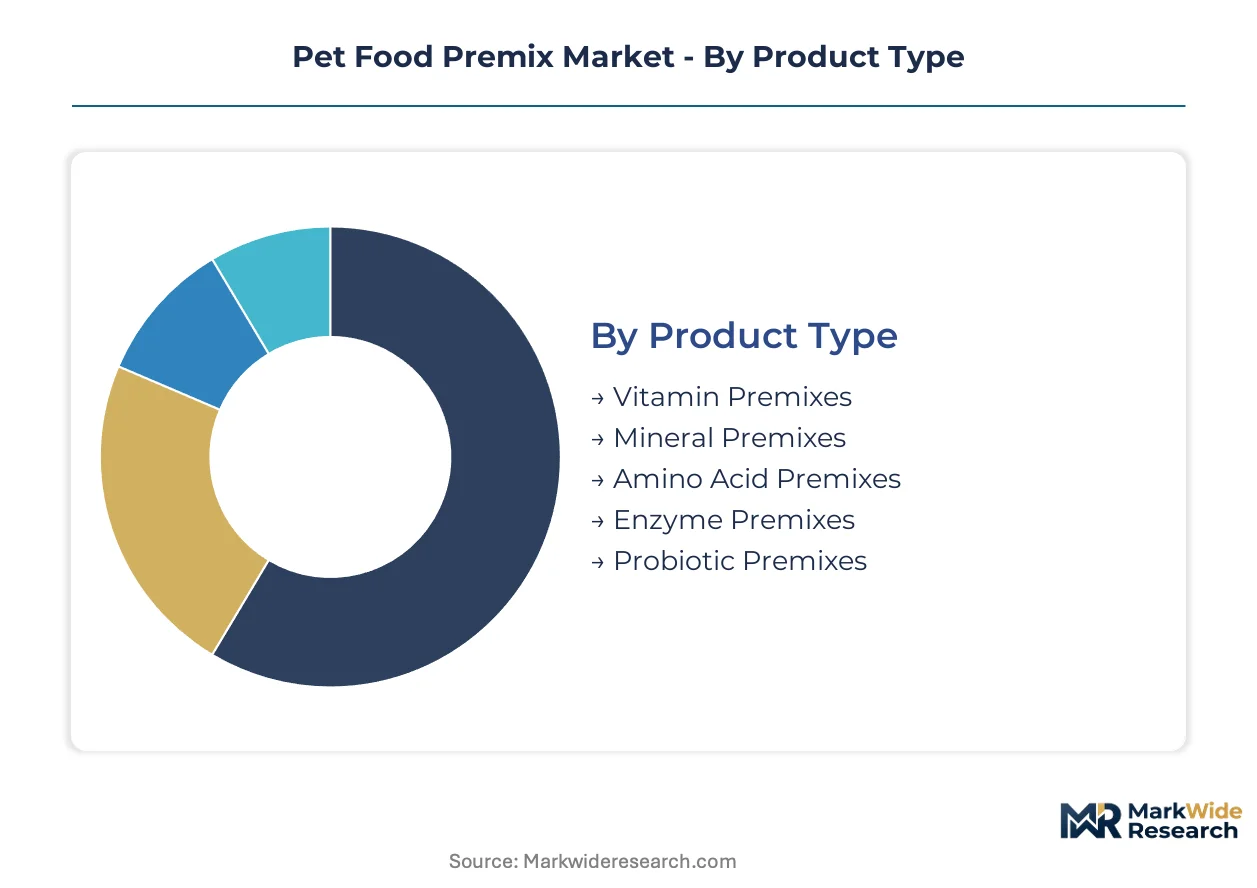
Segmentation in the pet food premix market reflects divergent compliance burdens, formulation complexity, and procurement economics across product categories and customer types. Understanding these divisions enables suppliers to align certification investments with margin potential and target reformulation cycles where regulatory pressure concentrates.
Product Type:
Vitamin premixes carry the heaviest dual-certification load, requiring ISO 22000 food safety validation alongside National Animal Supplement Council quality seals due to heat-labile actives demanding stabilization documentation. Mineral premixes face lighter regulatory scrutiny but must satisfy state-level feed control program variations across jurisdictions. Amino acid, enzyme, and probiotic categories occupy intermediate compliance tiers with emerging transparency mandates from EFSA and FDA ingredient verification protocols.
- Vitamin Premixes:Concentrated blends of fat-soluble and water-soluble vitamins requiring micro-encapsulation and coating technologies to survive extrusion temperatures. Demand concentrates among super-premium kibble producers in the United States seeking AAFCO nutrient profile compliance without sourcing dozens of individual raw materials. Heat degradation of vitamin A and thiamine during processing elevates technical service requirements and customer stickiness.
- Probiotic Premixes:Live-microbe concentrates stabilized through spray-drying, freeze-drying, or lipid encapsulation to maintain colony-forming unit counts through shelf life. Fresh pet food startups in urban coastal markets drive procurement as natural-positioned brands differentiate from synthetic alternatives. Advances in shelf-life technology are compressing historical viability constraints that limited commercial deployment.
- Mineral Premixes:Standardized calcium, phosphorus, and trace element blends for cost-sensitive mainstream formulations.
- Amino Acid Premixes:Precision-blended lysine, methionine, and taurine supplements for novel protein balancing.
- Enzyme Premixes:Phytase and protease additives targeting digestibility enhancement in high-fiber or alternative protein diets.
Leading the category by volume: Vitamin Premixes. Growing fastest: Probiotic Premixes.
Application:
Cost tier stratification separates applications by formulation sophistication and price elasticity, with therapeutic and premium positioning commanding disproportionate premix investment relative to tonnage.
- Dog Food:The largest application by absolute volume, spanning economy kibble through veterinary prescription diets. Canine therapeutic segments for renal, diabetic, and gastrointestinal conditions require condition-specific premix formulations with elevated micronutrient precision. Super-premium positioning in the United States drives bioactive-enriched procurement including omega fatty acids and joint-support compounds.
- Cat Food:Obligate carnivore physiology mandates taurine fortification and precise arachidonic acid balancing unavailable from plant-based inputs alone. Premium wet food and fresh formats in metropolitan corridors concentrate demand for high-potency vitamin premixes with shorter ingredient decks. Feline therapeutic diets for urinary and renal health command specialized mineral premix specifications.
- Fish Food:Aquaculture-derived and ornamental segments with distinct amino acid profiles for carnivorous versus herbivorous species.
- Bird Feed:Avian-specific vitamin A and D3 requirements with sensitivity to oversupplementation toxicity.
- Small Mammal Feed:Niche formulations for rabbits, guinea pigs, and ferrets with species-specific digestive adaptations.
Dominant by tonnage: Dog Food. Steepest expansion trajectory: Cat Food fresh and raw segments.
End User:
Customer type determines order frequency, batch size tolerance, and technical service intensity, fragmenting historically concentrated contract manufacturer procurement.
- Pet Food Manufacturers:Volume-driven procurement through legacy contract manufacturing relationships with quarterly or semi-annual tender processes. National brands require premix suppliers to navigate state-level feed regulatory fragmentation for multi-jurisdiction distribution. Technical specifications emphasize batch-to-batch uniformity and comprehensive Certificate of Analysis documentation.
- Specialty Feed Producers:Boutique operations serving premium companion animal diets with smaller order quantities but elevated pricing tolerance for customization. Direct-to-consumer brand proliferation is bypassing traditional contract manufacturers, creating direct premix procurement relationships with weekly or biweekly replenishment cycles. These buyers prioritize formulation flexibility and rapid turnaround over scale economies.
- Veterinary Clinics:Prescription diet dispensing with therapeutic-grade premix requirements and clinical outcome documentation.
- Animal Breeders:Performance-focused nutrition for reproductive health and neonatal development in commercial breeding operations.
Largest volume channel: Pet Food Manufacturers. Gaining share fastest: Specialty Feed Producers.
Packaging Type:
Supply concentration in bulk formats versus fragmentation in unitized packaging reflects divergent customer scale and inventory turnover requirements.
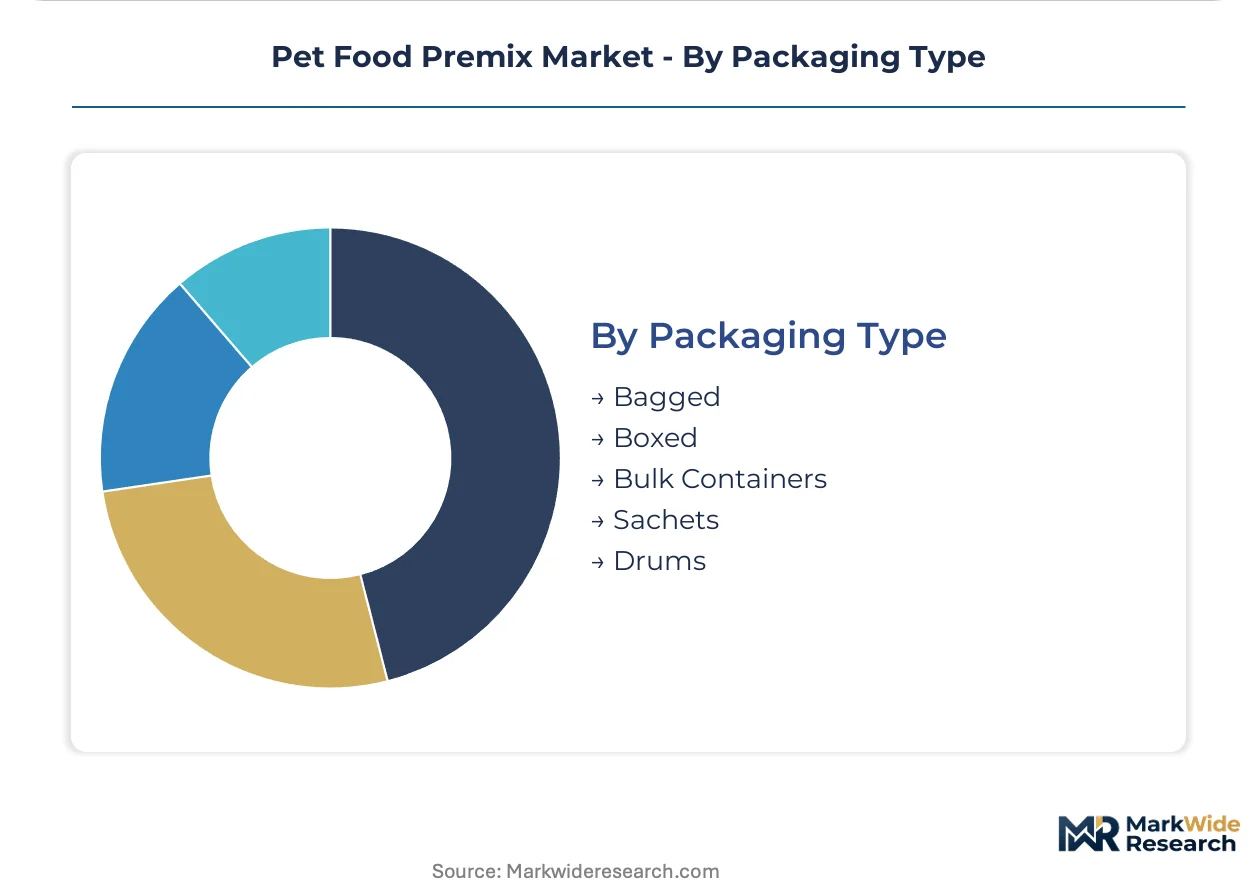
- Bulk Containers:Tote bins and flexible intermediate bulk containers for high-volume manufacturers with rapid throughput and silo storage infrastructure. Standardized in North American contract manufacturing where single premix SKUs feed continuous extrusion lines. Logistics optimization favors regional premix blending facilities to minimize freight cost per nutrient unit.
- Bagged:Multi-wall paper or woven polypropylene sacks for mid-scale operations with moderate batch frequencies and warehouse stacking requirements. Fresh pet food startups in subscription models favor smaller bagged quantities with lot-specific traceability codes. Packaging specification includes moisture barriers critical for hygroscopic vitamin stability.
- Drums:Steel or fiber drums for liquid premixes and specialty additives requiring sealed containment.
- Boxed:Corrugated cases with inner liners for retail-scale or sample quantities.
- Sachets:Single-use foil packets for precision dosing in small-batch or trial formulations.
Highest throughput format: Bulk Containers. Expanding most quickly: Bagged configurations for DTC brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Super-premium kibble and fresh pet food brands in the United States command disproportionate premix procurement volumes, while specialty feed producers across Western Europe and East Asia accelerate procurement as pet humanization deepens in their domestic markets.
United States
Subscription-based fresh pet food startups in metropolitan corridors drive smaller-batch, higher-frequency premix orders with premium pricing tolerance. FDA Center for Veterinary Medicine oversight of pet food labeling and ingredient safety elevates compliance costs for premix suppliers. Greater Boston and Pacific Northwest clusters concentrate direct-to-consumer brand headquarters establishing direct premix procurement relationships.
Germany
Mid-sized pet food brands adopt precision fermentation-derived nutrients to shorten supply chains and secure clean-label positioning. EFSA transparency requirements force premix suppliers to maintain comprehensive raw material traceability documentation from source to finished blend. Bavaria's industrial feed additive corridor hosts blockchain-enabled supply chain tracking system investments.
China
Bulk vitamin B and D3 manufacturing concentration exposes premix suppliers to supply disruption risks and input cost volatility from tariff fluctuations. The country's national feed safety regulator imposes evolving ingredient verification standards on imported premix formulations. Yangtze River Delta pet food manufacturing clusters rely on domestic mineral premix production for cost-sensitive mainstream kibble formulations.
Japan
Obligate carnivore physiology in feline diets mandates taurine fortification and precise arachidonic acid balancing unavailable from plant-based inputs alone. METI industrial standards shape quality certification requirements for imported bioactive premix ingredients. Kanto region super-premium pet food producers procure high-potency vitamin premixes with shorter ingredient decks for metropolitan consumers.
Brazil
Novel protein sources from black soldier fly and mealworm operations create demand for customized amino acid premixes to balance alternative protein nutritional profiles. ANVISA veterinary product oversight extends to therapeutic pet food ingredient verification. São Paulo state industrial feed complexes integrate South American amino acid manufacturing with premix blending operations.
Pet Food Premix Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioactive specialization and direct-to-consumer channel alignment. The supplier base stratifies across human-nutrition heritage conglomerates, agricultural commodity integrators, and yeast-derived bioactive specialists. Three archetypes dominate: micronutrient technology licensors, backward-integrated amino acid manufacturers, and natural-positioned fermentation platforms. Capacity expansion in regional blending facilities and strategic partnerships with precision fermentation startups constitute the primary competitive moves.
Among diversified nutrition conglomerates, dsm-firmenich and Cargill exemplify contrasting scale strategies. The Dutch-Swiss entity leverages human-nutrition micronutrient heritage, while the Minneapolis-based agricultural giant anchors North American supply through captive amino acid and vitamin manufacturing. BASF represents the German chemical conglomerate archetype with petrochemical-based vitamin production integration.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| dsm-firmenich |
| Cargill |
| BASF |
| Alltech |
| Kemin Industries |
| Zinpro |
| Adisseo |
| Evonik Industries |
| Others |
Pricing and Supply Chain Analysis
Micro-dosing precision engineering expertise concentrates in the Netherlands and Switzerland, where labor-cost differentials between these specialized European hubs and Asian blending facilities widen pricing-tier spreads across vitamin premix grades. FDA and AAFCO compliance investments at Western facilities command substantial premiums over baseline mineral premixes sourced from cost-optimized Yangtze River Delta operations.
Pricing Analysis
Volume-driven mainstream mineral premixes trade at compressed margins through contract manufacturing channels, while super-premium vitamin and probiotic categories capture pricing premiums from direct-to-consumer brands. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified therapeutic formulations from state-feed-registered commodity blends. Price differentiation hinges on heat-labile nutrient stabilization documentation and National Animal Supplement Council quality seals. Pricing pressure stems from China-dominant vitamin B and D3 raw material volatility, with specialty feed producers showing least price sensitivity due to premium positioning tolerance.
Supply Chain Analysis
ISO 22000 and National Animal Supplement Council certification gating restricts viable supplier pools to established Western and East Asian producers with multi-year audit track records. Bulk vitamin manufacturing concentrates in China, with secondary supply nodes in Germany and Switzerland for fermentation-derived alternatives. Raw material dependencies span petrochemical-based vitamins, yeast-derived bioactives, and novel protein amino acid feedstocks. Single-source vulnerability in Chinese vitamin B complexes exposes premix blenders to tariff and logistics disruption. Distribution runs through regional blending facilities serving metropolitan pet food manufacturing clusters with just-in-time replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet food premix market functions as a vertical-integration race where captive amino acid and vitamin manufacturing capabilities determine margin capture against raw material volatility. Players are pursuing upstream control over fermentation-derived nutrient platforms to decouple from Asian bulk vitamin dependencies.
For Market Incumbents: Extend precision fermentation partnerships into captive bio-identical vitamin production, securing supply chain autonomy against Chinese import volatility. Deepen technical service relationships with direct-to-consumer brands through rapid-turnaround formulation support, defending share against emerging regional blenders. Prioritize blockchain-enabled traceability investments to preempt EFSA and FDA transparency mandates.
For New Entrants and Emerging Players: Subscription-based fresh pet food startups represent the most penetrable channel, bypassing legacy contract manufacturer procurement concentration. Target urban coastal metropolitan corridors with smaller-batch, higher-frequency premix logistics capabilities. Pursue go-to-market alignment through veterinary therapeutic diet partnerships, where condition-specific formulation requirements create stickier customer relationships.
For Investors and Strategic Acquirers: The window for entry favors precision fermentation platforms with demonstrated commercial-scale amino acid or vitamin production. Long-term viability rests on supply chain regionalization trends compressing historical Asian import dependence. Watch for FDA ingredient verification mandate enforcement intensity as the inflection signal for compliance-capable asset premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Decentralizes vitamin supply from Chinese petrochemical dominance toward regional bio-identical production. |
| Blockchain Traceability Implementation | Meets EFSA transparency mandates and FDA verification protocols for heat-labile active documentation. |
| Direct-to-Consumer Channel Partnerships | Captures premium pricing tolerance from subscription fresh pet food brands in metropolitan corridors. |
| Therapeutic Diet Formulation Development | Accesses prescription pet food channels requiring renal, diabetic, and gastrointestinal condition-specific premixes. |
| Regional Blending Facility Expansion | Reduces freight cost per nutrient unit for high-volume contract manufacturers with continuous extrusion lines. |
Research Methodology
Independent corroboration across premix formulation chemists, pet food manufacturing procurement directors, and veterinary nutrition specialists underwrites the qualitative findings. Primary interviews with FDA Center for Veterinary Medicine compliance officers, AAFCO nutrient profile committee participants, and state feed control program administrators supplied regulatory trajectory insights. Secondary validation drew from FDA ingredient verification guidance documents, AAFCO official publication updates, National Animal Supplement Council quality seal audit records, and ISO 22000 certification registries. Bottom-up segmentation modeling triangulated against top-down industry association volume estimates.
Rate-of-change decomposition across the analysis window separated volume expansion from value-per-ton escalation drivers. The analytical framework modeled product type segmentation, application cost-tier stratification, end-user procurement pattern fragmentation, and packaging format logistics economics. CAGRs derived from regression analysis against pet humanization expenditure indices and regulatory reformulation cycle frequencies. Industry-specific forecast inputs incorporated AAFCO nutrient profile update implementation timelines and precision fermentation commercialization maturity curves.
Caveats apply where FDA enforcement intensity, Chinese vitamin export policy shifts, or probiotic shelf-life technology breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding sustained pet humanization expenditure growth and stable state-level feed regulatory fragmentation. A model refresh is warranted upon material change in AAFCO nutrient adequacy profile revision schedules or precision fermentation cost-parity achievement against petrochemical vitamin benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
North America Potato Protein Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Organic Starch Market
Ingredients
Amylase Market
Ingredients
Beef Concentrate Market
Ingredients
Yeast Autolysates Market
Ingredients
Protein Hydrolysate Market
Ingredients
US Plant-Based Oils Market
Ingredients
Lupin Flour Market
Ingredients
Chewing Gum Base Market
Ingredients
Europe Malt Extract Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market