
 China Floor Covering Market | 2026-2036
China Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
China Floor Covering Market Outlook
China's GB standards for formaldehyde emissions in wood-based panels is shifting compliance costs toward larger manufacturers with in-house testing labs. Power Dekor leverages captive resin production to absorb these regulatory burdens. Der International sustains premium positioning through FSC-certified supply chains. Yangzi Flooring anchors volume competitiveness across central China through distributed manufacturing.
Floor covering comprises surface materials installed over structural subfloors to provide wear resistance, acoustic dampening, and aesthetic finish; laminate products employ high-density fiberboard cores with aluminum oxide wear layers rated AC3-AC5 for residential and commercial traffic respectively. Tiles command the largest value share due to porcelain durability in humid southern climates, while vinyl surfaces represent the fastest-expanding category as click-lock installation displaces traditional glue-down methods in renovation projects. Natural fiber materials retain niche premium positioning despite PVC cost advantages in mass residential applications.
China's SAMR enforces product quality certification for flooring imports, while MEE oversight of VOC emissions during manufacturing shapes plant location decisions near urban demand centers. The country's dual carbon goals compel manufacturers to source lower-emission adhesives and recycled PVC content. Stakeholders must monitor evolving GB standard revisions and carbon intensity benchmarks to anticipate which production configurations will retain market access.
Market Dynamics
China's dual carbon goals are forcing manufacturers to reconfigure resin chemistry and sourcing footprints ahead of tightening MEE emissions benchmarks. This regulatory compression favors capital-heavy producers with captive testing infrastructure and distributed plant networks.
Growth Catalysts
- Tier-two residential renovation:Property upgrading across Hangzhou, Nanjing, and Chengdu is generating replacement demand for moisture-resistant surfaces. Local distributors report accelerating specification of click-lock vinyl in secondary city housing stock.
- GB standard formaldehyde limits:Stricter wood-based panel emission thresholds are filtering out small workshops. Compliance investments concentrate volume among manufacturers with in-house certification labs.
- Yangtze River Delta cluster concentration:Shanghai-Suzhou logistics density enables just-in-time resin delivery and same-day sample turnaround for specification architects.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with naphtha cracking margins. Manufacturers without backward integration into basic chemicals absorb margin compression directly.
- Southern porcelain lock-in:Humid climate zones around Guangzhou and Shenzhen exhibit high switching costs from ceramic tile due to embedded contractor expertise and homeowner familiarity.
- SAMR import certification friction:Overseas flooring brands face extended product quality approval timelines. Documentation requirements for VOC testing and origin tracing delay market entry by quarters.
Strategic Opportunities
- Central China manufacturing expansion:Hubei and Henan provinces offer lower industrial electricity rates and proximity to growing Wuhan-Zhengzhou demand corridors. Greenfield sites can incorporate carbon-capture adhesive systems from commissioning.
- Recycled PVC content mandates:Anticipated MEE circular economy directives will create preferential procurement status for post-consumer feedstock integration. Early movers secure waste supply agreements with demolition contractors.
- SpC flooring specification:Stone-polymer composite surfaces are penetrating commercial renovation for healthcare and education verticals. Rigid core construction satisfies heavy traffic wear ratings without subfloor remediation.
Industry Challenges
- Adhesive formulation talent scarcity:Low-VOC polyurethane and bio-based binder chemistry requires polymer scientists with cross-training in emissions testing protocols. Compensation premiums in the Yangtze Delta outbid interior competitors.
- Carbon accounting system integration:Manufacturers must deploy supply chain traceability software to document Scope 3 resin emissions. Legacy ERP platforms lack module compatibility with MEE reporting formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Floor Covering Market |
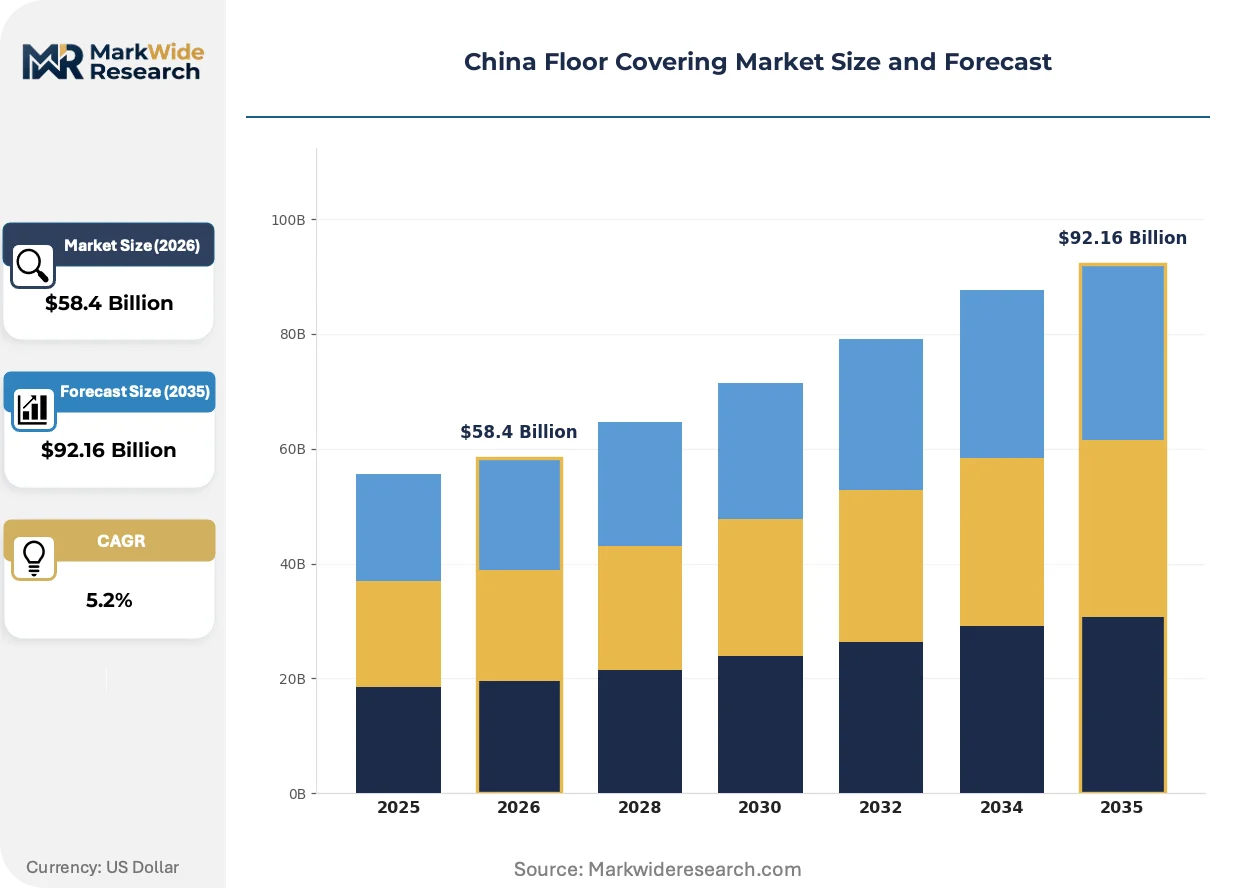
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Laminate, Vinyl, Tiles Material: Natural Fiber, Synthetic Fiber, Wood, PVC Installation Type: Glue-down, Floating, Click-lock, Loose Lay End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Yangzi Flooring, Der International, Power Dekor, DECNO, Changlongflor, Kentier, Nature Home, Shanghai Cimic Tiles, Anxin Flooring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Floor Covering Market Strategic Shifts
Digital specification tools and material traceability systems are compressing the architect-to-manufacturer feedback loop. Surface chemistry innovations now pivot on emissions performance rather than durability alone.
Water-based UV coating technology is unifying finish durability with near-zero VOC output during factory application. Specification architects in Shanghai commercial towers are mandating this chemistry for LEED-equivalent projects. The technology is compressing the competitive gap between laminate and engineered wood premium positioning.
China's MEE is tightening carbon intensity benchmarks for adhesive manufacturing in 2025-2026 compliance windows. Plants in Jiangsu province face retrofit deadlines for solvent recovery systems. Flooring manufacturers with captive resin operations are accelerating capital deployment ahead of enforcement waves.
Buying committees at state-owned property developers are unbundling flooring specification from general contractor packages. Direct manufacturer relationships now govern material selection for Xiong'an New Area and similar government-directed projects. This pattern concentrates volume among domestic suppliers with dedicated specification engineering teams.
China Floor Covering Market Segmentation
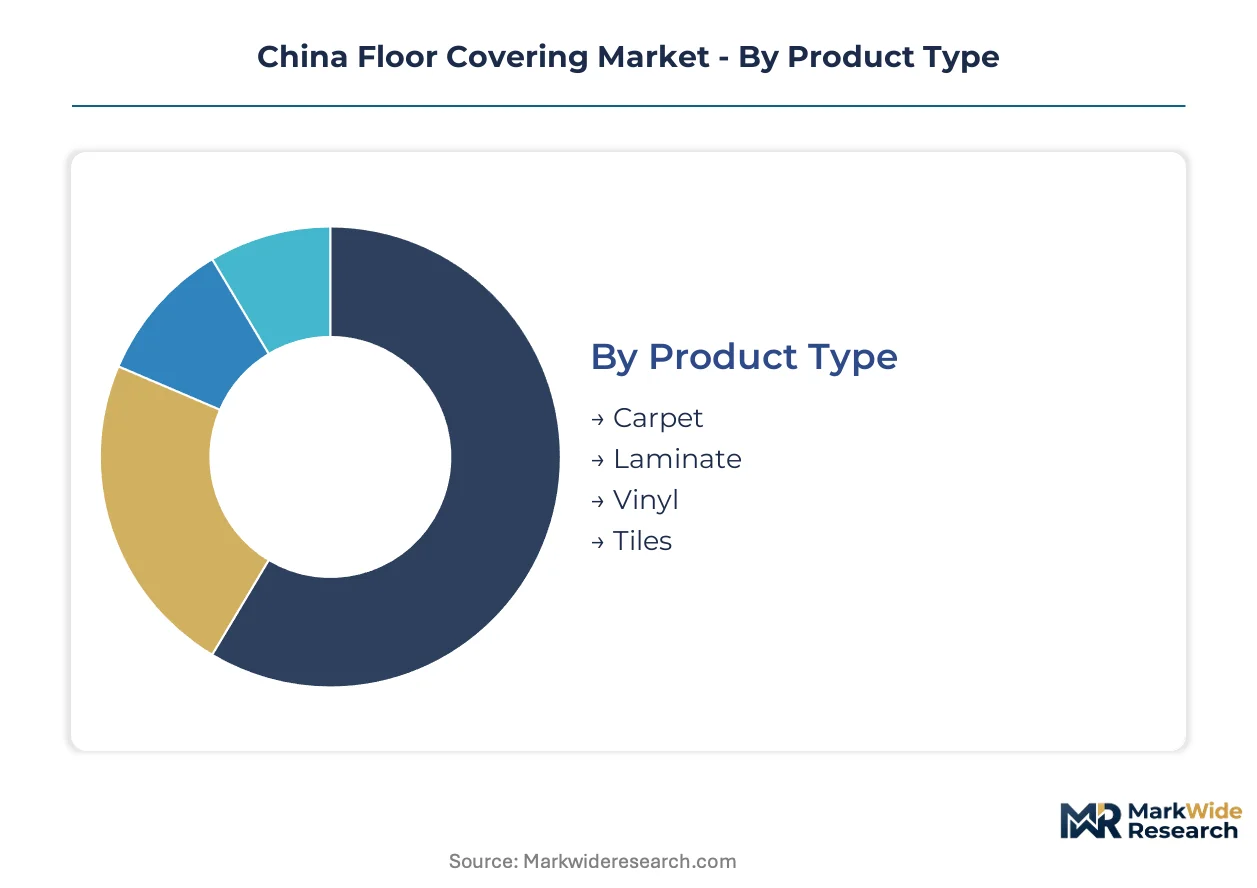
Segmentation in China's floor covering market reveals how material chemistry, installation mechanics, and end-use durability requirements split procurement decisions. Regulatory pressure on VOC emissions and the Yangtze River Delta's logistics density amplify differences between volume and premium tiers.
Product Type:
Tiles dominate by absolute volume while vinyl climbs fastest on renovation convenience.
- Tiles:Porcelain and ceramic surfaces withstand humid southern climates without subfloor remediation. Guangzhou and Shenzhen contractors specify tiles for residential wet areas due to embedded installation expertise and homeowner familiarity with grout maintenance.
- Vinyl:Rigid core and luxury vinyl tile formats employ click-lock systems that accelerate renovation timelines in tier-two housing stock. Hangzhou and Chengdu distributors report accelerating replacement of aging laminate with moisture-resistant vinyl in secondary city apartments.
- Laminate:High-density fiberboard cores with aluminum oxide wear layers serve cost-conscious residential segments. AC3-AC5 durability ratings distinguish residential from commercial traffic applications.
- Carpet:Broadloom and modular formats retain commercial hospitality specification. Natural fiber variants command premium positioning in boutique hotel lobbies despite PVC cost advantages.
Today's leader: Tiles. Tomorrow's challenger: Vinyl.
Material:
Petrochemical-derived inputs face carbon intensity scrutiny while wood-based panels absorb compliance costs.
- PVC:Resin and plasticizer formulations enable waterproof rigid core construction. MEE circular economy directives are pressuring manufacturers to secure post-consumer feedstock agreements with demolition contractors ahead of recycled content mandates.
- Wood:Engineered and solid hardwood surfaces carry FSC certification premiums. GB standard formaldehyde emission thresholds filter volume toward manufacturers with captive resin production and in-house testing laboratories.
- Synthetic Fiber:Nylon and polypropylene face yarns serve commercial carpet applications. Stain resistance chemistry differentiates specification for healthcare and education verticals.
- Natural Fiber:Wool and sisal surfaces occupy niche premium positioning. Limited supply elasticity constrains volume expansion despite sustainability marketing advantages.
Cost leadership sits with PVC. Certification premiums attach to wood.
Installation Type:
Mechanical fastening systems are displacing chemical adhesion on renovation speed and MEE emissions grounds.
- Click-lock:Tongue-and-groove profiles enable floating installation without subfloor preparation. This system is expanding most quickly in tier-two residential renovation where homeowners prioritize same-day completion.
- Glue-down:Full-spread adhesive application demands flat subfloors and extended cure times. VOC emission regulations in Jiangsu province are accelerating capital deployment into water-based adhesive chemistry.
- Floating:Underlayment-cushioned systems reduce sound transmission in multi-family housing. Shanghai commercial towers specify floating engineered wood for LEED-equivalent acoustic performance.
- Loose Lay:Friction-backed surfaces suit temporary commercial installations. Exhibition and retail pop-up applications drive intermittent demand without structural adhesion.
Speed favors click-lock. permanence still requires glue-down.
End User:
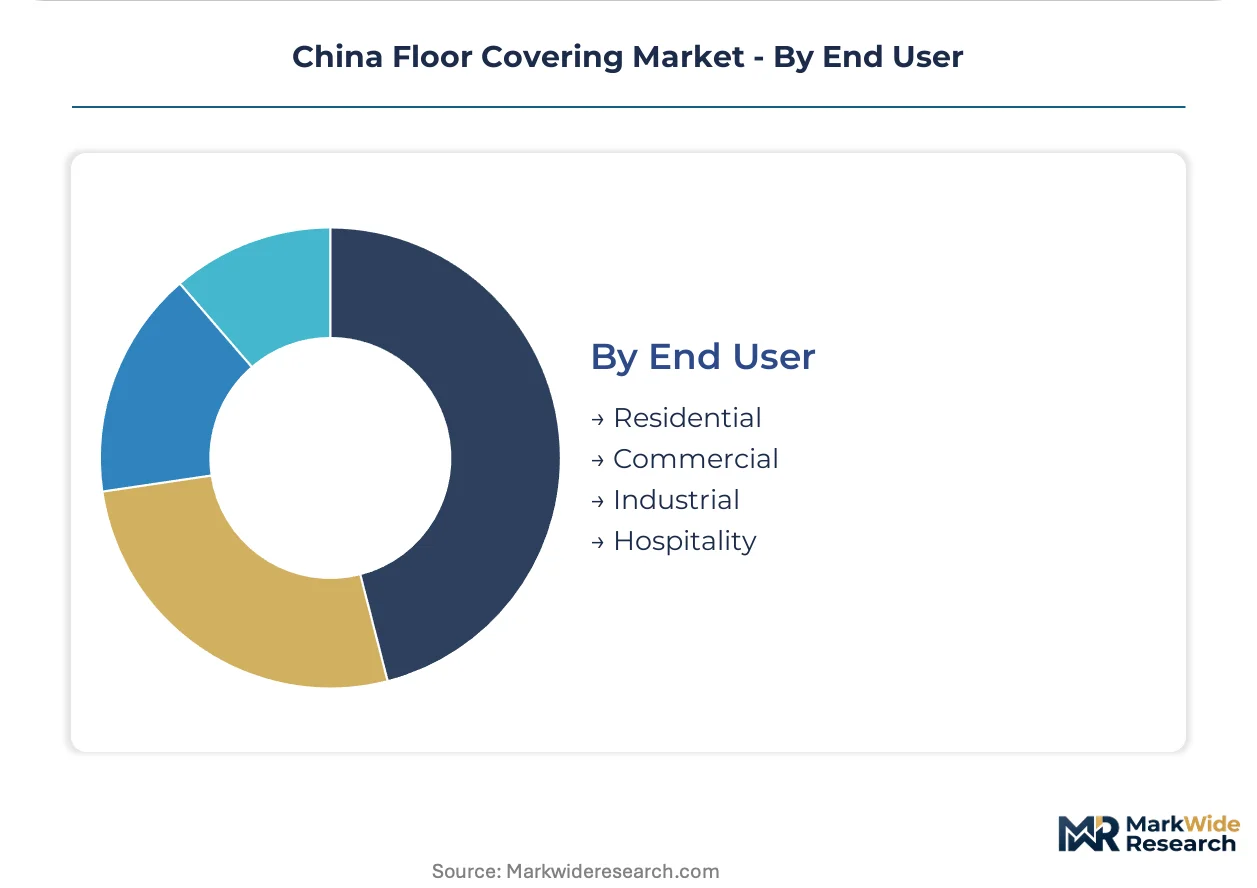
State-owned developer procurement unbundling is concentrating volume among domestic suppliers with specification engineering teams.
- Residential:Property upgrading across Nanjing and Wuhan generates replacement surface demand. Local distributors report specification shifting toward moisture-resistant formats in aging housing stock.
- Commercial:Office and retail fit-outs prioritize rapid installation and heavy traffic durability. Stone-polymer composite surfaces penetrate healthcare and education verticals with rigid core wear ratings.
- Hospitality:Hotel lobbies and corridors balance aesthetic finish with stain resistance. Buying committees at state-directed projects like Xiong'an New Area now govern material selection through direct manufacturer relationships.
- Industrial:Warehouse and manufacturing floors demand chemical resistance and load-bearing capacity. Epoxy-modified surfaces compete with polished concrete on lifecycle cost.
Residential commands volume scale. Commercial drives specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's floor covering industry traces its modern scale to state-led industrialization in the 1990s, when Jiangsu and Zhejiang provinces established specialized manufacturing zones for wood processing and ceramic production. Today, production concentrates in four distinct regional clusters shaped by raw material access, logistics infrastructure, and regulatory enforcement intensity.
Yangtze River Delta
Shanghai and Suzhou anchor the nation's highest-value flooring specification corridor. SAMR product quality certification requirements filter import competition, while MEE emissions oversight accelerates capital deployment into water-based adhesive chemistry. Just-in-time resin delivery networks enable same-day sample turnaround for commercial architects specifying stone-polymer composite surfaces.
Pearl River Delta
Guangzhou and Shenzhen contractors exhibit high switching costs from ceramic tile due to embedded installation expertise and humid climate suitability. Dual carbon goals pressure local manufacturers to source lower-emission adhesives and recycled PVC content. The cluster retains volume leadership in porcelain production despite vinyl's renovation convenience gains.
Beijing-Tianjin-Hebei
Property upgrading in secondary cities generates replacement demand for moisture-resistant surfaces. GB standard formaldehyde emission thresholds filter out small workshops, concentrating volume among manufacturers with captive testing laboratories. State-owned developer procurement unbundling directs specification toward domestic suppliers with dedicated engineering teams.
Sichuan-Chongqing
Chengdu distributors report accelerating specification of click-lock vinyl in aging housing stock. Lower industrial electricity rates compared to coastal provinces attract greenfield manufacturing investment. Greenfield sites incorporate carbon-capture adhesive systems from commissioning to anticipate MEE circular economy directives.
Shandong Peninsula
Qingdao and Jinan serve as distribution nodes for central China demand corridors extending toward Wuhan and Zhengzhou. Distributed manufacturing networks anchor volume competitiveness through proximity to growing renovation markets. Provincial energy pricing supports continuous production scheduling for high-density fiberboard core manufacturing.
China Floor Covering Market Competitive Environment
The competitive structure tilts toward capital-heavy producers with captive supply chains and distributed plant networks. Regulatory compression from dual carbon goals and GB standard revisions filters volume toward manufacturers with in-house testing infrastructure. Three archetypes dominate: vertically integrated resin producers, FSC-certified premium specialists, and distributed volume manufacturers serving central China. Competitive moves concentrate on backward integration into basic chemicals and geographic expansion into lower-cost energy provinces.
Among domestic fabricators, Power Dekor, Der International, and Yangzi Flooring occupy distinct positioning vectors. Power Dekor exemplifies the integrated archetype through captive resin production that absorbs regulatory compliance burdens. Der International represents premium-tier positioning through certified supply chain architecture. Yangzi Flooring anchors volume competitiveness across interior provinces through distributed manufacturing scale. These three patterns illustrate how capital deployment and regulatory anticipation separate sustainable market access from marginal positioning.
| Leading Market Players |
|---|
| Yangzi Flooring |
| Der International |
| Power Dekor |
| DECNO |
| Changlongflor |
| Kentier |
| Nature Home |
| Shanghai Cimic Tiles |
| Anxin Flooring |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FSC-certified engineered wood and commodity PVC separates procurement budgets by a factor of two, with premium tiers absorbing captive resin production costs while volume manufacturers compete on naphtha-linked input volatility. This divergence concentrates margin stability among Yangtze Delta producers with backward integration into basic chemicals, while distributed manufacturers in Henan and Hubei anchor competitiveness through proximity to tier-two renovation demand.
Pricing Analysis
Bundled specification-through-installation packages dominate state-directed projects in Xiong'an New Area, while unbundled material-only procurement accelerates across Hangzhou and Chengdu distributor networks. Price differentiation rests on GB standard compliance tier and captive laboratory certification status, with formaldehyde testing infrastructure commanding a fifteen-point premium over workshop-grade alternatives. Cost compression in commodity laminate intensifies as naphtha cracking margins transmit directly to non-integrated producers. State-owned developers exhibit lowest price sensitivity; secondary city renovators drive hardest bargain on per-square-meter quotes.
Supply Chain Analysis
Single-source vulnerability sits with Saudi naphtha feedstock and South Korean plasticizer chemistry, exposing margin structures to petrochemical input volatility. Geographic supply concentration draws from Jiangsu resin production, Zhejiang fiberboard milling, and Guangdong PVC compounding. Raw material dependencies rest on high-density fiberboard cores, aluminum oxide wear layers, and water-based polyurethane coatings. Logistics chokepoint risk concentrates in Shanghai-Suzhou just-in-time resin delivery networks. Distribution runs through specification architect relationships in commercial verticals and provincial distributor networks in residential renovation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's floor covering sector reads as a late-cycle quality story where residential renovation demand shifts toward moisture-resistant vinyl and stone-polymer composite surfaces with documented carbon intensity credentials.
For Market Incumbents: Deepen captive resin production to absorb MEE emissions compliance burdens before 2025-2026 retrofit deadlines hit Jiangsu province. Deploy carbon-capture adhesive systems at greenfield Hubei and Henan sites to anticipate circular economy directives. Defend against click-lock vinyl substitution by accelerating water-based UV coating certification for laminate premium repositioning. For New Entrants and Emerging Players: Capture specification relationships with Wuhan-Zhengzhou corridor distributors serving central China renovation demand. Target Sichuan-Chongqing greenfield manufacturing with lower industrial electricity rates than coastal competitors. Enter through post-consumer PVC feedstock agreements with demolition contractors ahead of recycled content mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where GB standard formaldehyde thresholds filter volume toward manufacturers with in-house testing laboratories and captive supply chains. Five-to-ten year viability favors integrated producers with distributed plant networks spanning Yangtze Delta logistics density and central China energy cost advantages. Watch MEE carbon intensity benchmark enforcement waves as inflection indicator for retrofit capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of low-VOC polyurethane chemistry absorbs SAMR compliance costs before competitor retrofit cycles. |
| Greenfield Manufacturing in Central China | Hubei and Henan sites exploit lower industrial electricity rates and proximity to Wuhan-Zhengzhou demand corridors. |
| Post-Consumer PVC Feedstock Agreements | Early waste supply contracts with demolition contractors secure preferential procurement status under anticipated MEE circular economy directives. |
| Water-Based UV Coating Certification | Near-zero VOC finish chemistry satisfies Shanghai commercial architect mandates for LEED-equivalent specification. |
| Specification Engineering Team Deployment | Direct manufacturer relationships with state-owned developer buying committees unbundle flooring from general contractor packages. |
Study Parameters
Direct dialogue with plant managers at Jiangsu and Zhejiang manufacturing facilities, procurement leads at state-owned property developers, specification architects in Shanghai commercial towers, and provincial distributors in Chengdu and Hangzhou grounded qualitative assessment. Secondary validation drew from SAMR product quality certification databases, MEE emissions disclosure filings, customs trade records for PVC resin imports, and GB standard revision notices. Bottom-up production capacity modeling and top-down renovation demand estimation were triangulated against distributor inventory turnover patterns.
Segment-level value outputs across the analysis window reflect product type, material chemistry, installation mechanics, and end-use durability requirements. CAGRs were derived from trend extrapolation of tier-two residential renovation permit data, commercial fit-out square footage tracking, and state-directed project specification flows. Industry-specific forecast inputs incorporated dual carbon goal implementation timelines and anticipated MEE circular economy directive sequencing.
Petrochemical input volatility, GB standard revision timing, and MEE enforcement intensity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory implementation pace and substitution elasticity between material categories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market