
 Europe Laminate Flooring Market | 2026-2036
Europe Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Laminate Flooring Market Foresight
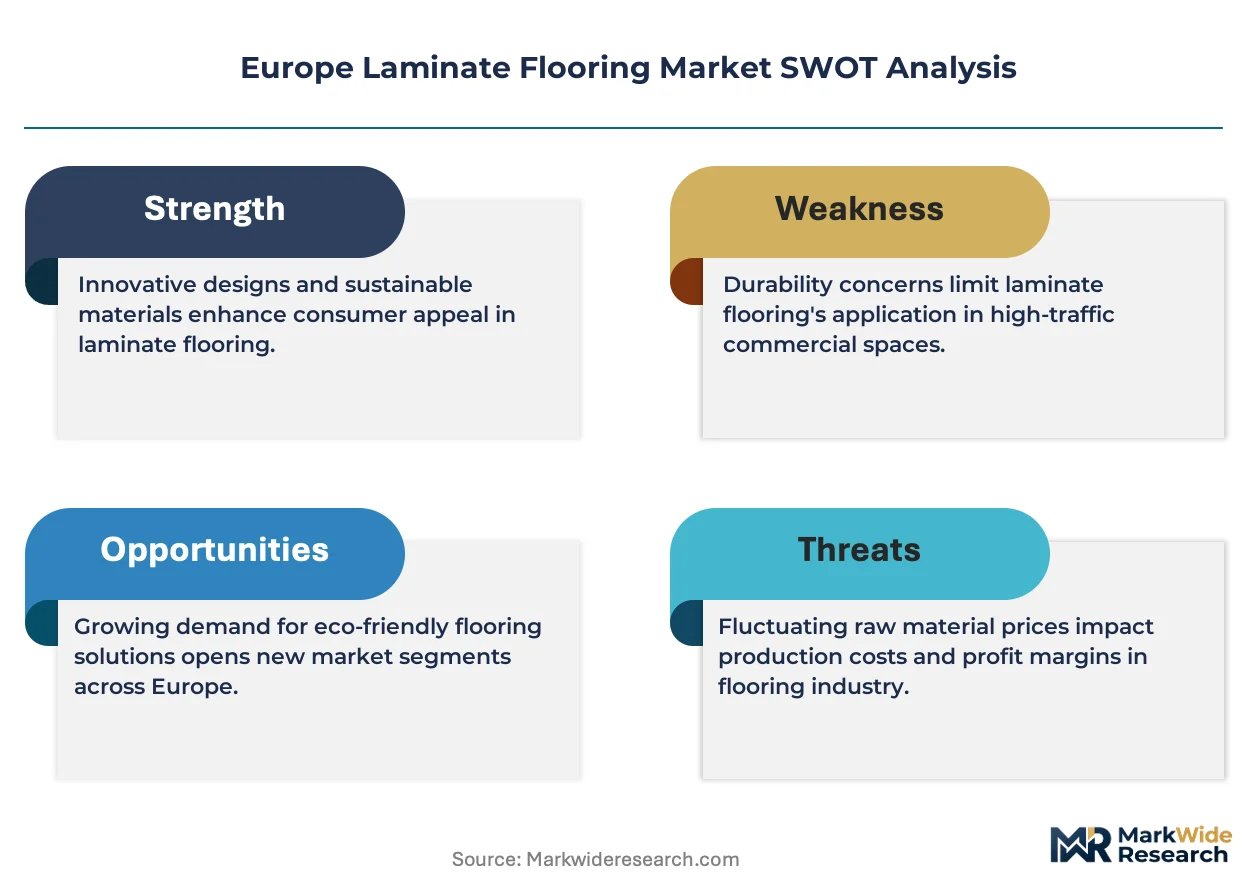
CE marking under the Construction Products Regulation is collapsing the supplier base for laminate flooring sold across EU member states. Swiss Krono Group leverages integrated fiberboard production to sustain margin control from raw material through finished plank. Tarkett S.A. competes through specialized commercial-grade wear layers that dominate airport and healthcare specifications. EGGER Holzwerkstoffe GmbH anchors its position with captive resin chemistry and particleboard supply across Austrian and German plants.
Europe laminate flooring consists of a multi-layer composite panel with a decorative paper impregnated with melamine resin bonded to a high-density fiberboard core, typically measuring 6mm to 12mm in total thickness, engineered to provide durable, cost-effective surfacing for interior spaces. The product type landscape shows moisture-resistant laminate capturing specification share in kitchens and bathrooms where traditional laminate faced exclusion, while high-pressure laminate retains premium positioning in commercial corridors with heavy rolling loads. End-user segmentation reveals the residential channel as the volume foundation, though commercial and institutional buyers increasingly dictate thickness requirements and acoustic underlayment standards that reshape manufacturing priorities.
The ECHA REACH framework governs formaldehyde emissions from fiberboard substrates, while the EU Green Deal's cascading carbon benchmarks pressure mills to document renewable energy use and recycled wood content. Germany's KBA building code and France's RE2020 environmental regulation for new construction jointly elevate low-emission, bio-based laminate in public procurement criteria. Stakeholders must monitor how the EU Deforestation Regulation's due diligence obligations recalibrate wood sourcing economics and which producers secure verified supply chains ahead of enforcement deadlines.
Market Dynamics
CE marking under the Construction Products Regulation is compressing the supplier base for laminate flooring sold across EU member states, forcing mills to consolidate testing and certification capabilities or exit cross-border trade entirely.
Growth Catalysts
- Germany's KBA building code:Elevates low-emission, bio-based laminate in public procurement criteria for residential renovation and new construction projects.
- Moisture-resistant laminate technology:Captures specification share in kitchens and bathrooms where traditional laminate faced exclusion from wet-area applications.
- Energy retrofit programs:Concentrate demand in Central European markets where housing stock turnover coincides with flooring replacement cycles.
Market Restraints
- Formaldehyde emission compliance:ECHA REACH framework governs fiberboard substrates, requiring continuous third-party testing and documentation.
- Decorative paper supply concentration:Reliance on specialized European mills for melamine-impregnated paper creates input bottlenecks during demand surges.
- Luxury vinyl tile substitution:Waterproof rigid core products capture specification in residential wet areas and commercial healthcare corridors.
Strategic Opportunities
- EU Deforestation Regulation due diligence:Producers securing verified chain-of-custody certification ahead of enforcement deadlines capture preferential sourcing contracts.
- France's RE2020 environmental regulation:Mandates embodied carbon disclosure for new construction, redirecting procurement toward wood-based laminate with documented renewable energy use.
- Digital specification platforms:Architects and contractors increasingly source certified products through BIM-integrated procurement tools.
Industry Challenges
- Acoustic underlayment integration:Commercial and institutional buyers dictate thickness requirements and sound-attenuation standards that reshape manufacturing priorities and inventory complexity.
- Resin chemistry expertise:Captive melamine and urea-formaldehyde formulation capabilities concentrate among integrated fiberboard producers, leaving independent laminators dependent on external supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Laminate Flooring Market |
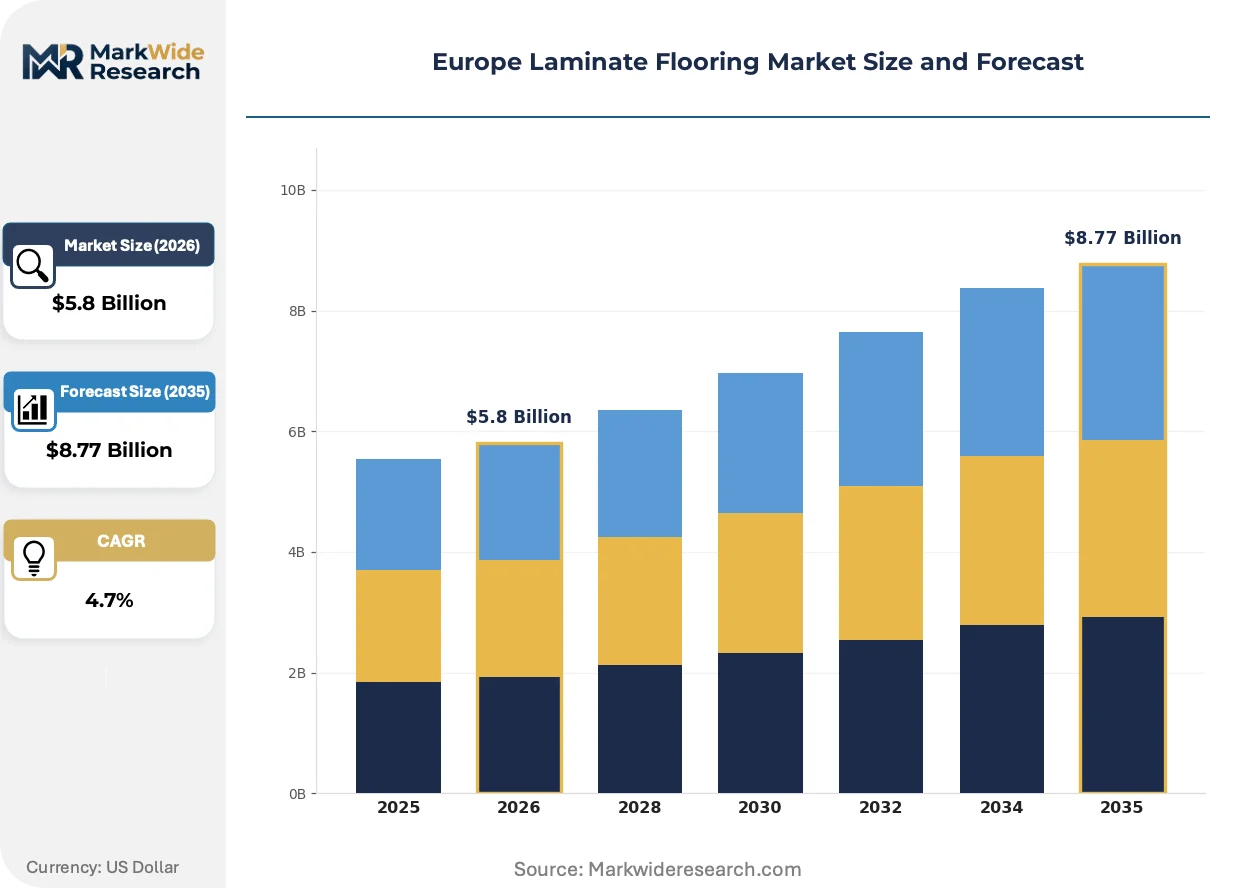
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminate, Low-Pressure Laminate, Moisture-Resistant Laminate, Wood-Based Laminate End User: Residential, Commercial, Industrial, Institutional Thickness: 6mm, 8mm, 10mm, 12mm Surface Texture: Smooth, Textured, Hand-Scraped, Glossy |
| Companies Covered | Armstrong Flooring, Inc., Swiss Krono Group, Tarkett S.A., EGGER Holzwerkstoffe GmbH, Kronospan Holding GmbH, Mohawk Industries, Inc., Beaulieu International Group, Classen Group, Shaw Industries Group, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Laminate Flooring Market Shifts & Advancements
Product architecture is fragmenting across performance tiers as regulatory pressure and end-use specialization force mills to abandon one-size-fits-all plank specifications.
Waterproof core technology is decomposing the traditional boundary between laminate and resilient flooring categories. Residential renovators in Germany and France specify 10mm and 12mm boards with integrated hydrophobic cores for kitchen and bathroom applications. The technology is compressing the addressable market for entry-grade vinyl sheet and enabling laminate mills to recapture wet-area specification.
EU Green Deal cascading carbon benchmarks are forcing fiberboard mills to document renewable energy use and recycled wood content in environmental product declarations. The regulation is elevating procurement scrutiny in public housing and institutional projects. French RE2020 and German KBA requirements jointly favor suppliers with verified bio-based content and third-party chain-of-custody certification.
Specification behavior is rotating toward certified low-emission products as architects and contractors face liability exposure under tightening indoor air quality standards. Digital procurement platforms with embedded EPD databases are displacing traditional distributor relationships for commercial projects. The shift is most visible in German and Austrian markets where public procurement mandates pre-qualification through centralized sustainability registries.
Europe Laminate Flooring Market Segmentation
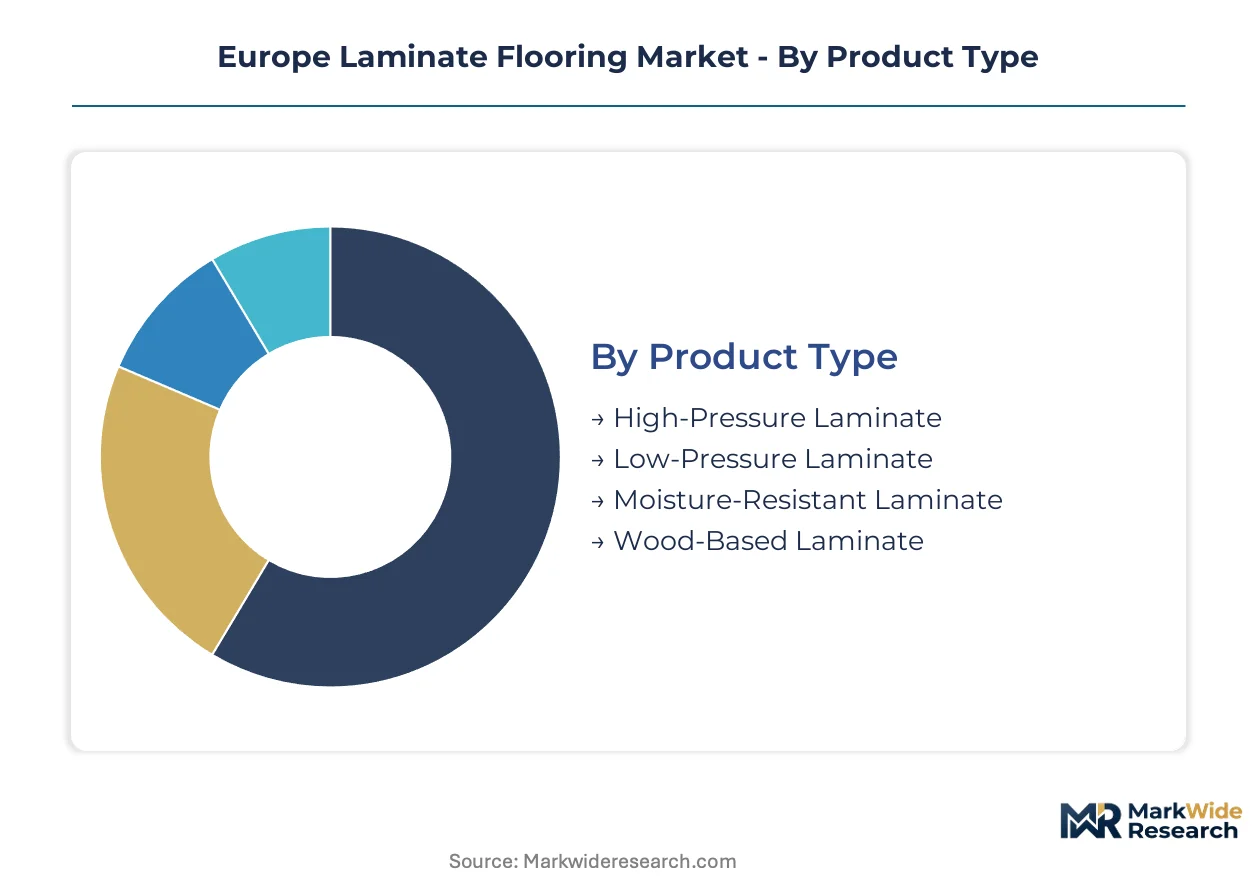
Segmentation in Europe's laminate flooring market reveals how regulatory pressure and application requirements fragment manufacturing priorities. CE marking under the Construction Products Regulation forces distinct compliance investments across product tiers, while end-use specialization drives divergent thickness and performance specifications.
Product Type:
REACH formaldehyde limits and EU Green Deal carbon disclosure requirements differentiate procurement eligibility across laminate categories.
- High-Pressure Laminate:Constructed with multiple kraft paper layers saturated with phenolic resin and fused under extreme heat and pressure. German airport terminals and French hospital corridors specify this grade for rolling load resistance. CE marking documentation for heavy commercial use demands extensive third-party testing that smaller mills cannot sustain.
- Moisture-Resistant Laminate:Hydrophobic core formulations and wax-impregnated edges enable kitchen and bathroom specification previously closed to laminate. Residential renovation in Central Europe favors 10mm and 12mm variants with integrated waterproofing as rigid vinyl alternatives face supply chain constraints.
- Low-Pressure Laminate:Direct-pressure manufacturing bonds decorative paper to fiberboard cores for cost-sensitive residential applications.
- Wood-Based Laminate:Verified chain-of-custody certification positions this category for public procurement under France's RE2020 and Germany's KBA codes.
Low-Pressure Laminate handles the majority of throughput; Moisture-Resistant Laminate is expanding most quickly on specification share.
End User:
Acoustic underlayment mandates and wear-layer requirements reshape margin profiles across customer categories.
- Residential:Volume foundation driven by renovation cycles in German and French housing stock. Thickness preferences cluster at 8mm for budget replacements and 10mm-12mm for primary living spaces. Energy retrofit program timing concentrates demand in Central European markets.
- Commercial:Airports, retail corridors, and office lobbies dictate AC5 wear-classification minimums and integrated sound-attenuation systems. Specification behavior rotates toward BIM-integrated procurement platforms with embedded EPD databases.
- Industrial:Chemical resistance and static-control properties dominate facility flooring decisions.
- Institutional:Healthcare and education procurement elevates low-emission certification and slip-resistance ratings.
Residential channels absorb the greatest production volume; Commercial buyers are gaining procurement leverage fastest.
Thickness:
Board dimension determines acoustic performance, installation compatibility, and price positioning across renovation and new construction.
- 10mm:Balanced specification for residential renovation requiring underfloor heating compatibility and moderate sound reduction. German and French markets favor this dimension for kitchen and bathroom applications where moisture-resistant cores justify premium positioning.
- 12mm:Maximum dimensional stability for commercial corridors and high-traffic residential entryways. Click-lock profile durability and impact resistance satisfy institutional procurement standards in Austrian and Swiss markets.
- 6mm:Thin-profile option for budget residential replacement over existing substrates.
- 8mm:Standard residential specification balancing cost and performance.
8mm boards maintain the highest shipment volumes; 10mm variants are climbing the fastest on renovation demand.
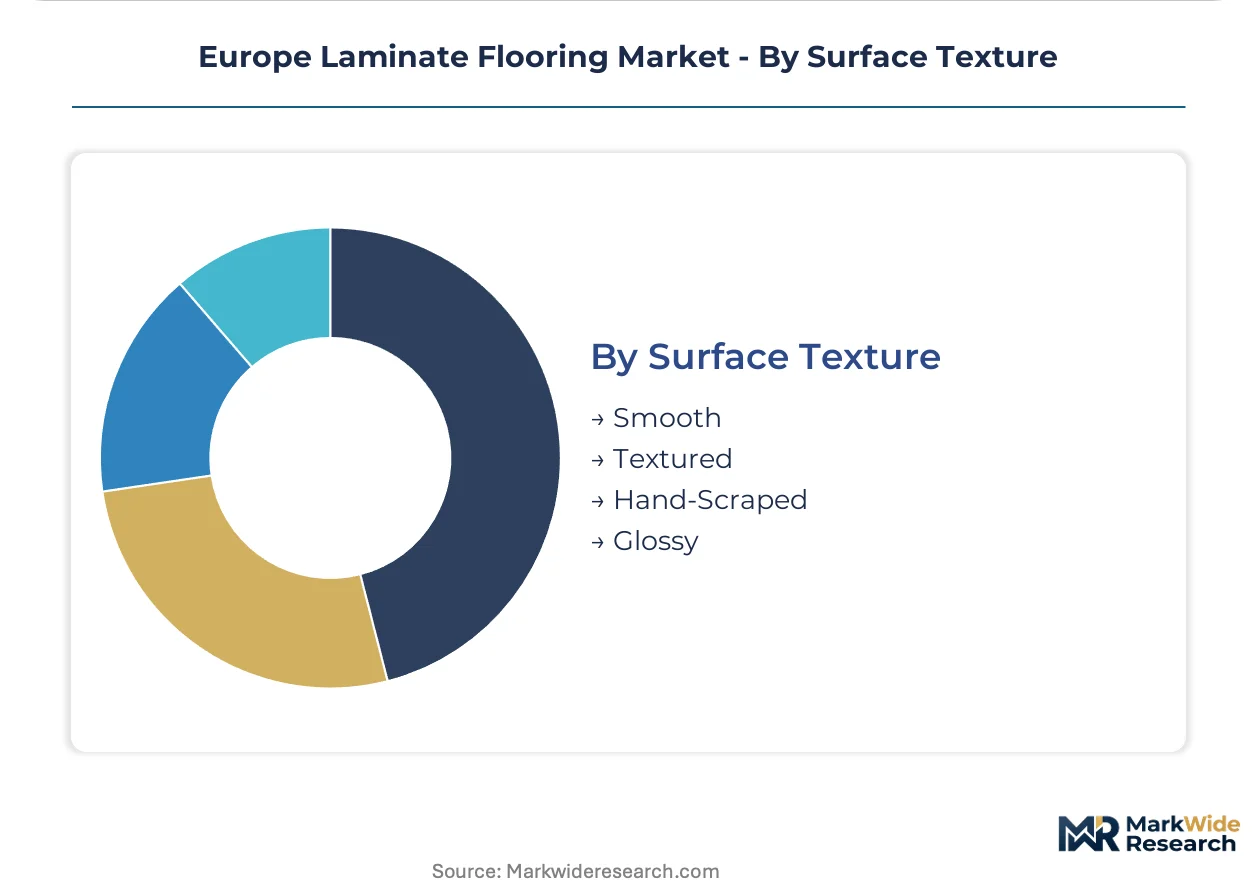
Surface Texture:
Aesthetic differentiation and maintenance requirements segment specification across residential and commercial interiors.
- Textured:Embossed-in-register technology aligns surface relief with decorative grain patterns for authentic wood replication. German and Austrian residential markets prefer this finish for high-visibility living spaces where tactile authenticity commands premium pricing.
- Hand-Scraped:Distressed surface treatment mimics artisanal hardwood for rustic interior specifications. French renovation contractors specify this texture for heritage property conversions requiring traditional material aesthetics.
- Smooth:Uniform surface enables easy cleaning in healthcare and food-service commercial applications.
- Glossy:High-sheen finish for contemporary residential and retail environments.
Textured surfaces dominate current specification; Hand-Scraped finishes show the steepest expansion trajectory in heritage renovation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA building code and France's RE2020 environmental regulation are redirecting public procurement toward low-emission, bio-based laminate across Central European renovation markets. Energy retrofit program timing concentrates flooring replacement demand in housing stock turnover zones.
Germany
Residential renovation activity in North Rhine-Westphalia and Bavaria accelerates specification of 10mm and 12mm moisture-resistant boards for kitchen and bathroom applications. The KBA building code elevates low-emission laminate in public housing procurement criteria. The Rhine-Main industrial corridor hosts integrated fiberboard production facilities serving cross-border distribution into Benelux markets.
France
Heritage property conversions in Île-de-France and Provence-Alpes-Côte d'Azur drive hand-scraped texture demand for traditional interior aesthetics. RE2020 mandates embodied carbon disclosure for new construction, redirecting procurement toward wood-based laminate with verified chain-of-custody certification. The Auvergne-Rhône-Alpes region concentrates decorative paper impregnation capacity serving southern European markets.
United Kingdom
London and Southeast England renovation cycles favor 8mm standard-grade laminate for budget-conscious residential replacement over existing substrates. CE marking under the Construction Products Regulation compresses the supplier base for cross-border trade. The Midlands manufacturing belt maintains particleboard supply relationships with Austrian and German laminate mills.
Poland
Warsaw and Kraków residential construction absorbs cost-sensitive low-pressure laminate for volume housing developments. EU Green Deal cascading carbon benchmarks pressure mills to document renewable energy use in environmental product declarations. The Silesian industrial region hosts fiberboard production feeding Central European distribution networks.
Italy
Lombardy and Veneto commercial corridors specify AC5 wear-classification laminate for retail and office lobby applications. ECHA REACH formaldehyde emission limits govern fiberboard substrate compliance for products sold across EU member states. The Emilia-Romagna furniture manufacturing cluster sources specialized commercial-grade wear layers for hospitality specifications.
Europe Laminate Flooring Market Competitive Landscape
Listed flooring conglomerates compete with private wood-based panel specialists across certification and raw material integration dimensions. The supplier base compresses around CE marking compliance capabilities and captive resin chemistry expertise. Three archetypes dominate: integrated fiberboard producers controlling substrate supply, specialized commercial-grade wear layer developers, and diversified building materials groups with distribution scale. Consolidation pressure and backward integration into decorative paper supply represent the dominant competitive vectors.
Within the integrated production tier, Swiss Krono Group and EGGER Holzwerkstoffe GmbH exemplify captive fiberboard and resin formulation capabilities that insulate margin control from input volatility. Tarkett S.A. occupies a position representing specialized commercial-grade specification expertise for institutional and transportation end-uses. These three entities anchor the competitive structure through distinct strategic postures: substrate integration, performance specialization, and distribution reach.
| Leading Market Players |
|---|
| Armstrong Flooring, Inc. |
| Swiss Krono Group |
| Tarkett S.A. |
| EGGER Holzwerkstoffe GmbH |
| Kronospan Holding GmbH |
| Mohawk Industries, Inc. |
| Beaulieu International Group |
| Classen Group |
| Shaw Industries Group, Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German fiberboard mills and Austrian decorative paper suppliers lock in raw material access while stabilizing input cost visibility across quarterly production cycles. This contract architecture insulates integrated producers from spot market volatility in melamine resin pricing, though independent laminators remain exposed to margin compression when energy costs spike.
Pricing Analysis
Certification level under ECHA REACH and CE marking creates the primary spread between premium and standard laminate tiers. Three-tier pricing structure across moisture-resistant, high-pressure, and low-pressure laminate levels reflects compliance investment differentials rather than raw material costs alone. Price erosion runs through entry-grade low-pressure laminate as Polish and Romanian mills expand capacity. Residential renovators in Central Europe exhibit highest price sensitivity, while French institutional buyers prioritize embodied carbon documentation over unit cost.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion ripple through decorative paper delivery schedules to German and Austrian laminate mills. Raw material supply concentrates in Germany, Austria, and Poland for fiberboard substrates, with decorative paper impregnation capacity clustering in France and Italy. The chain draws from specialized European mills for melamine-impregnated paper, creating single-source vulnerability during demand surges. Distribution runs through building materials wholesalers and BIM-integrated procurement platforms serving commercial specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent laminate producers face substitution pressure from waterproof rigid core luxury vinyl tile in residential wet areas and commercial healthcare corridors. Defense requires reinforcing the wood-based sustainability narrative against petrochemical alternatives.
For Market Incumbents: Shield specification share in public procurement by accelerating EU Deforestation Regulation compliance ahead of enforcement deadlines. Secure captive resin chemistry capabilities or long-term supply agreements with Austrian particleboard producers to defend margin control against input volatility. Counter luxury vinyl tile encroachment through moisture-resistant laminate technology investment targeting kitchen and bathroom renovation cycles.
For New Entrants and Emerging Players: Digital specification platform integration gaps expose incumbents' reliance on traditional distributor relationships. Penetrate commercial and institutional segments through BIM-embedded environmental product declaration databases that streamline architect procurement workflows. Target French heritage renovation contractors with hand-scraped texture specialization unsupported by major integrated producers.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated fiberboard producers with verified chain-of-custody certification and captive renewable energy supply. The five-to-ten year viability window favors mills with backward control over particleboard and resin formulation. Watch EU Green Deal cascading carbon benchmark enforcement as the inflection signal for preferential procurement contract allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiberboard Production | Captive substrate supply insulates margin control from ECHA REACH compliance cost volatility. |
| EU Deforestation Regulation Certification | Verified chain-of-custody positions mills for French RE2020 and German KBA public procurement. |
| Moisture-Resistant Core Technology Investment | Hydrophobic formulations recapture wet-area specification from rigid core vinyl competitors. |
| BIM-Integrated Digital Specification Platform | Embedded EPD databases displace traditional distributor relationships in commercial channels. |
| Renewable Energy Supply Documentation | Environmental product declarations satisfy EU Green Deal carbon disclosure mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at German and Austrian fiberboard mills, procurement leads at French construction firms, and regulatory affairs specialists at laminate trade associations; and secondary validation through ECHA REACH documentation, CE marking compliance registries, and EU Green Deal policy releases. Bottom-up volume estimates triangulated against top-down construction sector expenditure data from Eurostat and national housing renovation program disclosures.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, end-user segment, thickness tier, and surface texture finish. CAGRs were derived from regression analysis of historical replacement cycle timing against energy retrofit program implementation schedules. Forecast inputs incorporated ECHA formaldehyde limit enforcement trajectories and EU Deforestation Regulation compliance cost assumptions.
Forecasts assume regulatory continuity in ECHA REACH, EU Green Deal carbon benchmarks, and national building codes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market