
 Flood Protection Sandbags Market | 2026-2036
Flood Protection Sandbags Market Size, Share, and Industry Trends Forecast 2026-2036
Flood Protection Sandbags Market Analytics
The flood protection sandbags market is restructuring around a sharp split between military-grade woven polypropylene bags with reinforced stitching and untreated burlap sacks sold through hardware retail. FloodSax leverages its proprietary gel-filling technology to command premium positioning in rapid-deployment municipal contracts. Sandbag Store LLC anchors the commodity tier through bulk wholesale channels serving construction and agricultural buyers across the central United States. Quick Dam competes with self-activating polymer alternatives that reduce labor costs during emergency response windows.
Flood protection sandbags are woven or non-woven containers, typically 14 by 26 inches, designed to be filled with sand, soil, or engineered absorbent polymers to create temporary barriers against water ingress. Polyethylene dominates material type due to its UV resistance and tensile strength exceeding 800 psi in military-specification weaves, while jute retains niche demand among environmentally regulated European procurement programs. Application segmentation shows emergency response outpacing commercial and residential channels as FEMA and state-level disaster agencies centralize pre-positioned stockpiles rather than relying on last-minute retail purchases. Government procurement as a distribution channel captures the deepest margin pools through multi-year framework agreements, though online retail expands access for small-property holders in flash-flood zones.
The U.S. Army Corps of Engineers maintains EN 12572-equivalent testing protocols that filter out substandard imports, while EPA stormwater regulations indirectly elevate sandbag specifications by linking temporary barrier performance to discharge permit compliance. ISO 9001 certification has become a de facto threshold for federal contract eligibility, squeezing uncertified regional weavers toward consumer and light commercial segments. Stakeholders must track how climate adaptation funding reallocations between permanent levee construction and temporary mitigation supplies reshape procurement rhythms and inventory holding patterns.
Market Dynamics
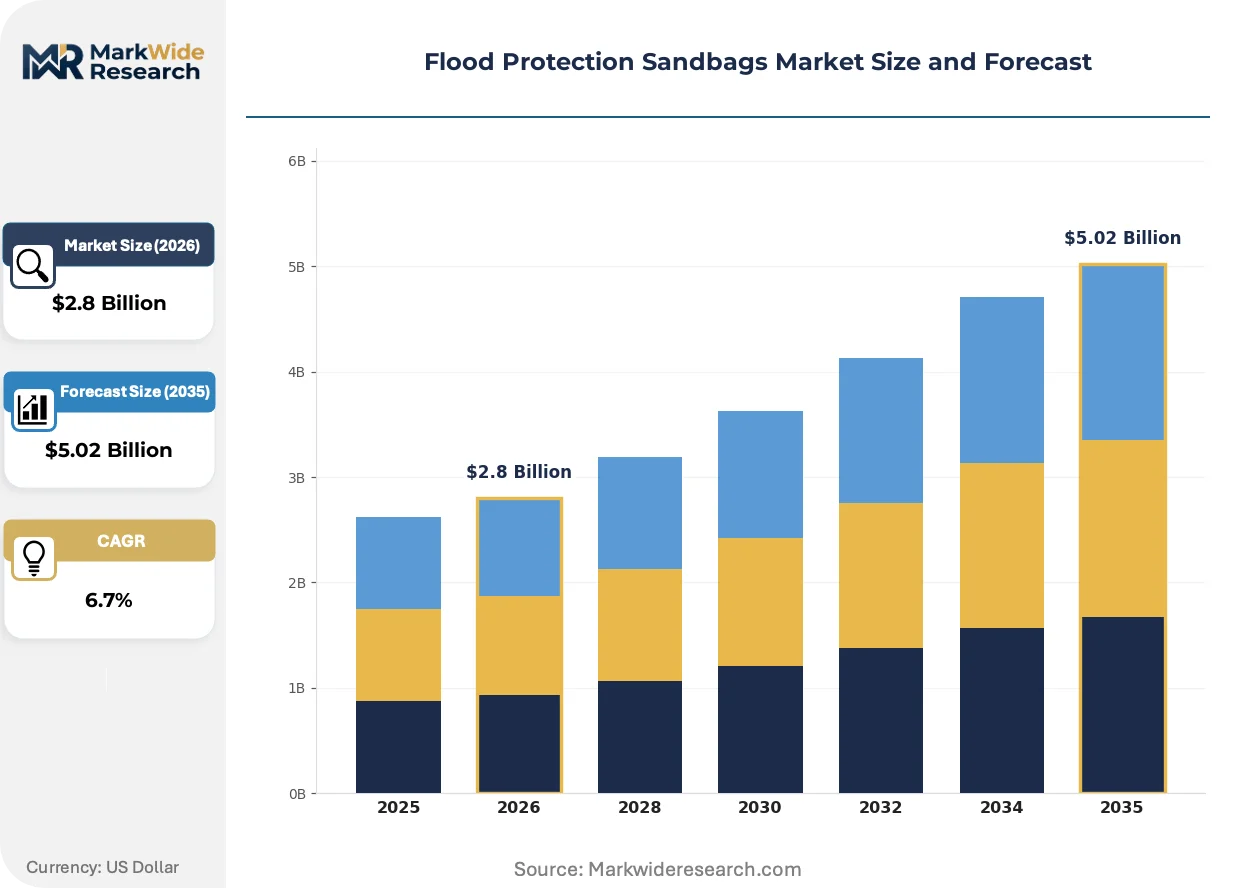
Climate adaptation funding reallocation is compressing procurement cycles for temporary flood mitigation supplies as permanent infrastructure budgets strain against intensifying storm seasons. Municipal emergency management agencies now prioritize pre-positioned stockpiles over last-minute retail sourcing.
Growth Catalysts
- FEMA Pre-Positioning Mandates:Federal emergency management directives require state-level agencies to maintain 72-hour self-sufficiency reserves, driving woven polypropylene procurement through multi-year framework agreements.
- UV-Stabilized Polyethylene Weaves:Military-specification tensile strength exceeding 800 psi enables sandbag reuse across multiple deployment cycles, reducing total cost of ownership for repetitive flood zones.
- Mississippi River Corridor Concentration:Repetitive levee overtopping events in Louisiana, Missouri, and Arkansas sustain replacement demand for degraded barrier inventories.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer price swings tied to petrochemical refining margins compress woven bag manufacturer margins during peak storm seasons.
- Import Quality Asymmetry:Substandard Asian woven products lacking EN 12572-equivalent testing protocols create liability exposure for uncertified regional distributors.
- Permanent Infrastructure Substitution:Concrete flood walls and deployable aluminum barriers capture municipal capital allocations where repetitive flooding justifies fixed asset investment.
Strategic Opportunities
- Flash-Flood Zone Retail Access:Online direct-to-consumer channels penetrate underserved Appalachian and Southwestern property holders lacking proximity to emergency supply depots.
- EU Green Deal Procurement:Biodegradable jute and hemp-blend sandbags qualify for environmentally regulated European public tenders with mandated circular economy criteria.
- Polymer-Gel Hybrid Convergence:Self-activating absorbent polymers integrated into woven shells reduce labor deployment time by eliminating manual sand-filling requirements.
Industry Challenges
- ISO 9001 Certification Timelines:Federal contract eligibility thresholds require 12-18 month quality management system implementation, excluding smaller regional weavers from framework bidding.
- Warehouse Capacity Constraints:Seasonal demand surges strain third-party logistics providers in Gulf Coast states, forcing inventory pre-positioning costs onto manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flood Protection Sandbags Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Jute, Nylon, Fabric Application: Commercial Use, Residential Use, Industrial Use, Emergency Response Distribution Channel: Online Retail, Wholesale, Direct Sales, Government Procurement Size: Small, Medium, Large, Custom Size |
| Companies Covered | FloodSax, Sandbag Store LLC, Quick Dam, TrapBag, Lloyd Bag Company, One Ton Bag, LC Packaging UK Ltd, Palmetto Industries, Flood Avert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flood Protection Sandbags Market Evolving Landscape
Material science advances and procurement centralization are restructuring competitive positioning across temporary flood barrier supply chains. Three developments warrant particular attention from market participants.
Engineered polymer-gel filling systems are integrating absorbent crystal matrices into woven polypropylene shells, creating self-deploying barriers that activate upon water contact without manual sand handling. Municipal emergency response units in flash-flood-prone jurisdictions are adopting these systems for rapid perimeter establishment. This technology is integrating rapid-deployment capabilities into standard procurement specifications, compressing competitive differentiation around labor efficiency rather than material durability alone.
EPA stormwater discharge regulations are tightening temporary barrier performance standards by linking sandbag deployment to NPDES permit compliance for construction and industrial sites. Contractors now face inspection failures if barrier integrity degrades before sediment containment targets are met. Site remediation and commercial construction segments are responding by specifying UV-stabilized polyethylene weaves with documented tensile retention curves.
Pre-positioned stockpile contracts are displacing spot-market purchasing as state emergency management agencies consolidate supplier relationships under multi-year framework agreements. Hardware retail and agricultural supply channels lose volume to centralized federal and state procurement offices. This concentration is most visible across Gulf Coast and Midwestern states where FEMA mitigation grants fund regional distribution hub construction.
Flood Protection Sandbags Market Segmentation
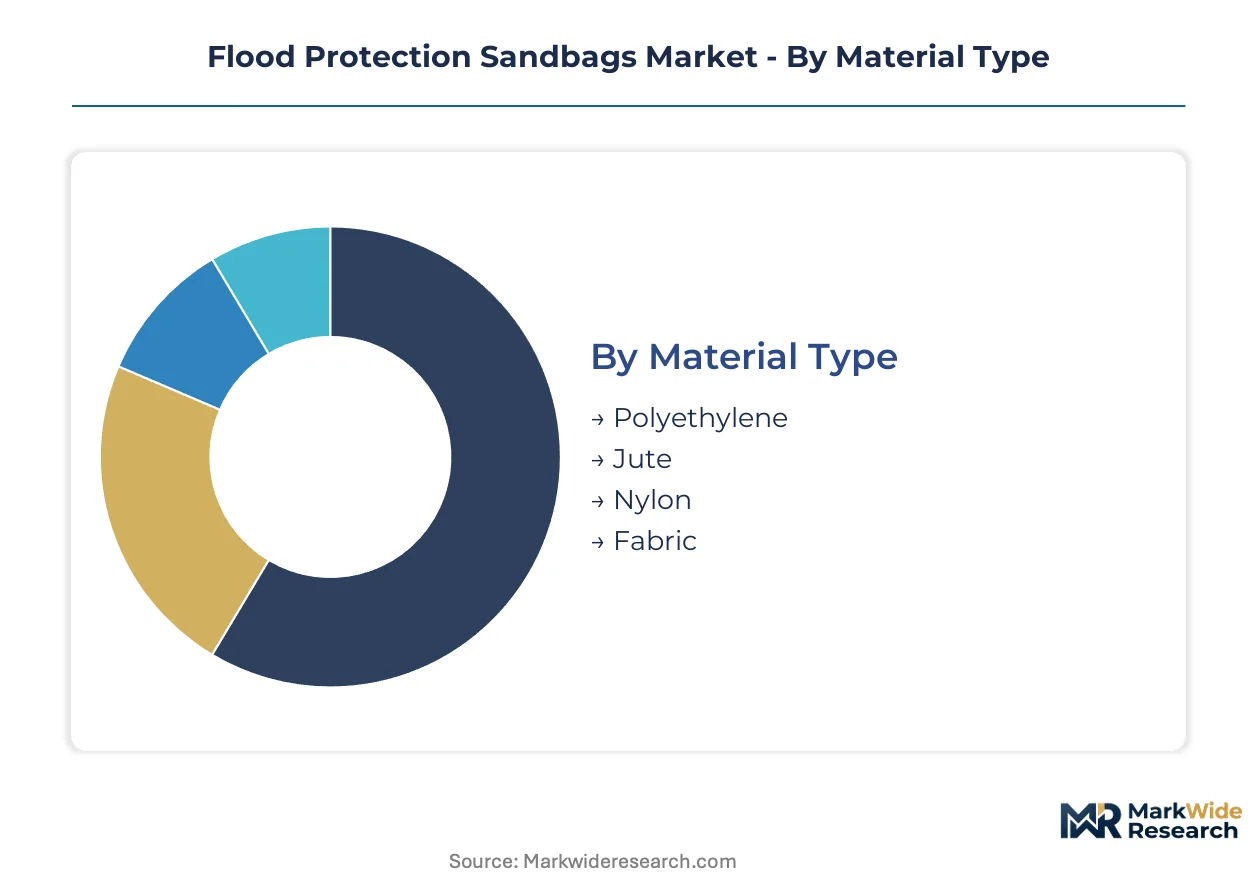
Material specifications determine procurement eligibility for federal frameworks, while distribution channel selection separates institutional buyers from property-level consumers. Application segmentation reveals how emergency response protocols now dominate volume allocation ahead of commercial construction.
Material Type:
Technical specifications around tensile strength and UV resistance create tiered procurement eligibility across federal, state, and consumer channels.
- Polyethylene:UV-stabilized woven construction delivers tensile strength exceeding 800 psi under military-specification protocols. Mississippi River corridor levee districts and Gulf Coast municipal agencies specify polyethylene for multi-deployment reuse cycles where storm recurrence justifies inventory amortization.
- Jute:Biodegradable natural fiber construction qualifies for EU Green Deal procurement mandates with circular economy compliance requirements. European public tenders in France, Germany, and the Netherlands specify jute blends where environmental regulations override durability premiums.
- Nylon:Synthetic polymer weave offers intermediate tensile performance between polyethylene military grades and commodity jute alternatives.
- Fabric:Non-woven and woven textile variants serve light-duty consumer applications with minimal load-bearing requirements.
Polyethylene leads on scale; jute leads on momentum.
Application:
End-use segmentation tracks how FEMA pre-positioning mandates reallocate volume from retail channels toward institutional stockpiles.
- Emergency Response:State emergency management agencies and municipal fire departments maintain 72-hour self-sufficiency reserves under federal directive. Louisiana, Missouri, and Arkansas agencies centralize procurement through multi-year framework agreements rather than spot-market acquisition.
- Commercial Use:Construction contractors deploy temporary barriers for EPA NPDES permit compliance at industrial sites. Site remediation projects in flash-flood zones specify UV-stabilized weaves with documented sediment retention curves.
- Residential Use:Individual property holders in Appalachian and Southwestern flash-flood zones purchase through online retail channels lacking proximity to emergency supply depots.
- Industrial Use:Manufacturing facilities and warehouse operators maintain perimeter protection inventories against stormwater ingress.
Emergency response commands volume concentration; commercial use delivers margin stability.
Distribution Channel:
Channel selection separates price-sensitive bulk procurement from premium rapid-deployment contracts.
- Government Procurement:Multi-year framework agreements with state emergency management agencies capture the deepest margin pools. FEMA mitigation grants fund regional distribution hub construction across Gulf Coast and Midwestern states.
- Wholesale:Bulk channels serve construction and agricultural buyers across the central United States with commodity-grade woven polypropylene.
- Online Retail:Direct-to-consumer penetration expands access for small-property holders in underserved flash-flood zones.
- Direct Sales:Manufacturer-direct relationships support large-contract municipal and industrial accounts.
Government procurement anchors revenue concentration; online retail offers the steepest expansion trajectory.
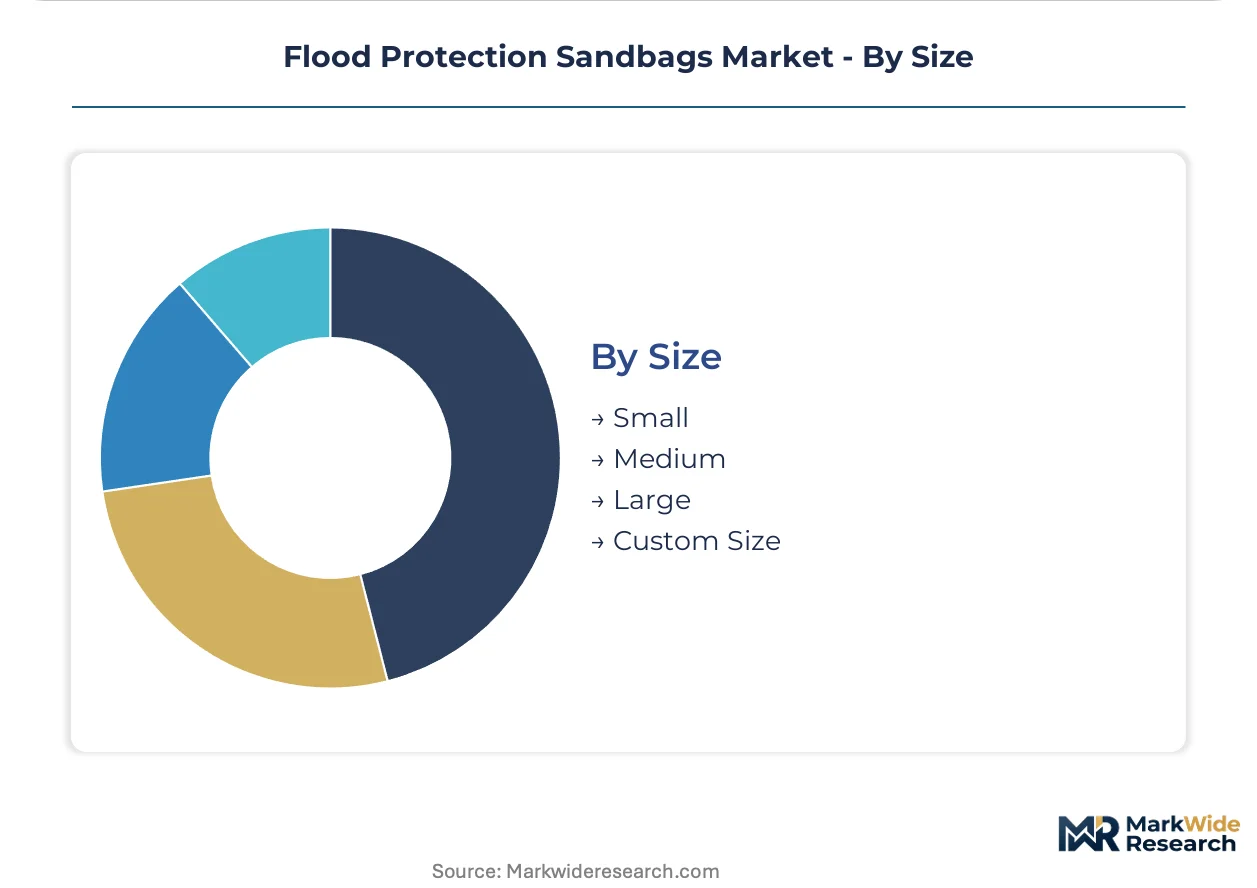
Size:
Dimensional segmentation aligns with deployment logistics and fill-material handling constraints.
- Medium:Standard 14-by-26-inch specification dominates municipal stockpiles and federal procurement catalogs. The U.S. Army Corps of Engineers maintains EN 12572-equivalent testing protocols that filter out substandard dimensional variants.
- Large:Oversized configurations reduce labor deployment time for rapid perimeter establishment at industrial and levee sites.
- Small:Compact dimensions serve residential consumer applications with limited storage and manual handling capacity.
- Custom Size:Engineered dimensions address specialized industrial containment and infrastructure protection requirements.
Medium sizes lead on procurement standardization; large sizes gain share fastest in rapid-deployment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emergency management agencies in flood-prone regions maintain specialized procurement teams that negotiate multi-year framework agreements for woven polypropylene stockpiles. These talent concentrations cluster along major river systems and coastal zones where repetitive storm damage justifies dedicated mitigation staffing.
United States
The Mississippi River corridor and Gulf Coast states sustain replacement demand for degraded barrier inventories. FEMA pre-positioning mandates require 72-hour self-sufficiency reserves, driving state emergency management agencies toward centralized procurement. Louisiana levee districts and Arkansas municipal agencies consolidate purchasing through regional distribution hubs funded by federal mitigation grants.
Germany
Rhine River floodplains and North Sea coastal municipalities specify biodegradable jute blends for temporary barriers. EU Green Deal procurement mandates with circular economy criteria elevate environmental compliance above durability premiums in public tenders. Bavarian and Baden-Württemberg emergency response units maintain hybrid stockpiles balancing polymer performance with regulatory biodegradability requirements.
Netherlands
Delta Works-adjacent municipalities and Rotterdam port authorities invest in rapid-deployment polymer-gel systems for flash-flood perimeter establishment. REACH compliance frameworks filter material specifications for construction and industrial site remediation. Randstad region emergency coordinators pilot self-activating barriers that reduce labor deployment time during North Sea storm surge events.
United Kingdom
Thames Estuary and Severn Valley flood management authorities centralize sandbag procurement under Environment Agency framework agreements. Construction contractors face tightened temporary barrier standards linked to EPA-equivalent discharge permit compliance at industrial sites. Yorkshire and Lancashire county councils pre-position UV-stabilized polyethylene inventories for repeated deployment across winter storm seasons.
China
Yangtze River basin provincial governments and Pearl River Delta municipal agencies expand woven polypropylene manufacturing capacity for domestic emergency stockpiles. GB standards and MEE stormwater regulations tighten weave density specifications for public infrastructure projects. Sichuan-Chongqing region emergency management bureaus integrate sandbag reserves into landslide and flash-flood response protocols.
Flood Protection Sandbags Market Competitive Landscape
Top-tier vendors anchor military-specification and polymer-gel innovation tiers, while commodity-grade weavers compete on volume throughput and regional logistics proximity. The vendor base stratifies across three functional layers: rapid-deployment technology specialists, bulk wholesale distributors serving construction and agricultural channels, and certified federal contractors capturing multi-year framework agreements. Two dominant competitive moves define current positioning: ISO 9001 certification investments to unlock federal eligibility, and warehouse pre-positioning partnerships with Gulf Coast third-party logistics providers to compress emergency response delivery windows.
Within the rapid-deployment technology tier, FloodSax represents proprietary gel-filling innovation for municipal contracts, while Quick Dam exemplifies self-activating polymer alternatives that reduce labor requirements. Sandbag Store LLC anchors the commodity wholesale vector through bulk channels across the central United States. These three entities collectively illustrate how material science differentiation, volume scale, and certification compliance separate premium positioning from price-driven competition.
| Leading Market Players |
|---|
| FloodSax |
| Sandbag Store LLC |
| Quick Dam |
| TrapBag |
| Lloyd Bag Company |
| One Ton Bag |
| LC Packaging UK Ltd |
| Palmetto Industries |
| Flood Avert |
| Others |
Value Network & Pricing Analysis
A sharp certification-performance divergence separates ISO 9001-qualified federal contractors from uncertified regional weavers, concentrating pricing power with the former while fragmenting supply chains into parallel premium and commodity channels across Gulf Coast distribution networks.
Pricing Analysis
Bundled multi-year framework agreements dominate institutional procurement, while unbundled spot-market transactions persist for consumer retail. Three-tier pricing structure across premium polymer-gel systems, military-specification polyethylene weaves, and commodity jute alternatives differentiates on certification grade and UV-stabilized tensile performance. Cost compression in commodity polypropylene tiers is intensifying because propylene monomer volatility compresses weaver margins during peak storm seasons. State emergency management agencies show least price sensitivity under FEMA pre-positioning mandates; individual property holders in flash-flood zones exhibit highest sensitivity.
Supply Chain Analysis
Warehouse-distribution layer pre-positioning partnerships with Gulf Coast third-party logistics providers compress emergency response delivery windows. Manufacturing concentrates in the United States, China, and India for woven polypropylene capacity. Raw material inputs draw from petrochemical propylene feedstocks, UV stabilizer additives, and natural jute fiber imports. Single-source vulnerability runs through concentrated propylene refining capacity tied to Gulf Coast petrochemical corridors. Distribution runs through government procurement offices, wholesale construction channels, and direct-to-consumer online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. FEMA pre-positioning mandates and tightened Army Corps specifications are reallocating volume toward certified premium tiers.
For Market Incumbents: Deploy ISO 9001 certification leverage to deepen federal contract capture and lock out uncertified regional competitors. Prioritize warehouse pre-positioning partnerships with Gulf Coast logistics providers to compress delivery windows during surge demand. Threat substitution from self-activating polymer-gel systems demands R&D investment in rapid-deployment hybrid technologies to maintain specification relevance. For New Entrants and Emerging Players: Enter via biodegradable jute-blend positioning for EU Green Deal procurement mandates in France, Germany, and the Netherlands where environmental compliance overrides durability premiums. Target underserved online retail channels for Appalachian and Southwestern flash-flood zone property holders lacking depot proximity. Go-to-market angle: direct-to-consumer rapid-deployment kits with self-filling polymer alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier weavers possessing latent ISO 9001 certification capacity and Gulf Coast warehouse assets. Long-term viability frames around climate adaptation funding durability and permanent infrastructure substitution risk. Acquisition target archetype: certified regional weavers with FEMA framework relationships. Signal to watch: Army Corps specification updates tightening weave density thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Investment | Unlocks federal framework eligibility and excludes uncertified competitors from multi-year agreements. |
| Warehouse Pre-Positioning Partnership | Compresses emergency response delivery windows for Gulf Coast and Mississippi River corridor agencies. |
| Polymer-Gel Hybrid R&D | Integrates self-activating absorbent systems into woven shells for rapid-deployment municipal contracts. |
| EU Green Deal Product Line | Qualifies biodegradable jute blends for environmentally regulated European public tenders. |
| Direct-to-Consumer Channel Buildout | Penetrates underserved flash-flood zones in Appalachia and the Southwest lacking depot proximity. |
Research Methodology
Multiple input streams — emergency management procurement officers, woven polypropylene plant managers, construction contractor purchasing leads, and third-party logistics coordinators — were reconciled against customs trade records, FEMA mitigation grant disclosures, Army Corps specification documents, and state emergency management inventory reports. Bottom-up shipment data triangulated against top-down federal funding allocations.
Data-stream reconciliation across material type, application channel, distribution pathway, and regional procurement cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by FEMA pre-positioning mandate implementation timing. Industry-specific forecast inputs included propylene feedstock price curves and Army Corps specification update probability.
Inputs from federal procurement databases and state emergency management inventory systems were available through the study window; gaps in real-time spot-market pricing for commodity jute alternatives introduce uncertainty bands around consumer segment projections. Forecasts reflect documented assumptions around climate adaptation funding continuity and permanent infrastructure substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Spain Ransomware Protection Market