
 Global Data Protection and Recovery Solutions Market | 2026-2036
Global Data Protection and Recovery Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Protection and Recovery Solutions Market Intelligence
The bundling of data protection with broader cloud infrastructure platforms is realigning buyer preferences away from standalone tools. This shift favors large-scale providers who can offer integrated solutions. Microsoft Corporation leverages its Azure cloud ecosystem to embed backup and recovery services. Veeam Software AG competes by specializing in virtual machine backup and replication for hybrid cloud environments, while International Business Machines Corporation (IBM) sustains its position in large enterprise accounts with comprehensive data management suites.
Data protection and recovery solutions encompass software and services designed to safeguard information from loss, corruption, or disaster. These systems use techniques like storage snapshots, which create point-in-time copies of data with minimal performance impact, to ensure business continuity. Cloud-based deployment models are expanding rapidly, overtaking traditional on-premises setups in many sectors. Within solution types, demand for continuous data protection is growing in financial services and telecommunications, where near-zero data loss is critical.
Regulatory frameworks are a significant catalyst for market adoption. The EU's GDPR imposes strict requirements for data portability and the right to be forgotten, while the US HIPAA mandates secure backup for protected health information. These regulations compel organizations to invest in compliant recovery solutions. Vendor selection will increasingly hinge on the ability to support multi-cloud data sovereignty and demonstrate auditable recovery test results.
Market Dynamics
The convergence of sophisticated ransomware threats and stringent data sovereignty mandates creates a powerful structural force, compelling organizations to modernize backup and recovery systems beyond simple data preservation toward comprehensive cyber resilience.
Growth Catalysts
- Regulatory Mandates:The EU's GDPR forces organizations to provide data portability and honor deletion requests, requiring sophisticated backup and recovery systems that can manage data at a granular level.
- Ransomware Mitigation:Escalating ransomware attacks targeting critical infrastructure and the financial services industry drive investment in immutable backups and rapid recovery solutions to ensure business continuity.
- Near-Zero RPO Demand:Industries like telecommunications and online retail require continuous data protection to minimize data loss, pushing adoption of solutions with near-zero recovery point objectives (RPO).
Market Restraints
- Implementation Costs:The high initial cost and total cost of ownership for advanced, near-zero data loss systems can be a significant barrier for small and medium-sized enterprises.
- Management Complexity:The technical difficulty of managing and orchestrating data protection across disparate on-premises, hybrid, and multi-cloud environments creates significant operational overhead and requires specialized skills.
- Platform Bundling:The inclusion of basic backup functionalities within broader cloud infrastructure platforms can dissuade customers from investing in more capable, specialized third-party data protection solutions.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Latin America, where digitalization is accelerating, present significant growth opportunities for data protection and recovery service providers.
- Edge and IoT Data Protection:The proliferation of IoT devices and edge computing creates a new frontier for specialized solutions designed to protect and recover data generated outside traditional data centers.
- Compliance-Specific Services:Developing managed Disaster Recovery as a Service (DRaaS) offerings tailored to specific regulatory frameworks, such as HIPAA in the US healthcare sector, addresses a critical market need.
Industry Challenges
- Talent Scarcity:A persistent shortage of cybersecurity and cloud architects skilled in designing, implementing, and testing complex, multi-cloud recovery plans constrains enterprise adoption and vendor support capabilities.
- Legacy System Integration:Integrating modern data protection tools with aging legacy applications and infrastructure without causing operational disruption or data incompatibility remains a primary technical hurdle for many organizations.
- Recovery Verification:The difficulty and expense of conducting realistic, full-scale recovery tests lead many organizations to operate with unverified and potentially unreliable business continuity plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Protection and Recovery Solutions Market |
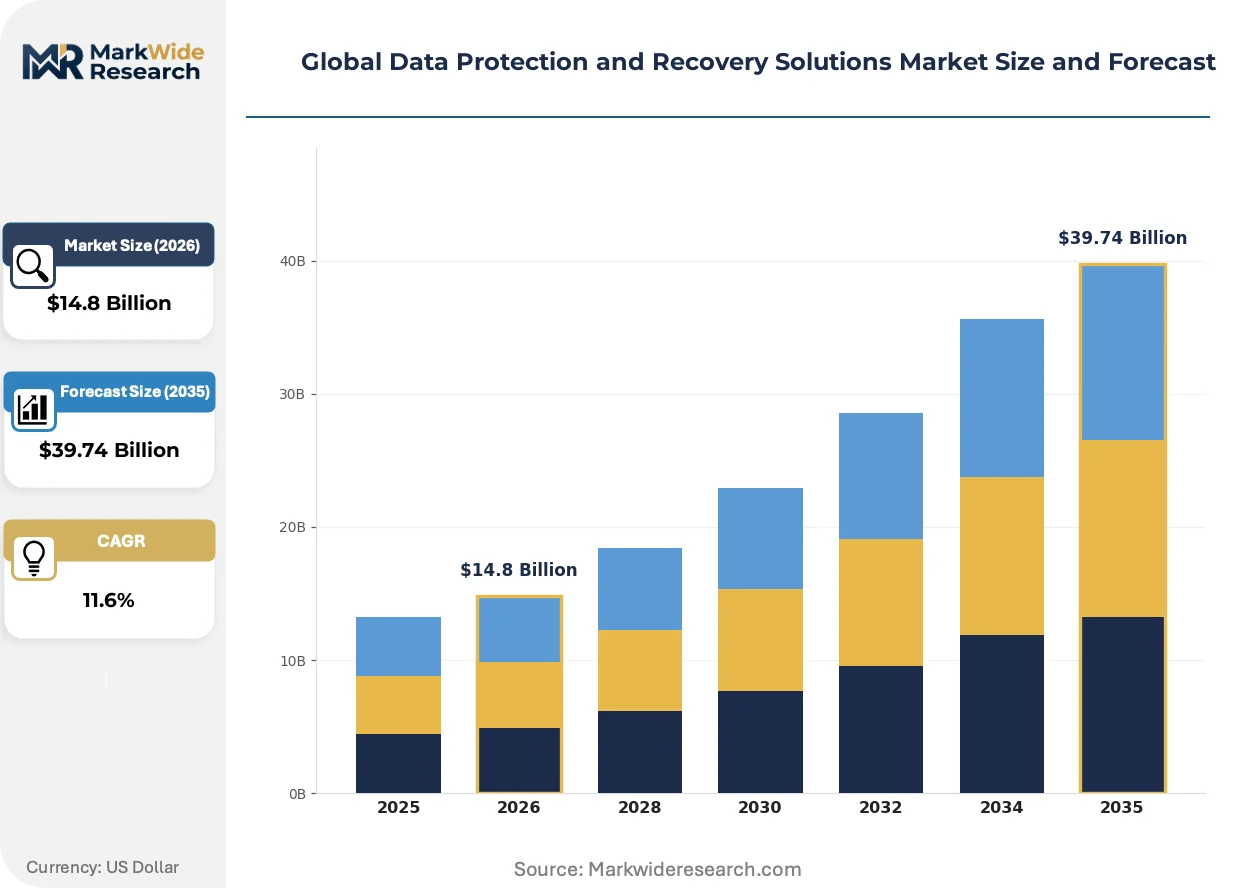
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Backup Software, Disaster Recovery, Data Archiving, Storage Snapshots, Continuous Data Protection, Deduplication Deployment Model: Cloud-Based, On-Premises, Hybrid Cloud, Managed Services End User Industry: Information Technology, Telecommunications, Financial Services, Education, Manufacturing, Government Agencies Data Source: Virtual Machines, Databases, File Systems, Applications, Email Servers, Mobile Devices |
| Companies Covered | International Business Machines Corporation (IBM), Dell Technologies Inc., Microsoft Corporation, Veeam Software AG, Commvault Systems Inc., Veritas Technologies LLC, Acronis International GmbH, Rubrik Inc., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Protection and Recovery Solutions Market Strategic Shifts & Innovations
Automation and artificial intelligence are redefining data protection, shifting the focus from reactive recovery to proactive data resilience. This evolution emphasizes predictive threat detection and self-healing capabilities, changing how organizations ensure business continuity.
AI-driven anomaly detection continuously monitors data patterns to identify potential ransomware encryption or data corruption. Financial services and healthcare sectors are rapidly adopting this technology to minimize data loss windows. This intelligent oversight is consolidating the functions of malware scanning, data integrity checks, and backup verification into a single, automated workflow.
Brazil's Lei Geral de Proteção de Dados (LGPD) imposes strict rules on cross-border data transfers, mirroring the EU's GDPR. This regulation compels multinational firms to implement local or region-specific data backup and recovery infrastructure. The cloud services segment is most affected, now offering in-country data residency to retain enterprise customers.
A shift from large, upfront capital expenditures on perpetual software licenses toward flexible, subscription-based models is accelerating. This disrupts the traditional enterprise sales channel, favoring cloud marketplace transactions and direct-to-customer digital platforms. This consumption-based procurement is most visible in the mid-market segment across North America and Europe.
Global Data Protection and Recovery Solutions Market Segmentation
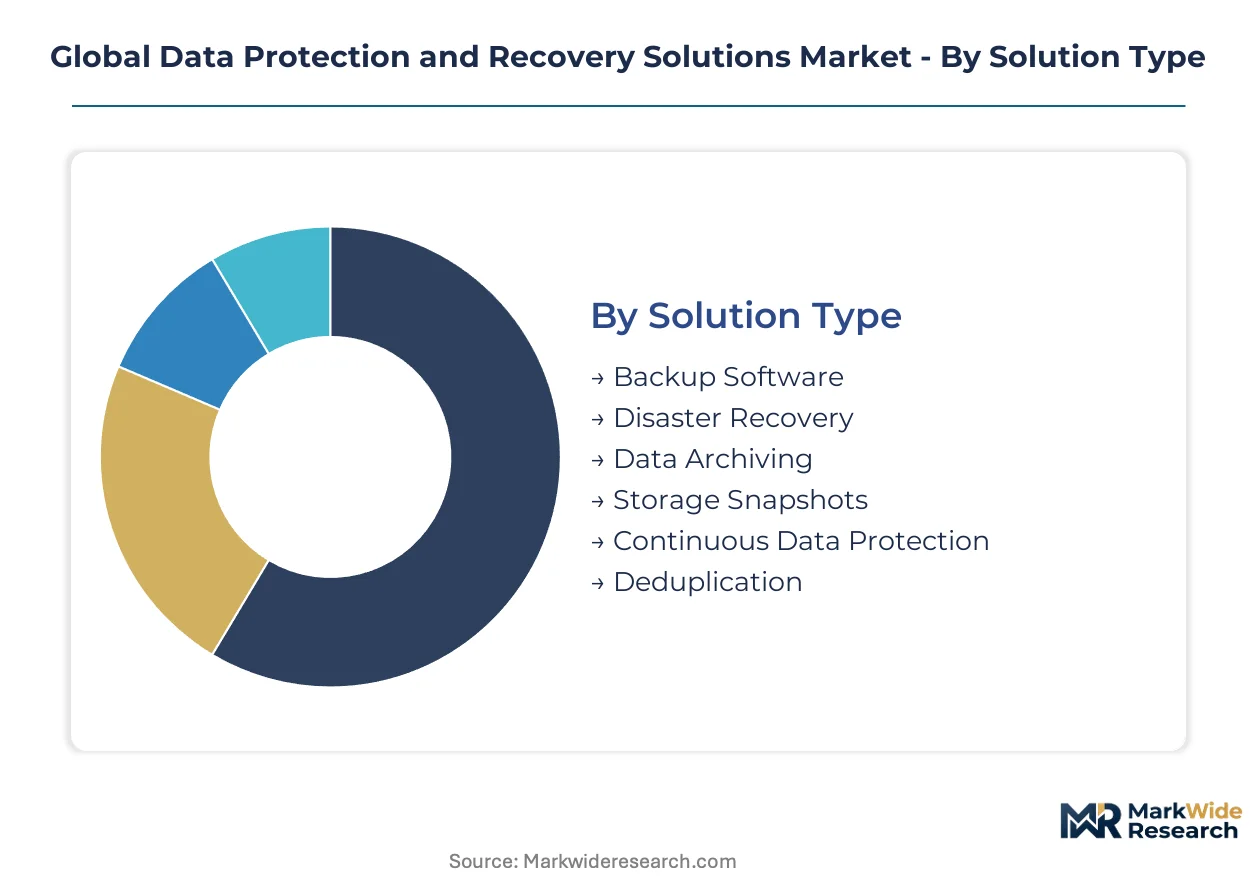
Understanding the Global Data Protection and Recovery Solutions Market requires a granular breakdown of its components. This segmentation highlights how diverse technological approaches and deployment preferences cater to varied organizational needs. Analyzing these segments reveals critical shifts in buyer priorities and operational models.
Solution Type:
Buyer decisions in data protection often hinge on the specific recovery objectives and resilience requirements.
- Backup Software:These solutions create copies of data at a specific point in time, enabling restoration in case of loss or corruption. Demand concentrates in regulated industries like financial services, driven by stringent data retention policies and audit requirements.
- Continuous Data Protection:This technology captures every change to data, allowing recovery to any point in time with minimal data loss. Financial services and telecommunications sectors require this near-zero RPO capability to maintain uninterrupted operations.
- Disaster Recovery:These services and tools facilitate the restoration of IT infrastructure and operations following a disruptive event.
- Data Archiving:Solutions for long-term storage of inactive data, primarily for compliance or historical reference.
- Storage Snapshots:Point-in-time virtual copies of data that offer quick recovery options with minimal performance impact.
- Deduplication:A process that eliminates redundant copies of data, optimizing storage capacity and network bandwidth.
Volume sits with Backup Software; growth tilts toward Continuous Data Protection.
Deployment Model:
The operational cost structure and scalability demands heavily influence an organization's choice of deployment architecture.
- Cloud-Based:These models leverage public or private cloud infrastructure for data storage and recovery, offering scalability and reduced on-premises hardware management. Enterprises globally are migrating to cloud-based solutions for disaster recovery, driven by cost efficiencies and remote accessibility.
- Hybrid Cloud:This approach integrates on-premises infrastructure with public or private cloud resources, balancing control with scalability. Organizations in Germany and France adopt hybrid models to meet data sovereignty laws while leveraging cloud benefits.
- On-Premises:Traditional deployments where infrastructure and software reside within the organization's own data centers.
- Managed Services:Third-party providers manage data protection and recovery operations on behalf of the client organization.
Cloud-based deployment models are gaining share fastest, while hybrid cloud solutions maintain strong relevance for complex environments.
End User Industry:
The industry-specific compliance mandates and data criticality levels significantly shape the adoption patterns for data protection solutions.
- Financial Services:This sector requires robust, highly available data protection due to the critical nature of transactional data and strict regulatory oversight. Ransomware mitigation and compliance with GDPR and US SEC regulations drive significant investment in advanced recovery systems.
- Telecommunications:Operators manage vast quantities of customer and network data, necessitating continuous data protection and rapid recovery to ensure service uptime. The sector's demand for near-zero RPO solutions is accelerating across Asian markets.
- Information Technology:IT organizations require comprehensive solutions to protect their own infrastructure, applications, and client data.
- Education:Institutions need to safeguard student and administrative data, often balancing budget constraints with compliance needs.
- Manufacturing:Protection of intellectual property, operational data, and supply chain information is critical for manufacturing continuity.
- Government Agencies:Public sector entities require secure and compliant data protection for citizen information and critical government functions.
Financial services exhibit the largest demand, with telecommunications showing the steepest expansion trajectory.
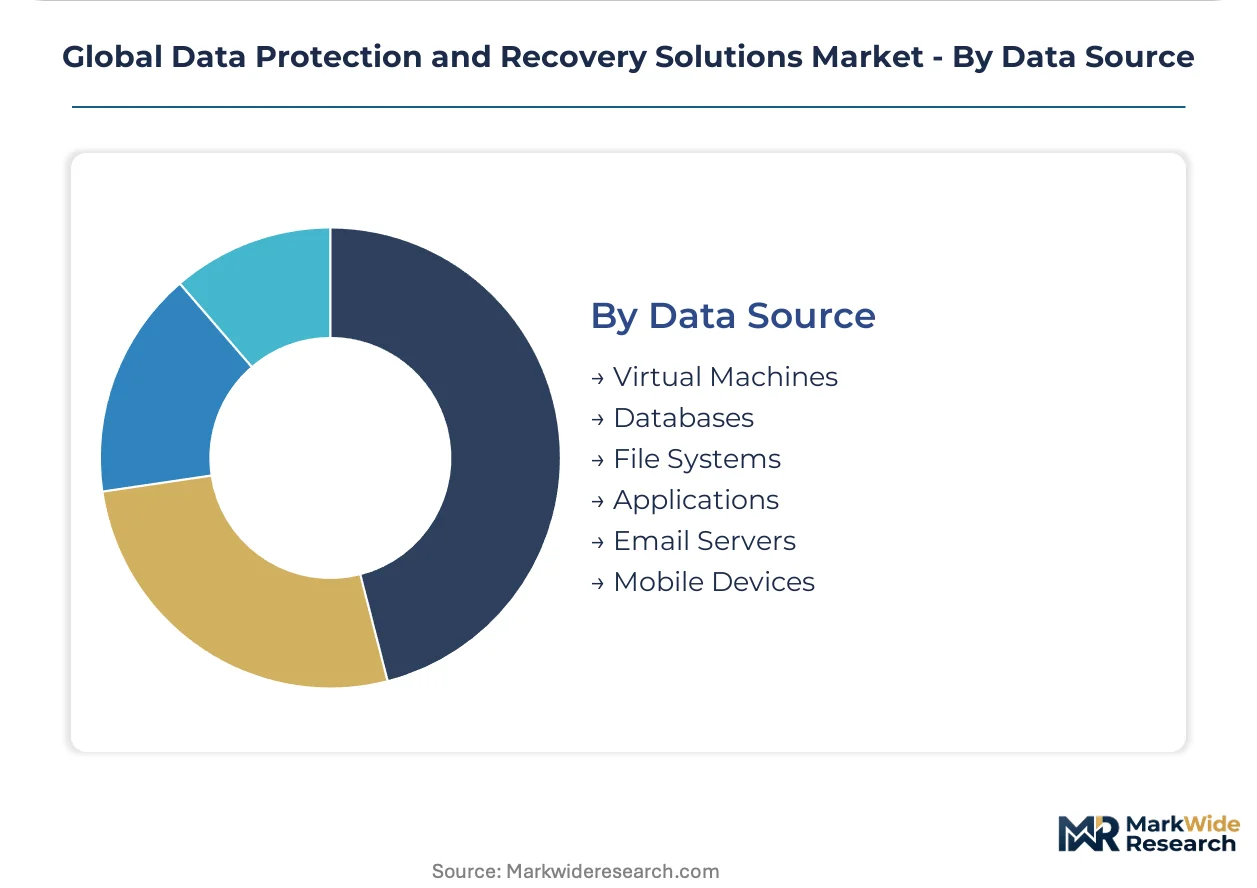
Data Source:
The underlying data infrastructure and its inherent complexity dictate the specialized tools required for effective protection and recovery.
- Virtual Machines:These virtualized computing environments require specialized backup and recovery agents that can handle entire VM images or granular data within them. Enterprises in the United States rely on VM protection for efficient resource utilization and rapid workload restoration.
- Databases:Critical business applications rely on databases, necessitating point-in-time recovery and transactional consistency for data integrity. Organizations across Europe prioritize database protection to ensure business continuity and meet audit requirements.
- File Systems:Protection for unstructured data stored in traditional file systems, including documents, images, and videos.
- Applications:Solutions designed to protect data generated and used by specific business applications, ensuring their availability.
- Email Servers:Specialized tools for backing up and restoring email communications and mailboxes, crucial for business records.
- Mobile Devices:Protection strategies for data residing on smartphones, tablets, and other portable devices, often critical for remote workforces.
Virtual machines represent a substantial segment, with databases demonstrating consistent growth in protection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global data protection and recovery solutions market exhibits a clear divide between regions driving technological innovation and those experiencing rapid adoption. While mature economies often lead in developing advanced solutions, emerging markets increasingly contribute to demand. This dynamic interplay shapes regional investment priorities and regulatory responses to data security challenges.
United States
Demand for data protection solutions in the United States stems from stringent compliance requirements across critical sectors. The US HIPAA mandates secure backup and recovery for protected health information, driving significant investment in healthcare. Financial services firms, concentrated in New York City and Chicago, require robust systems to meet SEC regulations and mitigate ransomware risks.
Germany
Germany's market for data protection is heavily influenced by strict data sovereignty laws and the EU's GDPR. Organizations prioritize hybrid cloud solutions to balance data residency needs with scalability. The KBA, Germany's federal motor transport authority, influences automotive sector data practices, while industrial clusters in Bavaria adopt advanced recovery for operational technology data.
Japan
Japan's digitalization initiatives and focus on data privacy fuel the need for advanced backup and recovery systems. The country's METI promotes cybersecurity investments across industries to protect critical infrastructure. Technology hubs in Tokyo and Osaka are seeing increased adoption of continuous data protection for financial transactions and cloud-native applications.
India
India's rapid digital transformation across government and enterprise sectors generates substantial demand for scalable data protection. Data localization policies and the proposed Digital Personal Data Protection Act compel organizations to secure data within national borders. Major IT centers like Bengaluru and Hyderabad are experiencing growth in managed recovery services for cloud environments.
Brazil
Brazil's Lei Geral de Proteção de Dados (LGPD) imposes strict data protection rules, mirroring the EU's GDPR, which drives investment in compliant solutions. Financial services in São Paulo require near-zero RPO capabilities to ensure business continuity and meet central bank regulations. The country's national health surveillance agency, ANVISA, influences data management standards in the healthcare sector.
Global Data Protection and Recovery Solutions Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the data protection and recovery solutions market. The industry structure is tiered, featuring large enterprise IT providers alongside agile, cloud-native vendors. Strategic partnerships and portfolio diversification represent dominant competitive moves as companies seek to offer integrated cyber resilience platforms.
At the scale-driven end, International Business Machines Corporation (IBM) anchors comprehensive data management suites for large enterprise accounts. Microsoft Corporation exemplifies a cloud ecosystem provider, embedding backup and recovery services within its Azure platform. Veeam Software AG occupies a specialized position, focusing on virtual machine backup and replication for hybrid cloud environments.
| Leading Market Players |
|---|
| International Business Machines Corporation (IBM) |
| Dell Technologies Inc. |
| Microsoft Corporation |
| Veeam Software AG |
| Commvault Systems Inc. |
| Veritas Technologies LLC |
| Acronis International GmbH |
| Rubrik Inc. |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Specialized cybersecurity talent concentration in regions like the United States and India drives labor-cost differentials, directly influencing pricing-tier spreads for advanced data protection services. This talent availability shapes the competitive landscape.
Pricing Analysis
Cost-down pressure on basic backup functionalities accelerates because cloud infrastructure platforms increasingly bundle them, impacting standalone software vendors. The dominant pricing structure shifts toward flexible, subscription-based models for advanced solutions. Price differentiation stems from solution complexity, such as continuous data protection, and the level of managed services provided. Small and medium-sized enterprises (SMEs) exhibit the most price sensitivity, often opting for bundled or basic offerings, while large enterprises prioritize comprehensive, high-availability systems.
Supply Chain Analysis
Workforce availability for software development and technical support in countries like the United States, India, and Ireland forms the backbone of the data protection supply chain. This ecosystem relies on cloud infrastructure services from major providers and specialized software components for encryption and deduplication. Talent scarcity, particularly for cloud architects and cybersecurity experts, represents a significant structural risk. Distribution runs through direct sales channels for large enterprises and cloud marketplaces for mid-market and smaller customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is supply-constrained by the persistent shortage of cybersecurity and cloud architects, which props up pricing for specialized implementation and managed services.
For Market Incumbents:Cement ecosystem lock-in by deeply integrating data protection services within broader cloud platforms, countering the threat from specialized niche players. Invest in AI-driven automation for anomaly detection and self-healing capabilities, enhancing service value. Expand managed Disaster Recovery as a Service (DRaaS) offerings tailored to specific regulatory frameworks like HIPAA. Control over critical cloud infrastructure components serves as a key lever.
For New Entrants and Emerging Players:Begin with specialized solutions targeting underpenetrated segments, such as edge computing or IoT data protection, where legacy systems struggle. Focus on developing compliance-specific services for regional regulations like Brazil's LGPD or India's proposed Digital Personal Data Protection Act. A go-to-market angle emphasizing rapid deployment and simplified management through cloud-native architectures can attract mid-market clients.
For Investors and Strategic Acquirers:Re-rating potential sits with pure-play specialists demonstrating strong recurring revenue from subscription models, given the shift away from perpetual licenses. Target companies with proprietary AI-driven anomaly detection or robust multi-cloud data sovereignty capabilities. The signal to watch is the increasing enterprise adoption of continuous data protection, indicating a sustained need for near-zero RPO solutions over the long term.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Anomaly Detection | Enhances proactive threat identification and minimizes data loss windows in critical sectors. |
| Expand Cloud-Native DRaaS Offerings | Addresses growing demand for flexible, scalable disaster recovery solutions across various industries. |
| Develop Multi-Cloud Data Sovereignty Tools | Helps multinational corporations meet diverse regional data residency and compliance requirements. |
| Invest in Edge and IoT Data Protection | Captures new market opportunities from the proliferation of data generated outside traditional data centers. |
| Form Strategic Partnerships with Hyperscalers | Extends market reach and embeds specialized solutions within established cloud ecosystems. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a broad market overview. Primary research involved in-depth interviews with CTOs, IT procurement officers, data center managers, and compliance specialists across key geographies. This approach combined qualitative insights with quantitative validation, ensuring comprehensive data coverage and accuracy through bottom-up and top-down triangulation.
Market volume and value were modeled across the analysis window, segmented by solution type, deployment model, end-user industry, and data source. The analytical framework incorporated historical growth trends, technological adoption rates, and regulatory impact assessments. Compound annual growth rates (CAGRs) were derived from a detailed analysis of market drivers and restraints, with forecast inputs including projected cloud adoption and cybersecurity spending patterns.
Geopolitical instability, rapid technological shifts in AI, and evolving regulatory frameworks are the dominant revision risks for market projections. Forecasts reflect assumptions regarding sustained digital transformation and increasing cyber threats. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Rope Rescue Harness Market