
 Global Disaster Recovery Software Market | 2026-2036
Global Disaster Recovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disaster Recovery Software Market Foresight
The shift from on-premise-only to hybrid multi-cloud sourcing is hardening across enterprise IT departments. Cohesity leverages unified data management architectures to compete in fragmented mid-market accounts. Veeam anchors its position through deep Microsoft ecosystem integration and channel density. Rubrik specializes in immutable backup and ransomware recovery, differentiating its platform against legacy tape-dependent rivals.
Disaster recovery software encompasses platforms that automate backup, replication, failover, and restoration of IT systems following disruptive events, typically achieving recovery time objectives under four hours for tier-one workloads. The technology serves commercial and industrial users by minimizing operational downtime and preserving data integrity across distributed infrastructure. Cloud-based deployment leads solution uptake as organizations exit capital-intensive data center commitments, while backup management and data replication capture the dominant margin pools within the solution stack. Automation orchestration represents the fastest-growing segment as enterprises seek to reduce manual intervention during declared incidents.
ISO 22301 business continuity standards, GDPR data residency mandates, and SEC cybersecurity disclosure rules collectively elevate disaster recovery from operational checkbox to board-level accountability. HIPAA and FERC requirements impose sector-specific recovery timelines that filter vendor qualification criteria. Stakeholders must weigh immutable architecture claims against actual recovery validation testing before committing to multi-year platform contracts.
Market Dynamics
Immutable backup architectures and zero-trust security frameworks are collapsing the distinction between cybersecurity and disaster recovery procurement, forcing vendors to certify joint resilience capabilities before enterprise buyers release budget.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Mandated incident reporting timelines compress recovery planning cycles across US-listed enterprises, elevating automated failover from optional to compliance-critical infrastructure.
- Financial Services:Basel III operational resilience guidelines and ECB stress-testing protocols drive tier-one banks to replace tape-dependent recovery with sub-hour replication SLAs.
- Edge Computing Proliferation:Distributed manufacturing and remote energy assets generate fragmented data estates that demand localized recovery orchestration beyond centralized data center models.
Market Restraints
- Skilled Architect Scarcity:Shortages of certified cloud resilience engineers in Germany and Japan extend implementation timelines and inflate professional services margins.
- Hyperscaler Concentration:AWS, Azure, and GCP control over seventy percent of secondary storage infrastructure, creating single-point-of-failure risk for multi-tenant disaster recovery platforms.
- Cross-Border Data Friction:China's Cybersecurity Law and Russia's data localization mandates fragment global recovery orchestration, forcing redundant in-country infrastructure investments.
Strategic Opportunities
- India Manufacturing:PLI scheme incentives for semiconductor and electronics production create greenfield demand for industrial IoT backup and operational technology recovery systems.
- EU AI Act:Proposed high-risk system availability requirements position automated disaster recovery as essential infrastructure for algorithmic trading and healthcare diagnostics platforms.
- Channel Convergence:Managed security service providers in the United Kingdom are bundling ransomware recovery with endpoint detection, opening distribution paths for integrated data protection vendors.
Industry Challenges
- Legacy Integration Complexity:Mainframe-dependent insurers and government agencies struggle to orchestrate failover across COBOL workloads and containerized cloud environments.
- Validation Testing Gaps:Enterprises lack disciplined chaos engineering programs, leaving claimed recovery time objectives unverified until actual incidents expose orchestration failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disaster Recovery Software Market |
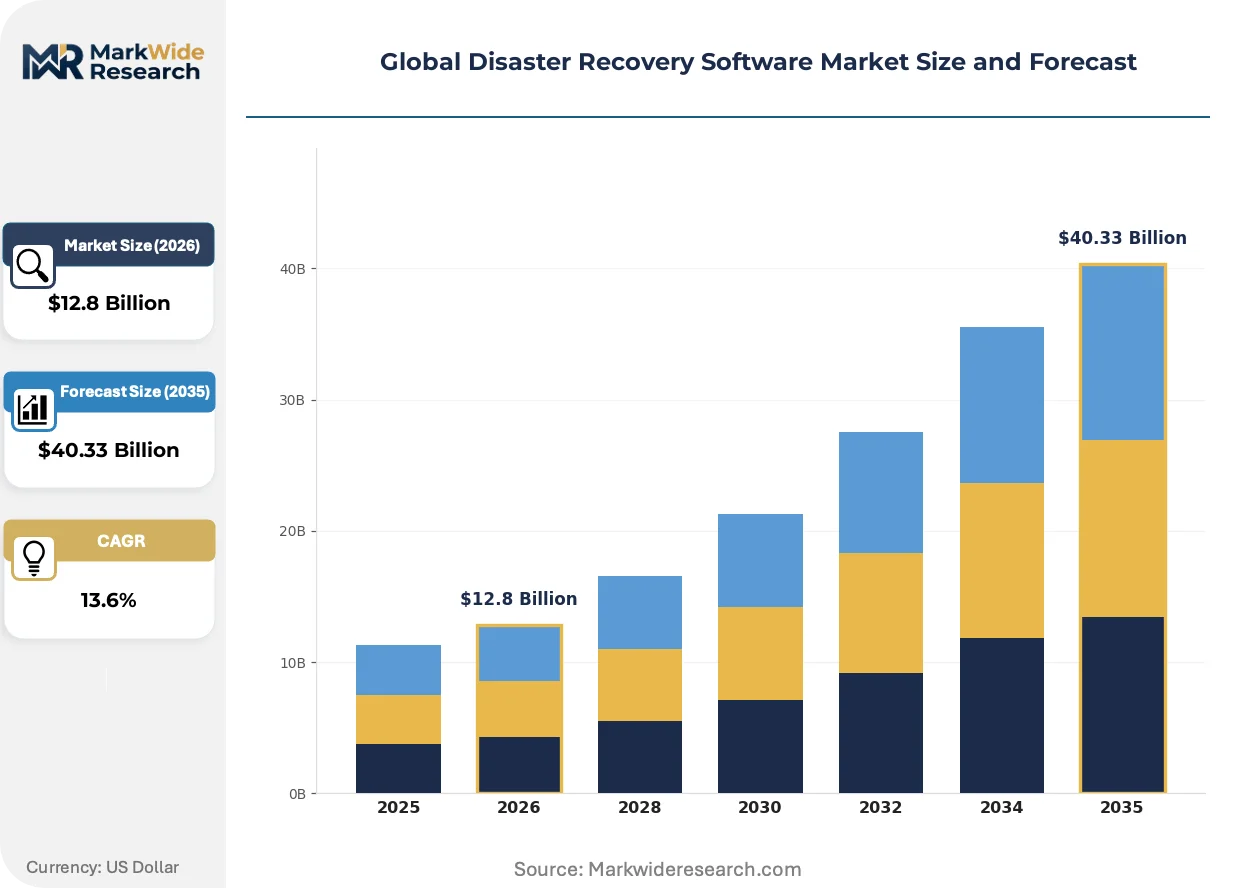
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premise, Hybrid Cloud, Managed Services Solution: Backup Management, Data Replication, Virtualization, Automation Orchestration, Compliance Monitoring Use Case: Data Protection, Business Continuity, Risk Management, Incident Response, IT Infrastructure Protection End User: BFSI Institutions, Telecommunication Providers, Government Agencies, Educational Organizations, Energy Companies |
| Companies Covered | Druva, Cohesity, Veeam, Rubrik, Quorum, Zerto, Commvault, Arcserve, Acronis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disaster Recovery Software Market Shifts & Advancements
Artificial intelligence and policy mandates are compressing the window between incident detection and system restoration, redefining competitive advantage around autonomous recovery rather than backup capacity alone.
Unified data management platforms are unifying backup, archive, and analytics storage tiers into single software-defined architectures. Mid-market healthcare and legal services buyers in the United States are adopting these consolidated stacks to eliminate siloed point products. This convergence is unifying vendor selection criteria around API extensibility and cross-cloud portability rather than restoration speed metrics alone.
GDPR Article 32 security requirements and proposed NIS2 Directive continuity mandates are hardening recovery specifications across European critical infrastructure operators. Energy utilities and transport networks must now demonstrate tested failover procedures under regulatory examination. German grid operators and French hospital systems are prioritizing vendors with pre-certified compliance documentation to accelerate procurement cycles.
Consumption-based licensing models are displacing perpetual software agreements in enterprise disaster recovery procurement. Buyers in Japan and Australia now demand metered pricing tied to actual protected data volumes rather than peak capacity commitments. This shift pressures traditional vendors to restructure revenue recognition while enabling mid-size organizations to access tier-one resilience capabilities previously locked behind capital expenditure barriers.
Global Disaster Recovery Software Market Segmentation
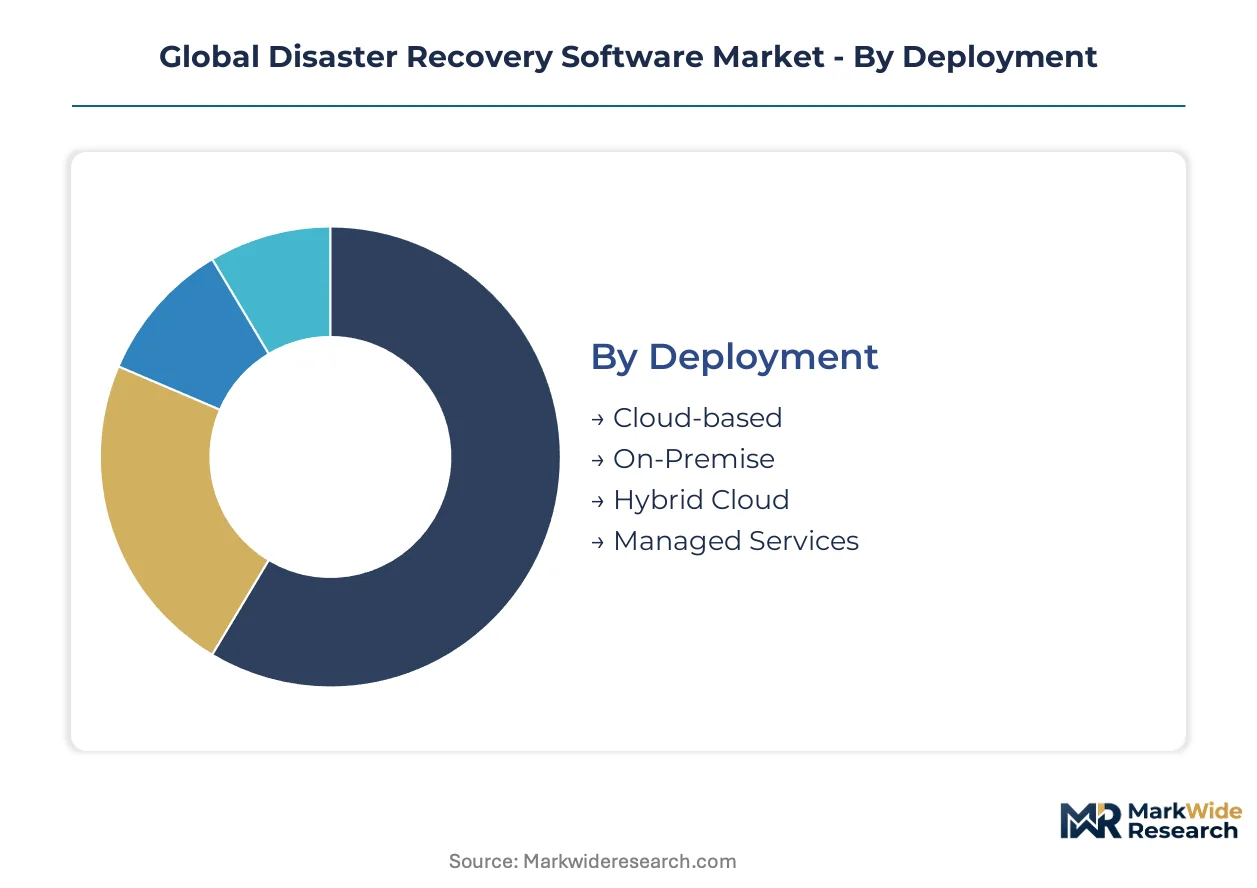
Disaster recovery procurement varies sharply across deployment modes and use cases, with regulatory mandates dictating which solution architectures qualify for specific industries. Buyers segment budgets by recovery time requirements, data sovereignty constraints, and audit traceability needs rather than feature checklists alone.
Deployment:
Cloud-based deployments face ISO 27001 certification requirements for financial services adoption, while on-premise installations must satisfy FERC physical security standards for energy sector procurement.
- Cloud-based:Multi-tenant architectures with consumption-based licensing dominate mid-market uptake in the United States and Australia. Healthcare providers in Germany select these platforms to satisfy GDPR Article 32 data residency mandates without capital expenditure commitments.
- On-Premise:Dedicated hardware installations serving classified government workloads and air-gapped industrial control systems. Japanese manufacturing conglomerates maintain these configurations for operational technology networks that cannot tolerate external connectivity.
- Hybrid Cloud:Tiered architectures combining local caching with cloud archival for variable recovery time objectives. Energy utilities in Texas and California deploy these models to balance sub-hour failover for SCADA systems against cost-optimized long-term retention.
- Managed Services:Third-party operated platforms where service providers assume operational responsibility for testing and validation. United Kingdom financial services firms contract these arrangements to transfer regulatory liability under SEC cybersecurity disclosure rules.
Cloud-based sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Solution:
Backup management commands the largest budget allocation, though automation orchestration captures expanding share as labor costs for manual failover procedures escalate.
- Backup Management:Core platforms executing scheduled data capture, deduplication, and retention policy enforcement. BFSI institutions in Switzerland and Singapore prioritize these systems for Basel III operational resilience documentation.
- Data Replication:Real-time or near-real-time synchronization across geographically distributed storage targets. Telecommunication providers in South Korea deploy these for 5G network function virtualization continuity.
- Virtualization:Snapshot-based recovery for virtual machine estates, enabling rapid restoration without bare-metal rebuilds. Educational organizations across Canada adopt these tools to protect research computing clusters.
- Automation Orchestration:Policy-driven runbook execution that eliminates manual decision-making during declared incidents. French hospital systems under ANSM oversight implement these to compress recovery windows for patient-critical applications.
- Compliance Monitoring:Continuous audit trail generation and control validation for regulatory examination. Government agencies in Saudi Arabia require these capabilities for SFDA-aligned healthcare data protection.
Backup management retains the largest installed base, while Automation Orchestration expands most quickly.
Use Case:
Risk management applications attract premium pricing as insurers and reinsurers quantify downtime exposure with increasing precision.
- Data Protection:Foundational backup and restore operations preserving information integrity against corruption or deletion. Small and medium enterprises across Brazil prioritize these capabilities for ANVISA pharmaceutical record retention.
- Business Continuity:Comprehensive planning frameworks ensuring operational persistence through workforce relocation and alternative site activation. German automotive suppliers implement these for supply chain disruption mitigation.
- Risk Management:Quantified assessment of recovery probability and residual exposure for insurance underwriting and board reporting. Lloyd's of London syndicates mandate these analyses for cyber policy pricing.
- Incident Response:Coordinated technical and procedural activation following security breaches or infrastructure failures. Australian critical infrastructure operators deploy these under TGA-aligned health sector continuity protocols.
- IT Infrastructure Protection:Hardware and network resilience measures spanning redundant power, cooling, and connectivity. Data center operators in the United Arab Emirates construct these defenses for MOHAP healthcare cloud hosting requirements.
Data Protection dominates current deployment, with Risk Management gaining share fastest.
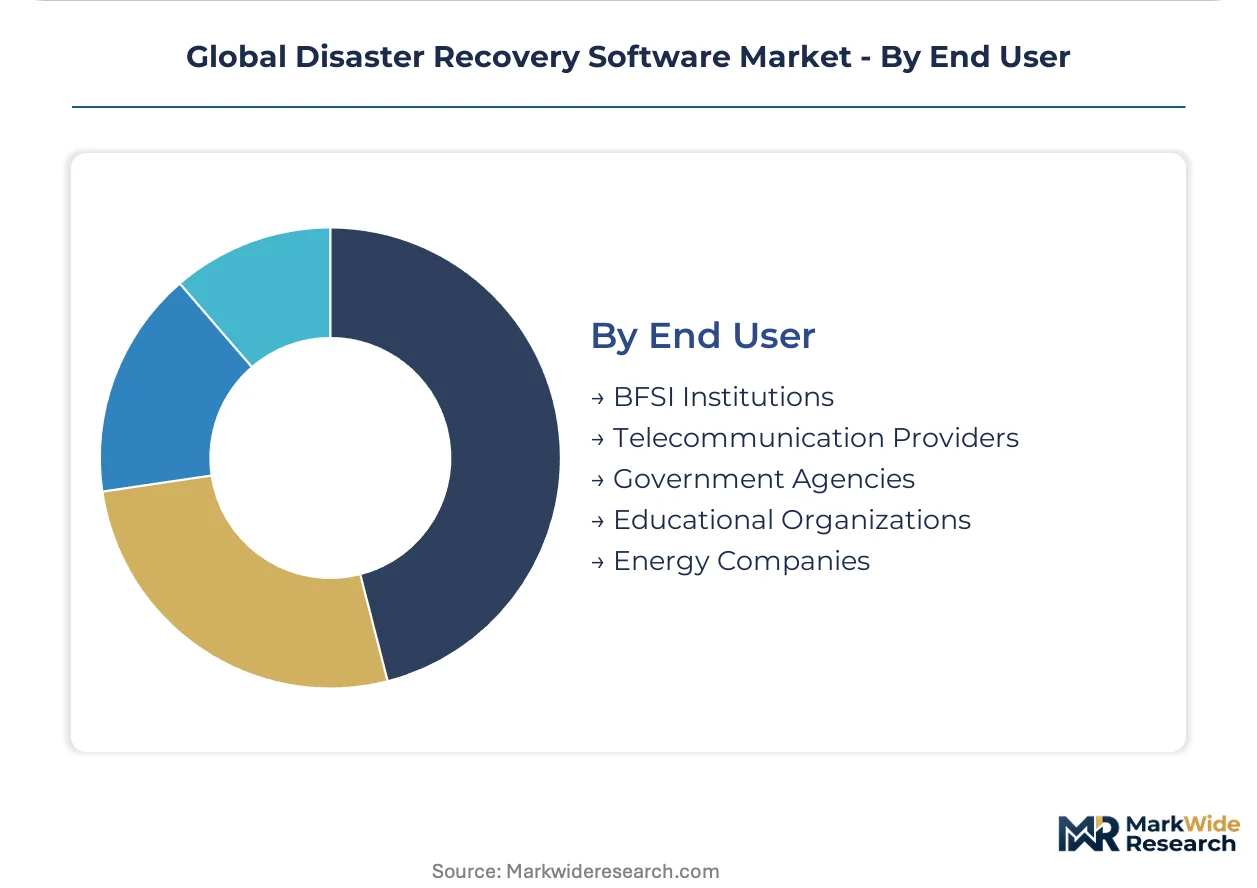
End User:
BFSI procurement cycles run longest due to multi-layered regulatory approval requirements across ECB, SEC, and national banking supervisors.
- BFSI Institutions:Banks, insurers, and asset managers subject to stringent recovery time obligations and audit frequency. Swiss private banks and Japanese megabanks lead spending on sub-hour replication architectures.
- Telecommunication Providers:Network operators maintaining service continuity for emergency communications and national infrastructure. South Korean carriers under MSIT oversight invest heavily in distributed edge recovery.
- Government Agencies:Federal, state, and municipal entities protecting citizen records and administrative systems. Indian state governments deploy these for RBI-mandated financial inclusion program continuity.
- Educational Organizations:Universities and research institutions safeguarding intellectual property and student information. Canadian institutions prioritize these for provincial privacy commissioner compliance.
- Energy Companies:Generation, transmission, and distribution operators facing NERC CIP and FERC reliability standards. French EDF and German RWE implement specialized operational technology recovery for generation control systems.
BFSI Institutions sit at the top of the volume ranking, with Energy Companies climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services clusters in New York, London, and Frankfurt drive disproportionate procurement volumes as regulatory mandates harden recovery specifications. Cloud infrastructure density and critical infrastructure protection budgets concentrate demand across the United States, Germany, and Japan.
United States
SEC cybersecurity disclosure rules compress recovery planning cycles for listed enterprises, elevating automated failover to compliance-critical infrastructure. Financial services firms in Manhattan and Chicago deploy sub-hour replication architectures to satisfy Basel III operational resilience guidelines. Energy utilities across Texas and California implement hybrid cloud models balancing SCADA failover speed against long-term retention costs.
Germany
ECB stress-testing protocols drive tier-one banks to replace tape-dependent recovery with immutable backup architectures. GDPR Article 32 data residency mandates reshape procurement criteria for healthcare providers in Berlin and Munich. Industrial conglomerates in Baden-Württemberg prioritize vendors with pre-certified ISO 22301 documentation to accelerate procurement cycles.
Japan
Critical infrastructure protection budgets expand across Tokyo and Osaka metropolitan areas under METI operational continuity directives. Manufacturing conglomerates maintain on-premise configurations for operational technology networks that cannot tolerate external connectivity. Skilled cloud resilience engineer scarcity extends implementation timelines and inflates professional services margins nationwide.
United Kingdom
Managed security service providers in London bundle ransomware recovery with endpoint detection, opening distribution paths for integrated data protection vendors. Lloyd's of London syndicates mandate quantified recovery probability analyses for cyber policy pricing. NHS trusts under TGA-aligned protocols prioritize automated orchestration to compress recovery windows for patient-critical applications.
India
PLI scheme incentives for semiconductor and electronics production create greenfield demand for industrial IoT backup systems across Karnataka and Tamil Nadu. State governments deploy disaster recovery platforms for RBI-mandated financial inclusion program continuity. Mumbai-based BFSI institutions lead private sector spending on cloud-based resilience architectures.
Global Disaster Recovery Software Market Competitive Landscape
Global majors compete with regional champions across data sovereignty requirements and ecosystem integration depth. The vendor base stratifies into three tiers: hyperscale-integrated platforms, compliance-specialized providers, and managed service bundlers. Strategic differentiation centers on immutable architecture certification, Microsoft ecosystem anchoring, and ransomware recovery validation. M&A activity targets chaos engineering capabilities and edge orchestration technologies.
Within the unified data management tier, Cohesity and Rubrik exemplify platform consolidation strategies competing for mid-market healthcare and legal services accounts. Veeam anchors the Microsoft ecosystem integration archetype through channel density and replication SLA guarantees. These three companies occupy positions spanning backup management, automation orchestration, and compliance monitoring segments.
| Leading Market Players |
|---|
| Druva |
| Cohesity |
| Veeam |
| Rubrik |
| Quorum |
| Zerto |
| Commvault |
| Arcserve |
| Acronis |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices cascade through disaster recovery software supply chains, compressing margins for vendors tethered to hyperscaler storage commitments while enabling consumption-based competitors to capture mid-market accounts across Australia and Japan.
Pricing Analysis
Input-cost pass-through from hyperscaler storage and compute fees shapes tiered SaaS pricing structures across the market. Price differentiation hinges on ISO 27001 certification tier and geographic data residency compliance, with German healthcare buyers paying premiums for GDPR-aligned architectures. Pricing pressure stems from metered licensing displacement of perpetual agreements, particularly in Japan's mid-market. Small and medium enterprises exhibit highest price sensitivity, while BFSI institutions prioritize recovery SLAs over cost minimization.
Supply Chain Analysis
Enterprise storage hardware supply rests on Taiwanese semiconductor foundries, South Korean memory fabricators, and Chinese server assembly operations. Cloud resilience platforms draw from specialized encryption processors, NVMe storage controllers, and network acceleration silicon. Single-source vulnerability concentrates in hyperscaler API dependencies, where AWS, Azure, and GCP control secondary storage infrastructure. Distribution runs through managed security service providers in the United Kingdom and value-added resellers across North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disaster recovery procurement arbitrage opportunities open between Germany's certified-premium segment and India's price-sensitive greenfield manufacturing base, exploiting a three-to-five-fold cost differential in implementation labor and regulatory compliance documentation.
For Market Incumbents: Anchor market position through immutable architecture certification investments that preempt regulatory scrutiny under SEC cybersecurity disclosure rules. Deepen Microsoft ecosystem integration to defend against cloud-native challengers. Prioritize chaos engineering capability acquisitions to close validation testing gaps that erode enterprise trust in claimed recovery SLAs. For New Entrants and Emerging Players: Capture white-space demand in India's PLI-scheme manufacturing corridors, where semiconductor and electronics production lacks established operational technology recovery vendors. Target mid-market legal services in the United States with unified data management platforms that consolidate backup, archive, and analytics tiers. Pursue channel partnerships with managed security service providers in London to bundle ransomware recovery with endpoint detection offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with edge orchestration specialists serving distributed energy and manufacturing assets beyond centralized data center models. Long-term viability favors vendors with pre-certified compliance documentation spanning ISO 22301, GDPR Article 32, and sector-specific mandates like HIPAA and FERC. Watch hyperscaler pricing volatility as the inflection indicator that reshapes vendor margin structures and customer switching economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified data management architectures consolidate backup, archive, and analytics tiers for mid-market healthcare buyers. |
| Acquisition of Specialist Firm | Chaos engineering capabilities address enterprise validation testing gaps and strengthen recovery SLA credibility. |
| Strategic Partnership | Managed security service provider alliances in London open ransomware recovery distribution paths. |
| Geographic Expansion | India's PLI manufacturing corridors present greenfield demand for industrial IoT backup systems. |
| Product Launch | Immutable backup architectures with zero-trust certification satisfy collapsing cybersecurity-disaster recovery procurement boundaries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and regulatory mandate databases. Bottom-up deployment estimates and top-down market sizing triangulated across cloud infrastructure spend correlations and enterprise software procurement patterns.
Segment-weighting approaches distributed value across deployment modes, solution types, use cases, and end-user verticals, with regional adoption patterns and integration complexity tiers informing cross-sectional allocation. CAGRs derived from fitted growth curves against historical spending trajectories, incorporating compliance mandate acceleration timelines and hyperscaler pricing elasticity as software-specific forecast inputs.
Regulatory mandate delays, hyperscaler pricing volatility, and skilled architect scarcity are the dominant revision risks that could compress or extend projected market expansion. Forecasts reflect documented assumptions about compliance enforcement intensity and cloud migration velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Italy Ransomware Protection Market