
 France Ransomware Protection Market | 2026-2036
France Ransomware Protection Market Size, Share, and Industry Trends Forecast 2026-2036
France Ransomware Protection Market Insights
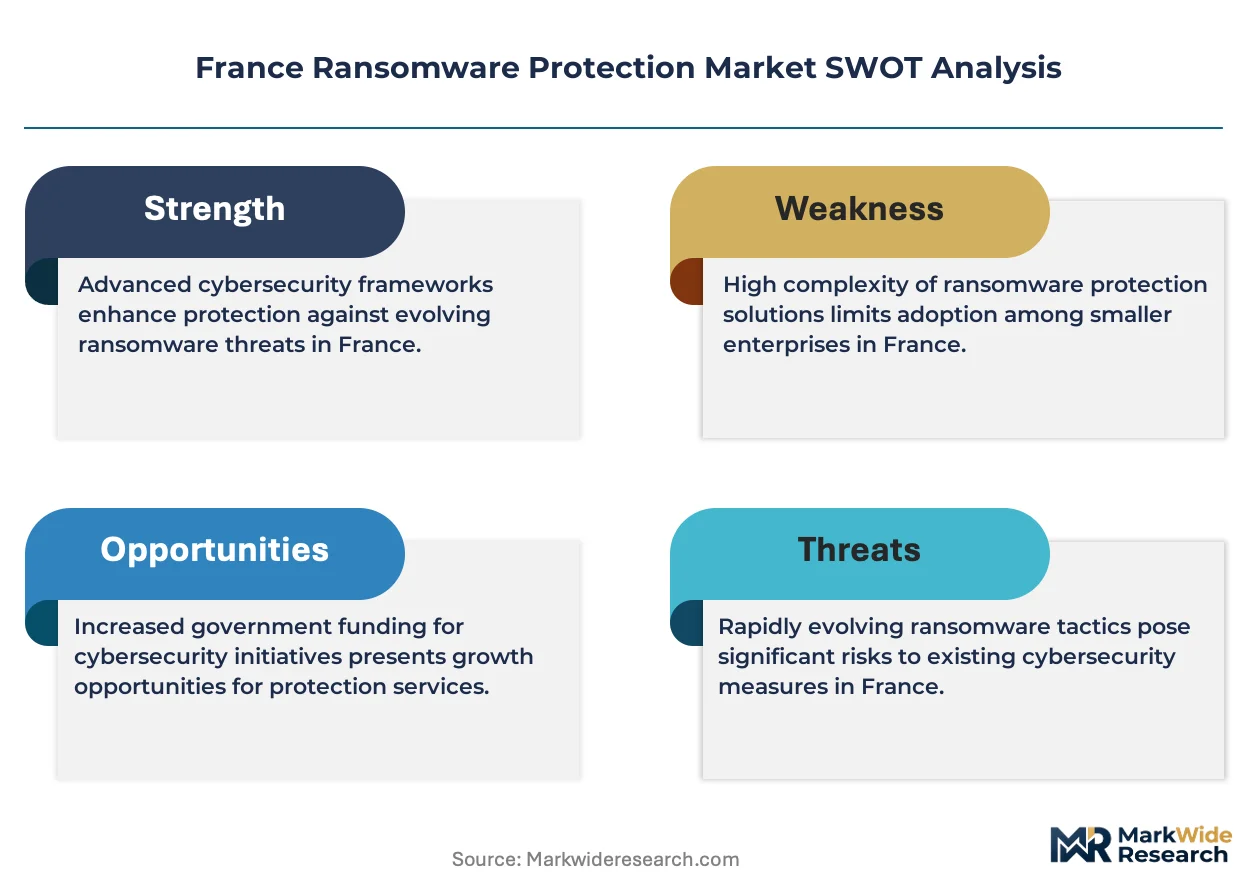
Subscription-based managed detection and response financing is reshaping how mid-sized French enterprises access enterprise-grade ransomware protection without capital-intensive infrastructure investments. Thales Group leverages its defense-grade encryption heritage to anchor high-assurance contracts with government and aerospace clients. Orange Cyberdefense competes through its nationwide SOC network and direct integration with France's critical infrastructure operators. Stormshield differentiates via its ANSSI-certified security suite, the only French-origin product holding the highest national cybersecurity qualification.
France Ransomware Protection encompasses integrated hardware, software, and service architectures engineered to prevent, detect, and recover from cryptographic extortion attacks against enterprise IT and operational technology environments, typically incorporating real-time behavioral monitoring, immutable backup verification with sub-15-minute recovery point objectives, and automated threat intelligence ingestion. The primary commercial purpose centers on preserving business continuity for organizations facing financially motivated adversaries targeting France's concentrated financial services, healthcare, and manufacturing sectors. Cloud-based deployment models are capturing disproportionate growth as French enterprises accelerate migration to sovereign cloud frameworks under EU data residency requirements. AI-Based Protection technology leads investment intensity among vendors, though behavioral analysis retains stronger margins due to scarcer engineering talent pools and longer integration cycles with legacy SIEM infrastructure.
ANSSI, France's national cybersecurity agency, mandates baseline security certification for products deployed within critical infrastructure, directly conditioning market access and procurement eligibility for domestic and foreign suppliers. The EU NIS2 Directive, transposed into French law through reinforced obligations on entities in transport, energy, and digital services, compels expanded ransomware protection spending and structured incident response capabilities. Stakeholders must monitor how France's pending implementation of the EU Cyber Resilience Act reshapes product liability and software supply chain security requirements for endpoint protection vendors.
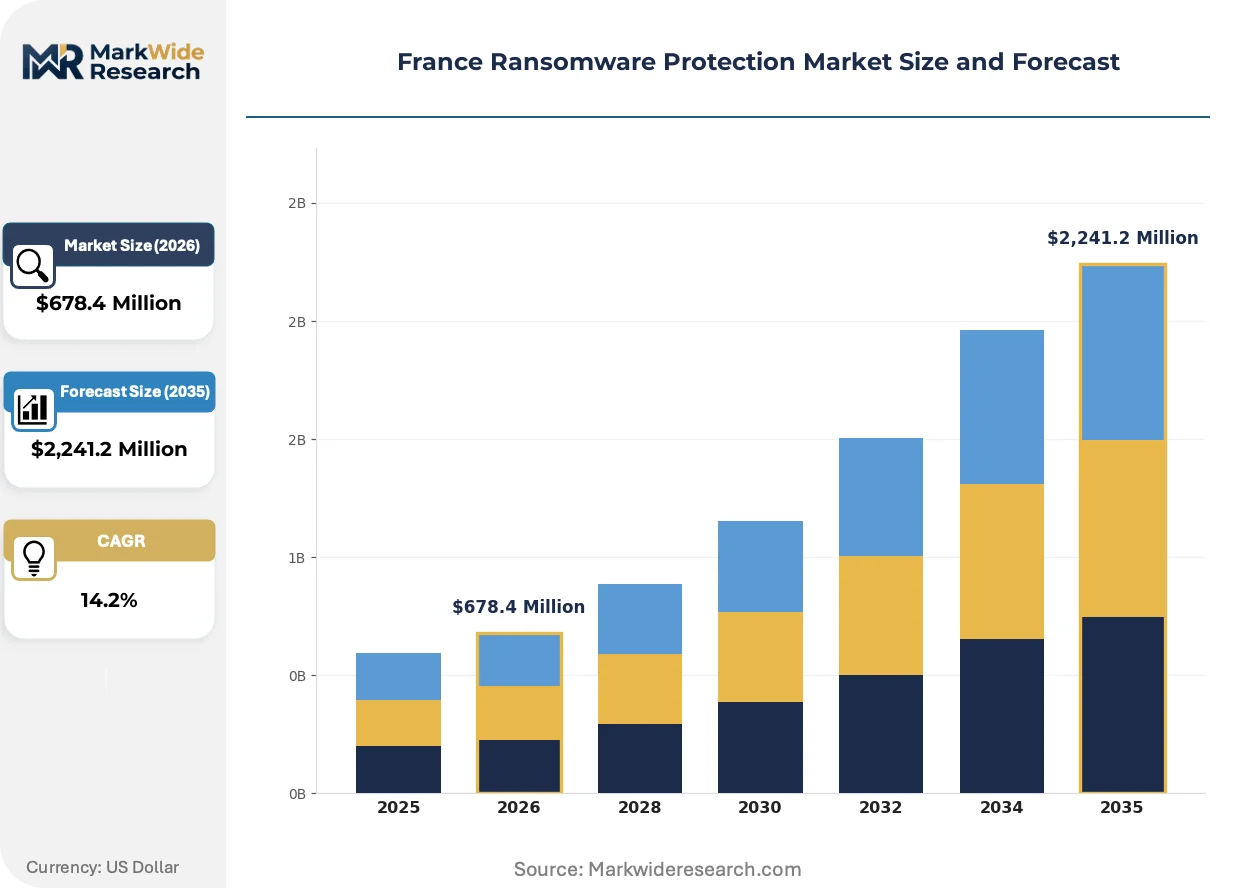
Market Dynamics
France's ransomware protection sector is compressing around sovereign cloud mandates and ANSSI certification requirements, forcing vendors to re-architect delivery models and foreign suppliers to establish domestic data residency infrastructure.
Growth Catalysts
- EU NIS2 Directive:The transposed framework imposes mandatory incident reporting and structured response capabilities on French energy, transport, and digital infrastructure operators, expanding addressable demand for managed detection services.
- Healthcare network expansion:French hospital systems are elevating cybersecurity budgets as ransomware attacks targeting patient data and operational technology intensify across the sector.
- Île-de-France enterprise clustering:Security operations concentrate in Paris and surrounding technology corridors, creating dense procurement environments where multi-tenant SOC services achieve scale economics.
Market Restraints
- Certification timeline friction:ANSSI's baseline security qualification process extends 18-24 months for foreign vendors, delaying market entry and privileging incumbent French suppliers.
- Engineering talent scarcity:Behavioral analysis and legacy SIEM integration require specialized cybersecurity skills concentrated in Paris, inflating implementation costs for mid-sized enterprises outside the capital region.
- Immutable backup infrastructure costs:Sub-15-minute recovery point objectives demand dedicated hardware and air-gapped storage architectures that strain capital budgets outside financial services.
Strategic Opportunities
- EU Cyber Resilience Act anticipation:Pending product liability and software supply chain mandates will compel endpoint protection vendors to re-certify offerings, creating first-mover advantages for ANSSI-prequalified domestic suppliers.
- AI-Behavioral convergence:Machine learning threat detection combined with human behavioral analysis addresses the talent gap while preserving margin structures in high-assurance contracts.
- Subscription financing penetration:Mid-sized manufacturing enterprises in Lyon and Marseille remain underpenetrated by managed detection and response models, presenting expansion targets for consumption-based pricing.
Industry Challenges
- Legacy infrastructure integration:Manufacturing and healthcare OT environments operate decades-old systems that resist seamless integration with modern behavioral monitoring platforms, extending deployment cycles.
- ANSSI compliance complexity:Multi-tier certification requirements for critical infrastructure create documentation burdens that smaller vendors struggle to resource, consolidating procurement around established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Ransomware Protection Market |
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $2,241.2 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Incident Response, Threat Intelligence, Backup Solutions, Security Assessment Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Finance, Retail, Education Technology: AI-Based Protection, Behavioral Analysis, Endpoint Detection, Encryption |
| Companies Covered | Thales Group, Orange Cyberdefense, Atos SE, Capgemini SE, Stormshield, Palo Alto Networks Inc., Cisco Systems Inc., Fortinet Inc., Check Point Software Technologies Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Ransomware Protection Market Trends and Innovations
Cloud delivery architectures are displacing on-premise deployment as French enterprises navigate data sovereignty requirements, while AI-driven detection converges with human behavioral analysis to address persistent talent constraints.
Extended detection and response platforms are virtualizing security operations by consolidating endpoint, network, and identity telemetry into unified cloud-native architectures. French financial services institutions in Paris are migrating fastest, compressing vendor consolidation timelines and reducing integration overhead across fragmented toolchains.
ANSSI's evolving certification framework is tightening product qualification requirements ahead of EU Cyber Resilience Act implementation. Industrial consequence includes mandatory supply chain security attestations for endpoint protection vendors. Critical infrastructure operators in energy and transport are pre-emptively requiring ANSSI-certified offerings in procurement specifications.
Mid-sized enterprises are abandoning capital-intensive security infrastructure ownership in favor of consumption-based managed services. System integrators and telecommunications carriers are capturing this demand through bundled SOC-as-a-service offerings. The shift is most visible among manufacturing enterprises in secondary French cities seeking enterprise-grade protection without Paris-scale security teams.
France Ransomware Protection Market Segmentation
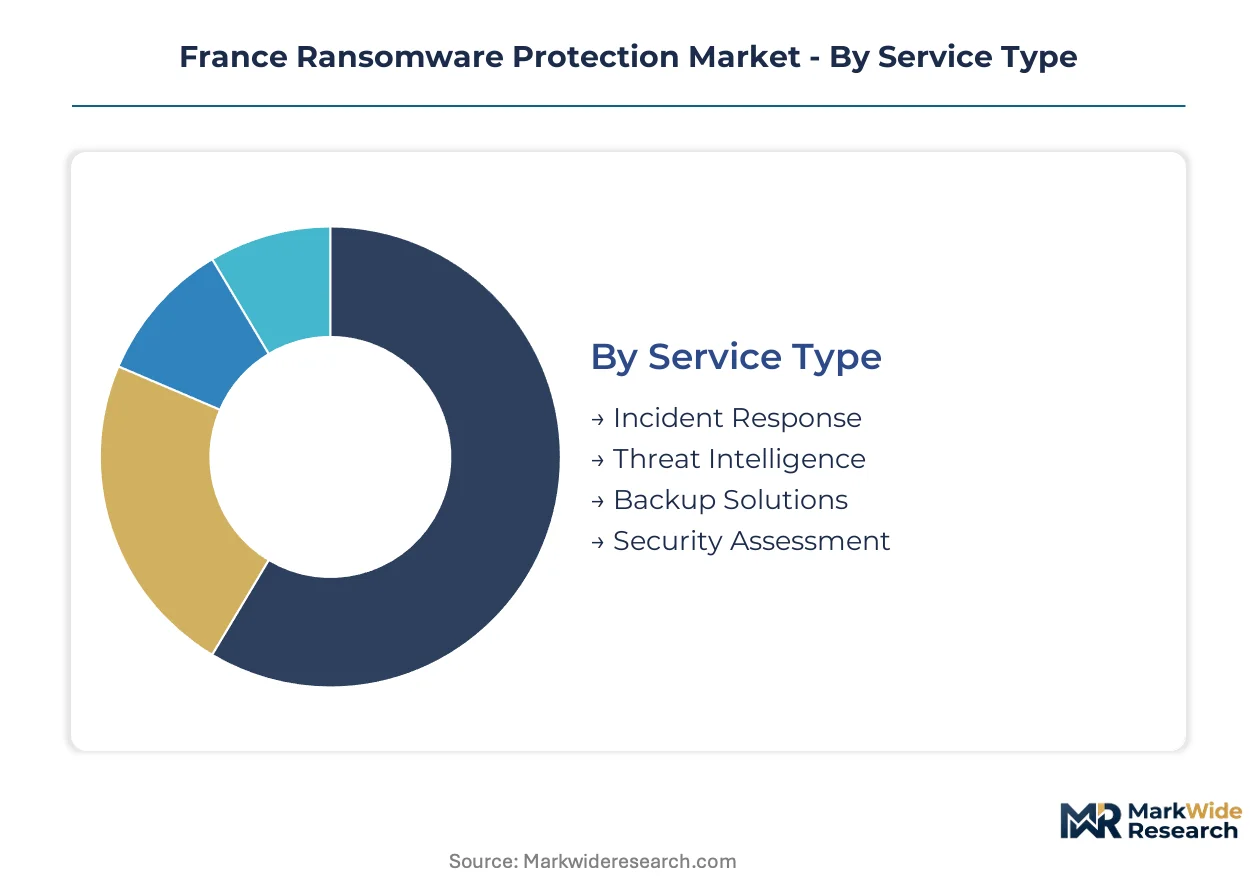
Segmentation reveals how ransomware protection procurement patterns diverge across French enterprises. Service intensity, deployment complexity, and regulatory exposure create distinct commercial pockets that vendors must navigate separately.
Service Type:
After-sales service intensity varies dramatically across protection services, with incident response demanding 24/7 human availability and backup solutions requiring minimal ongoing touchpoints.
- Incident Response:Retainer-based emergency deployment teams activate within contractual time windows to contain active encryption campaigns. French healthcare networks in Paris and Lyon concentrate spending here as ransomware attacks on hospitals intensify.
- Threat Intelligence:Curated feeds of adversary indicators and attack patterns delivered through API or analyst briefings. Energy and transport operators under EU NIS2 Directive obligations drive adoption for proactive defense.
- Backup Solutions:Immutable storage architectures with air-gapped recovery capabilities.
- Security Assessment:Penetration testing and vulnerability validation services.
By volume, Backup Solutions leads. By growth pace, Incident Response is ahead.
Deployment Model:
Cost tier separation shapes vendor selection, with capital-constrained mid-sized manufacturers favoring consumption models over infrastructure ownership.
- Cloud-Based:Sovereign cloud frameworks hosted within French data centers satisfy EU data residency requirements while eliminating hardware procurement cycles. Financial services institutions in Île-de-France migrate fastest to compress vendor consolidation timelines.
- Managed Services:Subscription-based SOC-as-a-service bundles monitoring, detection, and response capabilities. Manufacturing enterprises in secondary cities like Marseille and Lyon adopt these to access enterprise-grade protection without Paris-scale security teams.
- On-Premises:Dedicated hardware and software stacks deployed within customer facilities.
- Hybrid:Split architectures combining local processing with cloud analytics.
By installed base, On-Premises retains the edge. By expansion trajectory, Cloud-Based deployment is climbing fastest.
End User:
Application-specific risk profiles determine solution architecture, with operational technology exposure creating fundamentally different procurement criteria than pure IT environments.
- Healthcare:Patient data protection and medical device continuity requirements dominate. French hospital systems elevate cybersecurity budgets as ransomware attacks targeting operational technology intensify across the sector.
- Finance:Transaction integrity and regulatory reporting obligations shape investment. Paris-based banking institutions drive premium spending for sub-15-minute recovery point objectives.
- Retail:Point-of-sale system protection and customer payment data security.
- Education:Distributed campus networks with limited central IT resources.
By absolute spending, Finance dominates. By budget growth rate, Healthcare is expanding most quickly.
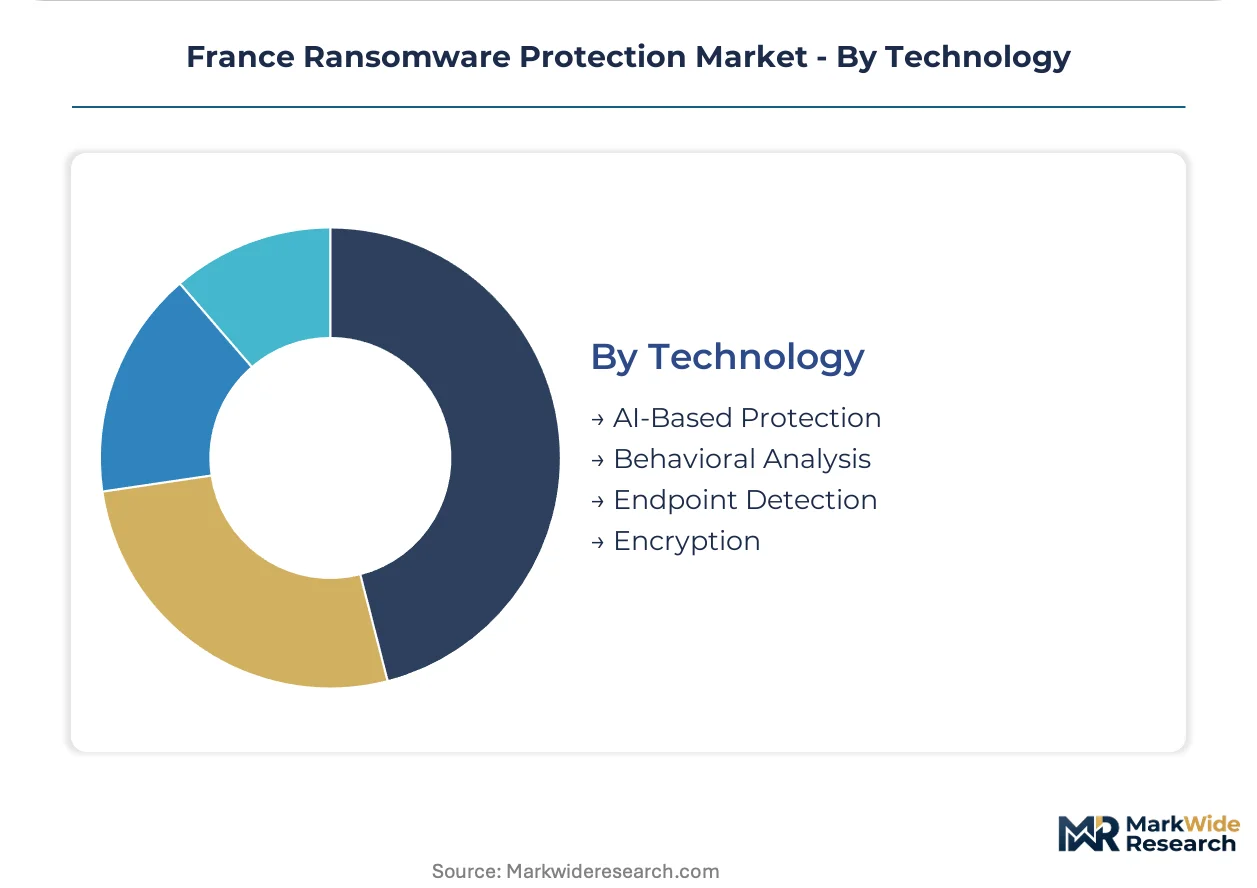
Technology:
Margin structures diverge sharply based on engineering scarcity, with behavioral analysis commanding premium pricing due to talent concentration in Paris.
- Behavioral Analysis:Human-driven pattern recognition integrated with legacy SIEM infrastructure. Scarce engineering talent pools and longer integration cycles preserve stronger margins in high-assurance contracts with government and aerospace clients.
- AI-Based Protection:Machine learning models trained on threat telemetry for automated detection. Vendors prioritize this technology for investment intensity despite compressed margins from competitive algorithm commoditization.
- Endpoint Detection:Agent-based monitoring of workstations and servers for anomalous activity.
- Encryption:Data-at-rest and data-in-transit cryptographic protection standards.
By current revenue share, Endpoint Detection leads. By vendor R&D allocation, AI-Based Protection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU NIS2 Directive transposition into French law is accelerating ransomware protection procurement across critical infrastructure sectors. Hospital networks and energy operators face mandatory incident reporting obligations. Regional demand concentrates where security operations clusters intersect with regulated industries.
Île-de-France
Paris anchors the densest concentration of enterprise security operations in France. Financial services institutions drive premium spending for sub-15-minute recovery point objectives. ANSSI headquarters proximity shapes procurement preferences toward certified domestic vendors. La Défense and Saclay technology corridors host multi-tenant SOC facilities serving banking and aerospace clients.
Auvergne-Rhône-Alpes
Lyon's healthcare networks are elevating cybersecurity budgets as ransomware attacks on hospitals intensify. The region's manufacturing base demands OT-compatible protection for legacy industrial systems. EU NIS2 obligations extend to transport operators along the Rhône corridor. Grenoble's cybersecurity research cluster supplies engineering talent to behavioral analysis vendors.
Provence-Alpes-Côte d'Azur
Marseille's port and logistics infrastructure falls under expanded critical infrastructure designation. Maritime and energy operators invest in managed detection services to satisfy transposed EU directive requirements. Aix-Marseille technology park hosts emerging SOC-as-a-service providers targeting mid-sized enterprises. Toulon's naval defense presence sustains demand for ANSSI-certified high-assurance contracts.
Hauts-de-France
Lille's banking and insurance sector concentrates procurement for cloud-based sovereign protection frameworks. The region's automotive manufacturing supply chain faces OT integration challenges with modern behavioral monitoring platforms. EU data residency requirements favor French-hosted cloud deployments. Valenciennes logistics hubs adopt subscription-based financing models for mid-market ransomware protection.
Nouvelle-Aquitaine
Bordeaux's aerospace and defense contractors leverage Thales Group heritage for encryption-intensive contracts. The region's wine and agri-food processing sector remains underpenetrated by managed detection services. ANSSI certification timelines delay foreign vendor entry, privileging established French suppliers. Biarritz data centers serve as secondary sovereign cloud nodes for Paris failover architectures.
France Ransomware Protection Market Competitive Landscape
On the supply side, the industry is consolidating around ANSSI certification barriers and sovereign cloud mandates. French-origin vendors command structural advantages in critical infrastructure procurement. Three archetypes dominate: defense-grade encryption heritage players, telecommunications-integrated SOC operators, and ANSSI-certified pure-play security specialists. Competitive moves center on domestic data residency infrastructure establishment and multi-tenant service platform expansion.
Among France-based suppliers, Thales Group anchors the defense-aerospace segment through its encryption heritage, while Orange Cyberdefense exemplifies telecommunications-carrier integration with nationwide SOC networks. Stormshield occupies a distinctive position as the sole French-origin vendor holding ANSSI's highest national cybersecurity qualification for its security suite. These three represent the core domestic tier that foreign competitors must displace through extended certification timelines and local infrastructure investment.
| Leading Market Players |
|---|
| Thales Group |
| Orange Cyberdefense |
| Atos SE |
| Capgemini SE |
| Stormshield |
| Palo Alto Networks Inc. |
| Cisco Systems Inc. |
| Fortinet Inc. |
| Check Point Software Technologies Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in behavioral analysis engineering talent across France's cybersecurity labor market compresses implementation timelines and elevates day rates for SIEM integration specialists, forcing vendors toward subscription financing models that shift capital burden to buyers while preserving margin structures for scarce expertise.
Pricing Analysis
ANSSI certification tier creates the primary spread between domestic and foreign supplier offerings, with SecNumCloud-qualified sovereign cloud services commanding premiums over uncertified alternatives. Three-tier pricing structure separates government-grade encryption contracts from mid-market managed detection subscriptions and economy backup solutions. Cost compression in cloud-based deployment stems from hyperscaler competition and algorithm commoditization in AI-driven detection. Mid-sized manufacturing enterprises outside Île-de-France exhibit highest price sensitivity, while aerospace and defense clients show least elasticity due to national security mandates.
Supply Chain Analysis
Upstream feedstock for encryption hardware draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with advanced node dependency for hardware security modules. Threat intelligence data sources rest on telemetry ingestion from global honeypot networks, dark web monitoring services, and government CERT exchanges. Single-source vulnerability in French sovereign cloud infrastructure creates concentration risk around domestic data center operators. Distribution runs through systems integrators and telecommunications carriers bundling SOC-as-a-service with connectivity contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's ransomware protection market sits in early-cycle expansion as EU NIS2 Directive transposition accelerates mandatory procurement across critical infrastructure sectors previously operating on voluntary security frameworks.
For Market Incumbents: Build certification moats through preemptive ANSSI SecNumCloud qualification ahead of EU Cyber Resilience Act implementation. Deepen vertical integration into sovereign cloud data center infrastructure to control residency compliance costs. Foreign hyperscaler entry threatens pricing power in mid-market segments; counter through multi-tenant SOC platform consolidation and behavioral analysis talent acquisition in Grenoble's cybersecurity cluster. For New Entrants and Emerging Players: Mid-market manufacturing enterprises in Lyon and Marseille represent the most penetrable entry point for consumption-based managed detection services lacking Paris-scale security operations. Healthcare networks in Auvergne-Rhône-Alpes face intensifying ransomware targeting with elevated procurement budgets but limited vendor relationships. Go-to-market through regional systems integrators already embedded in OT environments bypasses direct certification timeline disadvantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native delivery architectures as multi-tenant platforms achieve scale economics. Long-term viability favors acquisition targets combining ANSSI certification with behavioral analysis engineering depth rather than pure AI detection plays. Watch for EU Cyber Resilience Act implementation timeline as inflection signal for re-certification spending waves and vendor consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Investment | SecNumCloud qualification unlocks critical infrastructure procurement eligibility under transposed EU NIS2 obligations. |
| Sovereign Cloud Infrastructure Expansion | Domestic data center capacity addresses EU data residency requirements and reduces foreign supplier latency disadvantages. |
| Behavioral Analysis Talent Acquisition | Engineering scarcity in Paris and Grenoble clusters preserves margin structures in high-assurance government contracts. |
| Subscription Financing Model Penetration | Consumption-based pricing captures mid-sized manufacturing demand without capital-intensive infrastructure ownership. |
| OT-Compatible Platform Development | Legacy industrial system integration addresses manufacturing sector deployment friction and extends contract durations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANSSI certification registries, EU NIS2 implementation guidance, and hyperscaler sovereign cloud capex disclosures. Primary interviews engaged CISOs at French hospital networks, cybersecurity procurement leads at energy operators, platform engineers at domestic cloud providers, and channel partners distributing managed detection services. Secondary validation drew from SEC filings of listed security vendors, ANSSI annual activity reports, and EU Cyber Resilience Act legislative tracking. Bottom-up segment sizing triangulated against top-down critical infrastructure spending estimates.
Forecast inputs include deployment model migration rates, certification timeline distributions for foreign entrants, and healthcare sector budget expansion trajectories. Segmentation dimensions span service type intensity, deployment architecture, end-user regulatory exposure, and technology maturity tier. CAGRs derive from adoption curve modeling across the projection horizon, with AI-based protection investment intensity and behavioral analysis talent supply constraints as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in sovereign debt financing costs for public hospital networks or EU digital infrastructure grant disbursement schedules would shift the trajectory. Cross-checking against ANSSI incident reporting volume trends and healthcare sector cyber insurance premium movements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market