
 Rope Rescue Harness Market | 2026-2036
Rope Rescue Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Rope Rescue Harness Market Analytics
Lightweight load-distribution webbing is rewriting how rope rescue harnesses distribute force across the pelvis and upper thighs. Petzl leverages its alpine heritage to anchor premium positioning in mountaineering-derived rescue designs. CMC Rescue, Inc. dominates North American fire-service procurement through NFPA-certified product lines and deep distributor relationships. SKYLOTEC competes aggressively in European industrial fall-protection markets with modular harness architectures that extend into rope rescue applications.
A rope rescue harness is a personal protective system constructed from high-tenacity nylon or polyester webbing, rated typically to 13-15 kN breaking strength, designed to suspend and lower personnel during vertical extraction scenarios. Its primary purpose is to prevent suspension trauma while enabling controlled descent, ascent, and positioning in confined-space, high-angle, or tower rescue operations. Full-body harness configurations command the largest revenue pool due to mandatory adoption in professional rescue services, while tactical harness variants for military special-operations units represent the fastest-growing end-user category. Nylon remains the dominant material segment by volume, though Kevlar-reinforced models capture disproportionate margin in high-heat and cut-hazard environments.
NFPA 1983 in the United States, EN 358/EN 813 in Europe, and AS/NZS 1891 in Australia establish minimum breaking strength, corrosion resistance, and labeling standards that dictate product eligibility for institutional procurement. These certification frameworks create substantial compliance barriers for new entrants while mandating periodic equipment retirement that sustains replacement demand. Stakeholders must monitor evolving heat-resistance specifications as electric-vehicle battery fires introduce new thermal exposure profiles into urban rescue protocols.
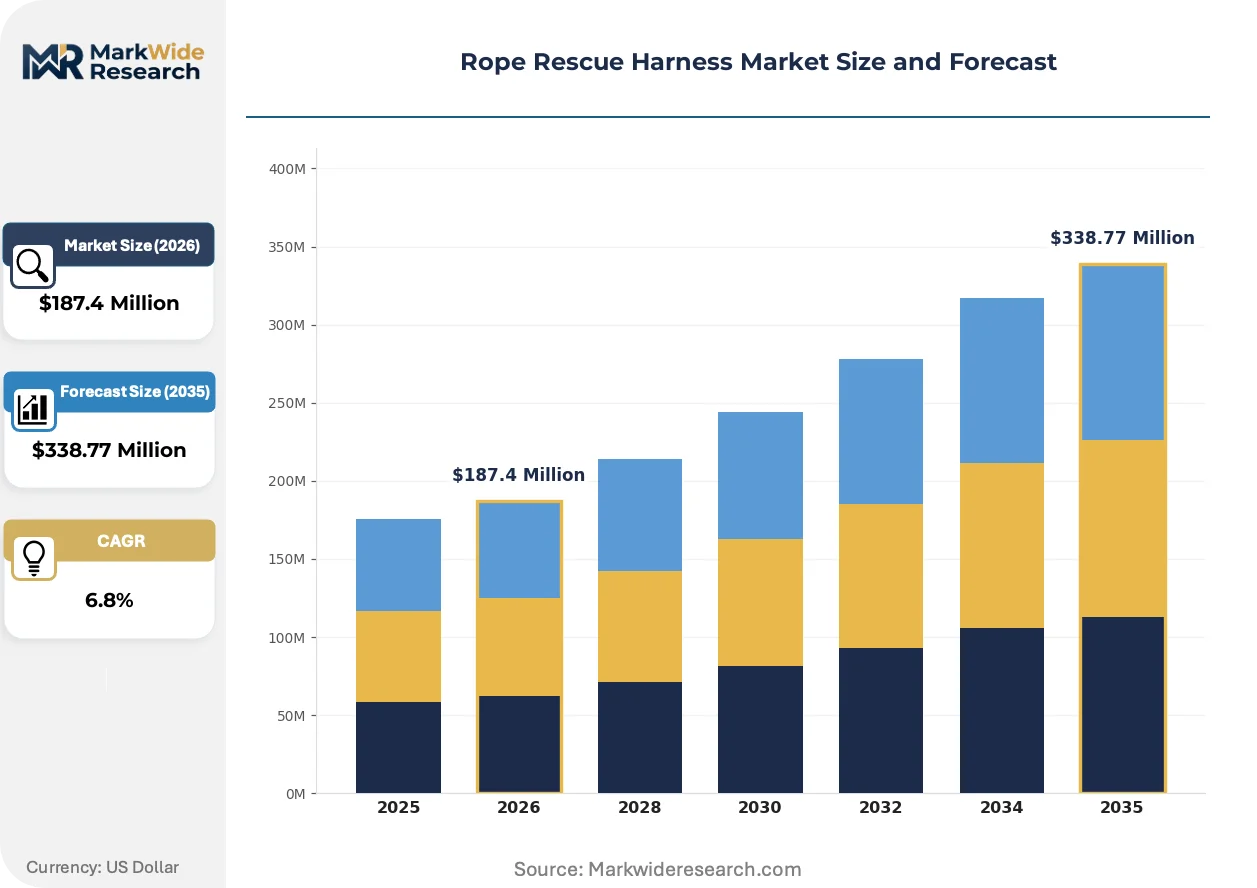
Market Dynamics
NFPA 1983's 2023 edition tightened heat-resistance thresholds and mandatory retirement timelines, forcing fire departments into accelerated replacement cycles while compressing supplier certification windows.
Growth Catalysts
- Urban Search-and-Rescue Funding:Federal allocations to FEMA USAR task forces in the United States drive institutional procurement volume for certified full-body systems.
- EN 358/EN 813 Harmonization:European standard convergence simplifies cross-border tender participation for manufacturers, expanding addressable market scope.
- Synthetic Webbing Substitution:Dyneema and Kevlar blends replace legacy nylon in high-heat configurations, opening premium tier expansion.
Market Restraints
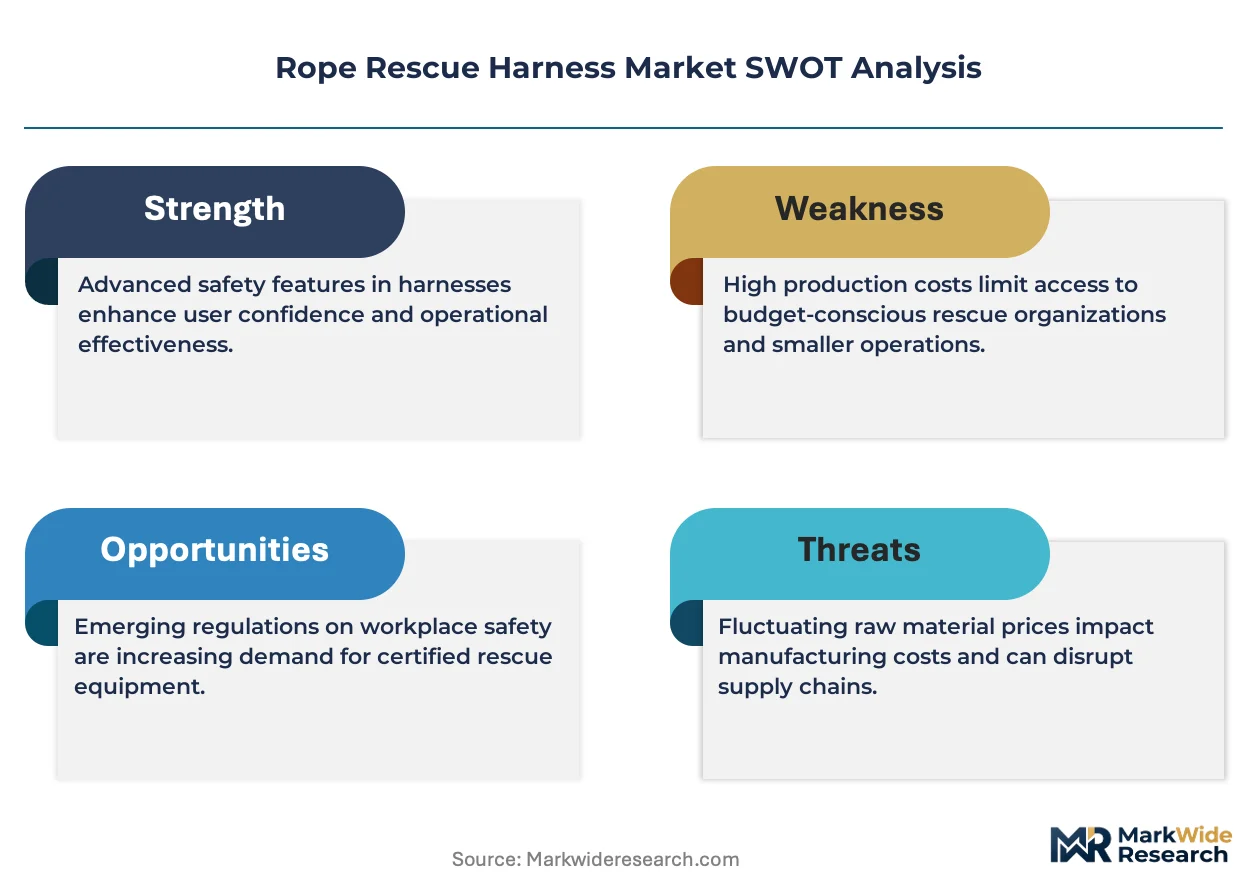
- Petrochemical Input Volatility:Nylon 6,6 and polyester resin prices fluctuate with crude oil indices, compressing margin on standard-grade harnesses.
- Certification Concentration:Third-party testing capacity clusters in Germany and the United States, creating bottlenecks for new market entrants.
- Extended Replacement Cycles:Industrial fall-protection harnesses rated to similar standards create substitution pressure in non-fire applications.
Strategic Opportunities
- Australia Infrastructure Investment:AS/NZS 1891 compliance mandates in mining and construction verticals create dedicated procurement channels for rescue-rated systems.
- Electric Vehicle Fire Protocols:Thermal runaway response training programs require heat-resistant harness configurations for battery compartment extractions.
- Direct Municipal Contracting:Digital procurement platforms bypass traditional distributor markups, enabling margin capture for certified manufacturers.
Industry Challenges
- Technical Rescue Instructor Scarcity:NFPA-certified trainer capacity limits deployment velocity for new harness technologies into fire-service academies.
- Multi-Standard Compliance Burden:Simultaneous EN, NFPA, and AS/NZS certification requires parallel testing streams, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rope Rescue Harness Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Body Harness, Chest Harness, Seat Harness, Tactical Harness End User: Firefighters, Military, Industrial Workers, Outdoor Enthusiasts Material: Nylon, Polyester, Kevlar, Cotton Application: Rescue Operations, Mountaineering, Rock Climbing, Search Operations |
| Companies Covered | CMC Rescue, Inc., Petzl, Martin Castle Limited, Conterra Inc, International Safety Components Ltd., SKYLOTEC, Arco Professional Safety Services Ltd., KASK s.p.a, ROCK EXOTICA LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rope Rescue Harness Market Evolving Landscape
Wearable sensor integration and advanced material science are compressing the performance gap between alpine mountaineering systems and institutional rescue configurations.
Load-sensing textile electronics is digitizing force distribution mapping in real-time rescue operations. Fire departments in California and Texas pilot harness-integrated strain gauges that transmit suspension trauma risk alerts to incident command. This capability is digitizing safety protocols that previously relied on visual buddy checks and manual timer discipline.
REACH Annex XVII restrictions on flame retardant chemistries are forcing reformulation of webbing coatings across European supply chains. Manufacturers serving German and French industrial markets accelerate halogen-free alternatives to maintain CE marking eligibility. Industrial rope access contractors face compressed material qualification periods as notified bodies adapt testing protocols.
Consolidated municipal purchasing cooperatives reshape how mid-sized fire departments acquire certified equipment. State-level procurement hubs in Ohio and Pennsylvania aggregate demand volumes that previously fragmented across individual city tenders. This concentration pressures regional distributors to demonstrate NFPA 1983 technical competency or exit the rescue equipment category entirely.
Rope Rescue Harness Market Segmentation
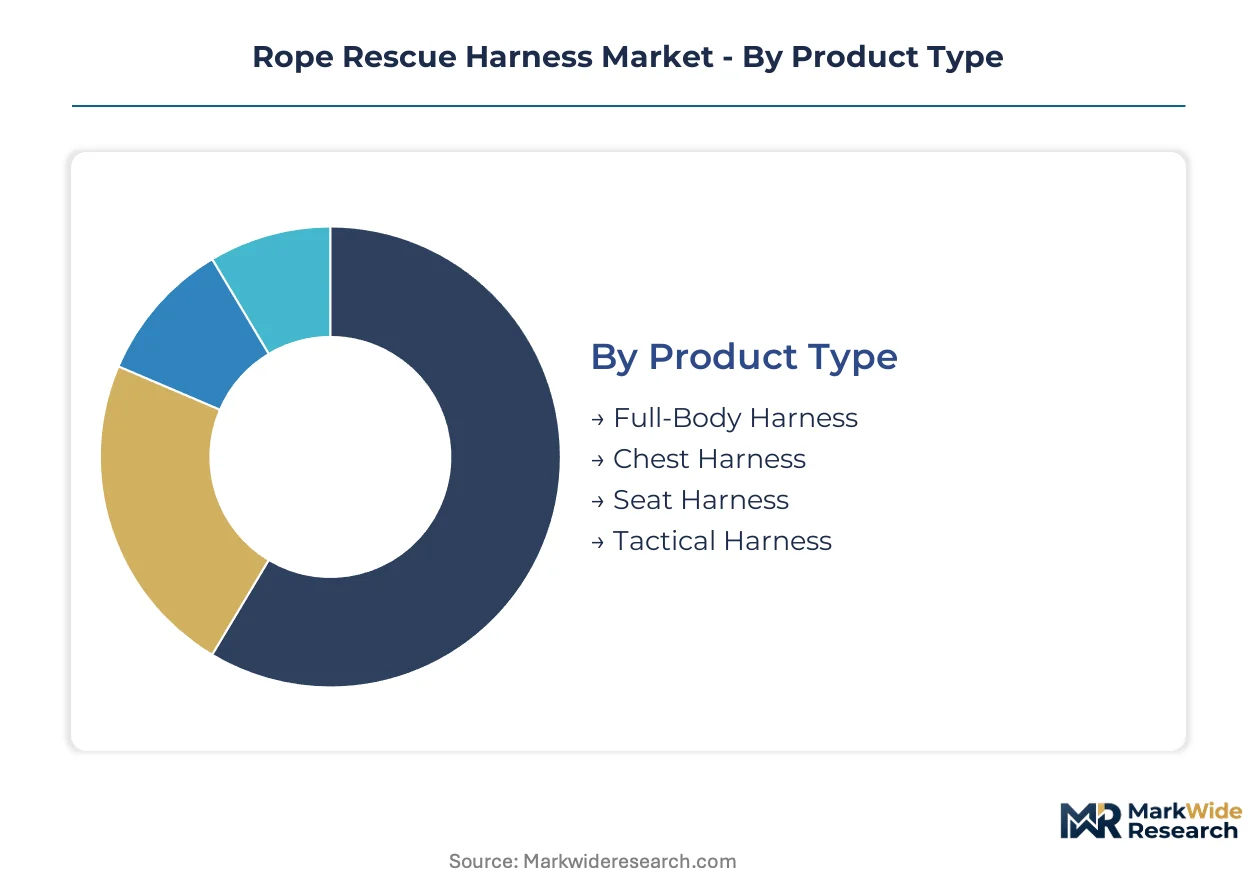
Segmentation in rope rescue harnesses reveals distinct equipment lifecycles across user categories. Fire departments replace harnesses on fixed retirement schedules driven by NFPA 1983 mandates, while military and industrial users stretch replacement intervals based on deployment intensity.
Product Type:
Replacement velocity varies dramatically by configuration complexity, with integrated full-body systems cycling fastest due to institutional mandates.
- Full-Body Harness:Constructed from high-tenacity nylon or polyester webbing with dorsal and sternal attachment points rated to 13-15 kN. Fire departments across the United States, Germany, and Australia drive procurement volume through dedicated federal funding for urban search-and-rescue teams.
- Tactical Harness:Modular designs optimized for military special-operations extractions feature quick-release buckles and MOLLE-compatible webbing. Special-operations units in NATO member states are expanding procurement as technical rescue capabilities integrate into counter-terror response protocols.
- Chest Harness:Upper-torso configurations supplement seat systems for confined-space entries.
- Seat Harness:Pelvic-focused designs dominate industrial rope access and tower work.
Full-Body Harness dominates installed base. Tactical Harness is where expansion concentrates.
End User:
Customer type determines pricing tolerance and certification stringency, creating tiered market access barriers.
- Firefighters:Municipal departments mandate NFPA 1983-certified configurations with mandatory retirement timelines. The 2023 edition tightened heat-resistance thresholds, compressing replacement cycles across North American fire services.
- Military:Special-operations units require harnesses meeting MIL-SPEC durability standards with reduced weight profiles. Procurement concentrates in United States, United Kingdom, and Australian defense channels prioritizing multi-mission adaptability.
- Industrial Workers:Rope access technicians and tower climbers drive demand for EN 358/EN 813-certified systems.
- Outdoor Enthusiasts:Recreational climbers and mountaineers represent price-sensitive demand with minimal institutional certification requirements.
Firefighters anchor procurement volume. Military represents the steepest expansion trajectory.
Material:
Raw material selection trades off tensile performance against thermal and chemical exposure profiles.
- Nylon:Dominates by volume due to superior energy absorption and fatigue resistance. Standard-grade nylon 6,6 webbing faces margin pressure from petrochemical input volatility tracking crude oil indices.
- Kevlar:Aramid-reinforced configurations command premium positioning for high-heat and cut-hazard environments. Electric-vehicle battery fire protocols are accelerating adoption among fire departments in California and Texas.
- Polyester:Offers superior UV resistance for outdoor and maritime applications.
- Cotton:Legacy material retained in specific training and ceremonial applications.
Nylon dominates installed base. Kevlar is where expansion concentrates.
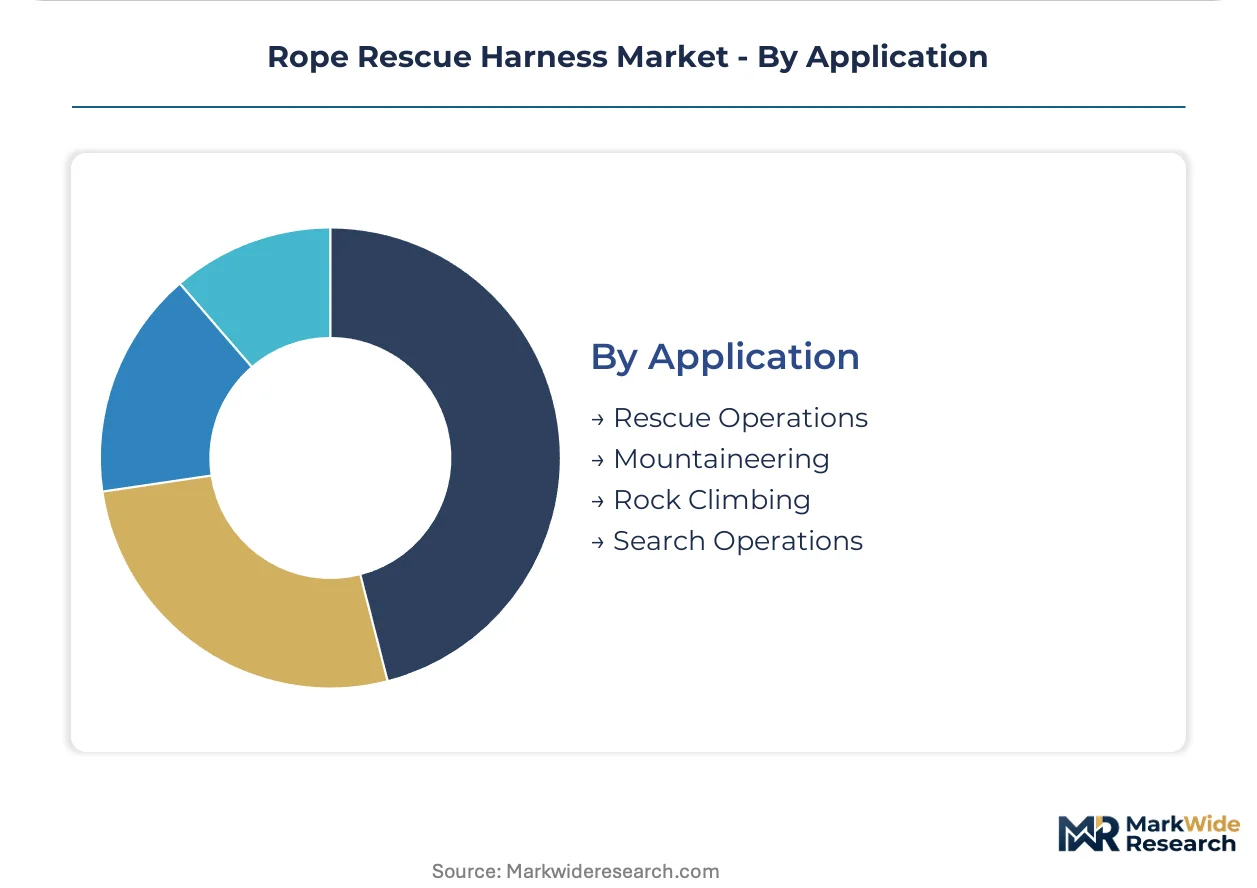
Application:
Use-case segmentation maps directly to regulatory jurisdiction and equipment specification intensity.
- Rescue Operations:Technical rescue scenarios demand full-body configurations with suspension trauma mitigation features. Urban search-and-rescue funding through FEMA USAR task forces institutionalizes procurement volume in the United States.
- Mountaineering:Alpine-derived designs prioritize weight reduction and packability. European manufacturers leverage CE marking pathways to access cross-border tenders under harmonized EN standards.
- Rock Climbing:Recreational and competitive climbing drives innovation in lightweight load-distribution webbing.
- Search Operations:Wilderness and disaster search teams require extended-wear comfort features.
Rescue Operations dominates installed base. Mountaineering is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of certified rope rescue harnesses concentrate in German, American, and Australian manufacturing clusters, while import dependence shapes procurement patterns in emerging technical rescue markets across Asia-Pacific and the Middle East.
United States
FEMA USAR task force funding and municipal fire department modernization drive institutional procurement volume. NFPA 1983 certification mandates from the National Fire Protection Association dictate product eligibility for federal procurement channels. California and Texas fire departments pilot heat-resistant harness configurations for electric vehicle battery fire extractions.
Germany
Industrial rope access contractors and alpine rescue services generate dual demand streams for EN 358/EN 813 certified systems. REACH Annex XVII restrictions on flame retardant chemistries force webbing coating reformulations across domestic supply chains. Bavaria-based manufacturers leverage CE marking pathways to access cross-border tenders under harmonized European standards.
Australia
Mining sector safety mandates and urban search-and-rescue team federal funding create dedicated procurement channels. AS/NZS 1891 compliance requirements from Standards Australia institutionalize replacement cycles across construction and resource extraction verticals. Queensland and Western Australia mining hubs accelerate adoption of rescue-rated fall protection systems.
United Kingdom
Specialist fire and rescue services and offshore energy operators sustain premium-tier demand. HSE regulations and BS EN standards convergence post-Brexit create parallel certification requirements for suppliers. Aberdeen and North Sea energy clusters drive specifications for marine-environment resistant harness configurations.
France
Sapeurs-pompiers technical rescue expansion and industrial confined-space protocols sustain institutional procurement. ANSM and CNIL oversight intersects with ECHA chemical compliance for notified body certification maintenance. Lyon and Marseille metropolitan fire services anchor regional demand concentration for full-body rescue systems.
Rope Rescue Harness Market Competitive Landscape
On the supply side, the industry is bifurcated between institutional certification specialists and alpine-heritage equipment crossover players. European and North American manufacturers dominate certified product lines, while Asian fabricators concentrate on component supply and private-label assembly. Three strategic archetypes define competitive positioning: NFPA-centric fire service suppliers, CE-marked industrial fall protection diversifiers, and mountaineering-brand rescue line extenders. Capacity expansion and certification portfolio diversification represent the dominant competitive moves as manufacturers respond to tightening heat-resistance standards.
Within the fire-service certification tier, CMC Rescue, Inc. and Petzl occupy positions as archetypal North American and European anchors respectively. SKYLOTEC exemplifies the industrial fall protection diversifier model with modular harness architectures. These three entities represent distinct geographic and regulatory specializations without overlapping core certification jurisdictions.
| Leading Market Players |
|---|
| CMC Rescue, Inc. |
| Petzl |
| Martin Castle Limited |
| Conterra Inc |
| International Safety Components Ltd. |
| SKYLOTEC |
| Arco Professional Safety Services Ltd. |
| KASK s.p.a |
| ROCK EXOTICA LLC |
| Others |
Value Network & Pricing Analysis
Bavaria's industrial textile cluster anchors European rope rescue harness manufacturing capacity, with certified weaving facilities concentrated around Munich and Nuremberg translating production scale into pricing leverage for EN-compliant product lines. This geographic concentration enables manufacturers to command premium positioning for heat-resistant configurations while standard-grade nylon harnesses face margin compression from volatile petrochemical feedstock costs.
Pricing Analysis
Next-generation Dyneema-Kevlar hybrid webbing commands substantial premiums over legacy nylon 6,6 configurations, while prior-generation polyester systems trade at discount tiers. Three-tier pricing structure across premium, standard, and economy levels separates NFPA 1983-certified fire-service systems from industrial fall-protection substitutes and recreational climbing harnesses. Cost compression in standard-grade tiers is intensifying because nylon resin prices track crude oil volatility, with municipal procurement departments exhibiting highest price sensitivity and military special-operations units showing lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for webbing hardware and buckle components. Manufacturing concentrates in Germany, the United States, and Australia, with high-tenacity nylon yarn drawing from petrochemical complexes in the Gulf Coast and Rotterdam. Single-source vulnerability persists for Kevlar aramid fiber from DuPont's Richmond, Virginia facility. Distribution runs through specialized rescue equipment distributors and consolidated municipal purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rope rescue harness market sits in cyclical recovery driven by NFPA 1983's 2023 edition mandating accelerated replacement timelines across North American fire departments.
For Market Incumbents: Build certification moats by securing parallel EN, NFPA, and AS/NZS testing streams before competitor capacity expands. Deepen distributor technical competency investments to defend against digital procurement platforms bypassing traditional channels. Anchor backward integration into high-tenacity webbing production to capture margin from synthetic fiber substitution trends. For New Entrants and Emerging Players: Australian mining safety mandates present the most penetrable geographic entry point, with AS/NZS 1891 compliance creating dedicated procurement channels outside saturated North American and European fire-service markets. Target industrial rope access contractors seeking rescue-rated fall protection as a white-space segment with lower certification barriers than municipal fire departments. Pursue direct digital tender participation to circumvent established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with wearable sensor integration capabilities and heat-resistant material science expertise. Long-term viability hinges on electric vehicle fire protocol adoption expanding addressable demand beyond traditional rescue applications. Watch for thermal runaway response training program rollouts as the inflection signal for premium-tier harness demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Diversification | Parallel EN, NFPA, and AS/NZS testing unlocks cross-border municipal tender access. |
| Heat-Resistant Material Science Investment | Dyneema-Kevlar hybrid development captures electric vehicle fire protocol specifications. |
| Digital Procurement Platform Integration | Direct municipal contracting bypasses distributor markups in Ohio and Pennsylvania hubs. |
| Wearable Sensor Technology Partnership | Load-sensing textile electronics integration enables real-time suspension trauma alerts. |
| Backward Integration into Synthetic Webbing | In-house high-tenacity nylon production insulates margins from petrochemical volatility. |
Research Methodology
A standing panel of fire service equipment procurement officers, NFPA-certified technical rescue instructors, industrial rope access contractors, and municipal safety directors provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from NFPA 1983 certification databases, EN standard harmonization documents, FEMA USAR funding appropriations records, and customs trade flow data. Bottom-up demand modeling from individual fire department replacement schedules was triangulated against top-down market sizing from manufacturer shipment disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with sensitivity testing around petrochemical input cost trajectories and certification timeline compressions. Segmentation dimensions modeled included product configuration complexity, end-user institutional type, material science generation, and regional regulatory jurisdiction. CAGRs were derived from replacement cycle velocity analysis and funding allocation patterns. Electric vehicle fire protocol adoption curves and wearable sensor integration rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, municipal budget cycles, or federal disaster preparedness appropriations would shift the trajectory. Forecasts reflect documented assumptions about standard retirement timelines and harmonization progress across certification regimes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Incident Response Services Market