
 Global Security Solutions Market | 2026-2036
Global Security Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Security Solutions Market Foresight
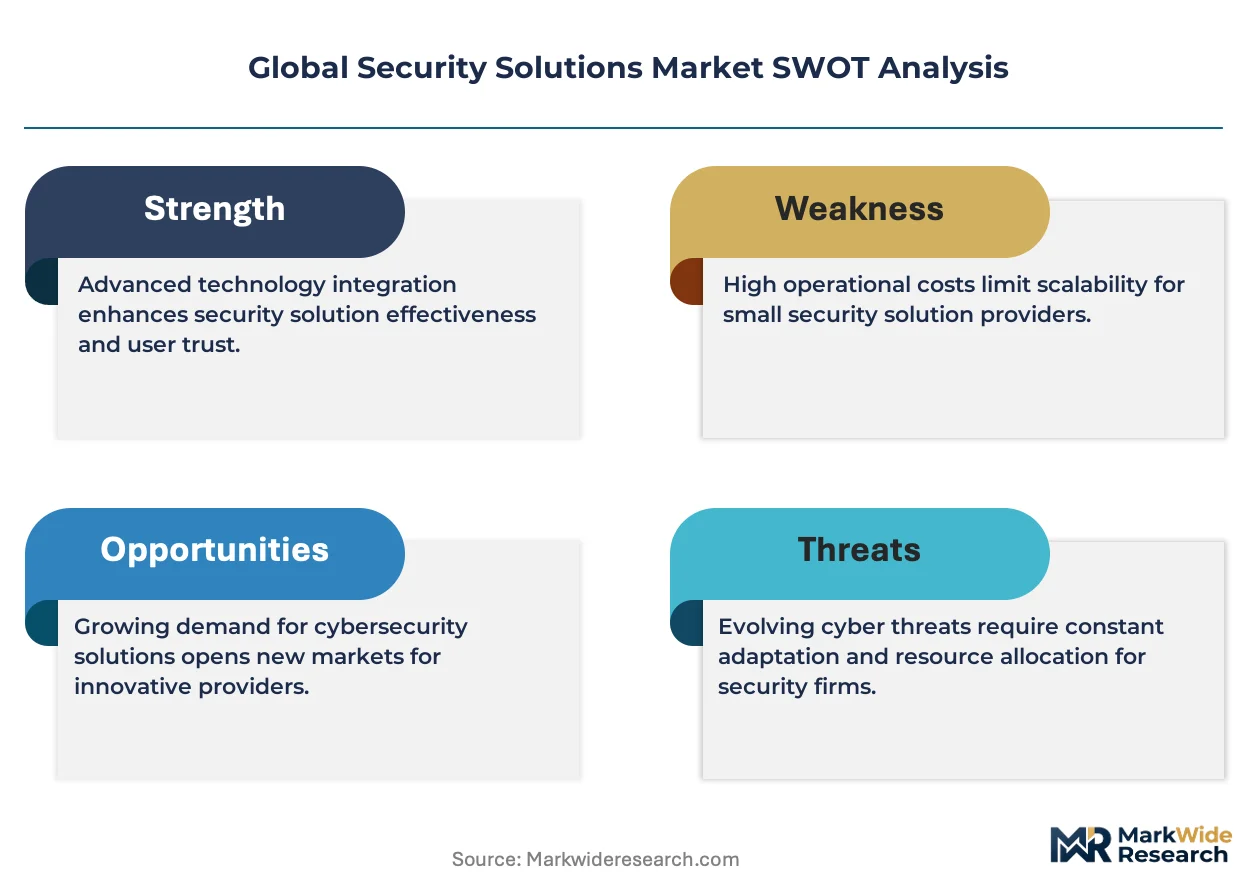
A widening capital-intensity gap between integrated platform providers and point-product vendors is redrawing competitive boundaries in security solutions. Honeywell International Inc. leverages its building-automation heritage to bundle HVAC, fire safety, and access control into unified command centers. Robert Bosch GmbH anchors its position through in-house sensor manufacturing and European manufacturing scale. Hangzhou Hikvision Digital Technology Co., Ltd. dominates video-analytics hardware through vertical control over chip design and camera assembly.
Security solutions encompass integrated systems for threat detection, access management, and emergency response, typically combining edge sensors, network infrastructure, and centralized software platforms operating on sub-100-millisecond latency thresholds for real-time alerting. Their primary commercial purpose is to reduce operational risk, protect physical assets, and ensure regulatory compliance across facilities ranging from single-tenant offices to multi-site critical infrastructure. Video analytics and cloud-based technology segments are capturing disproportionate R&D investment as enterprises shift from on-premise storage to hybrid architectures, while biometric authentication is maturing fastest in high-assurance government installations where fingerprint and iris modalities already dominate. The access control system product category holds the deepest margin pools due to recurring software-license revenue and integration complexity that locks in multi-year enterprise contracts.
The EU AI Act, GDPR, and the US FAA's drone-security directives are tightening compliance requirements for automated surveillance and perimeter-monitoring systems, forcing vendors to embed privacy-by-design features and audit trails directly into product firmware. India's BIS certification mandates and China's GB standards for video-security equipment further fragment market-access pathways, requiring region-specific hardware variants. Stakeholders must monitor how divergent national AI-governance frameworks reshape cross-border procurement eligibility and data-sovereignty obligations for cloud-hosted security platforms.
Market Dynamics
Cloud-native access control architectures are compressing deployment timelines from months to weeks, forcing legacy on-premise vendors to re-engineer software stacks or surrender enterprise accounts to platform-native competitors.
Growth Catalysts
- EU AI Act algorithmic surveillance mandates:Automated perimeter-monitoring systems across German critical infrastructure must embed audit trails and privacy-by-design firmware, creating replacement demand for compliant hardware.
- Smart city infrastructure deployment in Singapore:Integrated command centers bundling video analytics, emergency response, and traffic management are standardizing multi-sensor procurement packages for municipal buyers.
- Biometric authentication maturation:Fingerprint and iris modalities in high-assurance government installations are displacing card-based access, locking in multi-year software-license contracts with embedded hardware refresh cycles.
Market Restraints
- Semiconductor supply concentration:Video-analytics chip design and fabrication capacity clusters in East Asian foundries, exposing European and North American integrators to lead-time volatility and export-control friction.
- GDPR cross-border data-transfer restrictions:Cloud-hosted security platforms storing biometric templates face fragmented compliance obligations that increase legal review costs and delay procurement sign-offs.
- Legacy on-premise sunk investment:Enterprises with depreciated server infrastructure resist hybrid-architecture migration despite superior total cost of ownership, extending replacement cycles.
Strategic Opportunities
- India BIS certification pathway expansion:Domestic manufacturing incentives and mandatory certification for video-security equipment create localized production opportunities for foreign vendors willing to establish regional assembly.
- Drone-perimeter integration:Convergence of aerial surveillance platforms with ground-based sensor networks opens new contract structures for critical infrastructure operators seeking layered threat detection.
- Japan METI building-efficiency standards:Integration of HVAC, fire safety, and access control into unified energy-management systems rewards vendors with cross-functional automation expertise.
Industry Challenges
- Cyber-physical security skill convergence:Shortage of engineers proficient in both OT network segmentation and physical sensor calibration delays enterprise deployment timelines and inflates implementation costs.
- Multi-jurisdiction certification sequencing:Vendors must navigate India's BIS, China's GB standards, and EU CE marking in parallel, fragmenting product-variant strategies and compressing margin on hardware.
- Sub-100-millisecond latency engineering:Real-time alerting requirements for edge-to-cloud video analytics demand specialized network architecture expertise that sits outside traditional security integrator capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Security Solutions Market |
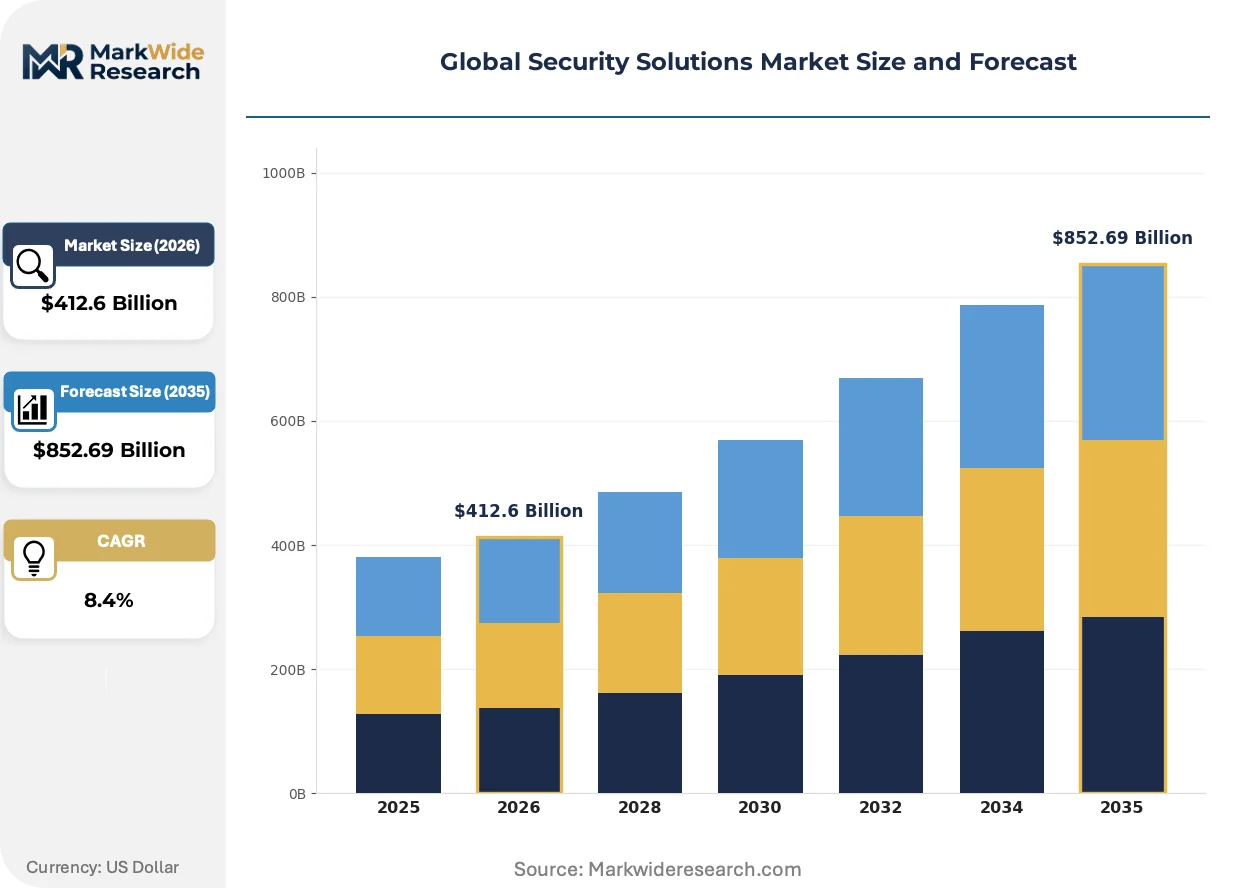
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $852.69 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV, Access Control System, Intrusion Detection, Fire Alarm Technology: Biometric, RFID, Video Analytics, Cloud-Based End User: Commercial, Government, Residential, Industrial Installation Type: Wired, Wireless, Hybrid, Integrated |
| Companies Covered | Honeywell International Inc., Johnson Controls, Robert Bosch GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., ADT Security Services, Axis Communications, Assa Abloy, IBM Corporation, Dahua Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Security Solutions Market Shifts & Advancements
Edge-computing video analytics are redistributing processing load from centralized servers to camera-embedded chips, altering hardware specifications and procurement evaluation criteria across enterprise and government segments.
GPU-accelerated inference engines embedded in surveillance cameras now perform facial recognition, object classification, and anomaly detection without round-trip cloud latency. Critical infrastructure operators in the United States and United Arab Emirates are specifying these capabilities in RFPs as baseline requirements. This capability is displacing server-room video-management software from the architectural center of large-scale deployments, compressing infrastructure spend toward edge hardware.
The EU AI Act's risk-classification framework for biometric identification systems imposes conformity-assessment obligations that extend product-development timelines by twelve to eighteen months for vendors without established European notified-body relationships. Security integrators serving French and German government accounts are pre-qualifying suppliers based on existing CE marking depth and audit-trail documentation maturity. Video-analytics vendors with immature compliance functions are retreating from public-sector tenders toward lower-regulation commercial verticals.
Enterprise buyers are consolidating vendor relationships around platform providers offering unified command centers spanning access control, video, and intrusion detection. Facilities managers in Singapore and Germany increasingly reject point-product vendors lacking API depth for building-automation integration. This concentration rewards Honeywell and Bosch for their pre-existing HVAC and fire-safety installed bases, while squeezing standalone access-control specialists into mid-market accounts with lighter integration demands.
Global Security Solutions Market Segmentation
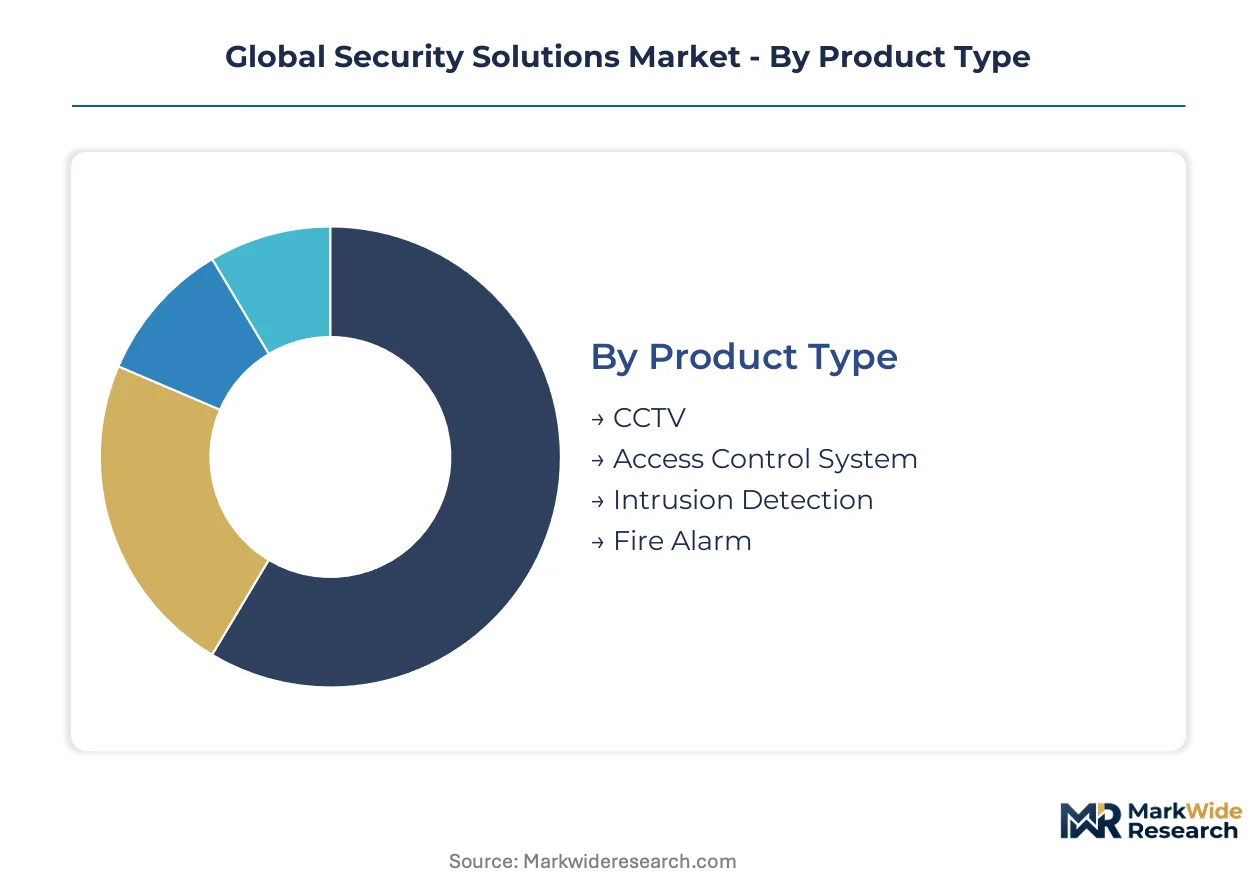
Security solutions procurement channels bifurcate sharply between enterprise integrators demanding unified platforms and mid-market buyers accepting point-product installations. Segment boundaries determine margin structure, contract duration, and vendor competitive positioning across deployment scales.
Product Type:
Channel mix varies by hardware complexity: CCTV and access control flow through certified integrators with multi-year service contracts, while intrusion detection and fire alarm segments split between professional installation and direct-to-facilities procurement.
- CCTV:Camera networks with edge-processing capabilities now embed GPU-accelerated inference engines for real-time facial recognition and anomaly detection. Demand concentrates in UAE and US critical infrastructure where sub-100-millisecond latency specifications appear in RFPs as baseline requirements.
- Access Control System:Biometric and card-based entry management systems generate recurring software-license revenue through multi-year enterprise contracts. German and Japanese facilities managers prioritize API depth for building-automation integration, locking in platform-native vendors.
- Intrusion Detection:Perimeter sensors and motion-detection networks serve commercial and residential channels with shorter replacement cycles.
- Fire Alarm:Code-mandated detection systems flow through construction contractors and facilities-maintenance channels with regulatory-driven refresh schedules.
CCTV dominates installed base. Access Control System is where expansion concentrates.
Technology:
Cost tiers separate enterprise-grade biometric and video analytics from mid-market RFID and cloud-based alternatives, with procurement authority shifting from IT security to facilities management as price points decline.
- Biometric:Fingerprint and iris recognition modalities operate on specialized sensor hardware with template encryption for high-assurance environments. Government installations in France and Germany drive specification under EU AI Act conformity-assessment frameworks.
- Video Analytics:Edge-computing inference engines redistribute processing from centralized servers to camera-embedded chips. US critical infrastructure operators specify these capabilities as mandatory, compressing infrastructure spend toward edge hardware.
- RFID:Card and tag-based identification systems serve cost-sensitive commercial and residential segments through standard hardware procurement.
- Cloud-Based:Remote-hosted management platforms face GDPR cross-border data-transfer restrictions that increase legal review costs for biometric template storage.
Video Analytics is gaining share fastest. RFID retains volume leadership in unit shipments.
End User:
Application context determines integration complexity: government and industrial buyers demand unified command centers, while commercial and residential segments accept standalone products with lighter interoperability requirements.
- Commercial:Office complexes, retail chains, and hospitality facilities procure multi-sensor packages through facilities-management departments. Singapore's smart city deployments standardize integrated command centers bundling video, access, and emergency response.
- Government:High-assurance installations require biometric authentication with embedded audit trails and privacy-by-design firmware. EU AI Act mandates drive replacement demand for compliant hardware across German critical infrastructure.
- Residential:Single-family and multi-tenant dwellings purchase through retail channels and smart-home ecosystems with DIY installation options.
- Industrial:Manufacturing and logistics facilities prioritize OT network segmentation alongside physical sensor calibration.
Government commands premium pricing. Commercial represents the steepest expansion trajectory.
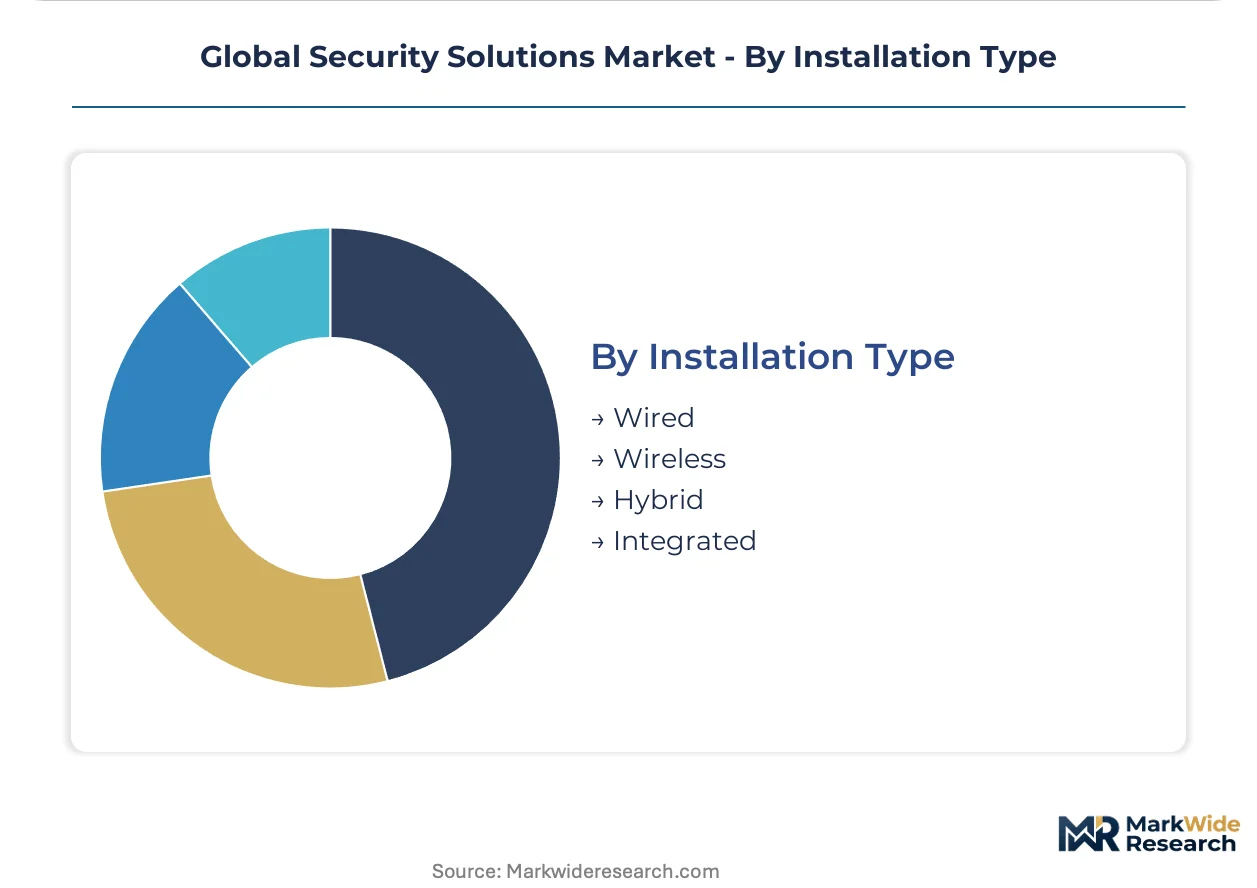
Installation Type:
Maturity curves diverge: wired infrastructure retains dominance in legacy facilities, while wireless and hybrid architectures compress deployment timelines from months to weeks for cloud-native access control.
- Wired:Ethernet and coaxial cabling infrastructure supports high-bandwidth video streaming in facilities with established server rooms. Depreciated on-premise investments extend replacement cycles despite superior total cost of ownership for hybrid alternatives.
- Wireless:Battery-powered sensors and Wi-Fi-connected cameras reduce installation labor and enable rapid retrofit of existing structures. Cloud-native vendors leverage this architecture to compress enterprise deployment timelines.
- Hybrid:Mixed wired-wireless configurations balance bandwidth requirements with deployment flexibility for multi-site operators.
- Integrated:Unified platforms spanning HVAC, fire safety, and access control reward vendors with cross-functional automation expertise under Japan METI building-efficiency standards.
Wired systems anchor legacy installed base. Wireless architectures show the steepest adoption climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for security hardware reveal concentrated manufacturing in East Asian foundries against distributed deployment demand across Western critical infrastructure. The United States and Germany remain net importers of video-analytics chipsets while exporting integrated platform software. Singapore and the UAE function as re-export hubs for regional smart city procurement.
United States
Critical infrastructure operators in Texas and California specify GPU-accelerated edge inference engines in federal procurement RFPs. FAA drone-security directives mandate perimeter-monitoring compliance for airports and energy facilities. Houston's petrochemical corridor drives demand for unified command centers bundling access control with OT network segmentation.
Germany
Industrial facilities in Bavaria and North Rhine-Westphalia prioritize building-automation integration under EU AI Act algorithmic surveillance mandates. CE marking conformity assessments extend product qualification timelines for biometric identification systems. Stuttgart's automotive manufacturing cluster locks in multi-year contracts with vendors offering HVAC-access-fire unified platforms.
Singapore
Smart nation infrastructure deployments standardize multi-sensor procurement packages combining video analytics, emergency response, and traffic management. The country's national cybersecurity agency imposes data-sovereignty requirements on cloud-hosted security platforms. One-North and Jurong Innovation District serve as testbeds for integrated command center rollouts.
Japan
METI building-efficiency standards reward cross-functional automation expertise in commercial real estate across Tokyo and Osaka. Facilities managers demand API depth for HVAC-fire-access integration in high-rise developments. Kansai's manufacturing belt generates concentrated demand for biometric authentication in high-assurance government installations.
India
BIS certification mandates for video-security equipment create localized production incentives in Maharashtra and Karnataka. Domestic manufacturing incentives under the PLI scheme attract foreign vendors establishing regional assembly. Mumbai's financial district and Bangalore's technology corridor drive enterprise procurement of cloud-native access control architectures.
Global Security Solutions Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing pre-installed building-automation bases. The vendor base stratifies across three tiers: integrated platform providers commanding enterprise accounts, point-product specialists serving mid-market buyers, and component manufacturers supplying upstream sensor hardware. Strategic moves center on API ecosystem expansion and regional certification pre-qualification rather than price competition.
Among diversified industrial conglomerates, Honeywell International Inc. and Robert Bosch GmbH occupy positions reflecting building-automation heritage. Hangzhou Hikvision Digital Technology Co., Ltd. exemplifies the vertical manufacturing archetype through captive control over chip design and camera assembly. These three anchors represent distinct competitive vectors: unified platform bundling, European manufacturing scale, and upstream hardware integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls |
| Robert Bosch GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| ADT Security Services |
| Axis Communications |
| Assa Abloy |
| IBM Corporation |
| Dahua Technology |
| Others |
Supply & Pricing Matrix
EU AI Act conformity-assessment obligations for biometric identification systems simultaneously gate supplier qualification and stratify price tiers, forcing vendors to absorb twelve-to-eighteen-month compliance timelines that premium-tier buyers reward with multi-year contract premiums while economy-tier procurement excludes non-compliant hardware entirely.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the security solutions market. Premium tiers command contract premiums based on CE marking depth and embedded audit-trail firmware under EU AI Act mandates, while price differentiation stems from certification grade and after-sales service bundling. Cost compression in standard tiers intensifies because cloud-native vendors compress deployment timelines, eroding legacy on-premise margins. Government facilities managers show least price sensitivity due to regulatory lock-in, whereas mid-market commercial buyers exhibit highest elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for video-analytics chipsets sourced from Taiwanese and South Korean foundries. Manufacturing concentration clusters in China, Taiwan, and South Korea for GPU-accelerated inference engines and specialized sensor hardware. Raw material dependencies span silicon wafers, rare-earth magnet components, and high-grade optical glass. Single-source vulnerability from East Asian foundry concentration exposes European and North American integrators to lead-time volatility. Distribution runs through certified security integrators with multi-year service contracts for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as procurement authority shifts from IT security to facilities management, creating niche openings for vendors with building-automation API depth that platform incumbents underserve.
For Market Incumbents: Fortify unified command center positioning by deepening HVAC-access-fire integration under Japan METI standards, while accelerating regional certification pre-qualification across India's BIS and China's GB frameworks to preempt emerging entrant capture of smart city tenders.
For New Entrants and Emerging Players: Differentiate on drone-perimeter integration for critical infrastructure operators in Texas and California, where FAA directives create compliance-driven replacement cycles that favor agile specialists over legacy platform vendors.
For Investors and Strategic Acquirers: EU AI Act risk-classification implementation reshapes the acquisition landscape toward biometric-identification vendors with mature notified-body relationships and existing CE marking depth. Five-to-ten-year viability favors targets with embedded firmware audit-trail capabilities. Watch for pre-qualification threshold tightening in French and German government RFPs as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Certification Pre-Qualification | EU AI Act conformity assessments lock out non-compliant vendors from German critical infrastructure tenders. |
| API Ecosystem Expansion | Facilities managers in Singapore reject point-product vendors lacking building-automation integration depth. |
| Edge Computing Hardware Investment | US critical infrastructure RFPs specify GPU-accelerated inference engines as baseline requirements. |
| Drone-Perimeter Integration Development | FAA directives mandate aerial-ground sensor convergence for airport and energy facility operators. |
| Backward Integration into Sensor Manufacturing | Captive chip design control insulates against East Asian foundry lead-time volatility. |
Research Methodology
Cross-validation between primary interviews with security integrators, facilities managers, and government procurement officers and secondary validation through SEC filings, customs trade data, EU tender databases, and FAA directive documentation anchors the qualitative findings. Bottom-up triangulation from product-level shipment data and top-down reconciliation against national smart city budget disclosures ensure segmentation integrity.
Sensitivity analysis on input variables including semiconductor availability, regulatory timeline shifts, and cloud-migration velocity informs the analytical framework across the projection horizon. Segmentation dimensions span product type, technology tier, end-user vertical, and installation architecture. CAGRs derive from installed base evolution, replacement cycle compression, and penetration rate modeling for biometric and video-analytics segments.
The analysis sits within stated boundaries; outcomes outside sustained East Asian foundry output, stable EU AI Act implementation timelines, or continued cloud-hybrid architecture migration would require recalibration. Forecasts reflect documented assumptions regarding procurement authority shifts and certification sequencing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Italy Ransomware Protection Market