
 Disaster Preparedness Systems Market | 2026-2036
Disaster Preparedness Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Disaster Preparedness Systems Market Intelligence
Defense contractors and municipal governments are unwinding legacy siloed procurement as integrated platform buyers gain share in disaster preparedness systems. Honeywell International Inc. leverages its building automation heritage to anchor command-and-control installations across federal facilities. Motorola Solutions, Inc. dominates narrowband and broadband public-safety communications with hardened infrastructure. Siemens AG extends its digital twin portfolio into predictive flood and wildfire modeling for regional authorities.
Disaster preparedness systems encompass hardware, software, and consumable assets engineered to detect threats, coordinate response, and sustain populations through catastrophic events, typically integrating sensor networks with sub-second latency alerting and redundant power architectures. Communication Devices and Monitoring Systems command the largest revenue pools where interoperability mandates and real-time situational awareness justify premium outlays. IoT Solutions and Data Analytics represent the fastest-expanding technology layer as edge computing and AI-driven risk scoring displace manual threshold monitoring. Mobile Apps penetration within Government Agencies and Healthcare Facilities is deepening as last-mile alerting replaces broadcast-only sirens.
FEMA, the EPA, and NFPA standards collectively shape United States product certification, procurement eligibility, and interoperability testing for equipment deployed in federally funded facilities. Japan's Fire and Disaster Management Agency and METI enforce building-hardening codes and industrial business-continuity protocols that dictate system redundancy levels. Stakeholders must weigh captive development against modular vendor ecosystems as regulatory fragmentation across national frameworks complicates platform standardization.
Market Dynamics
FEMA certification tightening and NFPA equipment specification upgrades are forcing vendors to re-engineer hardware architectures for interoperability compliance, compressing product development cycles while elevating R&D thresholds for market entry.
Growth Catalysts
- Climate vulnerability assessments:Infrastructure investment mandates in Japan, Germany, and the United States are accelerating procurement of integrated sensor-to-alert platforms for flood and wildfire zones.
- NFPA 1600 standardization:Emergency management accreditation requirements are consolidating fragmented municipal purchasing into unified command-and-control system deployments.
- Edge computing:AI-driven risk scoring at the network perimeter is displacing manual threshold monitoring in healthcare facilities and government agencies.
Market Restraints
- Semiconductor supply concentration:Hardened communication chip fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical disruption.
- Lithium-ion battery cost volatility:Redundant power architecture requirements for sub-second alerting systems amplify input price sensitivity.
- Spectrum allocation friction:FCC narrowband-broadband transition timelines create procurement uncertainty for public-safety agencies.
Strategic Opportunities
- India coastal resilience:Cyclone early-warning system gaps present white space for integrated platform vendors as the National Disaster Management Authority expands funding.
- Digital twin convergence:Predictive flood modeling fused with real-time sensor feeds is opening new service revenue streams for regional authorities.
- Mobile app last-mile alerting:Smartphone penetration in Southeast Asian urban corridors is displacing broadcast-only siren infrastructure.
Industry Challenges
- Cyber-physical systems engineering talent:Scarcity of specialists capable of integrating sensor networks with redundant power architectures is elongating deployment timelines.
- FEMA P-361 certification complexity:Safe room and storm shelter equipment testing protocols are creating multi-year approval backlogs for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disaster Preparedness Systems Market |
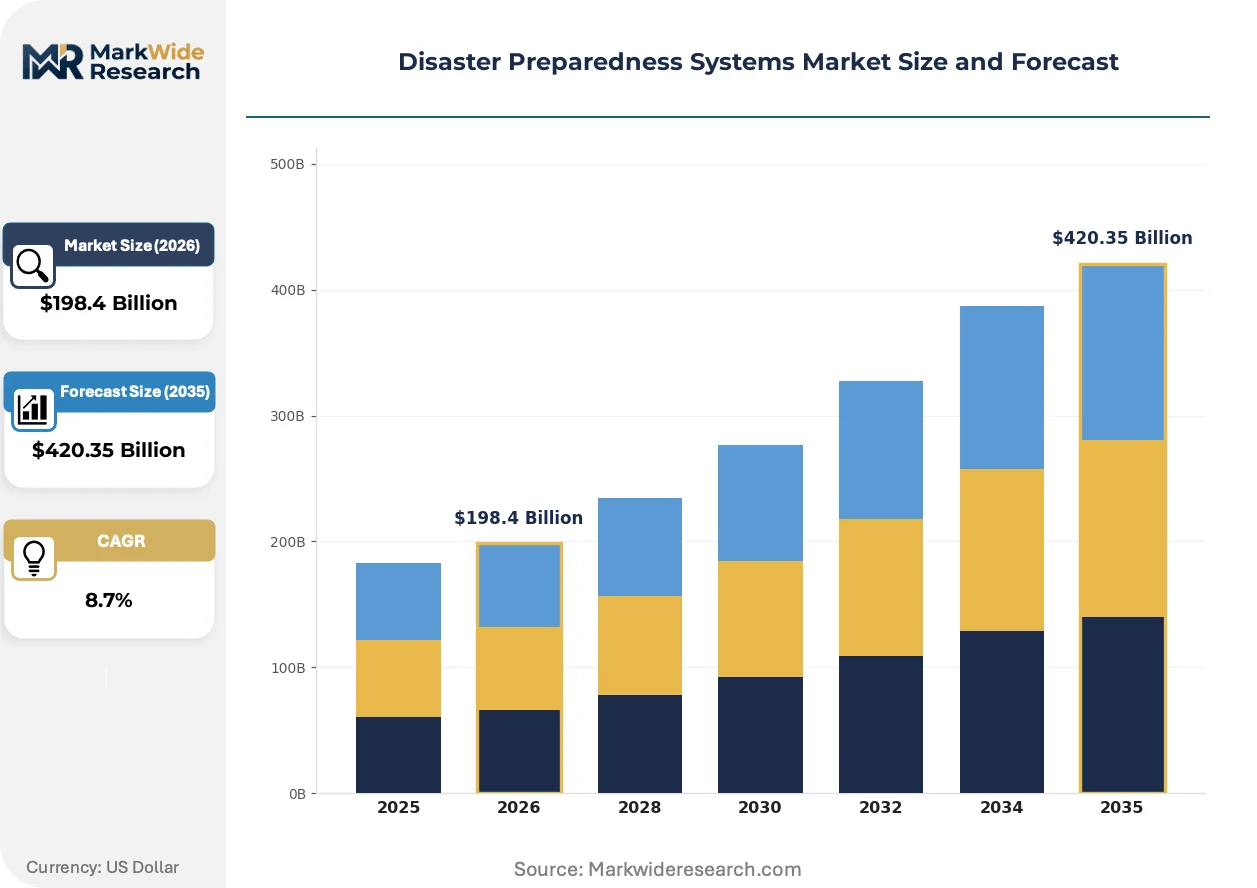
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $420.35 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Kits, Communication Devices, First Aid Supplies, Monitoring Systems End User: Government Agencies, Educational Institutions, Healthcare Facilities, NGOs Technology: Mobile Apps, IoT Solutions, Satellite Communication, Data Analytics Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Honeywell International Inc., Motorola Solutions, Inc., Everbridge, Inc., Lockheed Martin, Siemens AG, Hexagon AB, IBM Corporation, NEC Corporation, Esri, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disaster Preparedness Systems Market Strategic Shifts & Innovations
Sensor hardware and edge computing architectures are compressing form factors while elevating processing capability, enabling deployment in bandwidth-constrained environments previously unreachable by centralized systems.
Multi-spectral detection arrays for wildfire and chemical threat identification are miniaturizing from vehicle-mounted units to wearable and drone-integrated formats. Wildland firefighting agencies in California and Australia are piloting these reduced-weight configurations during extended suppression campaigns. This compression is collapsing the price-performance barrier for municipal departments previously excluded from real-time environmental monitoring.
EPA emergency response equipment decontamination standards are mandating modular component architectures that accelerate field servicing and reduce downtime. Manufacturers serving hazmat response teams must now design for rapid swap-out of contaminated subsystems. The industrial consequence is a shift from integrated monolithic units toward standardized interface protocols across federal procurement.
Subscription-based platform licensing is displacing perpetual software ownership among county-level emergency management departments. SaaS alerting and training modules reduce upfront capital requirements while embedding vendors in recurring revenue relationships. This transition is most visible in Texas and Florida counties rebuilding after successive hurricane seasons.
Disaster Preparedness Systems Market Segmentation
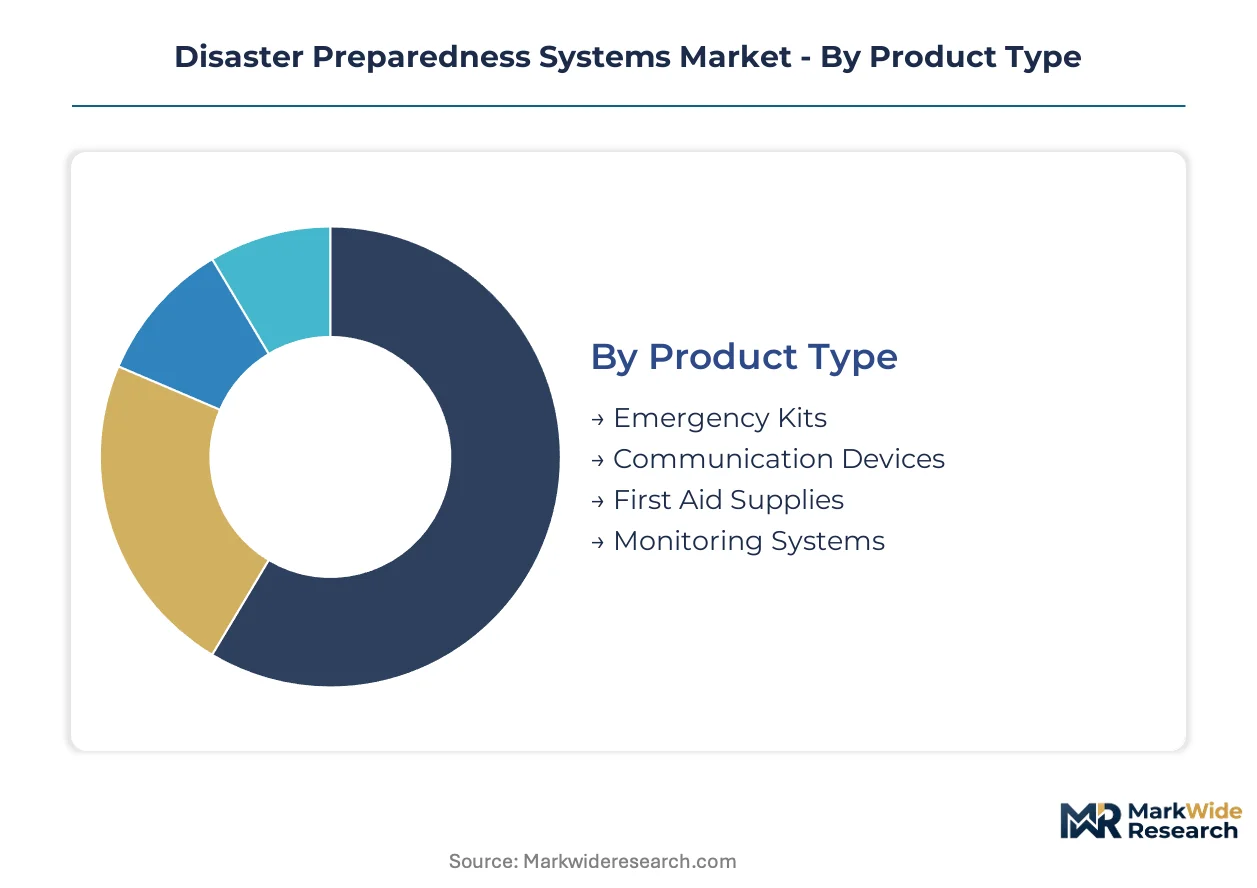
Segmentation in disaster preparedness systems reveals where procurement budgets concentrate and how regulatory mandates reshape technology adoption. Buyers prioritize interoperability-certified equipment over point solutions, compressing vendor selection criteria.
Product Type:
Margin pools concentrate in hardened infrastructure requiring FEMA certification and redundant power architectures.
- Communication Devices:Narrowband and broadband radio systems with hardened enclosures and sub-second latency alerting command premium pricing. Municipal fire departments in Texas and Florida counties rebuilding after successive hurricane seasons drive replacement cycles. NFPA 1600 standardization consolidates fragmented purchasing into unified deployments.
- Monitoring Systems:Multi-spectral detection arrays for wildfire and chemical threat identification integrate edge computing for bandwidth-constrained environments. California and Australia wildland firefighting agencies pilot miniaturized wearable and drone-integrated formats during extended suppression campaigns.
- Emergency Kits:Modular component architectures meeting EPA decontamination standards accelerate field servicing for hazmat response teams.
- First Aid Supplies:Consumable inventory rotation programs align with hospital accreditation requirements in Japan and Germany.
The dominant share belongs to Communication Devices, while Monitoring Systems is closing the gap fastest.
End User:
Volume concentration tracks federal funding flows and climate vulnerability assessment mandates.
- Government Agencies:FEMA, the EPA, and NFPA standards collectively shape product certification, procurement eligibility, and interoperability testing for equipment deployed in federally funded facilities. County-level emergency management departments in Texas and Florida adopt subscription-based platform licensing to reduce upfront capital requirements.
- Healthcare Facilities:Edge computing and AI-driven risk scoring displace manual threshold monitoring in patient safety systems. HIPAA compliance requirements dictate redundant alerting architectures.
- Educational Institutions:Campus emergency notification systems integrate mobile app last-mile alerting as smartphone penetration displaces broadcast-only sirens.
- NGOs:Humanitarian logistics operations prioritize satellite communication for infrastructure-destroyed environments.
Government Agencies capture the largest procurement volume, though Healthcare Facilities are expanding most quickly.
Technology:
Application intensity varies by bandwidth availability and processing latency requirements.
- IoT Solutions:Sensor networks with edge computing architectures compress form factors while elevating processing capability for deployment in previously unreachable environments. Japan's METI-enforced building-hardening codes dictate system redundancy levels.
- Data Analytics:Predictive flood and wildfire modeling fused with real-time sensor feeds opens service revenue streams for regional authorities. Germany's climate vulnerability assessments accelerate infrastructure investment.
- Mobile Apps:Last-mile alerting penetrates Southeast Asian urban corridors as smartphone adoption displaces legacy siren infrastructure.
- Satellite Communication:Redundant backhaul for public-safety agencies faces FCC spectrum allocation timeline uncertainty.
IoT Solutions holds established deployment share, while Data Analytics climbs the fastest.
Distribution Channel:
Customer type determines channel economics, with institutional buyers favoring direct relationships.
- Direct Sales:Federal and state procurement offices mandate vendor certification and interoperability testing before contract award. Siemens AG and Motorola Solutions anchor command-and-control installations through dedicated account teams.
- Distributors:Regional stocking locations reduce lead times for municipal departments with emergency replacement requirements.
- Online Retail:Individual and small-business buyers access consumer-grade emergency kits through e-commerce platforms.
- Resellers:Systems integrators bundle hardware with installation and training services for county-level deployments.
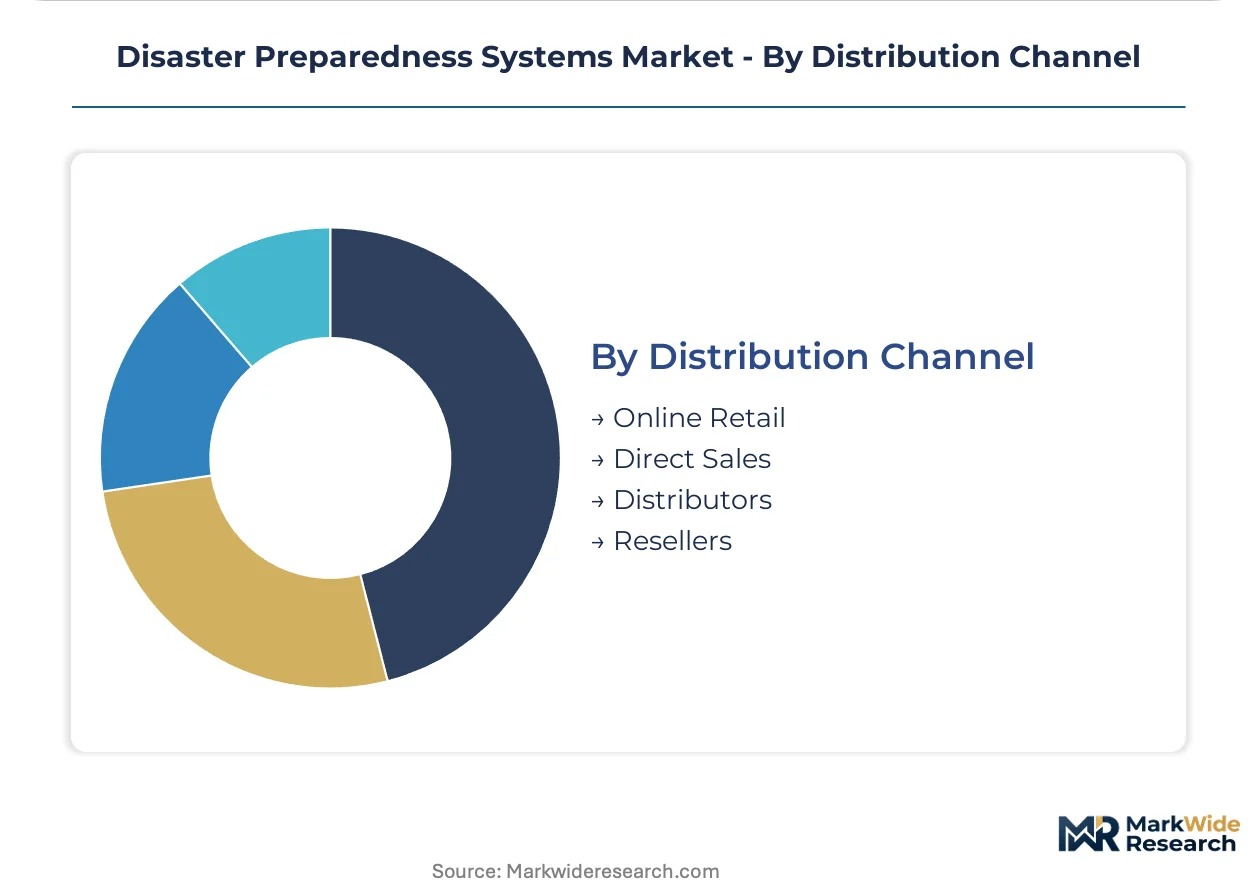
Direct Sales commands institutional procurement, though Distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Coast's submarine cable landing stations and the Gulf Coast's petrochemical pipeline networks anchor national disaster resilience investment. These infrastructure backbones concentrate procurement of hardened communication and monitoring systems where climate vulnerability intersects with critical asset density.
United States
FEMA certification tightening and NFPA 1600 standardization are consolidating fragmented municipal purchasing into unified command-and-control deployments. The EPA and FCC collectively shape equipment specifications for federally funded facilities through interoperability testing mandates. Texas and Florida counties rebuilding after successive hurricane seasons drive replacement cycles for subscription-based alerting platforms.
Japan
METI-enforced building-hardening codes and the Fire and Disaster Management Agency's industrial business-continuity protocols dictate system redundancy levels. Climate vulnerability assessments for flood and seismic zones accelerate procurement of integrated sensor-to-alert platforms. Tokyo and Osaka metropolitan authorities anchor regional deployment of edge-computing architectures for bandwidth-constrained environments.
Germany
Climate vulnerability assessments for Rhine floodplains and Alpine wildfire zones drive infrastructure investment in predictive modeling systems. Federal civil protection frameworks mandate interoperability standards for cross-state emergency coordination. Bavaria and Baden-Württemberg industrial clusters concentrate digital twin deployments for regional flood authorities.
India
Cyclone early-warning system gaps along the eastern coastline present procurement opportunities as the National Disaster Management Authority expands funding. BIS certification requirements and coastal resilience mandates shape equipment specifications for integrated platform vendors. Tamil Nadu and Andhra Pradesh state authorities pilot mobile app last-mile alerting as smartphone penetration displaces legacy siren infrastructure.
Australia
Extended wildfire suppression campaigns in Victoria and New South Wales drive miniaturization of multi-spectral detection arrays into wearable and drone-integrated formats. Federal emergency management frameworks mandate interoperability between state-level response agencies. Sydney and Melbourne metropolitan procurement offices anchor subscription-based platform licensing for county-level emergency management departments.
Disaster Preparedness Systems Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized public-safety technology providers. The vendor base spans three tiers: defense contractors with hardened infrastructure heritage, building automation specialists extending into command-and-control, and pure-play communications hardware manufacturers. Strategic moves center on portfolio diversification into predictive analytics and geographic expansion through modular vendor ecosystems.
Among diversified technology conglomerates, Honeywell International Inc., Siemens AG, and Motorola Solutions, Inc. exemplify the tier of players leveraging industrial automation heritage to anchor federal and municipal installations. These entities occupy positions where building management system expertise translates into integrated platform credibility for facilities requiring FEMA-certified redundant architectures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Everbridge, Inc. |
| Lockheed Martin |
| Siemens AG |
| Hexagon AB |
| IBM Corporation |
| NEC Corporation |
| Esri, Inc. |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery chemistry substitution for lead-acid backup systems is redrawing procurement geography toward South Korean and Chinese cell manufacturers while compressing margin structures for legacy power architecture vendors. This input shift simultaneously elevates working capital requirements for tier-one system integrators and exposes municipal buyers to commodity-linked price volatility in redundant alerting infrastructure.
Pricing Analysis
Volume-discount tiering structures separate FEMA P-361 certified safe room installations from uncertified municipal alert systems, with interoperability testing costs embedded in premium quotations. Certification grade and customization level drive price differentiation, with hardened broadband radio systems commanding substantial premiums over narrowband alternatives. Cost compression in economy-tier emergency kits is intensifying because EPA modular decontamination standards are forcing component standardization. County-level government agencies exhibit highest price sensitivity due to subscription-based SaaS licensing adoption, while federal facilities demonstrate lowest sensitivity given mandate-driven procurement timelines.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes are elevating landed costs for Taiwan- and South Korea-fabricated hardened communication chipsets. Semiconductor supply concentrates in Taiwan, South Korea, and the United States, with lithium-ion cell production anchored in China, South Korea, and Japan. The supply chain rests on rare earth magnet dependencies for sensor miniaturization and copper concentrate for power distribution. Single-source vulnerability in Taiwan wafer fabrication exposes lead times to geopolitical disruption. Distribution runs through authorized distributor networks with regional stocking locations for emergency replacement requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as AI-native alerting platforms threaten to displace legacy hardware-centric architectures in municipal procurement. SaaS-based emergency management platforms represent the most credible substitute threat requiring strategic response.
For Market Incumbents: Compound platform stickiness through predictive analytics module bundling and edge-computing hardware certification investments. Deepen vertical integration into sensor network manufacturing to offset semiconductor supply concentration risks. Prioritize FEMA interoperability compliance as a barrier against cloud-native entrants seeking to unseat installed command-and-control bases. For New Entrants and Emerging Players: Differentiate on mobile app last-mile alerting penetration in Southeast Asian urban corridors where smartphone density exceeds legacy siren coverage. Target India's cyclone early-warning system gaps through BIS-certified integrated platform offerings. Pursue systems integrator partnerships rather than direct municipal sales to bypass entrenched vendor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified industrial conglomerates with federal certification heritage over pure-play communications hardware specialists. Long-term viability hinges on predictive modeling service revenue streams displacing transactional equipment sales. Monitor FCC narrowband-broadband transition timeline clarity as an inflection indicator for public-safety agency procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FEMA Certification Investment | Interoperability compliance creates procurement eligibility barriers for federally funded facilities. |
| Edge Computing Architecture Deployment | Bandwidth-constrained environment penetration opens municipal departments previously excluded from real-time monitoring. |
| Predictive Modeling Service Launch | Digital twin convergence generates recurring revenue streams from regional flood and wildfire authorities. |
| Mobile App Platform Integration | Last-mile alerting displacement of broadcast sirens captures smartphone-penetrated urban corridors. |
| Strategic Partnership with Systems Integrators | County-level bundling of hardware with installation services accelerates subscription-based licensing adoption. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FEMA procurement databases, NFPA standard documentation, and municipal budget disclosures. Primary interviews engaged emergency management directors, federal procurement officers, systems integration specialists, and hardened communications hardware engineers. Secondary validation drew from EPA equipment decontamination standards, FCC spectrum allocation filings, and climate vulnerability assessment reports. Bottom-up unit deployment estimates triangulate against top-down infrastructure investment flows across the analysis window.
Segmentation dimensions modeled include product type, end-user category, technology layer, and distribution channel, with geographic regulatory cluster as an additional cross-cutting variable. CAGRs derive from deployment trajectory analysis across federally funded facilities, healthcare accreditation requirements, and municipal replacement cycles. Forecast inputs incorporate NFPA 1600 standardization timelines, semiconductor supply lead time assumptions, and lithium-ion battery cost curve projections throughout the forecast period.
Material uncertainties — FEMA certification timeline delays, Taiwan semiconductor supply disruption, and FCC spectrum reallocation decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interoperability mandate enforcement and climate vulnerability assessment funding continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market