
 Smart Sandbag Market | 2026-2036
Smart Sandbag Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sandbag Market Insights
Southeast Asian manufacturing expansion is reshaping component supply for smart sandbag producers. Sandbaggy leverages vertical integration across polymer sourcing and IoT module assembly to sustain margin control in North American distribution. FloodSax anchors European demand through specialized hydrogel-based deployable barriers that compete on rapid activation speed. Smart Sandbag Solutions differentiates via proprietary pressure sensor calibration that dominates municipal testing protocols in flood-prone jurisdictions.
A smart sandbag is a deployable flood barrier incorporating embedded sensors, wireless communication modules, and synthetic or composite fabric shells engineered to detect water pressure, structural displacement, or breach conditions in real time, transmitting alerts to centralized monitoring systems for emergency response coordination. IoT-enabled sandbags lead current municipal procurement volumes due to established integration with existing SCADA networks, while solar-powered units represent the fastest-growing sub-category as off-grid resilience investments expand in remote infrastructure corridors. RFID technology occupies mature, cost-optimized positioning across bulk military and construction inventories, whereas Bluetooth Low Energy and ultrasonic sensors concentrate in premium-tier deployments where real-time mesh networking justifies higher unit economics.
EPA stormwater management guidelines and FEMA floodplain construction standards shape product certification requirements and municipal eligibility for federal resilience funding in the United States. The EU Green Deal's climate adaptation directives and REACH material compliance frameworks govern polymer and sensor component market access across European member states. ISO structural performance benchmarks for temporary flood barriers further condition competitive qualification for international disaster relief procurement. Stakeholders must monitor evolving interoperability mandates between proprietary sensor platforms and emerging public emergency alert systems to preserve product relevance across fragmented buyer specifications.
Market Dynamics
FEMA's updated community resilience standards are forcing municipal procurement officers to replace passive sandbag inventories with sensor-embedded flood barriers, compressing replacement cycles and reshaping vendor qualification requirements across flood-prone jurisdictions.
Growth Catalysts
- EPA Stormwater Guidelines:Federal certification requirements for temporary flood barriers are accelerating sensor-embedded product adoption among municipal public works departments seeking eligibility for resilience funding.
- Hurricane Exposure Concentration:Coastal counties in Florida and Louisiana are driving replacement demand as repeated flood events demonstrate failure rates of legacy passive sandbag deployments.
- IoT-SCADA Integration:Established compatibility with existing municipal monitoring networks is reducing deployment friction for connected sandbag systems in urban flood management programs.
Market Restraints
- Polymer Input Volatility:Synthetic fabric shell costs fluctuate with petrochemical feedstock prices, squeezing margin stability for manufacturers without captive resin supply.
- Southeast Asian Supply Concentration:Component sourcing for IoT modules and polymer substrates clusters in Thailand and Vietnam, exposing producers to single-region disruption risk.
- REACH Material Compliance:EU chemical registration requirements create friction for hydrogel-based barrier entrants seeking European market access.
Strategic Opportunities
- Remote Infrastructure Corridors:Solar-powered smart sandbag units address off-grid resilience needs in rural Texas and Alaska where grid-tied monitoring is unavailable.
- EU Green Deal Adaptation Directives:Climate adaptation funding streams are opening procurement channels for certified flood barriers in German and Dutch municipal programs.
- Bluetooth-Ultrasonic Convergence:Mesh networking capabilities from combined low-energy and ultrasonic sensing are enabling premium-tier deployments in critical infrastructure protection.
Industry Challenges
- Sensor Calibration Expertise:Municipal testing protocols require specialized pressure sensor engineering talent that concentrates in flood-prone jurisdictions with established vendor relationships.
- ISO Certification Timelines:International disaster relief procurement qualification demands extended structural performance benchmarking that delays market entry for new product formulations.
- Legacy SCADA Integration Complexity:Proprietary sensor platforms face interoperability mandates with emerging public emergency alert systems that fragment buyer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sandbag Market |
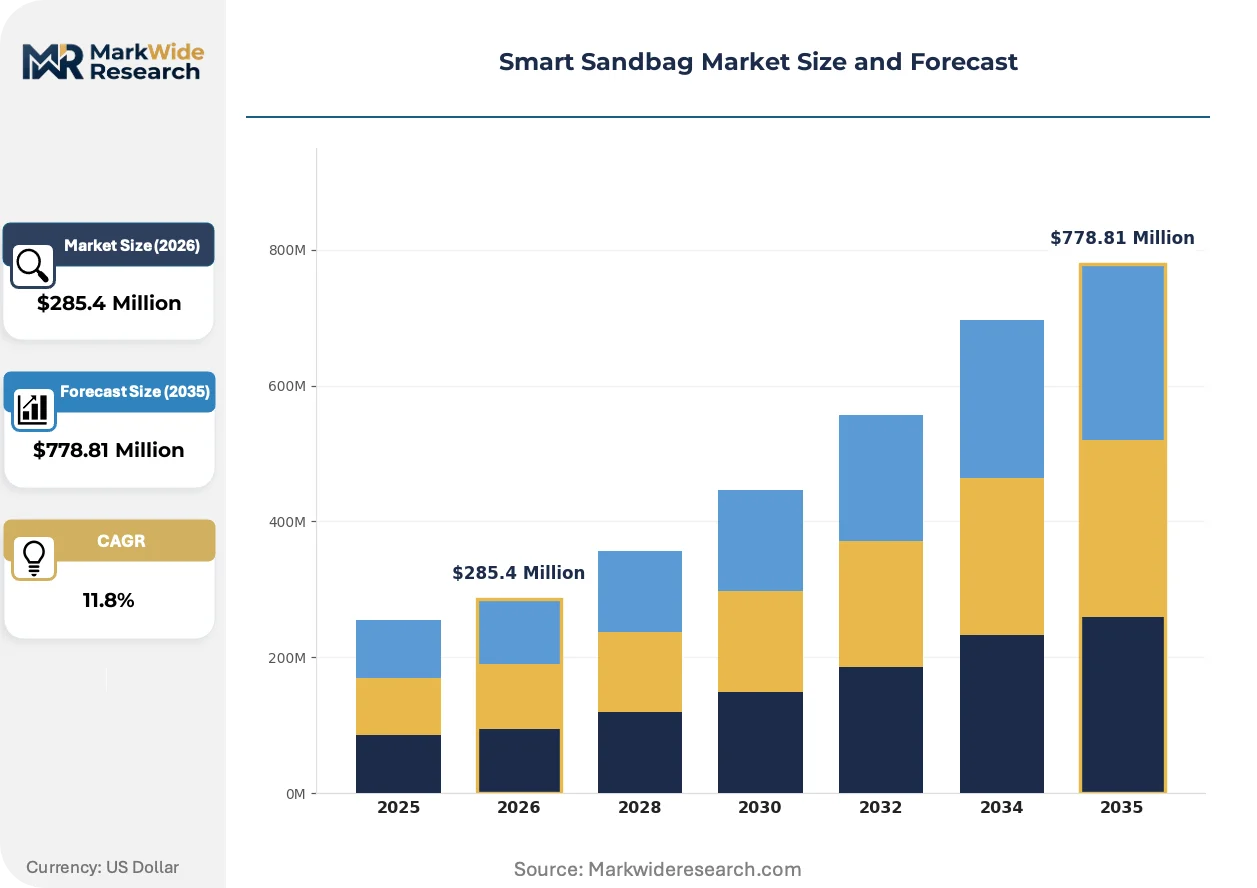
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $778.81 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IoT-Enabled Sandbags, Sensor-Embedded Sandbags, Wireless Communication Sandbags, Solar-Powered Units, Reusable Fabric Sandbags Application: Flood Control, Military Defense, Construction Site Safety, Erosion Prevention, Event Security Technology: RFID, Bluetooth Low Energy, Ultrasonic Sensors, Pressure Sensors, GPS Tracking End User: Municipal Authorities, Military Organizations, Construction Firms, Event Management Companies, Environmental Agencies |
| Companies Covered | Sandbaggy, FloodSax, Smart Sandbag Solutions, Sandbag Innovations, Smart Sandbag Technologies, FloodControl International, HydraTech Systems, Fortress Flood Defense, ABC Flood Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sandbag Market Trends and Innovations
Sensor miniaturization and energy harvesting advances are collapsing the cost-performance threshold for embedded flood monitoring, enabling mass-deployment economics previously reserved for critical infrastructure protection.
Solar-integrated power systems are collapsing the deployment cost differential between grid-connected and off-grid smart sandbag installations. Rural municipalities in Alaska and Texas are adopting these units for remote levee monitoring where electrical infrastructure is absent. The technology is collapsing the historical geographic constraint that limited sensor-embedded barriers to urban flood zones with existing SCADA access.
EPA stormwater management guidelines are tightening certification requirements for temporary flood barriers used in federally funded projects. Manufacturers must now document real-time breach detection capabilities to qualify for municipal procurement. Florida and Louisiana public works departments are responding by specifying IoT-enabled sandbags in replacement contracts for hurricane-season preparedness.
Bulk purchasing consortia are consolidating municipal demand into multi-year framework agreements that displace spot-market transactions. Regional emergency management associations in coastal states are aggregating sandbag procurement across county boundaries to extract volume pricing. This concentration is most visible in the Southeastern United States where interlocal cooperation agreements are standardizing technical specifications and reducing vendor fragmentation.
Smart Sandbag Market Segmentation
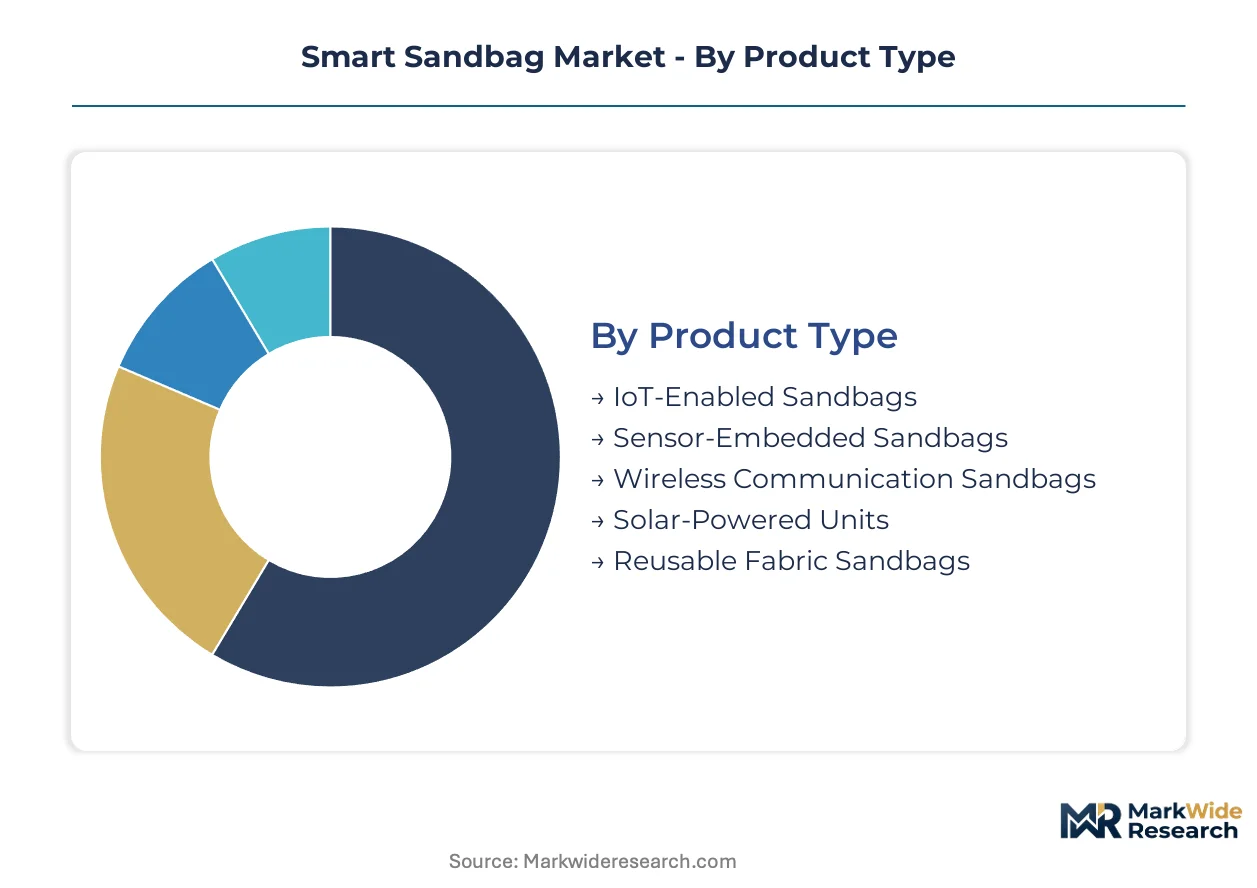
Smart sandbag procurement patterns diverge sharply between established municipal flood programs and emerging defense and construction applications. Technology selection, power architecture, and end-user compliance requirements fragment vendor positioning across these parallel demand channels.
Product Type:
Deployment scenarios span from grid-connected urban flood zones to off-grid remote infrastructure corridors.
- IoT-Enabled Sandbags:Embedded wireless modules transmit real-time breach alerts to municipal SCADA networks. Demand concentrates in Florida and Louisiana coastal counties where FEMA resilience funding mandates sensor-based monitoring for federal reimbursement eligibility.
- Solar-Powered Units:Photovoltaic-integrated power systems eliminate grid dependency for sensor operation. Rural Alaska and Texas municipalities are adopting these for remote levee monitoring where electrical infrastructure is absent, collapsing the historical geographic constraint that limited smart barriers to urban zones.
- Sensor-Embedded Sandbags:Discrete pressure and displacement detectors without full network connectivity. Construction firms favor these for site-specific hazard alerting where SCADA integration is unnecessary.
- Wireless Communication Sandbags:Mesh-networking capable units for coordinated multi-point deployment. Event security contractors specify these for temporary perimeter protection at outdoor venues.
- Reusable Fabric Sandbags:Synthetic shell designs with detachable sensor modules for cost-conscious bulk procurement. Military logistics programs prioritize these for training-cycle economics.
Established volume favors IoT-Enabled Sandbags; emerging adoption favors Solar-Powered Units.
Application:
End-use economics range from federally funded resilience programs to discretionary commercial safety spending.
- Flood Control:Municipal deployment of connected barriers for riverine and coastal inundation defense. EPA stormwater certification requirements under federal procurement guidelines are accelerating sensor-embedded product adoption among public works departments.
- Military Defense:Rapid-deploy perimeter protection and temporary fortification. RFID-tagged inventories dominate this segment for asset tracking across dispersed logistics networks.
- Construction Site Safety:Temporary diversion and containment for excavation and foundation work. Bluetooth Low Energy units are gaining preference for short-range crew alerting without infrastructure investment.
- Erosion Prevention:Coastal and riparian stabilization projects. Environmental agencies specify hydrogel-based alternatives where rapid activation speed outweighs sensor sophistication.
- Event Security:Temporary crowd control and flood perimeter deployment for outdoor venues. Disposable fabric economics predominate over reusable sensor systems in this price-sensitive segment.
Flood Control commands the procurement volume base; Construction Site Safety exhibits the steepest expansion trajectory as building codes tighten temporary barrier requirements.
Technology:
Sensing modality selection trades off network integration depth against unit cost and power consumption.
- Pressure Sensors:Membrane-based water force detection calibrated for breach threshold alerting. Municipal testing protocols in hurricane-prone jurisdictions require specialized calibration engineering that concentrates vendor relationships in established flood management corridors.
- Bluetooth Low Energy:Ultra-low-power mesh networking for localized device coordination. Premium-tier deployments in critical infrastructure protection favor BLE-ultrasonic convergence for redundant sensing coverage.
- RFID:Passive identification for inventory and chain-of-custody tracking. Military and construction bulk purchasing programs rely on this mature, cost-optimized positioning.
- Ultrasonic Sensors:Non-contact water level and structural displacement measurement. German and Dutch municipal programs are specifying these for precision monitoring in climate adaptation-funded projects.
- GPS Tracking:Geolocation for deployed asset recovery and position verification. Remote infrastructure corridors with sparse road networks require this capability for maintenance crew dispatch.
RFID anchors the installed cost base; Pressure Sensors capture the specification intensity in federally funded programs.
End User:
Buyer sophistication and procurement authority fragment across public, military, and commercial channels.
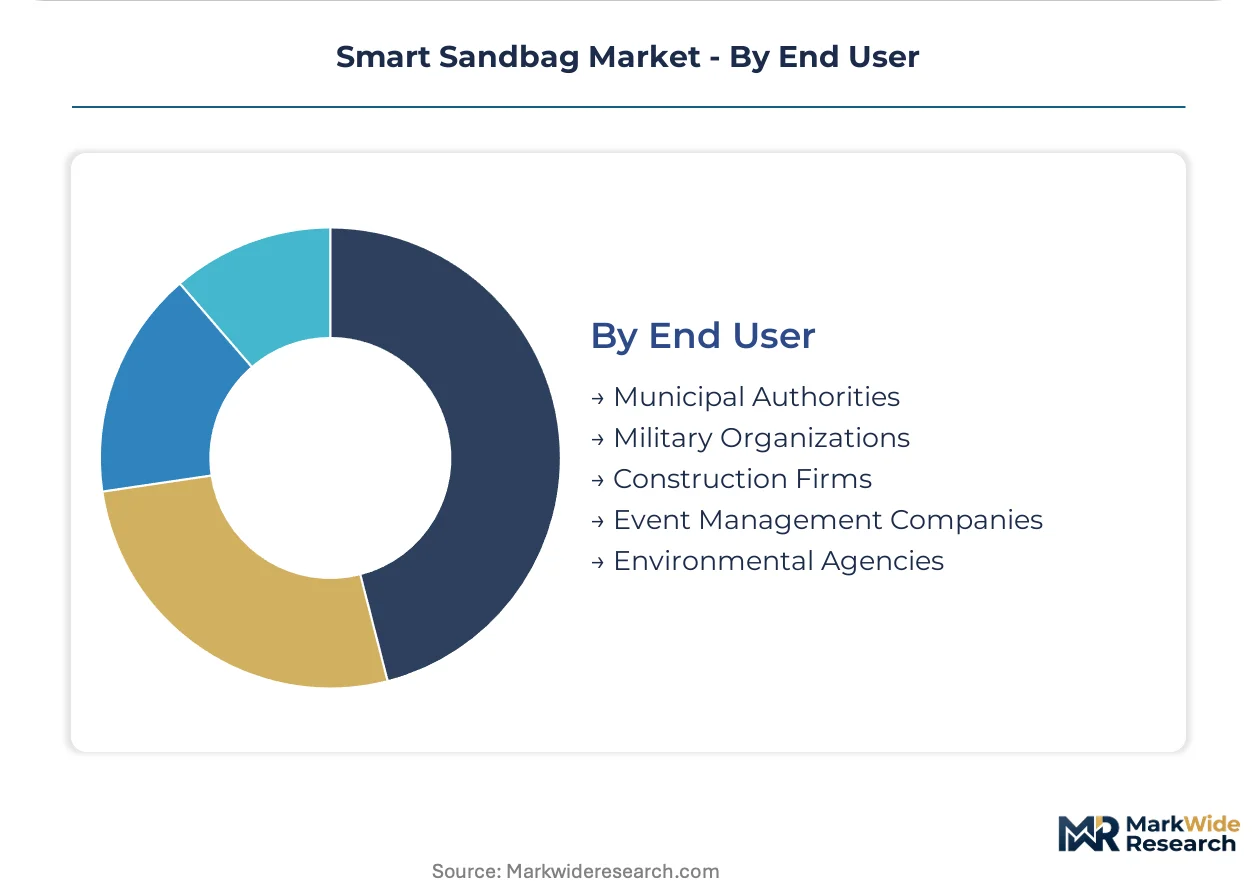
- Municipal Authorities:City and county public works departments with federal resilience funding access. FEMA community resilience standards are compressing replacement cycles and reshaping vendor qualification requirements across flood-prone jurisdictions.
- Military Organizations:Defense logistics and engineering commands with standardized procurement protocols. Bulk framework agreements displace spot-market transactions in this concentrated demand channel.
- Construction Firms:Commercial builders and civil contractors with project-based purchasing. OSHA-compliant temporary barrier specifications are expanding addressable volume in this segment.
- Event Management Companies:Temporary infrastructure providers for festivals and outdoor gatherings. Seasonal demand concentration in hurricane-season months creates procurement timing volatility.
- Environmental Agencies:Federal and state conservation authorities with habitat restoration mandates. EU Green Deal adaptation directives are opening procurement channels for certified flood barriers in member state riparian programs.
Municipal Authorities dominate specification-setting; Environmental Agencies are gaining procurement velocity through climate adaptation funding streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River levee system anchors United States demand for sensor-embedded flood barriers, while the Rhine-Maas-Scheldt delta underwrites Dutch procurement intensity for climate-adaptive infrastructure. German federal adaptation programs and Japanese river basin management authorities complete the core geography set.
United States
FEMA community resilience standards are compressing replacement cycles for passive sandbag inventories across coastal counties. EPA stormwater certification requirements under federal procurement guidelines accelerate sensor-embedded product adoption among public works departments. Florida and Louisiana municipal authorities concentrate procurement volume in hurricane-exposed jurisdictions where repeated flood events demonstrate legacy barrier failure rates.
Germany
EU Green Deal climate adaptation directives open procurement channels for certified flood barriers in municipal riparian programs. REACH material compliance frameworks govern polymer and sensor component market access across federal states. Bavaria and North Rhine-Westphalia anchor specification-setting through ISO structural performance benchmarking for temporary flood barriers in disaster relief frameworks.
Netherlands
Rhine-Maas-Scheldt delta infrastructure protection drives demand for precision water level monitoring in polder management systems. ECHA chemical registration requirements create compliance architecture for hydrogel-based barrier entrants seeking European market access. Randstad metropolitan clusters concentrate municipal testing protocol development for pressure sensor calibration in flood-prone jurisdictions.
Japan
River basin management authorities specify connected barriers for typhoon-season inundation defense in densely populated coastal corridors. METI industrial standards shape IoT module interoperability mandates with emerging public emergency alert systems. Kansai and Kyushu regional governments aggregate procurement across prefectural boundaries to extract volume pricing from framework agreements.
Smart Sandbag Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in polymer sourcing and sensor module fabrication. The vendor base organizes around three archetypes: vertically integrated fabricators with captive resin supply, technology licensors specializing in pressure sensor calibration, and regional assemblers serving bulk military and construction inventories. Dominant competitive moves include backward integration into polymer substrates and strategic partnerships for SCADA network interoperability certification.
Among North American platform integrators, Sandbaggy exemplifies the vertically integrated archetype with control across polymer sourcing and IoT module assembly. FloodSax occupies a position within the European technology licensing tier, anchoring specialized hydrogel-based deployable barrier development. Smart Sandbag Solutions represents the calibration-specialist archetype, sitting within municipal testing protocol concentration zones where pressure sensor engineering talent clusters.
| Leading Market Players |
|---|
| Sandbaggy |
| FloodSax |
| Smart Sandbag Solutions |
| Sandbag Innovations |
| Smart Sandbag Technologies |
| FloodControl International |
| HydraTech Systems |
| Fortress Flood Defense |
| ABC Flood Solutions |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Thai and Vietnamese IoT module assembly determines both pricing tier spreads and supply chain shape, compressing margins for non-integrated fabricators while rewarding those with captive polymer sourcing and regional distribution hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SCADA-integrated municipal deployments from Bluetooth-enabled construction applications and RFID-tagged military bulk orders. Price differentiation hinges on FEMA certification grade and volume scale, with certified units commanding substantial premiums for federal reimbursement eligibility. Cost compression in the economy tier is intensifying because Southeast Asian polymer substrate volatility squeezes non-integrated competitors. Municipal authorities exhibit the least price sensitivity due to resilience funding access, while event management contractors demonstrate acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and Southeast Asian manufacturing hubs dominates strategic planning for component sourcing. Production gravity centers on Thailand, Vietnam, and China for IoT modules, polymer substrates, and sensor calibration equipment. Raw material dependencies draw from petrochemical feedstocks, hydrogel compounds, and photovoltaic cells. Single-region concentration risk threatens continuity during geopolitical disruptions or climate events. Distribution runs through regional emergency management consortia in coastal states, consolidated bulk military procurement channels, and direct municipal framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability mandates between proprietary sensor platforms and emerging public emergency alert systems constitute a platform-economics inflection, rewarding vendors who architect open-standard compatibility ahead of fragmented buyer specifications.
For Market Incumbents: Build certification moats around FEMA community resilience standards and EPA stormwater guidelines to lock out unqualified competitors. Deepen backward integration into polymer substrates to insulate margin structures from petrochemical volatility. Anchor relationships in Florida and Louisiana municipal testing corridors where pressure sensor engineering talent concentrates and replacement cycles compress.
For New Entrants and Emerging Players: Establish a beachhead in solar-powered off-grid deployments across rural Alaska and Texas, where grid-tied SCADA dependency excludes established urban-focused vendors. Target construction site safety applications with Bluetooth Low Energy units that bypass municipal certification complexity. Pursue OEM partnerships with regional emergency management associations to access aggregated volume procurement without direct municipal sales infrastructure.
For Investors and Strategic Acquirers: FEMA's updated community resilience standards reshape the acquisition landscape toward platform-integrators with SCADA interoperability certification rather than component specialists. Long-term viability favors vertically integrated fabricators with captive resin supply and established municipal testing relationships. Monitor procurement consolidation through bulk purchasing consortia as the signal for pricing power shifts from vendors to aggregated buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| SCADA Interoperability Certification | FEMA resilience funding eligibility hinges on seamless integration with municipal monitoring networks. |
| Backward Integration into Polymer Sourcing | Captive resin supply insulates margin stability from petrochemical feedstock volatility. |
| Solar Power System Integration | Off-grid capability unlocks rural Alaska and Texas corridors previously excluded from smart barrier deployment. |
| Hydrogel Formulation Development | REACH-compliant rapid-activation barriers access EU Green Deal adaptation funding streams. |
| Pressure Sensor Calibration Partnerships | Proprietary testing protocols in hurricane-prone jurisdictions create vendor lock-in effects. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal public works directors, emergency management coordinators, polymer procurement leads, and IoT systems integrators; and secondary validation against FEMA procurement databases, EPA stormwater certification records, SEC filings from materials suppliers, and customs trade data for polymer substrate flows. Bottom-up unit economics triangulated with top-down federal resilience funding allocations.
Forecast inputs considered technology type, power architecture, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level adoption curves weighted by FEMA reimbursement eligibility timelines and municipal budget cycle patterns. Modeled variables included hurricane-season deployment velocity, SCADA network penetration rates, and solar integration cost trajectories.
Sensitivities concentrate around tariff regime shifts affecting Southeast Asian component sourcing, petrochemical price volatility, and interoperability mandate timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Infrastructure Protection Market