
 Incident and Deviation Management Solution Market | 2026-2036
Incident and Deviation Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Incident and Deviation Management Solution Market Foresight
Multi-source procurement for incident management tooling is rebalancing toward integrated platform suites that unify deviation tracking with broader quality management workflows. ServiceNow leverages its enterprise workflow heritage to anchor complex orchestration across regulated industries. Splunk competes through deep log analytics specialization that extends into root-cause identification for IT operational incidents. PagerDuty differentiates via real-time alerting mechanics that sustain uptime-critical environments in healthcare and aerospace.
An incident and deviation management solution constitutes a software platform engineered to capture, classify, investigate, and remediate operational anomalies, typically featuring configurable workflows, audit trails, and CAPA (Corrective and Preventive Action) linkages to satisfy ISO 9001 and 21 CFR Part 11 traceability requirements. Its primary commercial purpose centers on reducing regulatory exposure, shortening incident resolution cycles, and generating defensible documentation for inspectorate review. Cloud-based deployments now lead expansion as pharmaceutical and biotech end users prioritize elastic scalability and reduced infrastructure overhead, while hybrid architectures retain traction among hospitals with strict data residency requirements. The service type dimension shows implementation and consulting commanding margin pools due to complex validation protocols in GxP environments.
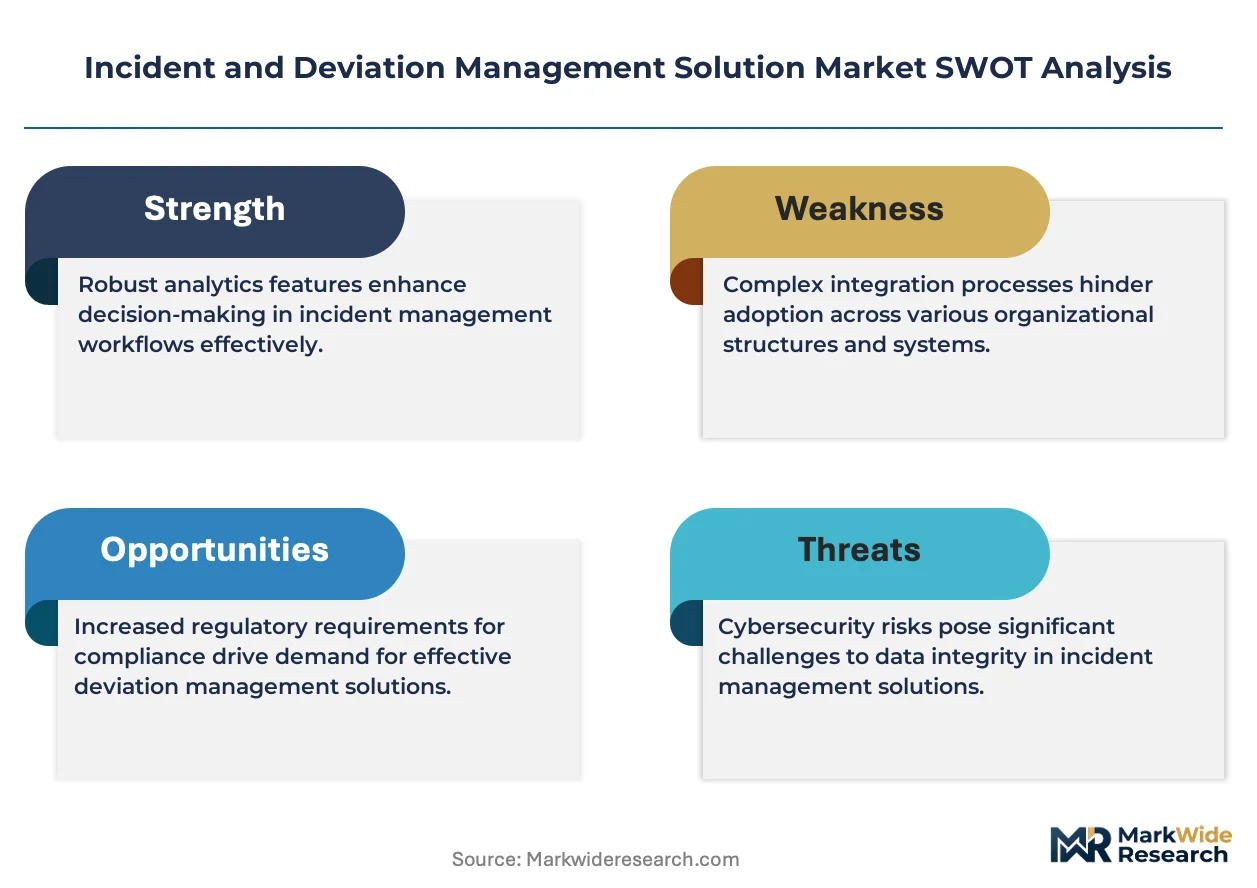
FDA 21 CFR Part 11 and EU Annex 11 shape product standards by mandating electronic signature integrity, audit trail immutability, and system validation documentation that vendors must embed natively. EMA's increased inspection frequency for deviation closure timelines directly tightens demand for automated escalation and root-cause analytics. ISO 14971 risk management requirements in medical device manufacturing further compress acceptable response windows. Stakeholders must monitor how AI-infused classification engines will alter regulatory acceptance criteria for automated deviation severity scoring.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for pharmaceutical quality systems while FDA 21 CFR Part 11 validation requirements force vendors to embed audit-trail immutability natively. This structural tension between agility and compliance is reconfiguring competitive positioning across the vendor landscape.
Growth Catalysts
- EMA Annex 11 Inspection Intensification:European regulators are tightening deviation closure timelines, forcing manufacturers to automate escalation workflows and root-cause analytics to avoid citation risk.
- Biotech Distributed R&D Expansion:Cloud-based platforms enable real-time collaboration across multiple research sites, eliminating latency in adverse event reporting chains.
- Medical Device ISO 14971 Mandates:Risk management requirements compress acceptable response windows for operational anomalies, driving demand for integrated CAPA linkages.
Market Restraints
- Validation Cost Burden:GxP environments require extensive system qualification documentation, inflating implementation budgets and extending procurement cycles.
- Data Residency Friction:Hospital networks in Germany and France face strict local storage requirements that complicate pure-cloud deployments and favor hybrid architectures.
- Legacy System Entrenchment:On-premise quality management installations create integration complexity that slows platform migration and extends parallel system maintenance.
Strategic Opportunities
- AI-Infused Classification Engines:Machine learning algorithms for automated deviation severity scoring represent unclaimed white space as regulators develop acceptance criteria.
- India CDSCO Alignment:India's pharmaceutical regulator is harmonizing with ICH guidelines, creating demand for complaint-handling systems that satisfy both domestic and export markets.
- Subscription Pricing Penetration:SaaS delivery models are displacing perpetual licenses in mid-tier biotech, opening recurring revenue streams previously captured by on-premise incumbents.
Industry Challenges
- Qualified Personnel Scarcity:Validation engineers with combined GxP and cloud architecture expertise command premium compensation, constraining implementation capacity.
- Cross-System Integration Complexity:Biotech firms struggle to synchronize deviation data across LIMS, ERP, and quality platforms without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incident and Deviation Management Solution Market |
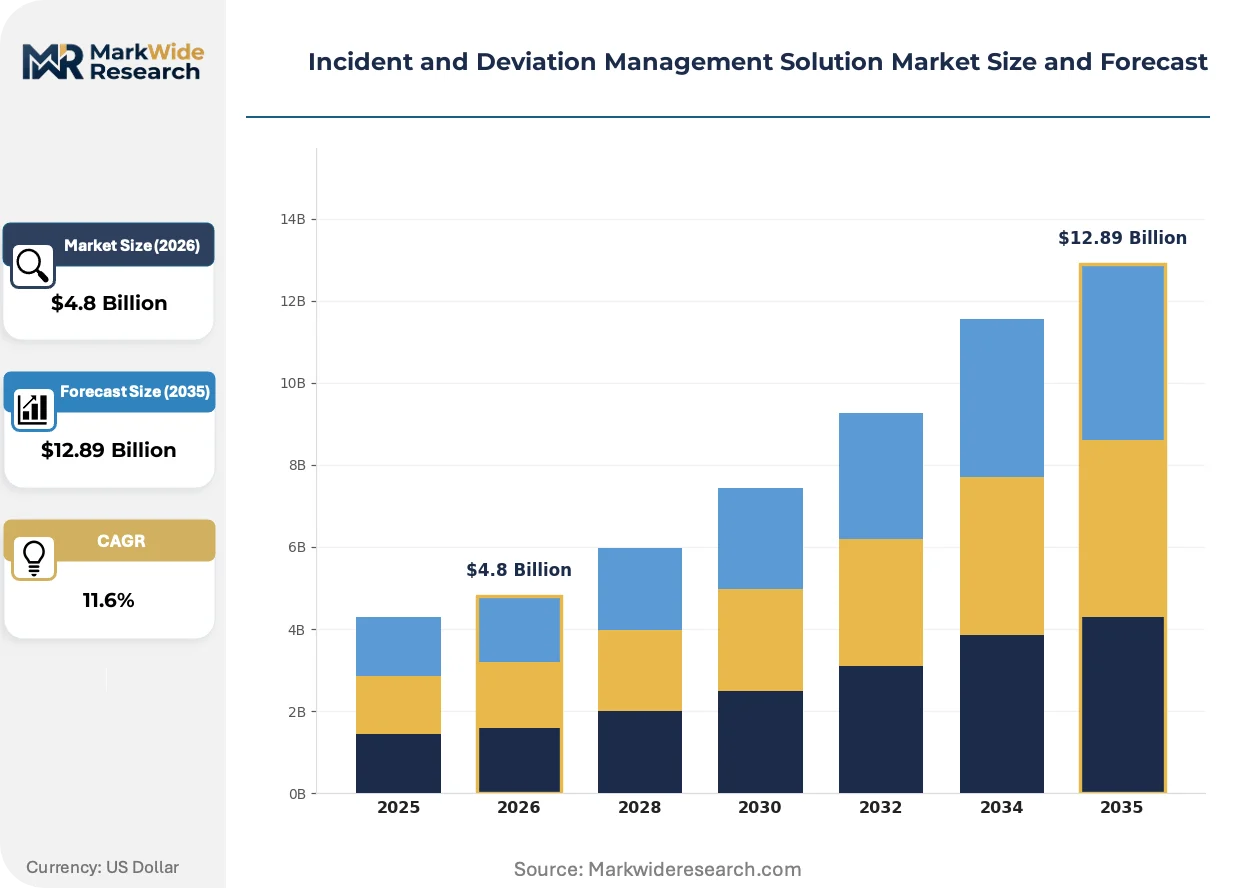
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Open Source End User: Pharmaceuticals, Biotech, Hospitals, Aerospace Service Type: Consulting, Implementation, Support, Training Deployment Model: Public Cloud, Private Cloud, Community Cloud, Multi-Cloud |
| Companies Covered | Atlassian, PagerDuty, SolarWinds, Splunk, ServiceNow, Microsoft, ETQ, MetricStream, MasterControl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incident and Deviation Management Solution Market Shifts & Advancements
Intelligent automation is penetrating quality workflows faster than regulatory frameworks can codify acceptance standards, creating a temporary competitive window for vendors with native AI capabilities. This technological acceleration is forcing incumbents to rearchitect core platforms or risk displacement.
Natural language processing engines are absorbing unstructured complaint data from call centers, social media, and field reports to auto-populate deviation records. Pharmaceutical manufacturers in the United States are piloting these tools to reduce manual transcription errors and accelerate initial triage. The technology is absorbing tasks previously requiring dedicated pharmacovigilance associates, compressing headcount requirements in high-volume reporting environments.
FDA's evolving guidance on computer software assurance is shifting validation burden toward critical functionality, reducing documentation overhead for lower-risk system components. Medical device manufacturers are responding by prioritizing automated testing frameworks over manual protocol execution. This regulatory recalibration is accelerating cloud migration timelines for Class II device makers previously paralyzed by validation scope uncertainty.
Hospital procurement departments are consolidating vendor relationships around platform suites that unify incident tracking with broader quality management workflows. Health systems in Texas and California are abandoning point solutions in favor of integrated contracts that reduce interface maintenance overhead. This buyer concentration is squeezing standalone deviation specialists and rewarding vendors with adjacent CAPA, change control, and audit management modules.
Incident and Deviation Management Solution Market Segmentation
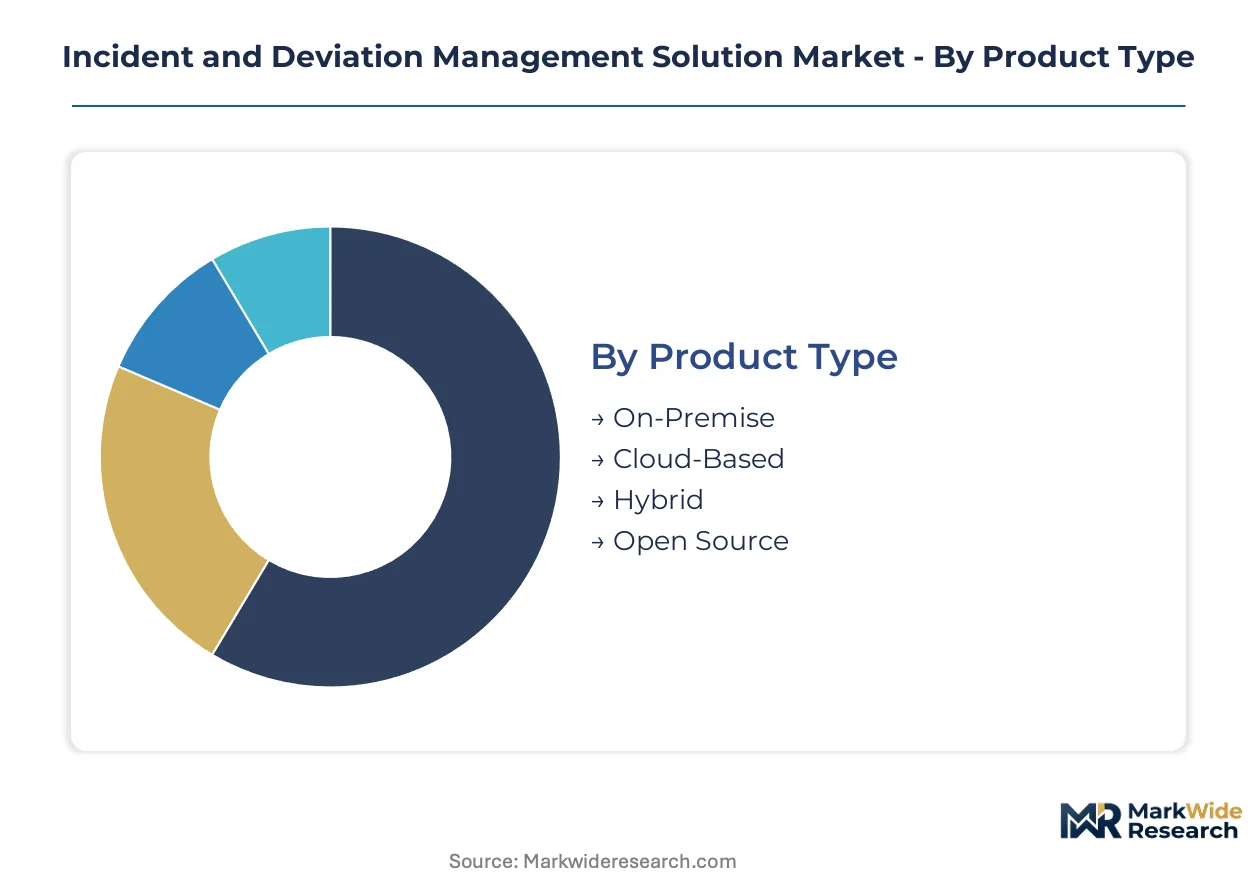
Segmentation in incident and deviation management solutions reveals how compliance requirements, infrastructure maturity, and risk tolerance fragment procurement patterns across regulated industries. Buyers prioritize different capability bundles based on their inspectorate exposure and IT modernization timelines.
Product Type:
Deployment architecture separates buyers by their tolerance for validation complexity versus infrastructure control.
- Cloud-Based:Multi-tenant SaaS platforms with pre-validated GxP configurations eliminate server qualification overhead. Pharmaceutical manufacturers in the United States favor these for elastic scaling during product launch surges and FDA inspection readiness.
- On-Premise:Single-tenant installations behind corporate firewalls satisfy strict data sovereignty mandates. German hospital networks and French medical device makers retain these for ANSM and BfArM audit trail localization requirements.
- Hybrid:Split architectures isolate sensitive deviation records on-premise while pushing analytics workloads to cloud infrastructure. Biotech firms with distributed R&D sites deploy these to balance collaboration speed with IP protection.
- Open Source:Community-maintained frameworks with customizable workflow engines attract mid-tier manufacturers with internal validation expertise.
Cloud-based deployments lead volumes today; hybrid architectures are gaining share fastest as buyers seek compromise positions.
End User:
Industry verticals dictate functional requirements through their distinct regulatory cadences and incident velocity profiles.
- Pharmaceuticals:Batch manufacturing environments with 21 CFR Part 11 mandates require electronic signature workflows and immutable audit trails. FDA warning letter exposure drives replacement cycles for legacy quality management systems.
- Biotech:Cell and gene therapy developers need deviation tracking that integrates with manufacturing execution systems for personalized medicine batches. CDER guidance on advanced therapy products tightens documentation standards.
- Hospitals:Patient safety event reporting with Joint Commission alignment prioritizes rapid escalation and root-cause templates for sentinel events.
- Aerospace:AS9100 quality systems with FAA production approval holder requirements emphasize non-conformance traceability through supply chain tiers.
Pharmaceuticals leads volumes today; biotech is expanding most quickly.
Service Type:
Professional services intensity correlates with buyer internal capabilities and validation risk appetite.
- Implementation:System configuration, data migration, and user acceptance testing for GxP environments. Project scopes inflate when legacy paper records require digitization for FDA pre-approval inspections.
- Consulting:Process redesign and regulatory strategy advisory for firms restructuring quality operations post-merger.
- Support:Ongoing technical assistance and patch management with validated change control documentation.
- Training:Role-based curriculum development for deviation investigators, CAPA owners, and system administrators.
Implementation commands the largest service spend; consulting shows the steepest expansion trajectory as buyers seek regulatory strategy guidance.
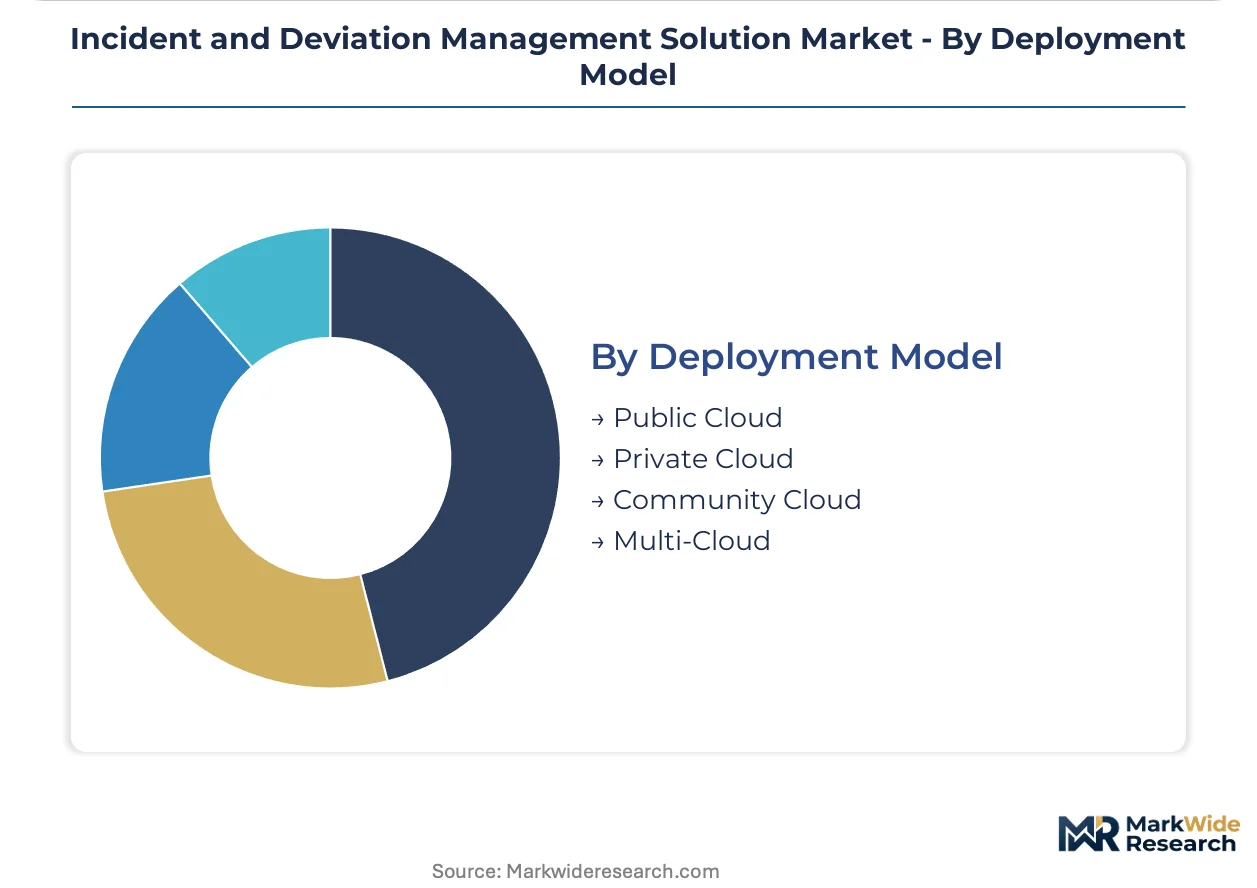
Deployment Model:
Infrastructure tenancy arrangements reflect data sensitivity classifications and cross-border collaboration needs.
- Public Cloud:Shared infrastructure with provider-managed security certifications accelerates time-to-validation for resource-constrained manufacturers.
- Private Cloud:Dedicated single-tenant environments with customized encryption key management serve defense contractors and government healthcare providers.
- Community Cloud:Sector-specific platforms shared among non-competing peers reduce per-seat costs for contract research organizations.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and GCP prevent vendor lock-in and satisfy business continuity requirements for critical quality systems.
Public cloud leads volumes today; multi-cloud is climbing the fastest as buyers diversify infrastructure risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturing clusters in the United States generate the highest concentration of deviation management platform deployments, with FDA inspection intensity driving replacement cycles for legacy quality systems across the country.
United States
Boston's biotech corridor and New Jersey's pharmaceutical belt demand cloud-native platforms with 21 CFR Part 11 validation. FDA warning letter volume in 2023 accelerated hospital network consolidation around integrated quality suites. Texas Medical Center in Houston now mandates automated escalation workflows for patient safety events.
Germany
Baden-Württemberg's medical device manufacturers anchor European demand for hybrid architectures balancing ANSM audit trail localization with cloud analytics. BfArM data residency requirements force vendors to offer sovereign hosting options. Munich's Siemens Healthineers ecosystem drives CAPA integration with manufacturing execution systems.
Switzerland
Basel's pharmaceutical headquarters cluster prioritizes multi-tenant SaaS platforms for adverse event reporting across global trial networks. Swissmedic inspection harmonization with EMA Annex 11 tightens deviation closure timelines. Roche and Novartis supplier ecosystems in the region demand real-time collaboration tools.
India
Hyderabad's vaccine manufacturing hub and Mumbai's API belt expand adoption as CDSCO aligns with ICH pharmacovigilance guidelines. Export-oriented contract manufacturers in Gujarat require complaint-handling systems satisfying both domestic and FDA inspections. Bangalore's biotech startups drive cloud-first procurement.
Japan
Tokyo-Osaka pharmaceutical corridor demands platforms integrating PMDA electronic submission requirements with deviation workflows. Cell therapy developers in Kobe cluster need manufacturing execution system linkages for personalized medicine batches. METI digitalization subsidies accelerate legacy system replacement.
Incident and Deviation Management Solution Market Competitive Landscape
Global majors compete with regional champions across compliance automation depth, with enterprise workflow vendors facing off against specialized quality software providers. The vendor base organizes into three tiers: horizontal platform extenders, vertical quality specialists, and open-source integrators. Consolidation pressure intensifies as hospital procurement departments demand unified suites over point solutions. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized validation support.
Among horizontal platform extenders, ServiceNow and Microsoft exemplify archetypes leveraging existing enterprise workflow footprints to anchor quality automation. Splunk and PagerDuty occupy positions on the IT-centric vector, applying operational incident expertise to regulated manufacturing environments. ETQ and MetricStream represent vertical specialists with native GxP configurations. MasterControl anchors the compliance-first tier with pre-validated pharmaceutical workflows.
| Leading Market Players |
|---|
| Atlassian |
| PagerDuty |
| SolarWinds |
| Splunk |
| ServiceNow |
| Microsoft |
| ETQ |
| MetricStream |
| MasterControl |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up quality software specialists now control three of the top five deviation management platforms, concentrating supply-side pricing power while compressing implementation margins through standardized SaaS delivery models. Their portfolio discipline favors recurring revenue over project-based consulting, reshaping how pharmaceutical buyers negotiate multi-year contracts.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers runs through subscription pricing tiers, with AWS and Azure compute inflation partially absorbed by vendors rather than fully transferred to biotech customers. Pricing stratifies across enterprise, mid-market, and entry-level tiers, with differentiation anchored in validation documentation depth and FDA 21 CFR Part 11 pre-certification status. Cost compression in the mid-market tier is intensifying as ServiceNow and Microsoft bundle deviation modules into broader workflow suites. Hospital networks exhibit highest price sensitivity due to capital budget constraints, while pharmaceutical manufacturers prioritize compliance assurance over per-seat economics.
Supply Chain Analysis
Dual-sourcing requirements for critical system components now mandate that pharmaceutical manufacturers qualify at least two deviation platform providers for business continuity, though true switching costs remain prohibitive. Software development concentrates in the United States, India, and Ireland, with implementation services drawing from consulting networks in Germany and Switzerland. Cloud infrastructure rests on hyperscaler data centers in Virginia, Frankfurt, and Singapore. Single-source vulnerability persists in specialized validation engineering talent pools. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for GxP deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India, where CDSCO alignment with ICH guidelines lags FDA enforcement intensity by approximately three inspection cycles, allowing export-oriented manufacturers to capture compliance premiums in regulated markets while operating under lighter domestic oversight.
For Market Incumbents: To counter Microsoft and ServiceNow platform bundling, MasterControl and ETQ should deepen native AI classification capabilities and anchor exclusive partnerships with top-tier systems integrators possessing GxP validation expertise. Capacity addition in Hyderabad and Bangalore captures biotech manufacturing expansion without competing for scarce US-based implementation engineers. For New Entrants and Emerging Players: Regional cloud service providers in Germany and France represent the most penetrable channel partner type for sovereign-hosting-compliant deviation platforms, given BfArM and ANSM data residency mandates that exclude US hyperscalers from sensitive hospital deployments. Target mid-tier medical device manufacturers in Baden-Württemberg seeking AS9100-aligned quality systems with lower total cost of ownership than incumbent offerings. For Investors and Strategic Acquirers: Valuations sit cheapest among bootstrapped European quality software specialists with established ANSM validation documentation and limited US market presence. Long-term viability hinges on AI-infused workflow automation escaping regulatory acceptance uncertainty. Acquisition targets should demonstrate live CAPA-MES integration deployments. The signal to watch is FDA guidance publication on computer software assurance for machine learning classification engines.| Strategic Initiative | Industry Significance |
|---|---|
| AI Classification Engine Development | Automated deviation severity scoring reduces pharmacovigilance headcount at FDA-inspected manufacturers. |
| Multi-Cloud Infrastructure Certification | AWS-Azure-GCP orchestration prevents vendor lock-in for EMA Annex 11 compliance-critical systems. |
| Validation Engineering Talent Acquisition | GxP-cloud hybrid expertise scarcity constrains implementation capacity across biotech distributed R&D sites. |
| CDSCO-Aligned Platform Localization | ICH pharmacovigilance harmonization opens Indian export-oriented contract manufacturers to integrated quality suites. |
| CAPA-MES Integration Partnership | Siemens and SAP manufacturing execution linkages differentiate platforms for cell therapy personalized medicine batches. |
Research Methodology
Direct dialogue with quality assurance directors, regulatory affairs leads at pharmaceutical manufacturers, hospital procurement managers, and GxP validation engineers grounded the qualitative framework, supplemented by FDA 483 observation databases, EMA inspection outcome reports, and SEC 10-K disclosures from publicly traded software vendors. Secondary validation drew from ISO certification registries, clinical trial deviation tracking publications, and cloud infrastructure capex disclosures. Bottom-up and top-down triangulation cross-checked segment sizing against aggregate market expenditure patterns.
Bottom-up modeling anchored volume estimates in deployment architecture splits and end-user industry concentrations, while top-down validation tested aggregate figures against IT spending ratios in regulated manufacturing. Segmentation dimensions included deployment model, organization size tier, vertical regulatory cluster, integration complexity level, and geographic adoption pattern across the analysis window. CAGRs derived from fitted growth curves applied to validated base-year estimates, with pharmaceutical inspection intensity and biotech funding cycles serving as industry-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA AI guidance timing and EMA inspection resource allocation. Deviation in cloud infrastructure cost trajectories or sovereign data localization mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Global Data Resiliency Market