
 Latin America Incident Response Services Market | 2026-2036
Latin America Incident Response Services Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Incident Response Services Market Insights
Channel architecture for incident response delivery across Latin America is fragmenting as multinational consultancies, pure-play cybersecurity vendors, and telecom-anchored MSSPs compete for enterprise relationships. Deloitte Touche Tohmatsu Limited leverages its audit-client trust base to cross-sell retained IR capabilities, while Palo Alto Networks sustains technology-led positioning through integrated endpoint and network detection platforms. IBM Corporation anchors mid-market penetration with localized Spanish-Portuguese SOC operations in São Paulo and Mexico City.
Incident response services encompass the systematic detection, containment, eradication, and recovery methodologies applied following cybersecurity breaches, typically executed through 24/7 security operations centers with mean-time-to-response targets under one hour for critical infrastructure clients. These services protect organizational continuity, preserve regulatory compliance postures, and minimize financial exposure from data exfiltration or operational technology disruption. Managed services within the service type dimension dominate current revenue as clients outsource continuous monitoring rather than build internal SOCs, while cloud deployment models expand fastest as Brazilian and Colombian enterprises abandon capital-intensive on-premises security stacks. Investigative services command premium pricing due to scarce forensic talent pools concentrated in São Paulo, Buenos Aires, and Santiago.
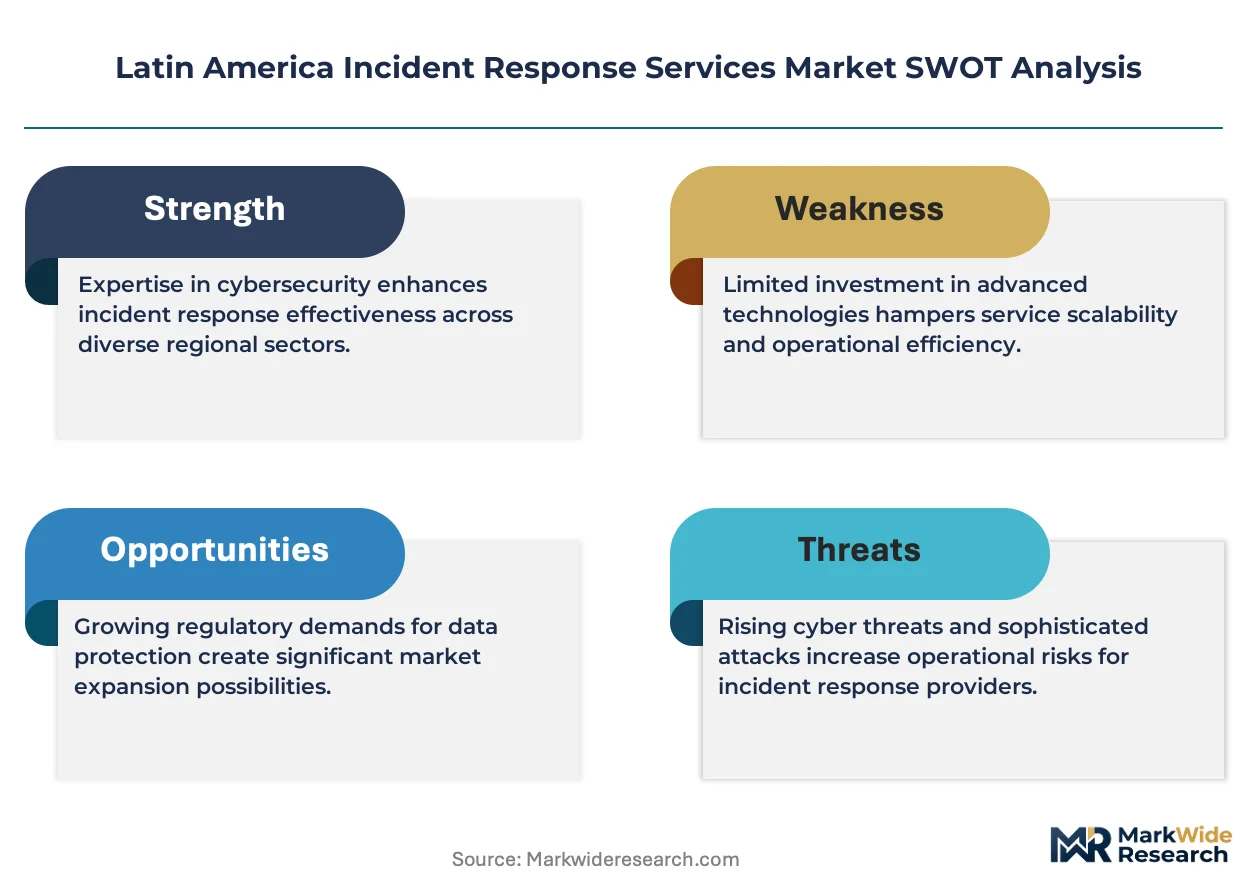
Brazil's LGPD enforcement by its national data protection authority and Mexico's fintech-specific cybersecurity provisions issued by CNBV reshape procurement requirements, compelling financial and healthcare verticals to retain external IR retainers with documented response timelines. Argentina's CNDC standards for critical infrastructure operators further tighten vendor qualification criteria, favoring providers with in-country incident handlers and local language capabilities. Stakeholders must weigh build-versus-buy decisions for SOC capacity against the accelerating regulatory expectation of demonstrable response readiness within contractual service level agreements.
Market Dynamics
Cloud migration by Brazilian and Mexican financial institutions is dismantling legacy security architectures and forcing procurement teams to rebuild incident response capabilities around API-driven detection platforms rather than perimeter-based defenses.
Growth Catalysts
- LGPD enforcement:Brazil's national data protection authority mandates documented breach response timelines, compelling banks and healthcare providers to retain external incident response retainers with guaranteed service level agreements.
- Ransomware proliferation:Escalating attacks against critical infrastructure operators across Argentina and Colombia create sustained demand for 24/7 security operations center coverage and forensic investigation capabilities.
- Cloud migration:Regional enterprises abandoning on-premises security stacks for AWS and Azure environments require cloud-native detection and response architectures that internal IT teams cannot architect independently.
Market Restraints
- Forensic talent scarcity:Certified incident handlers concentrate in São Paulo, Buenos Aires, and Santiago, creating 40-60% salary premiums that inflate service delivery costs across secondary markets.
- Legacy infrastructure drag:Colombian and Peruvian enterprises maintain decades-old core banking systems that resist API integration with modern extended detection and response platforms.
- Currency volatility:Argentine peso and Brazilian real fluctuations against the dollar compress margins for multinational providers pricing services in local currencies.
Strategic Opportunities
- Mid-market penetration:Chilean manufacturing and logistics firms below 5,000 employees remain underserved by current managed detection offerings optimized for large financial institutions.
- OT-IT convergence:Brazilian energy and mining operators require unified incident response spanning operational technology networks and enterprise IT, a capability few regional providers have assembled.
- CNBV fintech rules:Mexico's banking regulator mandates specialized cybersecurity provisions for digital payment platforms, creating compliance-driven demand from neobanks and payment processors.
Industry Challenges
- Certification bottlenecks:GIAC and EC-Council credential holders remain insufficient to staff expanding security operations centers in Mexico City and Bogotá, extending recruitment cycles to 90-120 days.
- Integration complexity:Enterprises running hybrid SAP and Oracle environments struggle to normalize log feeds into cloud-native SIEM platforms, delaying mean-time-to-detection improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Incident Response Services Market |
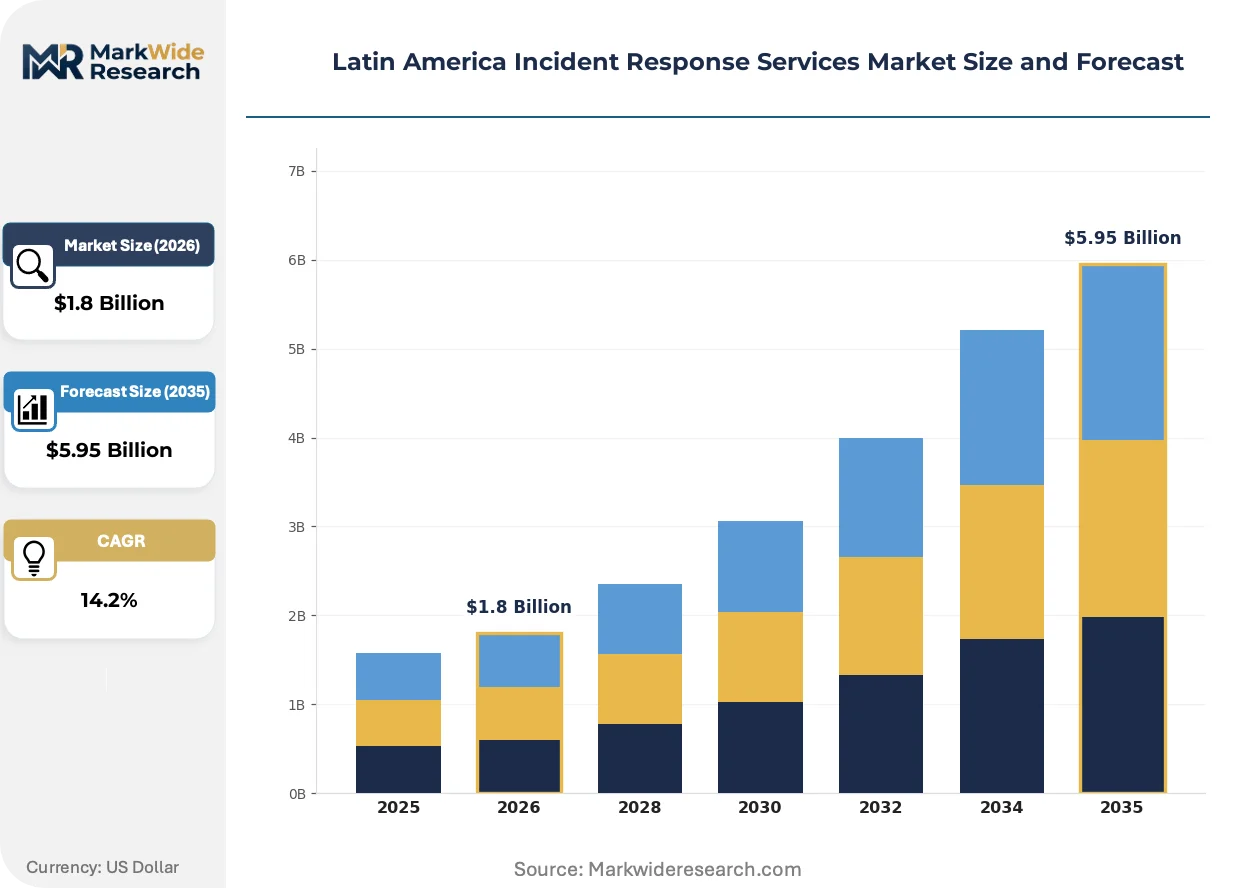
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Consulting, Incident Management, Investigative Services Industry Vertical: Healthcare, Finance, Telecommunications, Manufacturing Deployment Model: On-Premises, Cloud, Hybrid, Remote Client Size: Small Enterprises, Medium Enterprises, Large Enterprises, Multinational Corporations |
| Companies Covered | Deloitte Touche Tohmatsu Limited, Ernst & Young, IBM Corporation, Palo Alto Networks, Check Point Software Technologies Ltd, Cisco Systems, Kaspersky Lab, BAE Systems, FireEye, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Incident Response Services Market Trends and Innovations
Extended detection and response platforms are compressing the vendor landscape as buyers consolidate point solutions, while regulatory mandates harden procurement specifications around demonstrable response capabilities.
Extended detection and response technology aggregates endpoint, network, and cloud telemetry into unified investigation workflows. Brazilian retail banks with 500-2,000 employees are adopting these platforms fastest, displacing siloed antivirus and firewall management contracts. This convergence is digitizing incident response workflows that previously required manual correlation across five or more separate consoles.
Argentina's CNDC standards for critical infrastructure operators now require documented incident response playbooks with quarterly testing protocols. The regulation forces energy and telecommunications providers to abandon informal security relationships with local integrators in favor of audited managed security service providers with ISO 27035 certification. Mid-sized Argentine utilities are responding by consolidating vendor relationships to reduce compliance documentation burden.
Retainer-based procurement is displacing hourly incident response engagements across the region's financial sector. Colombian insurers and asset managers now demand fixed-fee arrangements covering guaranteed response times rather than unpredictable professional services billing. This shift is most visible in Bogotá's fintech corridor, where venture-backed payment platforms negotiate all-inclusive cybersecurity subscriptions that bundle detection, response, and regulatory reporting.
Latin America Incident Response Services Market Segmentation
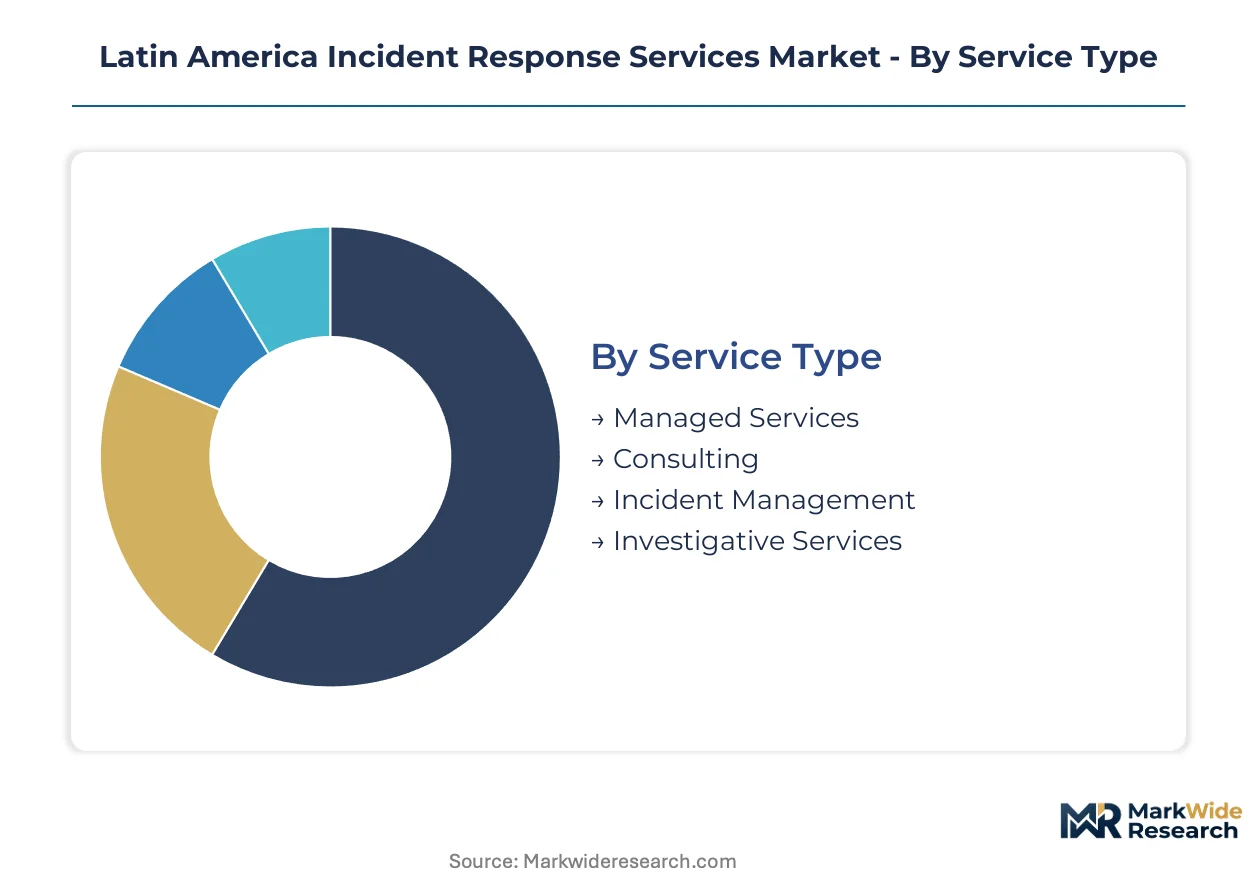
Incident response procurement in Latin America fragments across service delivery models, regulatory exposure levels, and infrastructure maturity. Buyers select configurations based on cloud migration status, internal SOC capabilities, and vertical-specific compliance burdens.
Service Type:
Use cases span continuous monitoring for banks without internal security operations centers to discrete forensic investigations following confirmed breaches.
- Managed Services:Continuous 24/7 monitoring delivered through security operations centers with contractual mean-time-to-response guarantees. Brazilian financial institutions with 500-2,000 employees dominate demand as LGPD mandates documented response timelines they cannot staff internally.
- Investigative Services:Post-breach digital forensics and malware reverse engineering executed by certified incident handlers. Scarce talent pools in São Paulo, Buenos Aires, and Santiago command premium pricing for ransomware recovery engagements.
- Consulting:Advisory engagements covering incident response playbook development and tabletop exercises.
- Incident Management:On-demand breach containment and eradication without ongoing monitoring commitments.
The dominant share belongs to Managed Services, while Investigative Services is closing the gap fastest.
Industry Vertical:
Regulatory intensity and asset criticality create divergent procurement patterns across sectors.
- Finance:Banks, insurers, and fintech platforms subject to LGPD, CNBV, and central bank cybersecurity mandates. Mexican neobanks and Colombian payment processors drive retainer-based procurement with embedded regulatory reporting.
- Healthcare:Hospitals and health insurers managing protected health information under Brazil's LGPD health data provisions. São Paulo hospital networks invest in cloud-native detection as they migrate electronic medical records.
- Telecommunications:Mobile and fixed-line operators designated as critical infrastructure under Argentina's CNDC standards.
- Manufacturing:Chilean and Brazilian industrial firms with operational technology exposure.
Finance commands the largest revenue concentration, though Healthcare is expanding most quickly as providers digitize patient records.
Deployment Model:
Infrastructure decisions track enterprise cloud migration trajectories and legacy system dependencies.
- Cloud:Native AWS and Azure detection architectures with API-driven telemetry ingestion. Brazilian retail banks abandon on-premises security stacks fastest, requiring cloud-native extended detection and response platforms.
- Hybrid:Mixed environments spanning legacy on-premises core systems and cloud-native workloads. Colombian banks running decades-old core banking infrastructure require this bridging configuration.
- On-Premises:Self-hosted security information and event management with localized data residency.
- Remote:Incident response delivered without physical presence, relying on endpoint agents and virtual private network access.
Cloud deployment holds the leading position, while Hybrid configurations are gaining share fastest among mid-market enterprises with partial modernization.
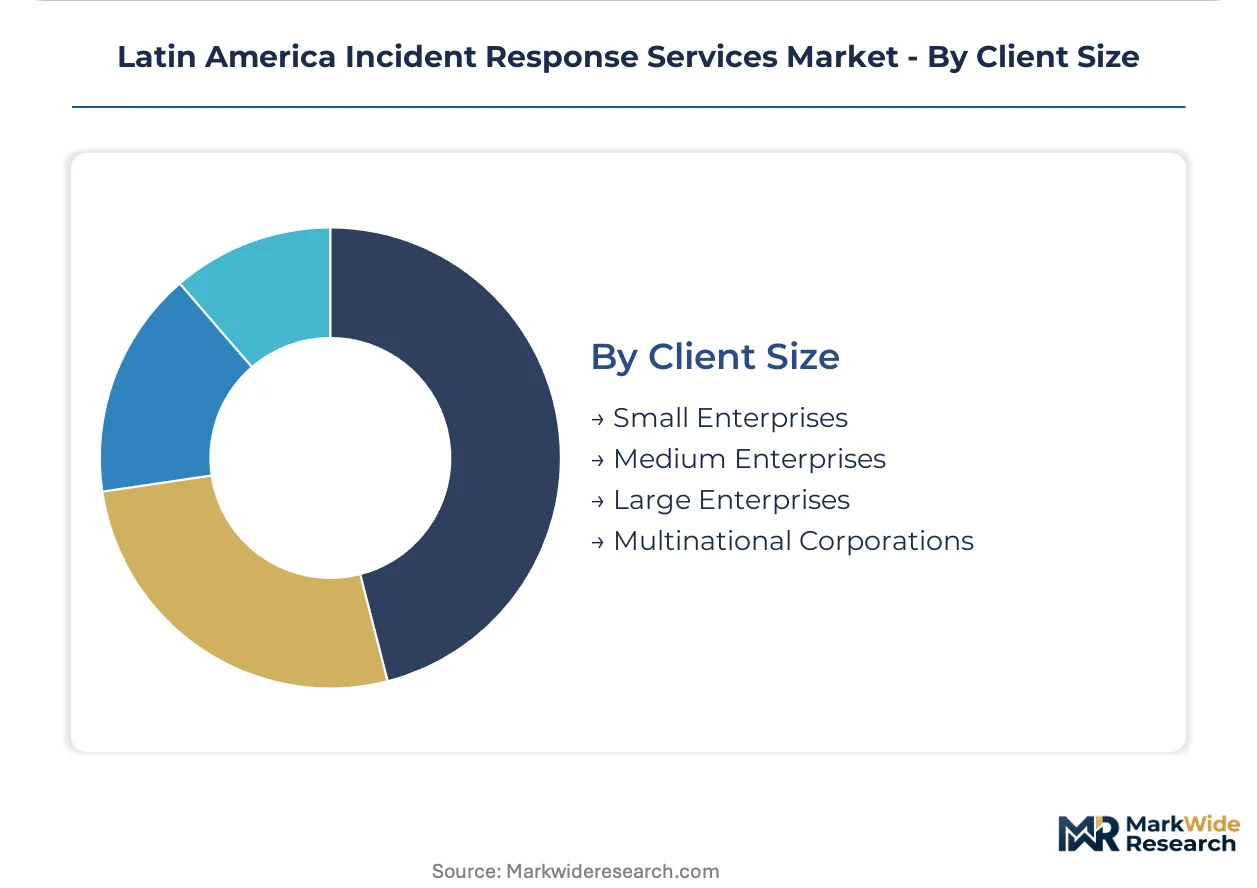
Client Size:
Resource availability and risk tolerance shape service tier selection across organizational scale.
- Large Enterprises:Major banks and energy operators with internal SOCs augmenting staff through co-managed detection services. Brazilian and Mexican financial institutions retain external specialists for forensic depth while maintaining internal tier-one response.
- Medium Enterprises:Regional insurers, logistics firms, and manufacturers with 500-5,000 employees. Chilean manufacturing clusters below 5,000 employees remain underserved by offerings optimized for larger financial institutions.
- Small Enterprises:Local healthcare providers and professional services firms with minimal internal security staffing.
- Multinational Corporations:Regional subsidiaries of global firms requiring harmonized response protocols across Latin American operations.
Large Enterprises consume the majority of current revenue, while Medium Enterprises show the steepest expansion trajectory as compliance mandates penetrate below top-tier institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANPD enforcement of Brazil's LGPD mandates documented breach response timelines, compelling financial institutions to retain external incident response capabilities with guaranteed service level agreements. Regional procurement patterns diverge sharply between cloud-native Brazilian retail banks and Colombian enterprises struggling with legacy core system integration.
Brazil
São Paulo's financial district drives concentrated demand for 24/7 security operations center coverage as regional banks migrate electronic medical records and core banking platforms to AWS and Azure environments. ANPD's data protection authority imposes penalties for inadequate breach documentation, forcing mid-market insurers to abandon informal security arrangements. Rio de Janeiro's energy operators require unified OT-IT incident response spanning operational technology networks and enterprise systems.
Mexico
CNBV's banking regulator mandates specialized cybersecurity provisions for digital payment platforms, creating compliance-driven procurement from Mexico City-based neobanks and payment processors. Fintech corridors in the capital negotiate all-inclusive cybersecurity subscriptions bundling detection, response, and regulatory reporting. Nuevo León's manufacturing clusters below 5,000 employees remain underserved by offerings optimized for larger financial institutions.
Argentina
CNDC standards for critical infrastructure operators require documented incident response playbooks with quarterly testing protocols, forcing energy and telecommunications providers toward audited managed security service providers. Buenos Aires concentrates scarce certified incident handlers who command premium pricing for ransomware recovery engagements. Córdoba's mid-sized utilities respond by consolidating vendor relationships to reduce compliance documentation burden.
Colombia
Bogotá's fintech corridor exhibits accelerating retainer-based procurement displacing hourly incident response engagements as insurers and asset managers demand fixed-fee arrangements. Decades-old core banking systems in Cali and Medellín resist API integration with modern extended detection and response platforms, forcing hybrid deployment configurations. Colombian banks running legacy SAP and Oracle environments struggle to normalize log feeds into cloud-native SIEM platforms.
Chile
Santiago anchors the region's forensic talent concentration alongside São Paulo and Buenos Aires, creating salary premiums that inflate service delivery costs across secondary markets. Manufacturing and logistics firms below 5,000 employees in Valparaíso and Concepción remain underserved by current managed detection offerings optimized for large financial institutions. Chilean enterprises with partial modernization drive fastest expansion in hybrid deployment configurations bridging legacy on-premises systems and cloud-native workloads.
Latin America Incident Response Services Market Competitive Landscape
Multinational consultancies and pure-play cybersecurity vendors split the market across retained incident response capabilities and technology-led detection platforms. Channel architecture fragments as telecom-anchored MSSPs compete for enterprise relationships against audit-firm cross-sell strategies. Three archetypes dominate: audit-trust leveraged consultancies, integrated platform vendors, and localized SOC operators. Competitive moves concentrate on geographic SOC expansion and retainer-based pricing model adoption.
Within the audit-trust tier, Deloitte Touche Tohmatsu Limited and Ernst & Young exemplify cross-sell strategies leveraging existing client relationships to embed retained IR capabilities. IBM Corporation occupies a position among technology-anchored providers with localized Spanish-Portuguese security operations. Palo Alto Networks represents the integrated platform archetype, sustaining positioning through consolidated endpoint and network detection architectures.
| Leading Market Players |
|---|
| Deloitte Touche Tohmatsu Limited |
| Ernst & Young |
| IBM Corporation |
| Palo Alto Networks |
| Check Point Software Technologies Ltd |
| Cisco Systems |
| Kaspersky Lab |
| BAE Systems |
| FireEye |
| Others |
Pricing and Supply Chain Analysis
Certified incident handler concentration in São Paulo, Buenos Aires, and Santiago directly determines where margin pools accumulate across Latin America's incident response value chain. Forensic talent scarcity in these three metropolitan clusters enables premium pricing for ransomware recovery engagements while compressing margins for providers forced to recruit remotely or subcontract across secondary markets.
Pricing Analysis
São Paulo-based investigative services command 40-60% premiums over equivalent offerings in Bogotá or Lima due to talent scarcity and LGPD-driven compliance urgency. Three-tier pricing structure across premium forensic retainers, standard managed detection subscriptions, and economy remote-response tiers stratifies the market. Pricing pressure stems from currency volatility as Argentine peso and Brazilian real fluctuations compress margins for multinational providers pricing in local currencies. Mid-market manufacturing firms below 5,000 employees exhibit highest price sensitivity, while Brazilian financial institutions facing ANPD enforcement deadlines show lowest.
Supply Chain Analysis
Export-control regimes restricting advanced threat-intelligence platforms and encryption technologies limit technology flows into the region, forcing providers to source through approved channels or develop localized alternatives. Supply concentrates in the United States, Israel, and Ireland for threat-intelligence feeds, endpoint detection engines, and security orchestration platforms. Raw material dependencies include cloud compute capacity from AWS and Azure, proprietary threat signatures from global intelligence networks, and GIAC-certified training pipelines. Single-source vulnerability runs through concentrated cloud infrastructure providers. Distribution runs through direct enterprise sales teams, telecom-anchored MSSP partnerships, and audit-firm cross-sell channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's incident response market operates as a capability-scarcity arena where certified forensic talent pools and localized SOC infrastructure represent the constraining assets. Procurement teams compete for the same limited pool of GIAC-credentialed incident handlers across São Paulo, Buenos Aires, and Santiago.
For Market Incumbents: Entrench position by acquiring boutique forensic shops in Córdoba and Medellín to preempt talent poaching from emerging competitors, while embedding ISO 27035 certification into all Argentine CNDC-facing engagements to raise compliance barriers against unqualified local integrators. For New Entrants and Emerging Players: Build out specialized OT-IT convergence capabilities for Brazilian energy and mining operators, a white-space segment where few regional providers have assembled unified response architectures. Target Chilean manufacturing clusters below 5,000 employees through channel partnerships with industrial automation distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier MSSPs that expanded too fast across Mexico City and Bogotá without securing certified talent pipelines. Long-term viability hinges on demonstrated client retention through retainer-based pricing transitions rather than hourly professional services. Watch for ANPD penalty announcements as inflection indicators accelerating procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Forensic Talent Acquisition | Secures scarce GIAC-certified handlers in Buenos Aires and Santiago before competitors lock employment contracts. |
| Cloud-Native SOC Expansion | Positions providers to capture Brazilian retail banks abandoning on-premises security stacks for AWS environments. |
| Retainer-Based Pricing Transition | Aligns revenue predictability with Colombian insurer demands for fixed-fee arrangements replacing hourly billing. |
| OT-IT Convergence Capability Build | Addresses Brazilian energy operator requirements spanning operational technology networks and enterprise IT systems. |
| CNBV Compliance Specialization | Captures Mexico City neobank procurement driven by banking regulator mandates for digital payment platform cybersecurity. |
Research Methodology
Operator-level perspectives from CISOs at Brazilian financial institutions, Mexican fintech compliance officers, Argentine critical infrastructure security directors, and Colombian healthcare IT managers anchored the qualitative base. These primary interviews combined with secondary validation from ANPD enforcement bulletins, CNBV regulatory circulars, CNDC standards documentation, AWS and Azure hyperscaler security service disclosures, and GIAC certification pipeline statistics. Bottom-up service provider revenue estimates triangulated against top-down addressable market calculations segmented by deployment model, client size tier, and vertical regulatory intensity.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting varying paces of LGPD enforcement stringency, ransomware attack frequency, and cloud migration completion rates. Segmentation dimensions modeled include service type, deployment architecture, organization scale, vertical compliance burden, and geographic talent availability. CAGRs derived from logistic adoption curves fitted to historical managed security service penetration patterns, cross-referenced with regulatory mandate implementation timelines and forensic certification graduation rates from regional training centers.
Stress conditions across Argentine peso volatility bands, Brazilian cloud infrastructure availability scenarios, and Mexico City talent recruitment cycle extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and threat actor targeting patterns. Material shifts in ANPD penalty structures or CNDC critical infrastructure designation expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Flood Protection Sandbags Market