
 Global Perimeter Protection Market | 2026-2036
Global Perimeter Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perimeter Protection Market Outlook
Edge AI inference is tilting perimeter protection toward on-device video analytics that reduce bandwidth and latency. Hikvision Digital Technology Co., Ltd. dominates manufacturing scale across camera and sensor production. Axis Communications AB differentiates through open-platform architecture that integrates third-party analytics. Dahua Technology Co., Ltd. extends its position via deep vertical integration into chip design and firmware development.
Perimeter protection encompasses physical and electronic systems engineered to detect, deter, and delay unauthorized intrusion across defined boundaries, typically incorporating detection zones measured in meters with response times under two seconds for critical infrastructure applications. These systems serve airports, power plants, military installations, and data centers where layered defense-in-depth strategies mandate continuous boundary monitoring. Video surveillance technology captures the largest margin pool as AI-enabled analytics transform cameras from passive recording devices into active threat detection nodes. Smart systems represent the fastest-expanding segment, fusing sensor fusion algorithms with automated response protocols that reduce false alarm rates below traditional threshold-based methods. Electromechanical solutions retain stability in mature industrial deployments where mechanical reliability outweighs digital upgrade costs.
The EU AI Act classifies biometric identification in perimeter systems as high-risk, mandating conformity assessments before CE marking and market entry. The US FAA and TSA impose stringent perimeter standards for airport critical security zones, while China's GB standards and NMPA cybersecurity rules shape product certification for domestic and export-bound equipment. Stakeholders must monitor divergence between EU algorithmic transparency mandates and US sector-specific performance standards as procurement specifications fragment across regulatory jurisdictions.
Market Dynamics
Edge AI inference is compressing response latency below 100 milliseconds for intrusion detection, forcing a hardware refresh cycle across critical infrastructure operators who previously relied on centralized processing architectures.
Growth Catalysts
- EU AI Act high-risk classification:Biometric identification mandates for perimeter systems are accelerating conformity assessment investments among European integrators seeking CE marking advantages.
- Data center construction:Hyperscale facility operators in the United States, Germany, and China are specifying sensor-fused fencing with sub-two-second alarm verification for campus boundaries.
- Sensor fusion algorithms:Multi-modal detection combining thermal, radar, and seismic inputs is reducing false alarm rates below threshold-based methods in airport and power plant deployments.
Market Restraints
- Semiconductor supply concentration:Specialized AI inference chips for edge cameras face fabrication bottlenecks concentrated in Taiwan and South Korea foundries.
- GDPR compliance friction:Video analytics with facial recognition capabilities trigger data protection impact assessments that extend European sales cycles by four to eight months.
- Mechanical reliability preference: Mature industrial sites in heavy manufacturing sectors resist digital upgrades where electromechanical sensors demonstrate decades of field-proven uptime.
Strategic Opportunities
- India smart city mandates:Urban infrastructure programs in Delhi, Mumbai, and Bangalore are creating procurement pipelines for integrated perimeter-video systems in transportation hubs.
- 5G private network convergence:Ultra-reliable low-latency communication is enabling wireless sensor density previously requiring fiber trenching at border and utility sites.
- US FAA perimeter modernization:Critical security zone standards for commercial airports are mandating layered detection that favors multi-technology integrators over single-product vendors.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for camera SoCs requires specialized talent pools concentrated in Shenzhen, Tel Aviv, and Silicon Valley that command premium compensation.
- Legacy analog integration complexity:Brownfield sites with coaxial infrastructure face signal compatibility hurdles when overlaying IP-based analytics without full cable replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perimeter Protection Market |
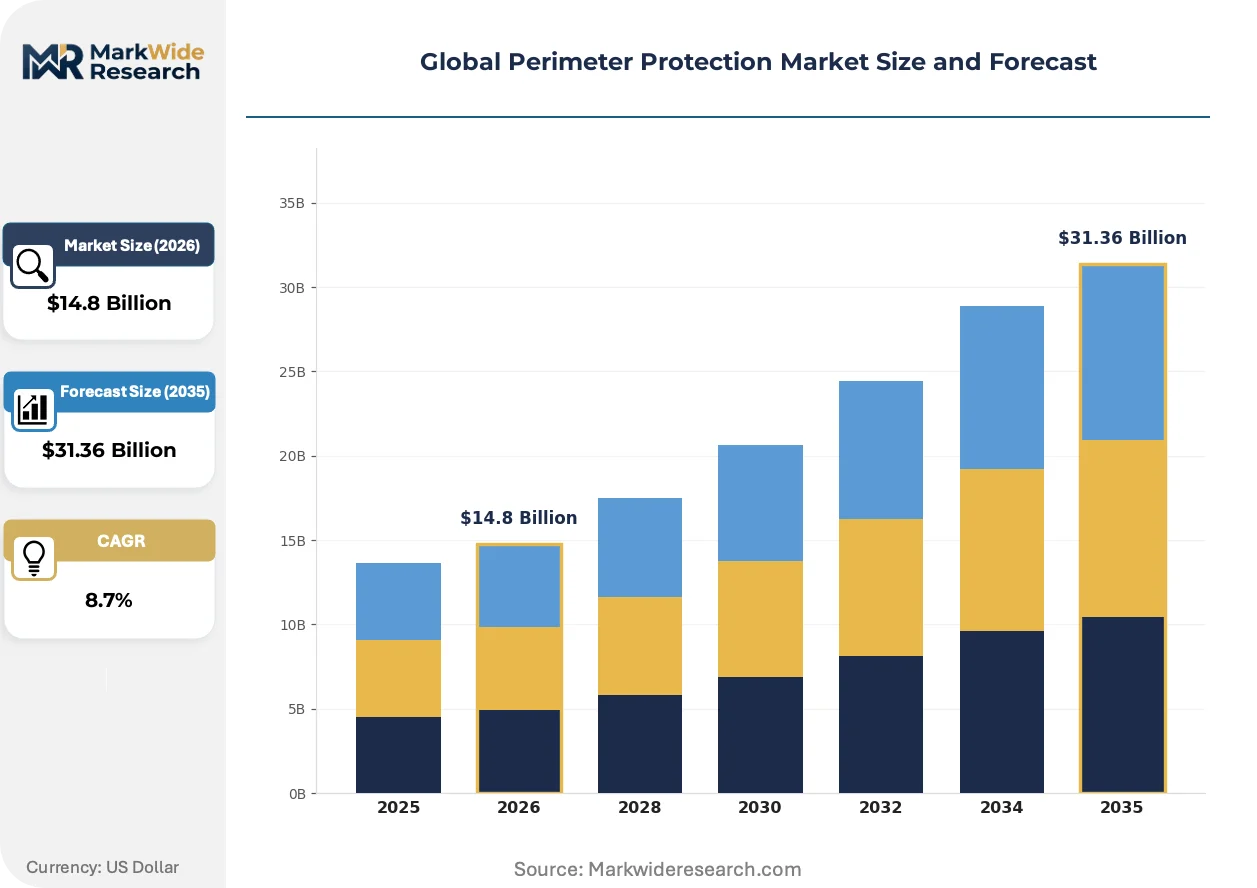
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fencing, Bollards, Barriers, Sensors Technology: Electromechanical, RFID, Video Surveillance, Smart Systems End User: Commercial, Industrial, Residential, Government Deployment: On-Site, Cloud-Based, Hybrid, Remote |
| Companies Covered | Honeywell International Inc., Dahua Technology Co., Ltd., Axis Communications AB, Hikvision Digital Technology Co., Ltd., Bosch Security Systems, Teledyne FLIR LLC, Johnson Controls Inc., Senstar Corporation, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perimeter Protection Market Strategic Shifts
Three forces are restructuring competitive advantage: on-device processing architectures, algorithmic accountability mandates, and procurement centralization among large facility operators.
Multi-spectral imaging sensors combining visible, near-infrared, and thermal bands are virtualizing the physical detection layer by collapsing separate camera networks into unified edge nodes. Data center and airport security directors are specifying these consolidated platforms for new construction projects. The technology is virtualizing hardware procurement decisions by reducing rack space, power draw, and maintenance contracts from three discrete systems to one.
The EU AI Act's high-risk system classification for biometric identification in perimeter applications is mandating conformity assessments before CE marking and market entry. European integrators must document algorithmic transparency, human oversight protocols, and accuracy testing across demographic groups. Video analytics vendors targeting Germany, France, and Netherlands deployments are restructuring product roadmaps to embed audit trails and explainability features by default.
Large critical infrastructure operators are consolidating vendor relationships from fragmented point-product purchases to integrated platform contracts spanning detection, analytics, and response orchestration. Energy utilities and transportation authorities in the United States and China are issuing multi-year framework agreements that favor suppliers with captive chip design and firmware development capabilities. This concentration is visible in procurement documentation from Texas grid operators and Shanghai port authority tenders that specify single-point accountability for system performance.
Global Perimeter Protection Market Segmentation
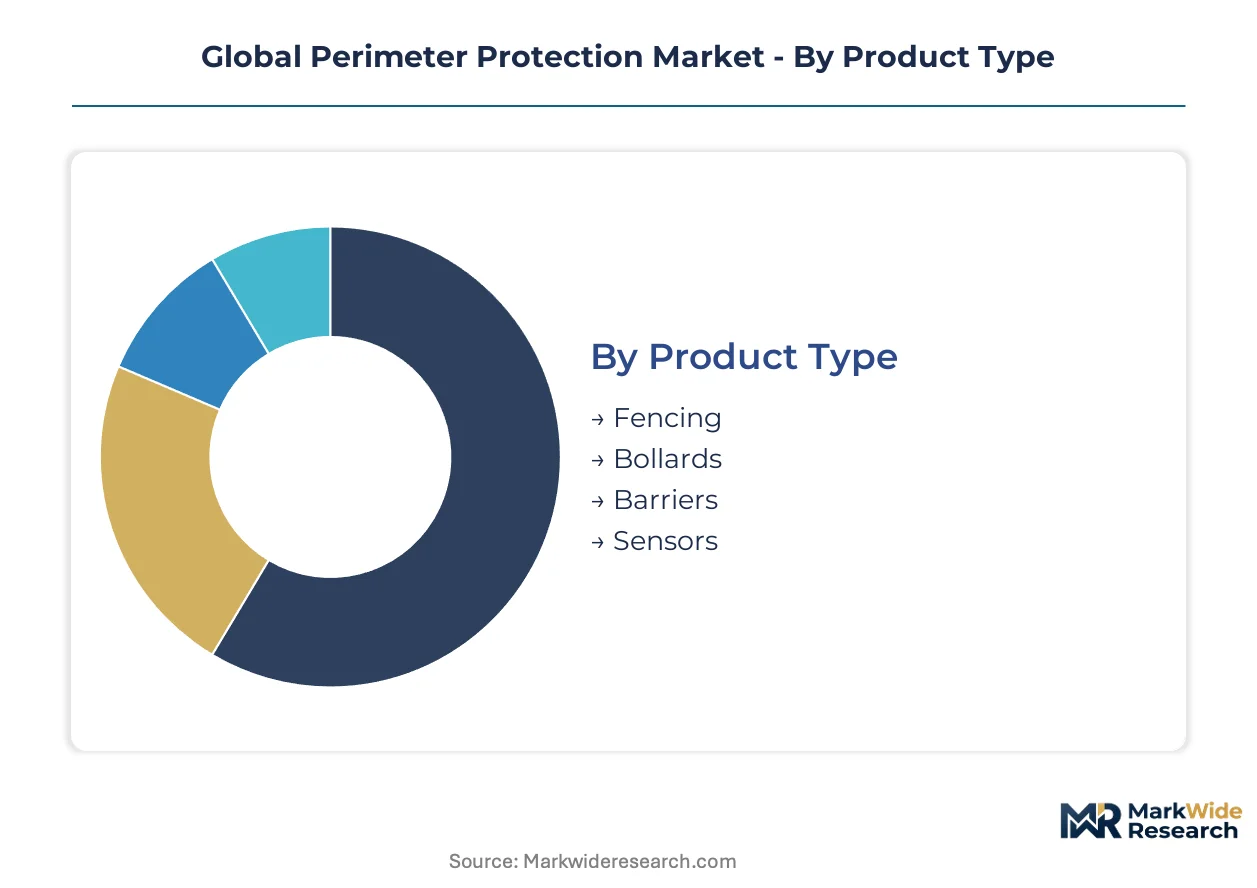
Perimeter protection procurement decisions fragment across four structural dimensions. Technology selection determines latency and false alarm performance. End-use context dictates regulatory compliance burden and integration complexity.
Product Type:
Mature physical barriers dominate installed base volume while sensor-integrated systems represent the emerging technology frontier.
- Fencing:Mesh, welded, and palisade configurations form the foundational detection layer, with sensor-embedded variants now specified for data center campuses in Germany and power substations in Texas. Demand concentrates where FAA and TSA mandate critical security zone compliance for layered boundary defense.
- Sensors:Seismic, magnetic, and fiber-optic cable systems detect vibration, pressure, and acoustic signatures across fence lines and buried perimeters. Airport operators in China and border agencies in the United States are driving procurement for multi-modal fusion with sub-two-second verification.
- Bollards:Crash-rated steel and concrete vehicle barriers protect building entries and plaza perimeters against ramming attacks.
- Barriers:Retractable road blockers and swing gates control vehicle access at commercial and government checkpoints.
Fencing retains volume leadership; sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy electromechanical installations from premium AI-enabled platforms requiring specialized engineering talent.
- Video Surveillance:AI-enabled cameras with on-device inference transform passive recording into active threat detection, processing thermal and visible spectrum inputs at the edge. Data center operators in Virginia and logistics hubs in Shanghai specify these for reduced bandwidth and sub-100-millisecond response latency.
- Smart Systems:Integrated platforms fuse sensor inputs with automated response protocols and centralized management dashboards. Energy utilities in California and port authorities in Rotterdam are consolidating procurement around these unified command interfaces.
- Electromechanical:Pressure mats, taut wire, and magnetic contact switches provide decades-proven reliability for heavy manufacturing sites resisting digital migration.
- RFID:Proximity card and tag-based access control manages personnel and vehicle entry at commercial and residential perimeters.
Video surveillance commands premium pricing tiers; smart systems are climbing the fastest as procurement centralizes around platform contracts.
End User:
Application context determines regulatory exposure and integration depth across facility types.
- Government:Military installations, border crossings, and critical infrastructure mandate layered defense-in-depth with classified certification requirements. Procurement in the United States flows through DHS and DoD frameworks; China's GB standards and NMPA cybersecurity rules shape domestic and export-bound equipment.
- Industrial:Power plants, refineries, and manufacturing facilities balance mechanical uptime against digital upgrade costs. European deployments face GDPR data protection impact assessments extending sales cycles when facial recognition capabilities are activated.
- Commercial:Corporate campuses, retail distribution centers, and logistics hubs prioritize cost-optimized detection with remote monitoring capabilities.
- Residential:Gated communities and high-net-worth properties demand aesthetic integration with smartphone-managed alert systems.
Government end-use retains specification authority; industrial applications are expanding most quickly as critical infrastructure operators refresh aging electromechanical installations.
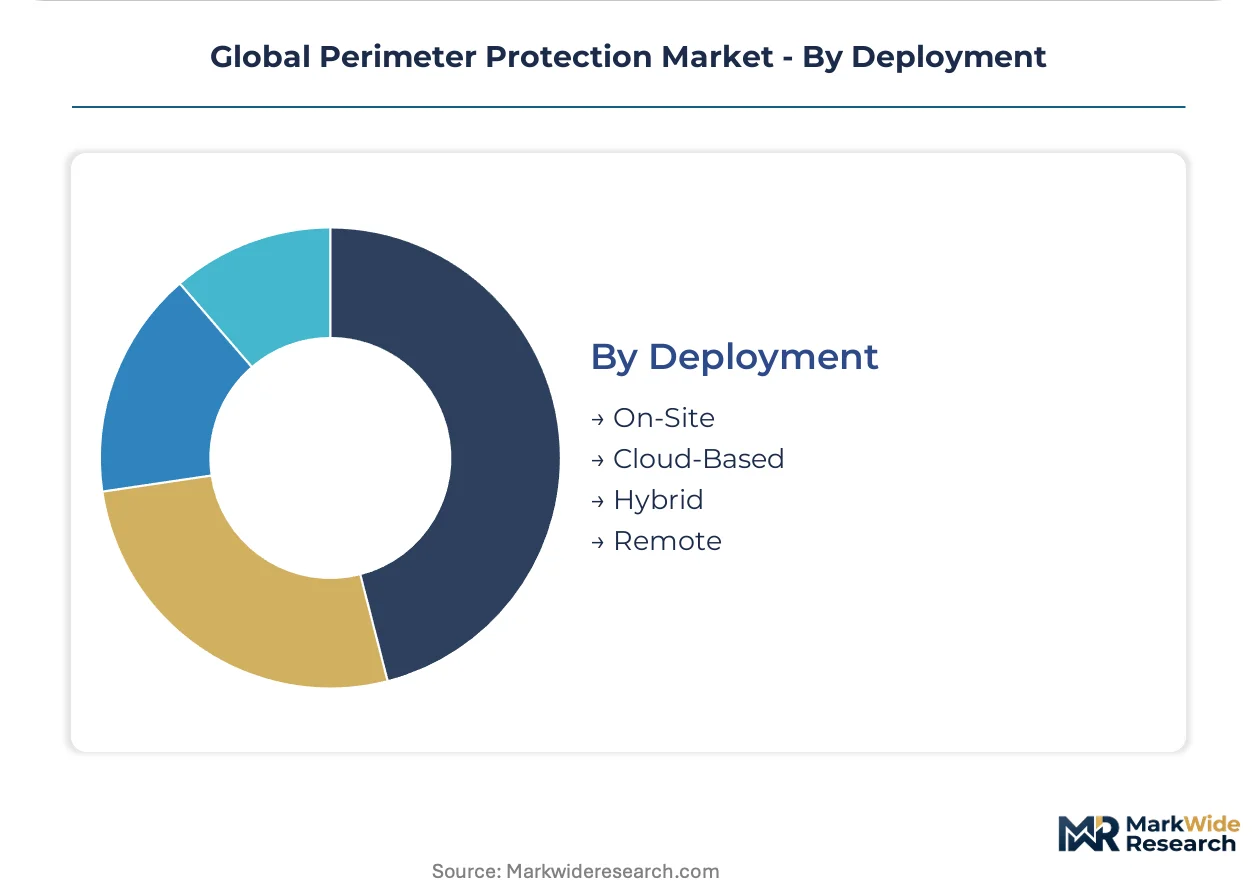
Deployment:
Customer type and facility scale drive architecture selection between capital-intensive on-site systems and operational-expense cloud models.
- On-Site:Localized processing and storage architectures satisfy air-gapped security requirements for military and nuclear facilities. Operators in these segments reject external network dependencies regardless of cloud convenience.
- Hybrid:Edge processing with cloud-based management dashboards balances latency performance against centralized oversight. This architecture dominates data center and airport deployments where facility operators demand local alarm verification with remote expert escalation.
- Cloud-Based:Fully managed video analytics and alert routing reduces capital burden for commercial and residential customers with limited security engineering staff.
- Remote:Satellite-linked monitoring extends perimeter protection to pipeline corridors and border segments beyond fiber infrastructure reach.
Hybrid deployment holds the dominant share trajectory; cloud-based models are gaining fastest among mid-market commercial customers prioritizing operational flexibility over capital ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in China supply integrated camera systems to data center operators in Germany and border agencies in the United States, while European integrators import edge AI chips from Taiwan and South Korea foundries to meet EU AI Act conformity timelines.
United States
Hyperscale data center construction in Virginia and Texas is driving procurement of sensor-fused fencing with sub-two-second alarm verification. FAA and TSA perimeter standards for commercial airports mandate layered detection systems that favor multi-technology integrators. Security directors at Dallas-Fort Worth International Airport and Northern Virginia data center clusters are specifying unified command platforms that collapse discrete camera networks into single edge nodes.
Germany
Industrial operators in North Rhine-Westphalia and Bavaria are refreshing aging electromechanical installations with privacy-certified video analytics. EU AI Act high-risk classification for biometric identification mandates conformity assessments before CE marking, extending procurement cycles for Frankfurt and Munich facility operators. Energy utilities in the Ruhr industrial corridor are consolidating vendor relationships around integrated platform contracts that bundle detection, analytics, and response orchestration.
China
GB standards and NMPA cybersecurity rules shape product certification for domestic and export-bound perimeter equipment. Port authorities in Shanghai and Shenzhen are issuing tenders specifying single-point accountability for system performance across detection and response layers. Smart city mandates in Beijing and Guangzhou are accelerating deployment of multi-spectral imaging sensors that combine visible, near-infrared, and thermal bands into unified edge nodes.
India
Urban infrastructure programs in Delhi, Mumbai, and Bangalore are creating procurement pipelines for integrated perimeter-video systems at transportation hubs. The country's national infrastructure regulator is aligning certification requirements with international standards to facilitate technology transfer from established suppliers. Industrial clusters in Maharashtra and Gujarat are piloting 5G private network convergence for wireless sensor density at utility sites previously requiring fiber trenching.
United Kingdom
Critical national infrastructure operators are specifying hybrid deployment architectures that balance edge processing with cloud-based management dashboards. London data center and logistics hub security directors demand local alarm verification with remote expert escalation capabilities. The national cybersecurity center is publishing procurement guidance that favors suppliers with demonstrable firmware development capabilities and captive chip design partnerships.
Global Perimeter Protection Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: scale-driven camera manufacturers with captive semiconductor partnerships, open-platform specialists integrating third-party analytics, and regional system integrators with deep vertical expertise. Strategic archetypes include full-stack hardware producers, software-defined platform vendors, and project-based security contractors. Dominant competitive moves span backward integration into chip design and multi-year framework agreements that lock in critical infrastructure operators.
Among scale-driven manufacturers, Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., and Axis Communications AB occupy positions that exemplify divergent strategic paths. Hikvision and Dahua represent integrated production architectures with upstream control over sensor fabrication, while Axis Communications AB exemplifies open-ecosystem positioning that accommodates heterogeneous analytics deployments. These three anchors collectively illustrate how procurement centralization among large facility operators is favoring suppliers with demonstrable firmware development capabilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Hikvision Digital Technology Co., Ltd. |
| Bosch Security Systems |
| Teledyne FLIR LLC |
| Johnson Controls Inc. |
| Senstar Corporation |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration for AI inference chips funnels margin capture downstream toward firmware-integrated platform vendors who command premium positioning in data center and airport procurement cycles. Edge camera SoC fabrication bottlenecks translate directly into pricing power for suppliers with captive semiconductor partnerships, while buyers without vertical integration face cost pass-through exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to AI-enabled video analytics with on-device inference and EU AI Act conformity certification, while economy tiers serve electromechanical sensor replacements in mature manufacturing sites. Price differentiation hinges on firmware customization depth and GDPR compliance documentation breadth. Pricing pressure stems from hyperscale facility operators consolidating vendor relationships into multi-year framework agreements that demand volume discounts. Government end-use segments exhibit lowest price sensitivity due to regulatory compliance mandates; residential buyers show highest sensitivity with preference for cloud-managed operational expense models.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment constrain chip fabrication capacity expansion for edge AI cameras. Supply concentrates in Taiwan and South Korea for specialized inference processors, with China dominating camera assembly and sensor module production. Raw material dependencies span silicon wafers, rare-earth magnets for seismic sensors, and fiber-optic cable sheathing compounds. Single-source vulnerability runs through Taiwan foundry capacity for sub-10nm AI accelerators. Distribution runs through regional system integrators who bundle detection hardware with installation and compliance certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering talent pools in Shenzhen, Tel Aviv, and Silicon Valley command premium compensation that constrains supplier scaling velocity. Firmware development capability gaps separate platform vendors from component assemblers across procurement cycles.
For Market Incumbents: Build firmware development moats through captive chip design partnerships that secure allocation priority at Taiwan foundries. Acquire regional system integrators in Germany and Texas to capture multi-year framework agreement flow from data center operators. Threat substitution from open-platform specialists demands defensive certification investments for EU AI Act conformity acceleration. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given limited incumbent platform penetration and price-sensitive procurement patterns. India's smart city transportation hub mandates offer white-space access with aligned certification pathways. Go-to-market execution should leverage 5G private network convergence as wireless sensor density enabler to bypass fiber trenching cost barriers. For Investors and Strategic Acquirers: Capital is best deployed toward firmware-integrated platform vendors with demonstrable EU AI Act conformity assessment completion and multi-year framework agreement backlog. Long-term viability across the analysis window favors suppliers with backward integration into edge AI chip design. Watch FAA perimeter modernization tender velocity as inflection signal for US critical infrastructure refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Design Acquisition | Captive semiconductor partnerships secure foundry allocation priority for Hikvision and Dahua. |
| EU AI Act Conformity Pre-certification | Early assessment completion accelerates CE marking timelines for German integrators. |
| 5G Private Network Sensor Integration | Ultra-reliable low-latency communication enables wireless density at Texas border sites. |
| Multi-spectral Imaging Platform Launch | Unified edge nodes collapse separate camera networks for Virginia data center operators. |
| Regional System Integrator Consolidation | Vertical acquisition captures multi-year framework agreement flow from Rotterdam port authority. |
Study Parameters
Desk research of customs trade databases, SEC infrastructure capex disclosures, and EU regulatory filing repositories preceded structured interviews with critical infrastructure security directors, perimeter systems integrators, semiconductor procurement leads, and airport compliance officers. Primary fieldwork captured procurement specification evolution across data center, airport, and power plant deployments. Secondary validation drew from FAA certification documentation, TSA critical security zone standards, and China's GB standards publications. Bottom-up unit economics triangulated against top-down facility construction spend estimates.
Forecast assumptions held fixed the EU AI Act high-risk classification timeline and US FAA perimeter modernization funding authorization while varying data center construction velocity across Virginia, Texas, and Shanghai clusters. Segmentation modeling spanned product type, technology tier, end-use vertical, and deployment architecture dimensions. CAGRs derived from facility operator capital expenditure trajectories and sensor refresh cycle compression rates. Industry-specific inputs included edge AI inference latency benchmarks and multi-modal sensor fusion algorithm adoption curves.
Practitioners should monitor Taiwan foundry capacity expansion announcements and US export control scope revisions for early signals of supply constraint easing. Forecasts reflect documented assumptions regarding hyperscale facility construction pipelines and regulatory compliance timeline adherence. Material shifts in EU AI Act enforcement intensity or FAA certification requirement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Infrastructure Protection Market