
 Italy Ransomware Protection Market | 2026-2036
Italy Ransomware Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Ransomware Protection Market Insights
The managed security services channel is reshaping how Italian enterprises procure ransomware defense, shifting from perpetual licenses to subscription-led engagements. IBM Corporation leverages its Security Command Center in Milan to anchor high-touch enterprise relationships across banking and public administration. Leonardo S.p.A. competes through sovereign-cloud positioning that aligns with Italy's data residency requirements. Cisco Systems Inc extends its distributor network to reach mid-market manufacturing clients in the Emilia-Romagna industrial belt.
Ransomware protection encompasses endpoint detection, network segmentation, backup isolation, and cryptographic containment technologies engineered to halt unauthorized encryption propagation and restore operational continuity. Solutions integrate behavioral heuristics, threat intelligence feeds, and immutable snapshot architectures with sub-minute recovery objectives. Software Solutions dominates current spending as organizations prioritize AI-driven detection engines over hardware appliances. Cloud-Based deployment is expanding fastest among SMBs seeking elastic capacity without capital commitment. Incident Response commands premium pricing where retainers include guaranteed breach containment within four hours.
AGID, the national cybersecurity agency, mandates incident reporting timelines and baseline controls for critical infrastructure operators under the NIS2 transposition. The EU AI Act and GDPR jointly shape product development, requiring explainability in automated threat response and strict data processing governance. Stakeholders must monitor how Italy's Golden Power mechanism applies to foreign cybersecurity vendors serving defense and energy sectors, as intervention thresholds tighten.
Market Dynamics
AGID's NIS2 transposition is compressing procurement cycles across Italian critical infrastructure, forcing operators to consolidate vendor relationships under unified security frameworks rather than point-solution accumulation.
Growth Catalysts
- NIS2 Compliance Deadlines:Italy's transposition of the EU directive mandates baseline controls and incident reporting timelines for energy, transport, and healthcare operators. CISOs are accelerating ransomware protection budgets to meet enforcement windows.
- Financial Sector Procurement:Italian banks under ECB supervision are expanding cybersecurity spend as operational resilience requirements tighten. Basel III operational risk frameworks treat ransomware exposure as a capital adequacy input.
- AI-Driven Detection Engines:Behavioral heuristics and machine learning classifiers are displacing signature-based endpoint protection. Lombardy-based insurers are piloting autonomous response systems with sub-minute containment objectives.
Market Restraints
- Skills Concentration in Northern Italy:Milan and Turin capture the majority of certified incident responders. Central and southern regions face 40-60 day hiring timelines for SOC analysts.
- Sovereign-Cloud Certification Costs:AGID's CSP qualification process requires extensive documentation and third-party audit cycles. Mid-market vendors struggle to absorb compliance overhead without pricing out SMB segments.
- Hardware Appliance Depreciation:On-premise sandboxing and network TAP infrastructure faces accelerated obsolescence as cloud-native alternatives commoditize detection capacity.
Strategic Opportunities
- Sicily and Calabria Manufacturing Bases:Southern industrial corridors remain underpenetrated by managed security services. Automotive suppliers in these regions operate with minimal ransomware coverage relative to northern peers.
- EU AI Act Convergence:Explainability requirements for automated threat response create product differentiation openings. Vendors documenting decision audit trails gain procurement preference in public administration tenders.
- Immutable Backup Integration:Air-gapped snapshot architectures are converging with disaster recovery orchestration platforms. Healthcare providers in Emilia-Romagna are consolidating backup and ransomware defense procurement.
Industry Challenges
- Incident Responder Certification Bottlenecks:ENISA's European Cybersecurity Skills Framework lacks Italian-language training pathways. Domestic talent pipelines cannot match SOC expansion rates.
- Legacy OT Integration Complexity:Energy and water utilities operate decades-old SCADA systems with limited API exposure. Ransomware protection vendors must deploy passive network monitoring rather than agent-based endpoint coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Ransomware Protection Market |
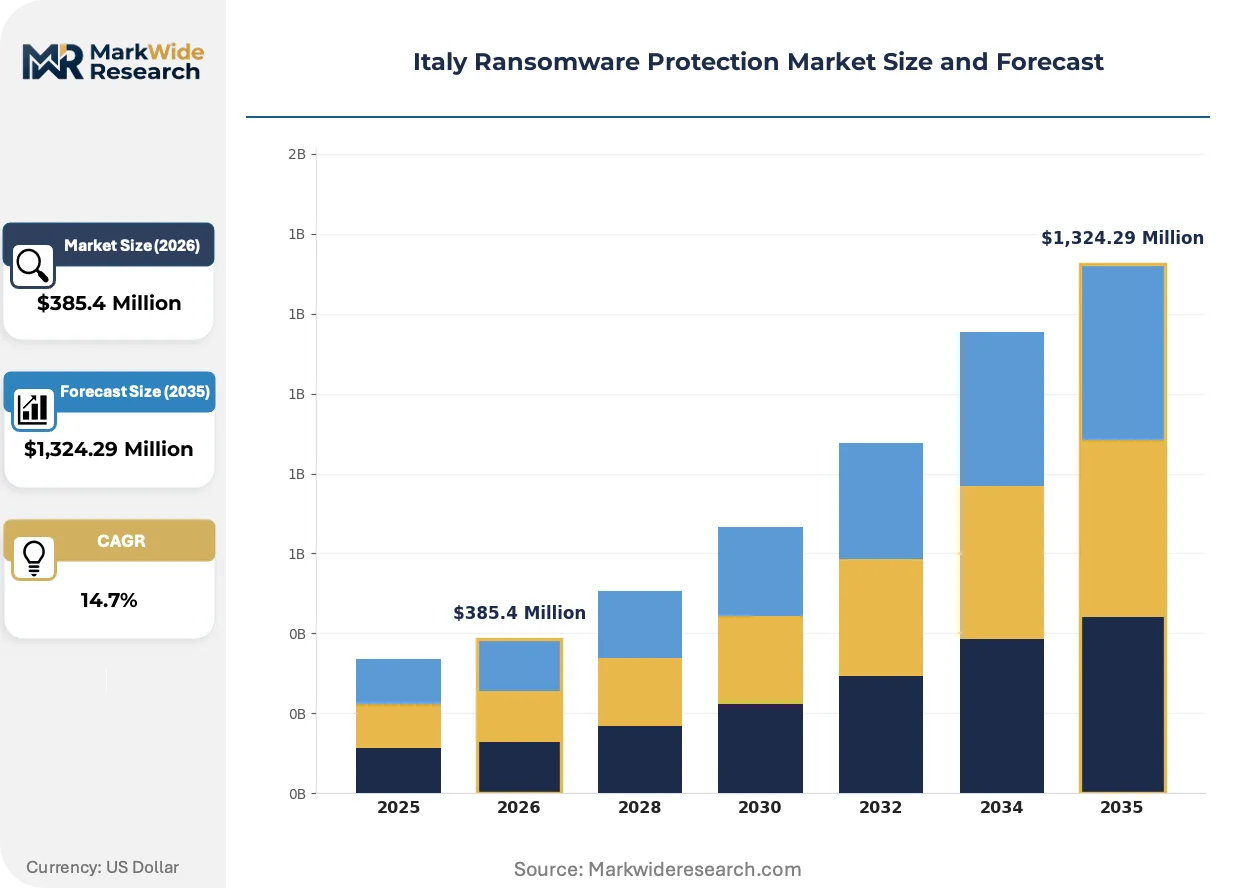
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,324.29 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Solutions, Software Solutions, Managed Security Services, Incident Response Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: SMBs, Large Enterprises, Government Agencies, Educational Institutions Industry Vertical: Finance, Healthcare, Retail, Manufacturing |
| Companies Covered | IBM Corporation, Cisco Systems Inc, Trend Micro Incorporated, Palo Alto Networks, Fortinet Inc., Leonardo S.p.A., Accenture Italia, Engineering Ingegneria Informatica S.p.A., Fastweb S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Ransomware Protection Market Trends and Innovations
Italian ransomware defense is pivoting from perimeter hardening toward resilience architectures that assume breach and prioritize recovery velocity over prevention certainty.
Extended detection and response (XDR) platforms are hybridizing telemetry streams from endpoints, cloud workloads, and identity systems into unified correlation engines. Mid-market manufacturers in the Veneto region are adopting these consolidated stacks to reduce agent sprawl and license fragmentation. The compression of best-of-breed point solutions into integrated platforms is narrowing vendor selection criteria toward API breadth and managed service attach rates.
AGID's incident reporting mandates under the NIS2 transposition are forcing operational technology operators to instrument previously air-gapped environments. Energy distributors must now document ransomware containment procedures and submit timeline disclosures within 24-72 hour windows. This regulatory pressure is accelerating passive network monitoring deployments where active agents risk production system stability.
Subscription consumption models are displacing perpetual license procurement across Lombardy and Piedmont financial services. Buyers are unbundling implementation and managed response from software licenses, treating ransomware protection as an operational expenditure rather than capital deployment. This shift favors vendors with Milan-based security operations centers capable of four-hour containment guarantees under retainer structures.
Italy Ransomware Protection Market Segmentation
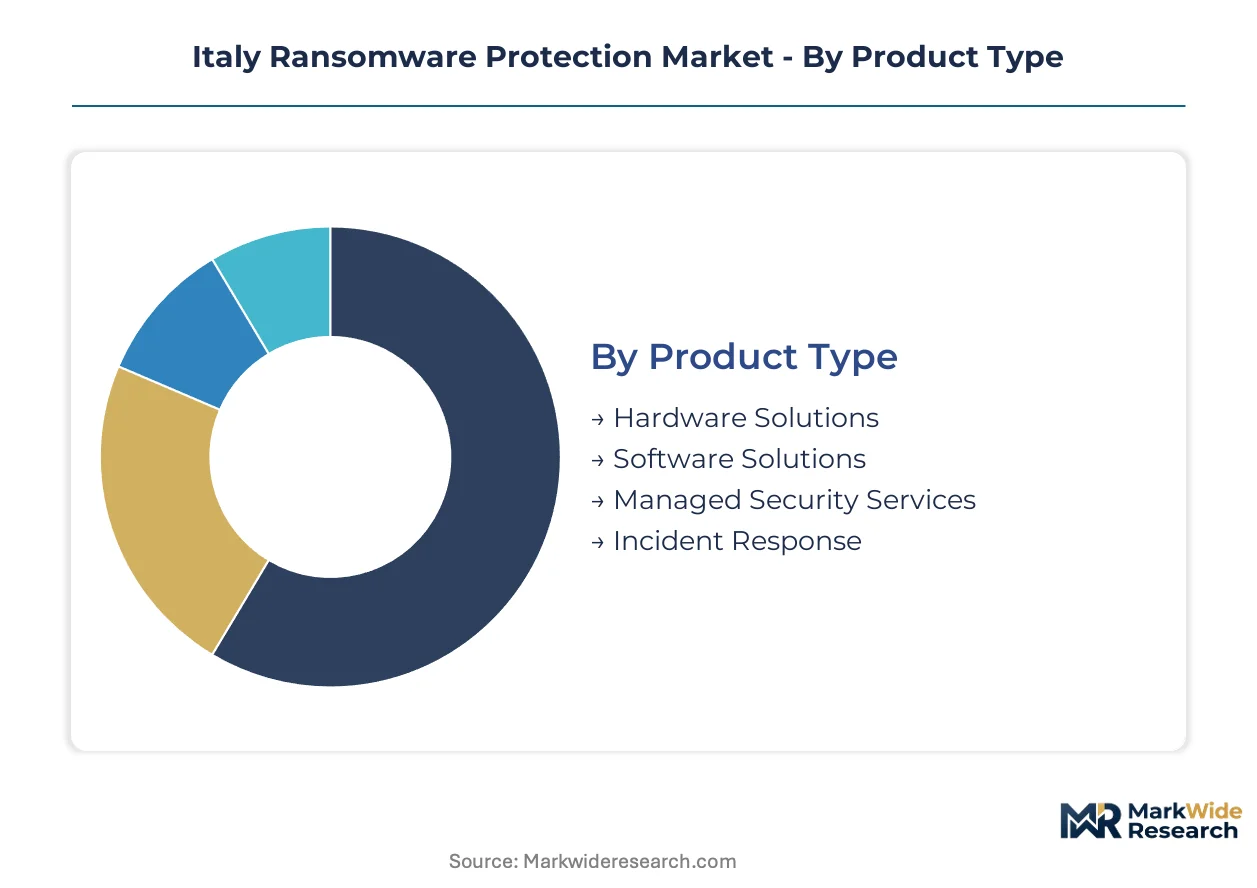
Italian ransomware protection procurement fragments across four critical dimensions. Each segmentation layer reveals distinct pricing power, deployment complexity, and service attach rate dynamics that shape vendor go-to-market strategies.
Product Type:
After-sales service intensity varies dramatically across product categories, with managed engagements commanding recurring revenue multiples that perpetual licenses cannot match.
- Software Solutions:AI-driven detection engines with behavioral heuristics and threat intelligence integration dominate Lombardy banking procurement. AGID compliance mandates accelerate replacement of signature-based endpoint protection across critical infrastructure operators.
- Managed Security Services:Subscription-led engagements bundle 24/7 SOC monitoring with guaranteed four-hour containment SLAs. Milan-based financial institutions favor these retainer structures over capital-intensive appliance procurement.
- Incident Response:Boutique retainers with breach containment guarantees command premium pricing in healthcare and energy verticals.
- Hardware Solutions:On-premise sandboxing appliances face accelerated obsolescence as cloud-native detection commoditizes capacity.
Software Solutions holds the largest share; momentum sits with Managed Security Services.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from operational expenditure models favored by mid-market buyers.
- Cloud-Based:Elastic capacity without capital commitment attracts SMBs in central and southern Italy where IT budgets constrain upfront investment. AGID's sovereign-cloud certification requirements add compliance overhead that mid-market vendors struggle to absorb.
- Hybrid:Workload-sensitive architectures split sensitive data processing on-premise while leveraging cloud analytics for threat correlation. Large manufacturers in Emilia-Romagna deploy these configurations to balance latency requirements with scalability.
- Multi-Cloud:Redundancy across AWS, Azure, and sovereign Italian cloud providers addresses data residency requirements for defense and energy sector procurement.
- On-Premises:Air-gapped deployments persist in OT environments where active agents risk SCADA system stability.
Hybrid configurations capture the most complex procurement; Cloud-Based deployment is expanding most quickly among new buyers.
End User:
Customer type determines solution complexity, with enterprise buyers demanding API breadth while SMBs prioritize managed service attach rates.
- Large Enterprises:Unified security frameworks consolidate point-solution accumulation under XDR platforms with cross-domain telemetry correlation. Turin-based automotive groups and Milan banking conglomerates drive this segment.
- SMBs:License fragmentation and agent sprawl push mid-market manufacturers toward consolidated stacks with single-pane management. Veneto region adoption rates lag northern peers by 18-24 months.
- Government Agencies:Public administration tenders require explainability documentation for automated threat response under EU AI Act convergence.
- Educational Institutions:Budget constraints favor open-source detection layers with commercial incident response retainers for high-severity events.
Large Enterprises dominate absolute spending; SMBs represent the steepest expansion trajectory as managed services democratize enterprise-grade protection.
Industry Vertical:
Application-specific risk profiles shape solution architecture, with regulated verticals commanding compliance premiums and specialized integration requirements.
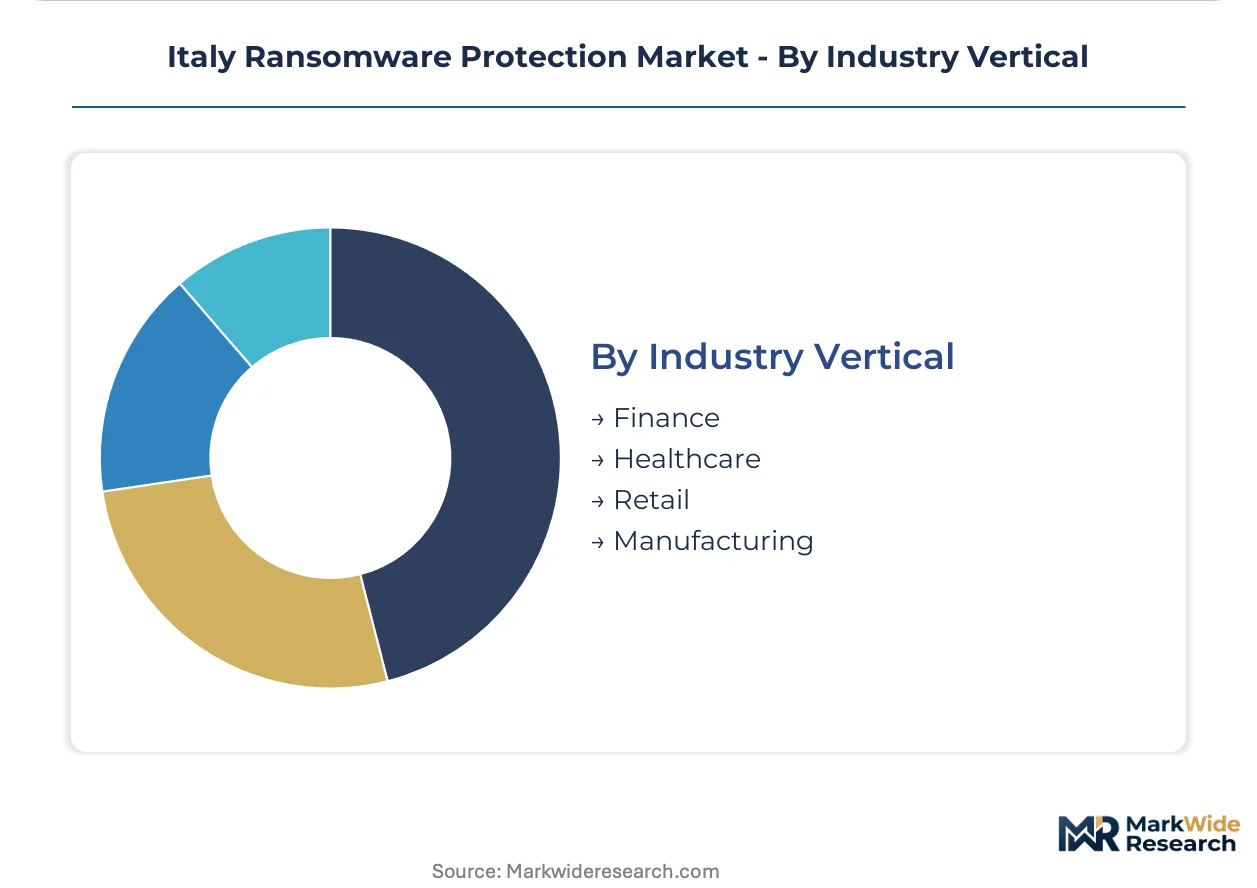
- Finance:ECB supervision and Basel III operational risk frameworks treat ransomware exposure as capital adequacy inputs. Italian banks under this regime expand cybersecurity procurement fastest.
- Healthcare:Immutable backup integration with disaster recovery orchestration consolidates procurement in Emilia-Romagna provider networks. GDPR processing governance adds documentation burdens.
- Manufacturing:Southern industrial corridors in Sicily and Calabria remain underpenetrated relative to northern peers, creating whitespace for distributor network expansion.
- Retail:Seasonal revenue concentration drives demand for sub-minute recovery objectives during peak transaction periods.
Finance commands the highest per-seat pricing; Manufacturing offers the deepest penetration runway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AGID, Italy's national cybersecurity agency, anchors procurement cycles across the peninsula through NIS2 transposition mandates that compress vendor selection timelines for critical infrastructure operators.
Lombardy
Milan's financial services cluster drives premium-tier ransomware protection procurement, with ECB-supervised banks expanding cybersecurity budgets under Basel III operational risk frameworks. AGID compliance deadlines accelerate replacement of legacy endpoint protection across the region's banking conglomerates. The Milan Security Command Center anchors high-touch enterprise relationships for managed security services with four-hour containment guarantees.
Piedmont
Turin-based automotive groups demand unified security frameworks that consolidate point-solution accumulation under XDR platforms with cross-domain telemetry correlation. The EU AI Act shapes product requirements for explainability in automated threat response systems deployed across manufacturing operations. Industrial automation suppliers in the province operate with elevated ransomware exposure due to OT-IT convergence.
Emilia-Romagna
Healthcare providers in this northern region consolidate backup and ransomware defense procurement around immutable snapshot architectures with disaster recovery orchestration. GDPR processing governance adds documentation burdens for patient data protection. Manufacturing clients in the industrial belt extend distributor network reach for mid-market coverage.
Veneto
Mid-market manufacturers adopt consolidated security stacks to reduce agent sprawl and license fragmentation, though adoption rates lag northern peers by 18-24 months. Skills concentration in nearby Milan and Turin creates 40-60 day hiring timelines for SOC analysts. Cloud-based deployment expands fastest among SMBs seeking elastic capacity without capital commitment.
Sicily and Calabria
Southern industrial corridors remain underpenetrated by managed security services relative to northern peers, creating whitespace for distributor expansion. Automotive suppliers operate with minimal ransomware coverage amid budget constraints and talent scarcity. Sovereign-cloud certification costs under AGID's CSP qualification process price mid-market vendors out of SMB segments.
Italy Ransomware Protection Market Competitive Landscape
Multinational technology conglomerates and domestic sovereign-cloud specialists split the market between scale-driven platform consolidation and data residency compliance. The vendor base concentrates around three strategic archetypes: global cybersecurity platforms with Milan-based security operations centers, Italian system integrators with public administration relationships, and telecommunications carriers extending into managed security services. Competitive moves center on M&A activity absorbing boutique incident response firms and strategic partnerships aligning foreign technology with domestic compliance expertise.
Within the multinational platform tier, IBM Corporation and Cisco Systems Inc occupy anchor positions exemplifying high-touch enterprise engagement models. Leonardo S.p.A. represents the sovereign-cloud specialist archetype, aligning product positioning with Italy's data residency requirements for defense and energy sector procurement. These three companies illustrate the competitive tension between global scale advantages and domestic regulatory alignment.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems Inc |
| Trend Micro Incorporated |
| Palo Alto Networks |
| Fortinet Inc. |
| Leonardo S.p.A. |
| Accenture Italia |
| Engineering Ingegneria Informatica S.p.A. |
| Fastweb S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Milan's security operations hub concentrates managed security services capacity, compressing pricing power for four-hour containment guarantees while southern regions absorb 40-60 day hiring premiums that inflate SOC analyst costs. AGID's sovereign-cloud certification requirements add compliance overhead that mid-market vendors struggle to pass through without losing SMB segments, creating geographic price stratification across the peninsula.
Pricing Analysis
Lombardy commands 20-35% premiums over Sicily and Calabria for equivalent managed security services, reflecting skills concentration and proximity to Milan-based SOCs. Subscription-led engagements with four-hour containment SLAs dominate financial services procurement, while SMBs in central and southern Italy favor cloud-based deployment to avoid capital commitment. Pricing pressure stems from cloud-native detection commoditizing capacity previously delivered through hardware appliances. Healthcare and energy verticals show lowest price sensitivity due to breach containment guarantees, while mid-market manufacturing remains most cost-constrained.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain mid-tier vendor working capital as distributor networks expand into underpenetrated southern corridors. Technology sourcing concentrates in the United States, Ireland, and Germany for threat intelligence feeds and AI detection engines, with domestic system integrators providing compliance overlay. Component dependencies include behavioral analytics libraries, immutable storage architectures, and ENISA-certified training pathways. Single-source vulnerability runs through Milan-centric SOC analyst talent pools. Distribution runs through telecommunications carriers and specialized cybersecurity distributors reaching Emilia-Romagna manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified incident responder scarcity across central and southern Italy constrains SOC expansion rates, compressing service attach rates for vendors without Milan-Turin talent access and inflating recruitment costs for mid-market entrants.
For Market Incumbents: Pre-empt boutique incident response firm absorption through targeted acquisition of ENISA-certified training providers, securing talent pipelines that emerging players cannot replicate. Consolidate distributor relationships in Veneto and Emilia-Romagna before cloud-native competitors commoditize detection capacity. AGID's tightening Golden Power thresholds on foreign vendors serving defense and energy sectors favor domestic compliance expertise as a defensive moat. For New Entrants and Emerging Players: Mid-market automotive suppliers in Sicily and Calabria represent the most penetrable entry point, operating with minimal ransomware coverage relative to northern peers and facing 40-60 day SOC analyst hiring timelines that favor outsourced managed services. Sovereign-cloud certification gaps among incumbent mid-market vendors create pricing whitespace for AGID-qualified entrants. Channel partnerships with regional telecommunications carriers bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed security services providers with Milan-based SOCs and four-hour containment guarantees, anchoring valuation premiums over perpetual-license software vendors. Long-term viability hinges on AI-driven detection engine differentiation and EU AI Act explainability documentation. Acquisition targets should demonstrate ENISA certification pathways and public administration tender track records. The signal to watch is AGID enforcement action against non-compliant NIS2 operators, which would accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Absorbing boutique incident response firms secures ENISA-certified talent pipelines against SOC expansion constraints. |
| Strategic Partnership | Aligning foreign AI detection engines with Leonardo's sovereign-cloud positioning satisfies defense sector Golden Power requirements. |
| Geographic Expansion | Distributor network extension into Sicily and Calabria manufacturing corridors captures underpenetrated mid-market demand. |
| Platform Integration | Consolidating XDR telemetry with immutable backup architectures addresses healthcare procurement convergence in Emilia-Romagna. |
| Product Launch | EU AI Act-compliant explainability documentation unlocks public administration tenders requiring automated response audit trails. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of AGID compliance directives, ECB operational risk frameworks, and ENISA cybersecurity skills documentation. Primary interviews engaged CISOs at Lombardy financial institutions, procurement leads at Emilia-Romagna healthcare networks, SOC directors in Milan and Turin, channel partners serving Veneto manufacturing, and AGID policy officials. Secondary validation drew from NIS2 transposition texts, EU AI Act regulatory filings, and Basel III operational risk guidance. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Forecast inputs include deployment model adoption curves, compliance deadline enforcement intensity, and AI detection engine displacement rates across the projection horizon. Segmentation dimensions encompass product type, deployment architecture, organization size tier, industry vertical, and regional adoption pattern. CAGRs derive from weighted scenario analysis across enforcement, technology substitution, and macroeconomic sensitivity cases. Inputs specific to this market include AGID sovereign-cloud certification penetration and ENISA training pathway completion rates.
Macroeconomic conditions sit as an overlay; deviation in ECB interest rate trajectories or Italian public sector IT budget allocations would shift the trajectory. Forecasts reflect documented assumptions around NIS2 enforcement timing and AI Act implementation sequencing. Regulatory acceleration, skills pipeline expansion, or cloud-native detection commoditization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market