
 Incident Response Services Market | 2026-2036
Incident Response Services Market Size, Share, and Industry Trends Forecast 2026-2036
Incident Response Services Market Intelligence
Capital-intensity divergence between boutique forensics shops and platform-scale providers is collapsing as cloud-native detection infrastructure commoditizes elite-tier tooling. CrowdStrike Holdings, Inc. leverages its endpoint telemetry graph to anchor premium managed-detection pricing. IBM Corporation sustains enterprise trust through decades of security consulting relationships and hybrid-cloud integration depth. Check Point Software Technologies Ltd. competes on network-layer containment speed, differentiating itself from endpoint-centric rivals.
Incident Response Services encompass the technical and procedural capabilities required to detect, contain, eradicate, and recover from cybersecurity breaches, typically delivered through 24/7 security operations centers with mean-time-to-containment targets under one hour for critical assets. The primary purpose is minimizing business disruption and data exfiltration while preserving forensic integrity for regulatory reporting and potential litigation. Managed Services currently occupies the largest revenue pool as organizations outsource around-the-clock monitoring rather than building in-house SOCs. Cloud-based deployment is expanding fastest among mid-market adopters seeking elastic capacity without capital expenditure. Healthcare as an industry vertical carries outsized margin potential due to HIPAA breach-notification complexity and ransomware targeting of patient records.
FDA, SEC, and HIPAA collectively impose breach-notification timelines and documentation standards that directly dictate incident response service specifications for regulated entities. The EU NIS2 Directive extends similar obligations across European critical infrastructure operators, creating cross-border demand for providers with multi-jurisdictional compliance expertise. Stakeholders must evaluate whether their retained incident response provider maintains active investigator certifications and nation-state threat intelligence feeds that match their specific regulatory exposure profile.
Market Dynamics
Retainer-based contracting is compressing procurement cycles for incident response services as financial services and critical infrastructure operators lock in guaranteed response capacity ahead of tightening breach-notification deadlines imposed by the SEC and EU NIS2 Directive.
Growth Catalysts
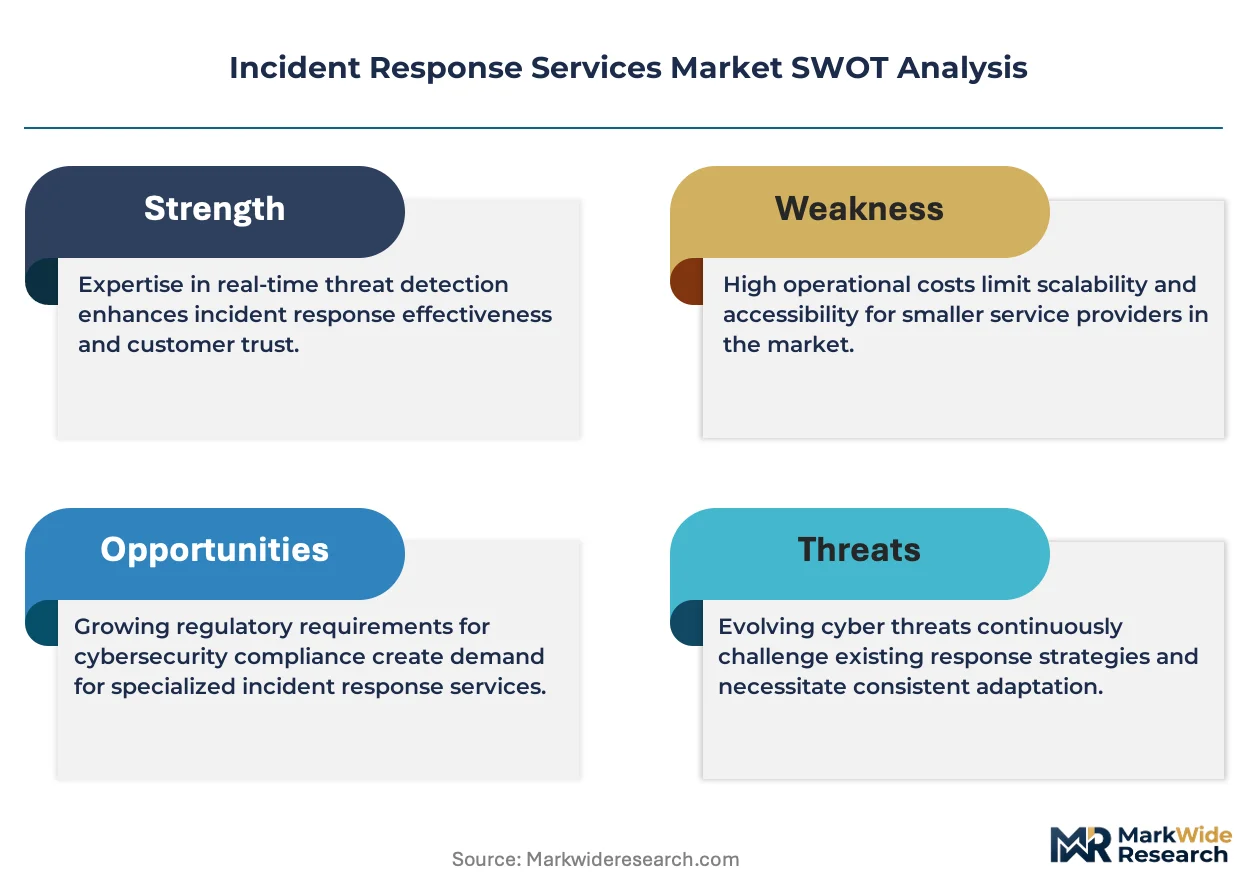
- EU NIS2 Directive:European critical infrastructure operators must secure 24/7 incident response capabilities with documented containment procedures, expanding compliance-driven procurement across energy, transport, and healthcare sectors.
- Ransomware targeting:Patient record systems in healthcare face escalating attack frequency, forcing HIPAA-covered entities to outsource forensic containment rather than risk multi-million dollar breach penalties.
- Cloud-native SOCs:Mid-market organizations deploy elastic security operations capacity without capital expenditure, accelerating subscription-based incident response adoption.
Market Restraints
- Forensic talent scarcity:Active investigator certifications with nation-state threat intelligence access concentrate among a limited pool of specialists, constraining provider scaling.
- Multi-jurisdictional complexity:Cross-border breach response requires simultaneous compliance with FDA medical device rules, SEC disclosure timelines, and HIPAA notification standards, fragmenting service standardization.
- Endpoint telemetry commoditization:Cloud-native detection infrastructure erodes pricing power for elite-tier forensic tooling, compressing margins for boutique forensics shops.
Strategic Opportunities
- Healthcare vertical expansion:HIPAA breach-notification complexity and ransomware targeting of patient records create outsized margin potential for specialized response retainers.
- Hybrid-cloud integration:Enterprises with on-premise legacy systems and multi-cloud environments require unified incident response workflows, favoring providers with consulting depth.
- SEC cybersecurity rules:Mandatory four-day disclosure windows for material breaches force accelerated procurement of pre-positioned response capacity among publicly traded firms.
Industry Challenges
- Mean-time-to-containment execution:Achieving sub-one-hour response targets for critical assets demands 24/7 staffing and automated orchestration that strains operational resourcing.
- Forensic integrity preservation:Containing breaches while maintaining chain-of-custody documentation for regulatory reporting and litigation requires specialized investigator training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incident Response Services Market |
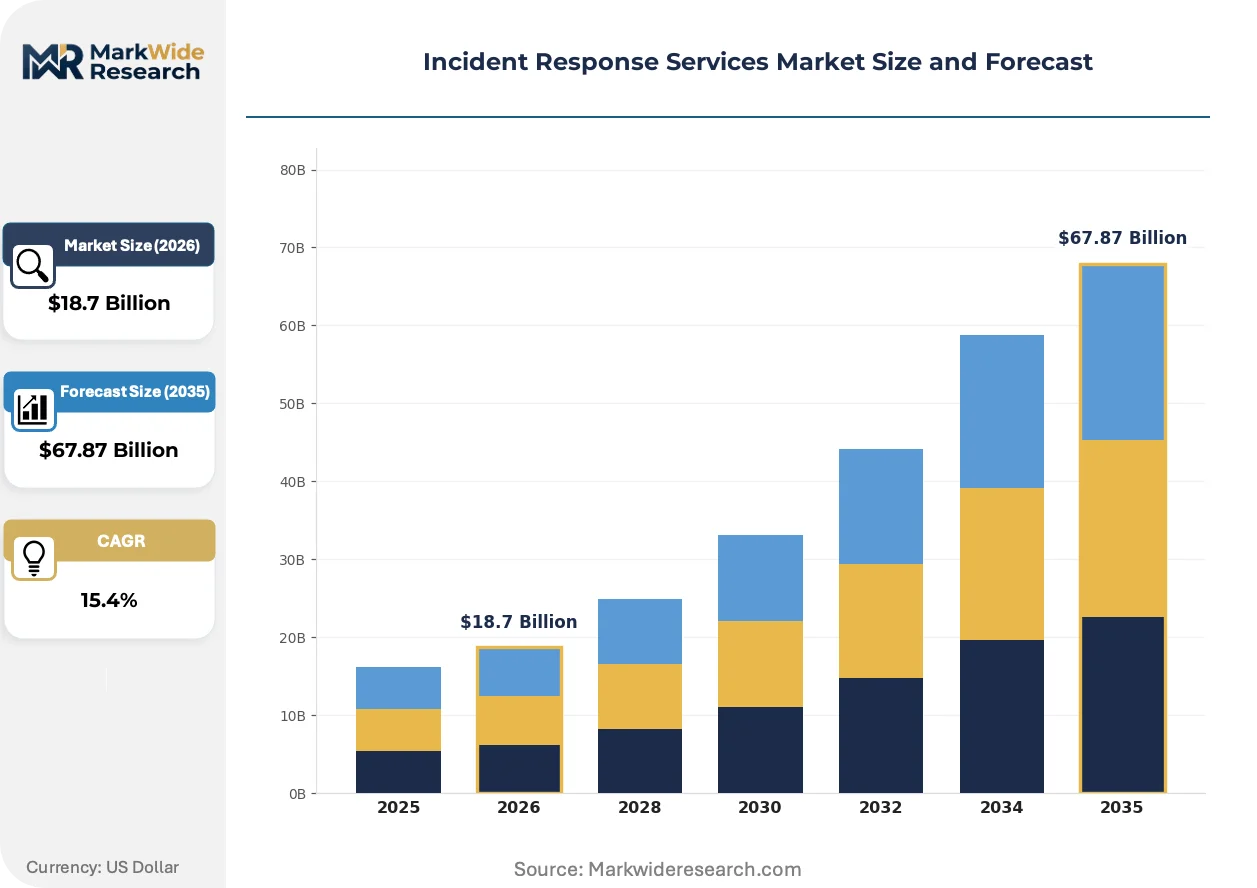
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Consulting, Outsourcing, Incident Management Industry Vertical: Healthcare, Finance, Retail, Government Deployment: On-premises, Cloud-based, Hybrid, Remote Client Type: Small Enterprises, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | Accenture PLC, Cisco Systems, Inc., AT&T, Inc., IBM Corporation, BAE Systems PLC, Check Point Software Technologies Ltd., CrowdStrike Holdings, Inc., Rapid7, Inc., Mandiant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incident Response Services Market Strategic Shifts & Innovations
Automation and policy mandates are restructuring how incident response capacity is procured, delivered, and priced across regulated industries.
Extended detection and response platforms with native automated containment playbooks are displacing manual tier-1 analyst workflows in mid-market security operations centers. Healthcare and financial services adopters deploy these tools to compress initial response latency without proportional headcount expansion. The shift is reducing reliance on traditional managed security service providers for routine alert triage.
SEC cybersecurity disclosure rules now mandate four-day reporting windows for material incidents, forcing publicly traded entities to pre-negotiate retainer contracts with guaranteed response time service level agreements. Legal and compliance departments have gained procurement veto power over vendor selection. Technology and energy sector boards are accelerating budget approvals for pre-positioned forensic capacity.
Buyers now unbundle monitoring from response execution, selecting specialized forensics boutiques for breach containment while retaining separate vendors for routine security operations center operations. This disintermediation fragments vendor relationships and compresses pricing for commodity monitoring services. Financial services firms in the United States exhibit the most advanced procurement sophistication, running competitive retainer RFPs annually.
Incident Response Services Market Segmentation
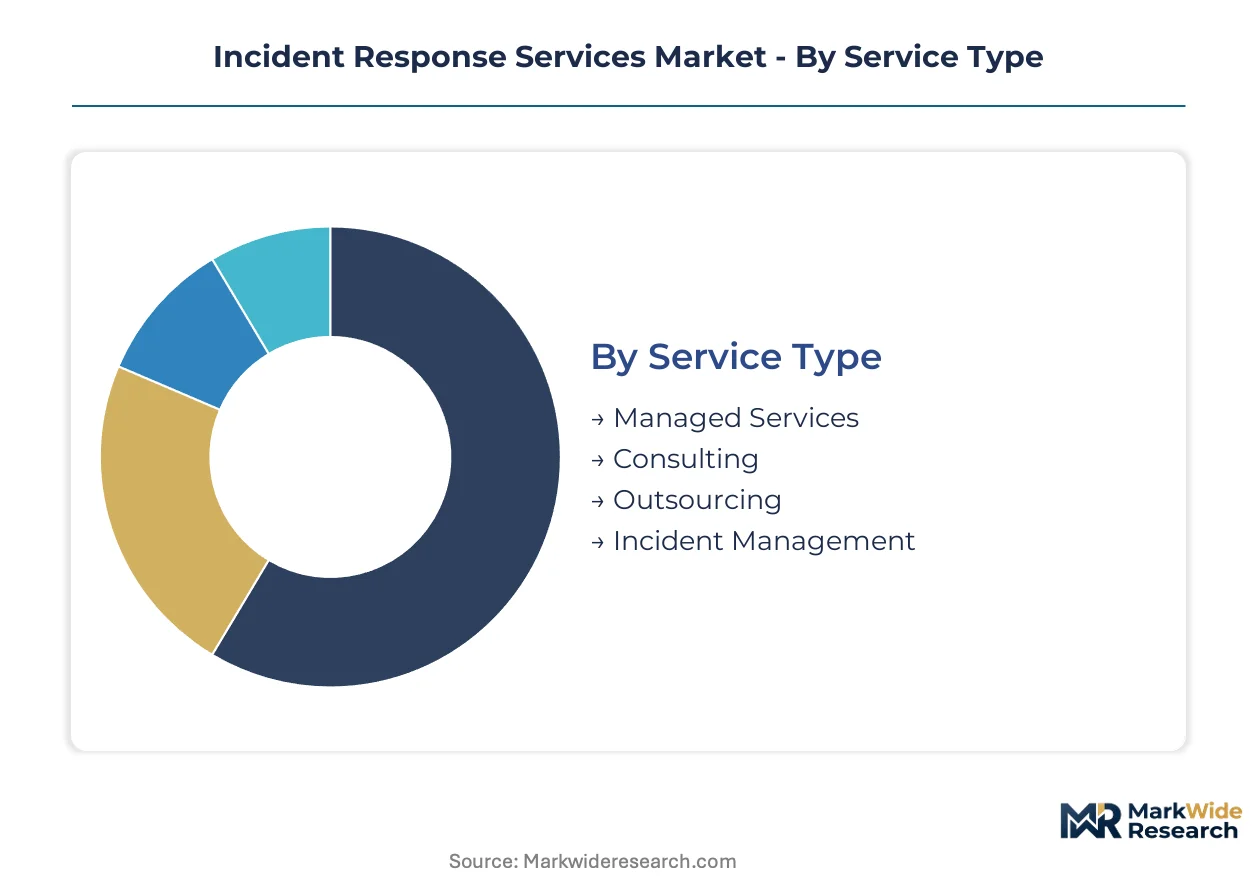
Incident response services fragment across service delivery models, regulatory exposure profiles, infrastructure architectures, and organizational scale. Each segmentation axis channels procurement decisions toward distinct provider capabilities and pricing structures.
Service Type:
Retainer contracts flow through consulting relationships while subscription monitoring scales through platform vendors, creating divergent margin profiles across delivery channels.
- Managed Services:Continuous 24/7 security operations center coverage with automated threat detection and tiered analyst escalation. Financial services firms in the United States concentrate procurement here, driven by SEC four-day disclosure mandates that demand guaranteed response capacity.
- Consulting:Project-based forensic investigation and breach response planning delivered by specialist investigators with nation-state threat intelligence access. HIPAA-covered healthcare entities retain boutique providers for patient record breach complexity.
- Outsourcing:Full transfer of incident response functions to third-party operators, including staff augmentation and playbook development.
- Incident Management:Coordinated crisis response with legal, communications, and regulatory reporting integration.
By volume, Managed Services leads. By growth pace, Consulting is ahead.
Industry Vertical:
Regulatory penalty structures and breach notification timelines create tiered pricing power across end-use sectors.
- Healthcare:HIPAA breach-notification complexity and ransomware targeting of patient record systems generate premium retainer pricing. United States hospital networks outsource containment to avoid multi-million dollar penalties.
- Finance:SEC disclosure rules and EU NIS2 Directive obligations force pre-positioned response capacity. Trading infrastructure operators demand sub-one-hour containment SLAs.
- Retail:Payment card industry compliance and customer data protection drive seasonal procurement patterns around transaction peaks.
- Government:Classified network requirements and sovereign data residency rules restrict vendor eligibility to cleared providers.
By revenue concentration, Finance leads. By margin expansion, Healthcare is climbing the fastest.
Deployment:
Capital expenditure tolerance and legacy infrastructure weight determine infrastructure architecture choices across buyer segments.
- Cloud-based:Elastic SOC capacity without hardware investment attracts mid-market adopters seeking subscription economics. European critical infrastructure operators under NIS2 Directive procurement deadlines favor this model.
- Hybrid:Unified workflows across on-premise legacy systems and multi-cloud environments command consulting premiums. United States enterprises with decades of technical debt drive demand here.
- On-premises:Air-gapped security operations for classified or regulated data environments.
- Remote:Distributed analyst access without physical SOC presence, accelerated by workforce mobility.
By adoption velocity, Cloud-based leads. By contract value, Hybrid is expanding most quickly.
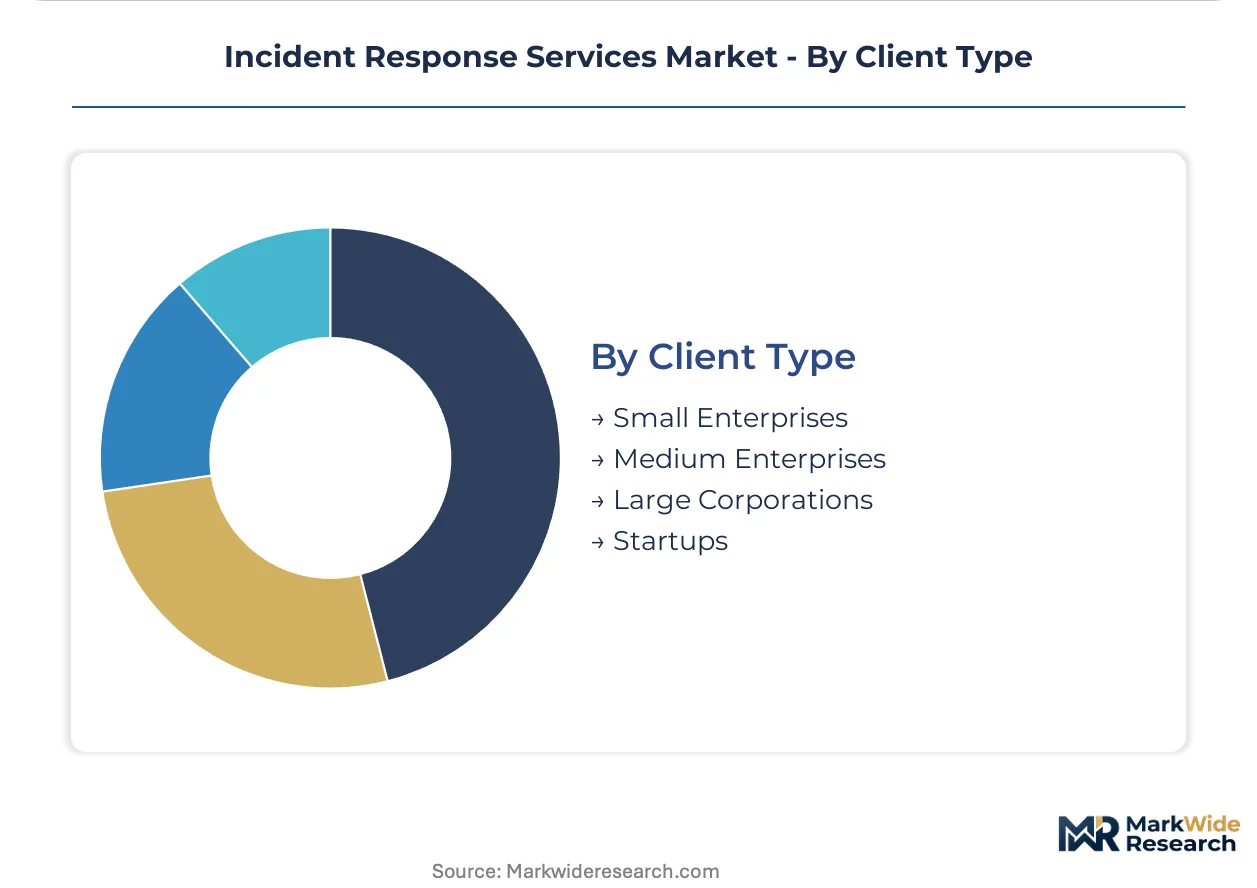
Client Type:
Organizational scale dictates whether buyers self-build, outsource, or hybridize incident response capabilities.
- Large Corporations:Dedicated in-house SOCs supplemented by specialized retainer relationships for breach containment. Publicly traded firms maintain SEC-compliant response playbooks.
- Medium Enterprises:Platform-native managed detection with automated tier-1 response, avoiding headcount expansion.
- Small Enterprises:Shared SOC services and insurance-bundled response retainers.
- Startups:Founder-led security with episodic consulting for investor due diligence.
By contract volume, Medium Enterprises leads. By pricing power, Large Corporations commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where SEC disclosure mandates and HIPAA breach penalties drive premium retainer contracts, while European markets under NIS2 Directive procurement deadlines favor standardized cloud-based deployment economics.
United States
Financial services and hospital networks dominate procurement, with trading infrastructure operators demanding sub-one-hour containment SLAs. SEC four-day disclosure windows and HIPAA multi-million-dollar breach penalties reshape vendor selection criteria. New York and Boston anchor the largest concentration of specialized forensics boutiques serving regulated entities.
Germany
Critical infrastructure operators in energy and transport accelerate compliance-driven spending under EU NIS2 Directive obligations. The country's national cybersecurity regulator enforces documented 24/7 response procedures with cross-border coordination requirements. Munich and Frankfurt host the densest clusters of managed security operations centers serving Central European industrial clients.
United Kingdom
Financial services firms in the City of London pre-negotiate annual retainer RFPs with guaranteed response capacity. The national data protection authority maintains strict breach-notification timelines that overlap with SEC rules for dual-listed companies. London's consulting ecosystem supports sophisticated vendor unbundling between monitoring and response execution.
Japan
Manufacturing conglomerates and pharmaceutical operators build hybrid-cloud incident response workflows across legacy on-premise systems. METI guidelines emphasize supply chain resilience and documented containment playbooks for industrial control systems. Tokyo and Osaka metropolitan areas concentrate domestic platform providers integrating automated orchestration capabilities.
Singapore
Regional headquarters for multinational banks and commodity trading firms drive demand for multi-jurisdictional compliance expertise. The national cybersecurity agency mandates incident reporting standards that bridge ASEAN member state requirements. The city-state's data center cluster supports elastic SOC capacity serving mid-market enterprises across Southeast Asia.
Incident Response Services Market Key Industry Players
Concentration sits with platform-scale providers that combine endpoint telemetry depth with managed detection infrastructure, while boutique forensics shops retain pricing power in specialized healthcare and nation-state threat intelligence segments. The vendor base separates into three archetypes: cloud-native platform operators, legacy consulting integrators with hybrid-cloud workflows, and specialized boutiques with active investigator certifications. Consolidation pressure intensifies through M&A activity targeting boutique talent pools, and strategic partnerships between platform vendors and legal advisory networks.
Within the platform-scale tier, CrowdStrike Holdings, Inc. and IBM Corporation occupy positions that exemplify divergent competitive vectors—endpoint-centric telemetry graph deployment versus decades-deep enterprise consulting relationships. Check Point Software Technologies Ltd. anchors the network-layer containment specialization, differentiating from endpoint-centric rivals through perimeter-focused response speed. These three entities represent the dominant archetypes shaping procurement evaluation criteria across financial services and critical infrastructure operators.
| Leading Market Players |
|---|
| Accenture PLC |
| Cisco Systems, Inc. |
| AT&T, Inc. |
| IBM Corporation |
| BAE Systems PLC |
| Check Point Software Technologies Ltd. |
| CrowdStrike Holdings, Inc. |
| Rapid7, Inc. |
| Mandiant |
| Others |
Cost & Logistics Intelligence
Retainer-based capacity reservation locks in guaranteed incident response access for financial services and critical infrastructure operators while anchoring price visibility against tightening SEC and EU NIS2 Directive breach-notification deadlines. This contract structure concentrates procurement power among buyers with multi-year consulting relationships, compressing spot-market pricing for episodic forensic services.
Pricing Analysis
Configured-to-order retainer pricing commands substantial premiums over standardized subscription monitoring tiers. Three-tier pricing structure across elite forensic boutiques, integrated platform providers, and commodity SOC operators reflects investigator certification depth and nation-state threat intelligence access. Cost compression in commodity monitoring stems from cloud-native detection infrastructure commoditization. Mid-market enterprises exhibit highest price sensitivity, while HIPAA-covered hospital networks and SEC-regulated trading firms accept premium positioning for guaranteed sub-one-hour containment SLAs.
Supply Chain Analysis
The United States and Germany anchor elite-tier forensic talent pools with active investigator certifications and nation-state threat intelligence feeds. India and Eastern European markets feed tier-1 analyst staffing for 24/7 SOC operations. Raw material dependencies span specialized cybersecurity training pipelines, cleared personnel security vetting infrastructure, and proprietary threat intelligence data feeds. Single-source vulnerability concentrates in boutique forensics shops with limited investigator scaling capacity. Distribution runs through direct enterprise sales relationships and insurance-bundled broker channels serving mid-market adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as financial services procurement teams consolidate vendor relationships through competitive annual retainer RFPs, fragmenting the vendor base between monitoring and response execution specialists.
For Market Incumbents: Shield platform-scale positioning by deepening endpoint telemetry graph density and automating tier-1 containment playbooks. Acquire boutique forensics talent pools to defend against cloud-native entrants commoditizing elite-tier tooling. Certification investment in HIPAA and SEC compliance specializations anchors enterprise trust against specialized challengers. For New Entrants and Emerging Players: Healthcare patient record breach containment represents the most penetrable service-layer gap where incumbents under-serve HIPAA notification complexity. Target European critical infrastructure operators under NIS2 Directive procurement deadlines with standardized cloud-based deployment economics. Partner with legal advisory networks for crisis communications integration to differentiate from pure-technology platform vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-scale providers with hybrid-cloud consulting depth over pure-play endpoint vendors. Boutique forensics shops with active investigator certifications and nation-state threat intelligence access represent priority acquisition archetypes. Watch for inflection in SEC enforcement patterns around four-day disclosure compliance as signal for retainer contract expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Containment Playbook Development | Compresses mean-time-to-containment for HIPAA-covered hospital networks facing ransomware targeting. |
| Multi-Jurisdictional Compliance Certification | Unlocks EU NIS2 Directive procurement opportunities across German energy and transport operators. |
| Boutique Forensics Talent Acquisition | Secures scarce investigator certifications with nation-state threat intelligence access. |
| Legal Advisory Network Partnership | Integrates crisis communications and SEC disclosure workflows for publicly traded clients. |
| Hybrid-Cloud SOC Deployment | Captures United States enterprise technical debt requiring unified legacy and multi-cloud workflows. |
Research Approach
A spread of perspectives from CISOs at financial services and healthcare organizations, incident response retainer procurement officers, SOC operations directors, and regulatory compliance attorneys converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC disclosure filings, HIPAA breach notification databases, EU NIS2 Directive implementation guidance, and hyperscaler security services revenue disclosures. Bottom-up service provider capacity estimates and top-down enterprise spending surveys were triangulated to anchor market sizing.
Segmentation dimensions modeled span service delivery type, industry vertical regulatory exposure, deployment architecture, and organizational scale across the projection horizon. CAGRs were derived from elasticity analysis of compliance-driven procurement acceleration and cloud-native adoption curves. Forecast inputs incorporated retainer contract renewal rates, investigator certification pipeline constraints, and automated containment technology displacement patterns.
Material uncertainties — regulatory enforcement intensity variations, nation-state threat actor targeting shifts, and forensic talent scarcity resolution — sit outside the modeled envelope. Forecasts reflect assumptions about sustained SEC and EU NIS2 Directive compliance pressure. Recalibration cycles align with material shifts in breach-notification timeline enforcement and cloud-native SOC technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
Global Incident Response Market