
 Business Continuity Management Solutions Market | 2026-2036
Business Continuity Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Business Continuity Management Solutions Market Analysis
Subscription-based financing and managed-service leasing is narrowing the competitive field for midsize enterprises seeking enterprise-grade resilience capabilities. ServiceNow leverages its workflow automation platform to extend continuity orchestration into IT service management. MetricStream anchors its position through integrated governance, risk, and compliance modules that reduce standalone procurement complexity. Fusion Risk Management differentiates via scenario modeling tools that stress-test operational dependencies across distributed supply chains.
Business continuity management solutions comprise software platforms, consulting frameworks, and recovery services designed to maintain critical operations during disruptions, typically incorporating real-time alerting, alternate site coordination, and communication protocols with recovery time objectives measured in hours or minutes. Their primary commercial purpose is to minimize revenue loss and regulatory exposure when primary systems fail. Cloud solutions and SaaS deployment models are capturing the fastest expansion as organizations abandon capital-intensive on-premises infrastructure. Plan development and testing services command durable margin pools because regulatory auditors require documented exercise evidence, while recovery services generate event-driven revenue spikes that smooth operational planning cycles.
The National Institute of Standards and Technology SP 800-34 framework and ISO 22301 standards shape product design by mandating documented business impact analyses and exercised recovery procedures. The Federal Financial Institutions Examination Council and state insurance commissioners enforce sector-specific continuity obligations that expand addressable demand. Stakeholders must monitor how artificial intelligence-driven threat detection integrates with legacy notification systems before committing to platform consolidation strategies.
Market Dynamics
Cloud migration is compressing deployment cycles while ISO 22301 certification mandates force financial institutions to consolidate fragmented continuity tools into unified platforms.
Growth Catalysts
- FFIEC Examination Guidelines:US federal banking regulators mandate documented business continuity plans with tested recovery procedures, compelling regional banks to upgrade from spreadsheet-based tracking.
- AI-powered threat detection:Machine learning models now predict operational disruptions before they cascade, embedding predictive analytics into continuity orchestration workflows.
- Germany:The country's implementation of EU Digital Operational Resilience Act requirements is accelerating procurement of integrated risk management platforms among Frankfurt-based financial institutions.
Market Restraints
- Specialized consultant dependency:Effective business impact analysis requires certified continuity planners, and the talent pool concentrates in London, New York, and Singapore.
- Legacy system integration costs:Mainframe-dependent insurers face seven-figure migration expenses to connect aged policy administration systems with modern SaaS continuity platforms.
- Substitution by generic project management tools:Smaller enterprises repurpose Asana or Monday.com for incident tracking rather than purchasing dedicated continuity software.
Strategic Opportunities
- Brazil:Central Bank of Brazil resolution requirements for operational resilience create first-mover advantage for vendors establishing local data residency.
- Convergence of ESG reporting and continuity planning:Climate scenario stress-testing tools now satisfy both CSRD disclosure rules and ISO 22301 exercise requirements.
- Managed service provider channel:MSPs in the United Kingdom are bundling continuity-as-a-service with cyber insurance, opening midmarket access without direct enterprise sales cycles.
Industry Challenges
- ISO 22301 lead auditor scarcity:Certification bodies cannot train assessors fast enough to meet demand from organizations seeking accredited business continuity management systems.
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and Google Cloud struggle to maintain consistent recovery time objectives when failover logic must span incompatible APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Continuity Management Solutions Market |
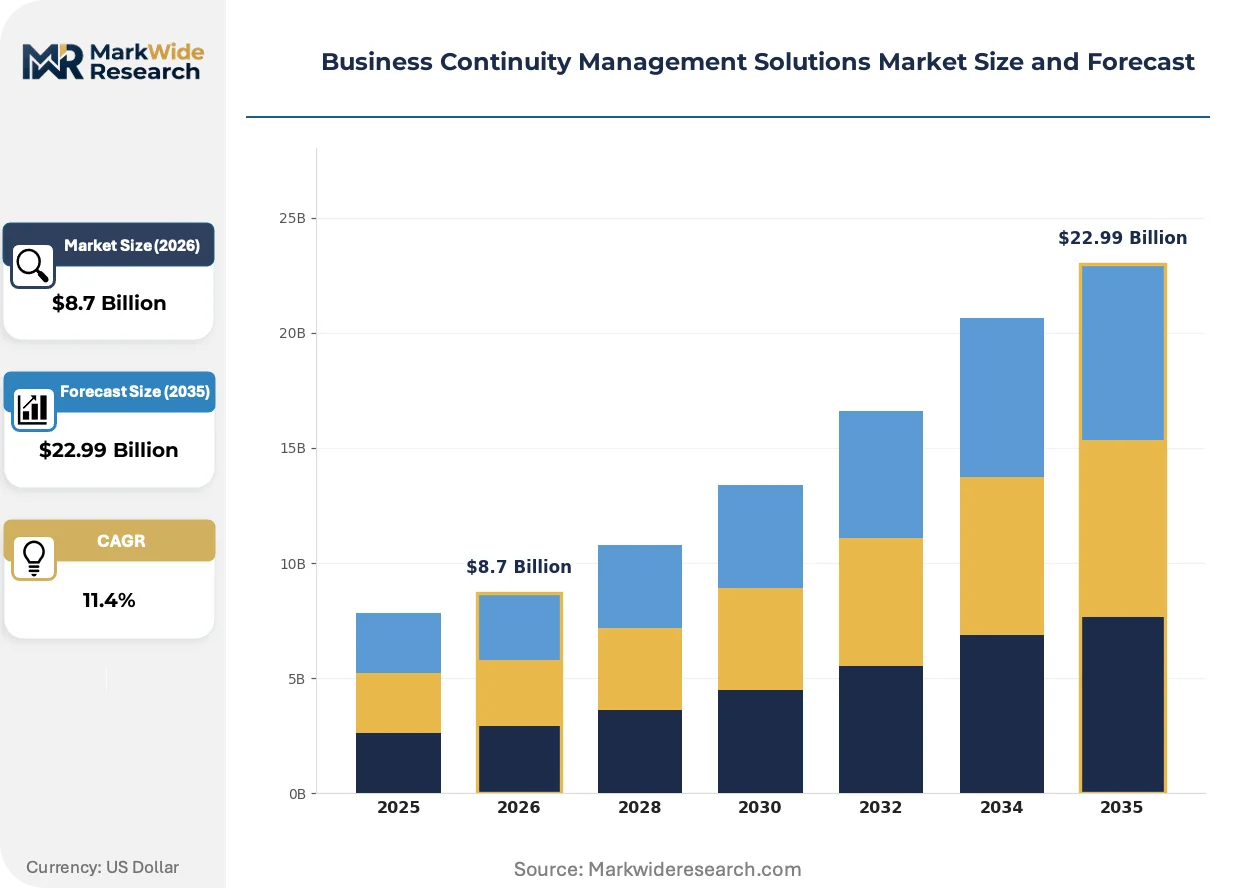
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cloud Solutions, On-Premises Solutions, Hybrid Solutions, Consulting Services Deployment: Public Cloud, Private Cloud, SaaS, Managed Services Industry Vertical: Finance, Healthcare, Retail, Telecommunications Service Type: Plan Development, Testing Services, Training Programs, Recovery Services |
| Companies Covered | Continuity2, ServiceNow, Riskonnect, SAI360, Everbridge, Fusion Risk Management, MetricStream, Corporater, Origami Risk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Continuity Management Solutions Market Emerging Trajectories
Artificial intelligence is embedding predictive capabilities into continuity platforms while regulatory deadlines compress implementation windows across financial services.
Digital twin technology is virtualizing operational environments for disruption simulation. Large manufacturers in automotive and aerospace sectors deploy virtual replicas of production lines to test failover scenarios without halting actual operations. This approach is virtualizing the traditional tabletop exercise, compressing months of planning into automated simulation runs that identify single points of failure in complex supplier networks.
EU Digital Operational Resilience Act implementation timelines are forcing cross-border coordination. Financial entities must map critical ICT third-party providers and test incident response protocols with European Supervisory Authorities oversight. Asset managers in Luxembourg and Ireland face the steepest compliance curves as they renegotiate outsourcing contracts to meet January 2025 continuity testing deadlines.
Subscription pricing is displacing perpetual licenses in enterprise procurement. Risk officers prefer operational expenditure treatment that aligns spending with actual platform utilization rather than front-loaded capital commitments. This preference is strongest among mid-tier banks in the United States seeking to preserve balance sheet flexibility while meeting heightened regulatory expectations for resilience investment.
Business Continuity Management Solutions Market Segmentation
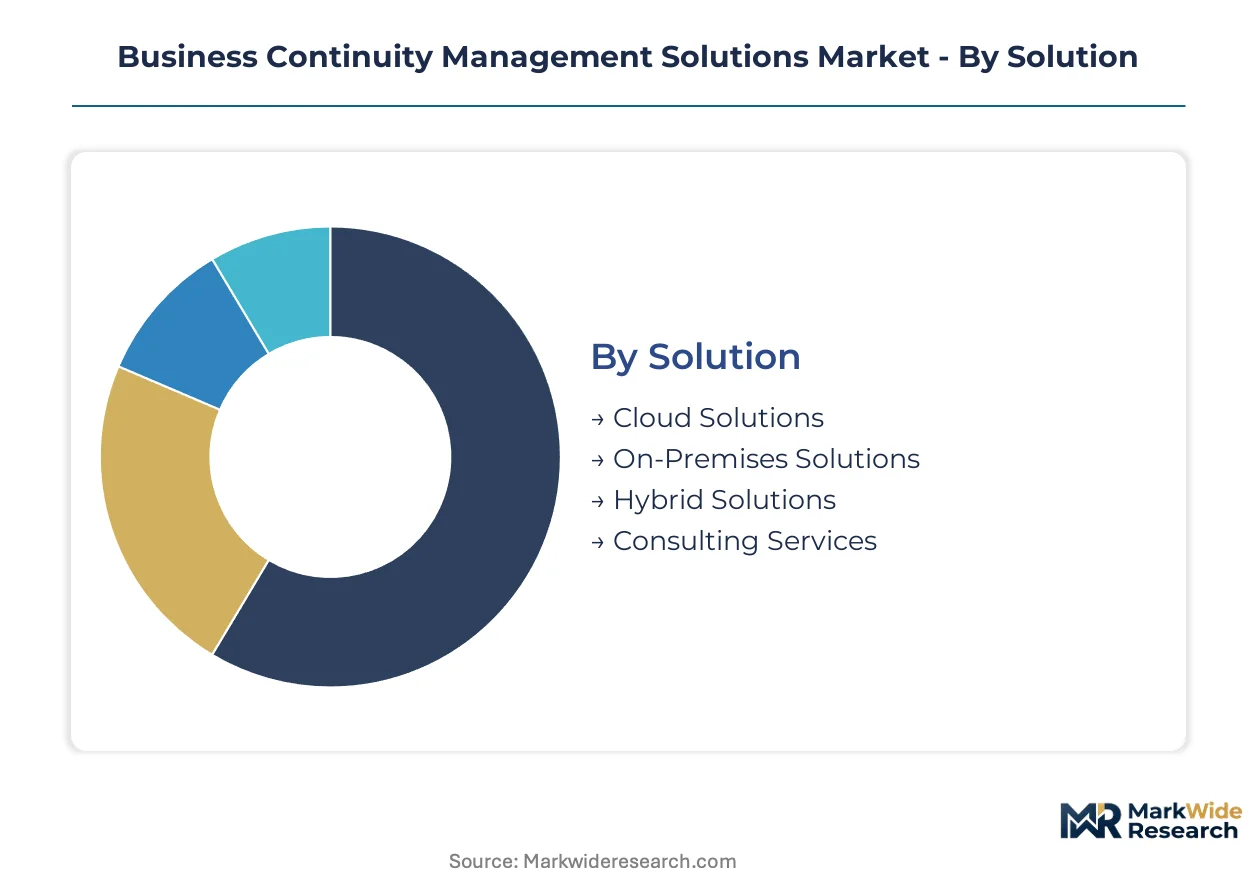
Business continuity management solutions segment across technical architecture, delivery mechanisms, sector-specific requirements, and service maturity levels. Procurement patterns diverge sharply between regulated financial institutions seeking certified resilience frameworks and mid-market enterprises prioritizing operational expenditure flexibility.
Solution:
Use-case spectrum spans capital-intensive infrastructure ownership to fully outsourced resilience capabilities, with procurement decisions tethered to regulatory audit requirements and internal IT governance maturity.
- Cloud Solutions:Multi-tenant architectures with automated failover orchestration and geographically distributed redundancy. Financial services firms in the United States concentrate procurement here as FFIEC examination guidelines mandate tested recovery procedures without capital-intensive infrastructure commitments.
- On-Premises Solutions:Dedicated hardware deployments within client-controlled data centers with custom recovery time objective configurations. Healthcare systems with HIPAA-protected data workflows maintain preference for physical infrastructure control despite higher total cost of ownership.
- Hybrid Solutions:Workload-specific deployment mixing cloud burst capacity with core system on-premises retention.
- Consulting Services:Certified continuity planner engagements for business impact analysis and documentation preparation.
Established volume favors On-Premises Solutions; emerging adoption favors Cloud Solutions.
Deployment:
Cost tier stratification separates enterprise-grade resilience investment from accessible mid-market entry points, with contract structure determining balance sheet treatment and procurement cycle length.
- SaaS:Subscription-based platform access with standardized recovery workflow templates and automated exercise documentation. Mid-tier banks across Germany and France accelerate procurement here to meet EU Digital Operational Resilience Act timelines without seven-figure capital commitments.
- Managed Services:Third-party operational control of continuity orchestration including alternate site management and communication protocol execution. United Kingdom MSPs bundle this with cyber insurance, opening midmarket access without direct enterprise sales cycles.
- Public Cloud:Shared infrastructure deployments with pay-per-use failover testing capabilities.
- Private Cloud:Single-tenant cloud environments with dedicated security boundaries and custom compliance configurations.
Contract value concentrates in Managed Services; subscription velocity climbs fastest in SaaS.
Industry Vertical:
Application criticality varies by sector-specific regulatory pressure and revenue-at-risk per hour of operational disruption, shaping platform complexity requirements and service bundling preferences.
- Finance:Integrated risk management platforms with real-time transaction recovery and regulatory audit trail automation. Frankfurt-based institutions drive procurement acceleration as Germany implements EU Digital Operational Resilience Act requirements with January continuity testing deadlines.
- Healthcare:Patient data protection with HIPAA-compliant communication protocols and clinical system prioritization matrices. Hospital networks prioritize recovery services with documented exercise evidence for accreditation surveys.
- Retail:Point-of-sale continuity and supply chain disruption mitigation with seasonal demand spike protection.
- Telecommunications:Network infrastructure resilience with subscriber notification systems and regulatory outage reporting automation.
Compliance expenditure peaks in Finance; recovery service attach rates run highest in Healthcare.
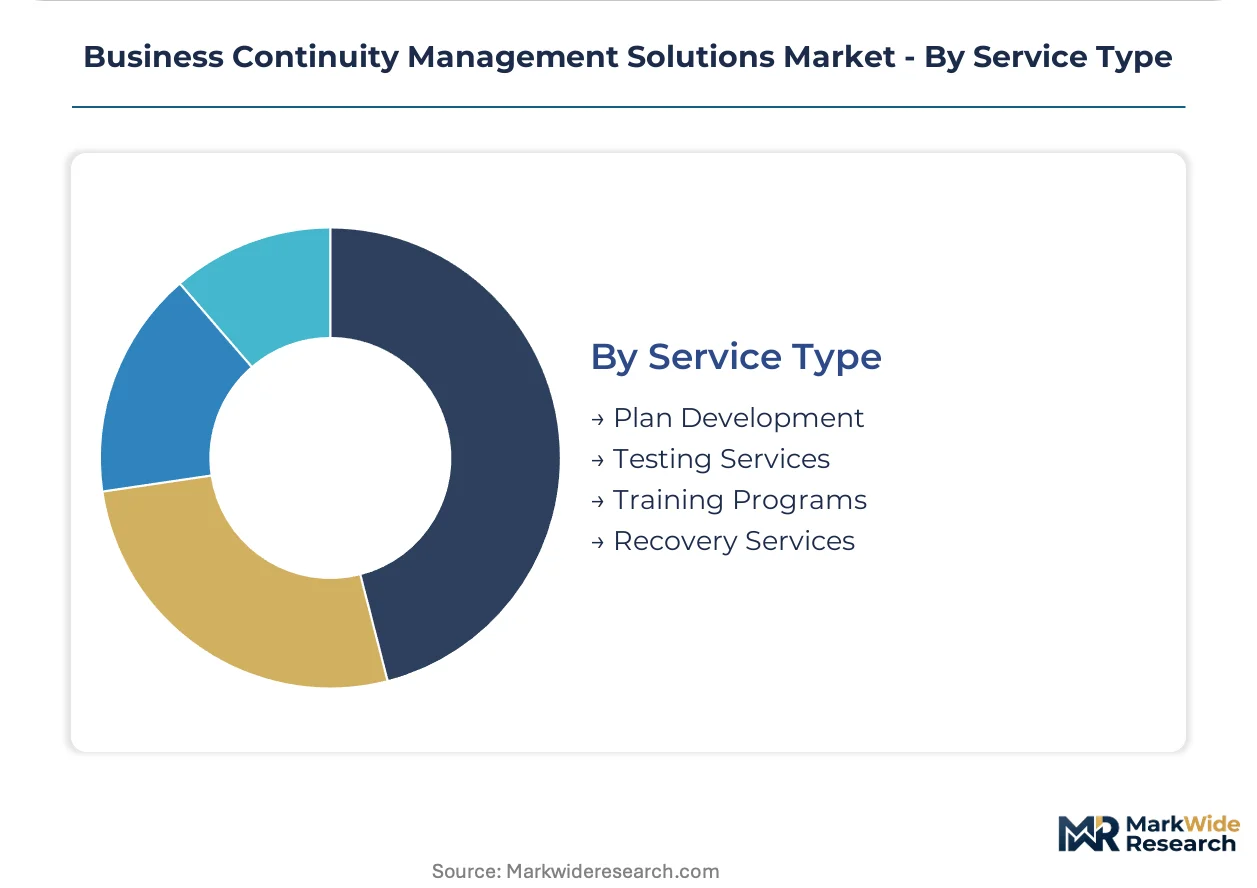
Service Type:
Maturity gradient separates foundational documentation from advanced operational capabilities, with procurement sequencing following certification requirements rather than pure risk mitigation logic.
- Plan Development:Business impact analysis documentation and recovery procedure specification with ISO 22301 alignment. Organizations across Luxembourg and Ireland concentrate spending here to renegotiate outsourcing contracts for European Supervisory Authorities oversight compliance.
- Testing Services:Exercised recovery procedure validation with auditor-ready documentation and scenario refinement recommendations. Regulatory mandates require documented evidence, creating durable margin pools independent of actual disruption frequency.
- Training Programs:Role-specific continuity response certification and tabletop exercise facilitation.
- Recovery Services:Event-driven alternate site activation and crisis communication execution with time-bound service level agreements.
Recurring revenue concentrates in Testing Services; event-driven spikes characterize Recovery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FFIEC examination guidelines and EU Digital Operational Resilience Act deadlines are accelerating procurement across financial centers. Cloud migration and ISO 22301 certification mandates compress implementation timelines in major banking hubs.
United States
Enterprise resilience spending has become a board-level priority at financial institutions. The Federal Financial Institutions Examination Council mandates documented business continuity plans with tested recovery procedures. New York-based regional banks upgrade from spreadsheet-based tracking to unified platforms under regulatory pressure.
Germany
Frankfurt-based institutions drive procurement acceleration as the country implements EU Digital Operational Resilience Act requirements. The European Supervisory Authorities oversee cross-border coordination for incident response protocols. Asset managers renegotiate outsourcing contracts to meet January continuity testing deadlines.
United Kingdom
Managed service providers bundle continuity-as-a-service with cyber insurance to open midmarket access. The Prudential Regulation Authority and Financial Conduct Authority enforce operational resilience expectations across banking and insurance sectors. London concentrates certified continuity planner talent for business impact analysis engagements.
Brazil
Central Bank of Brazil resolution requirements for operational resilience create first-mover advantage for vendors. Local data residency mandates shape procurement decisions among São Paulo-based financial institutions. International platforms establish regional infrastructure to satisfy national sovereignty requirements.
India
RBI guidelines on business continuity planning drive adoption among Mumbai and Bangalore financial institutions. The Securities and Exchange Board of India mandates tested disaster recovery procedures for market infrastructure institutions. IT services exporters invest in resilience capabilities to protect offshore delivery operations.
Business Continuity Management Solutions Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement decisions at financial institutions and healthcare systems. The market exhibits tiered concentration with workflow automation incumbents, integrated governance platforms, and scenario-modeling specialists each occupying distinct positions. Three archetypes dominate: IT service management extenders, GRC-anchored suites, and risk-analytics pure-plays. Competitive moves center on API ecosystem expansion and managed service provider channel development.
Within the IT service management tier, ServiceNow occupies a position as a workflow automation extender. MetricStream and Fusion Risk Management exemplify the governance-risk-compliance anchored archetype with integrated module approaches. These three companies represent the primary competitive vectors as financial institutions consolidate fragmented continuity tools into unified platforms.
| Leading Market Players |
|---|
| Continuity2 |
| ServiceNow |
| Riskonnect |
| SAI360 |
| Everbridge |
| Fusion Risk Management |
| MetricStream |
| Corporater |
| Origami Risk |
| Others |
Supply Flow & Price Mechanics
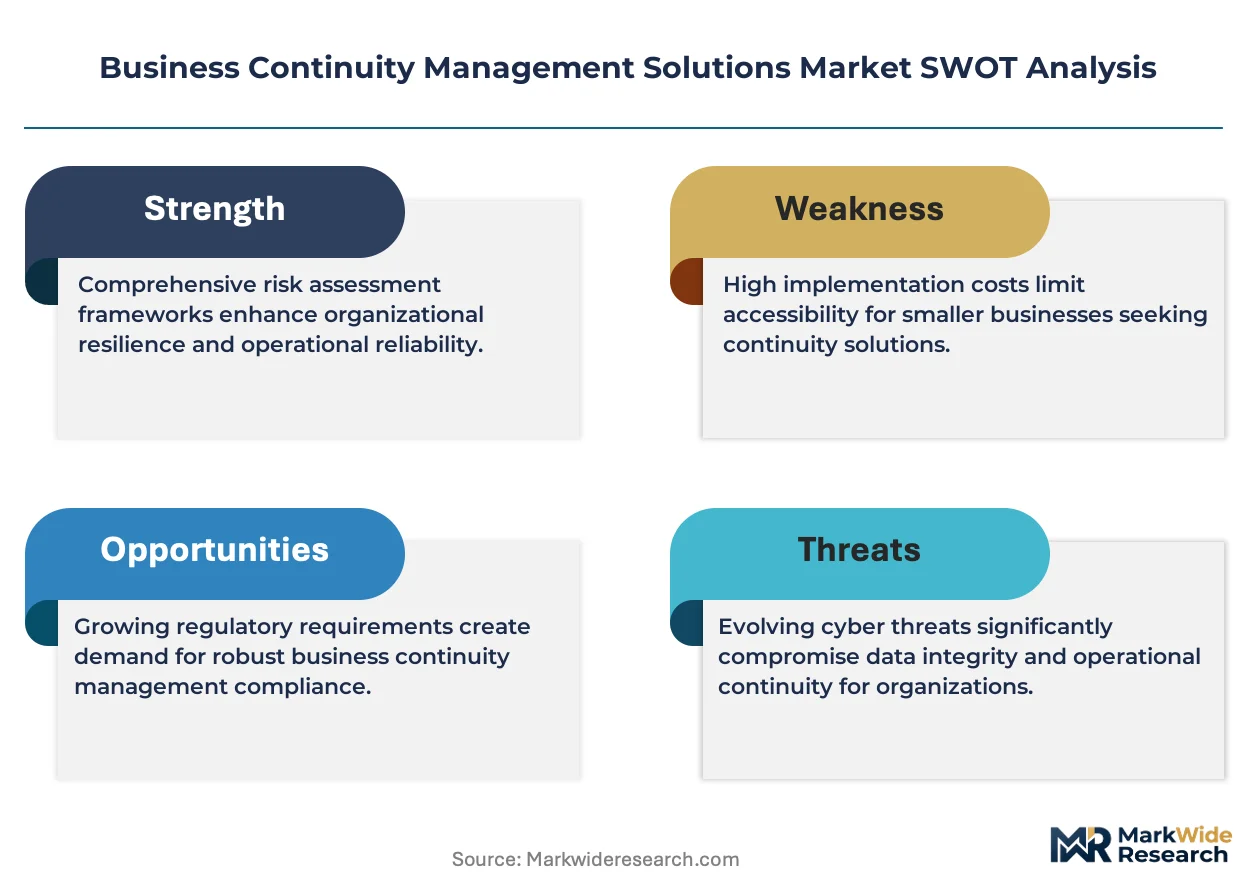
Undercapacity among certified ISO 22301 lead auditors in London and New York drives premium pricing for consulting engagements while compressing margins on standardized SaaS subscriptions. Financial institutions absorb elevated rates for business impact analysis documentation as regulatory deadlines approach, forcing trade-offs between consultant-dependent customization and platform-native automation.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 22301-aligned platforms commanding subscription premiums over generic project management alternatives. Three-tier pricing structure across enterprise-grade orchestration, mid-market SaaS, and entry-level compliance tools reflects integration depth and audit-ready documentation capabilities. Cost compression in the mid-tier is intensifying because managed service providers bundle continuity-as-a-service with adjacent cyber offerings. Regional banks exhibit highest price sensitivity as they migrate from spreadsheet-based tracking, while multinational asset managers prioritize compliance-grade capabilities over unit economics.
Supply Chain Analysis
Platform engineering capacity concentrates among cloud infrastructure providers in the United States, Ireland, and Germany where data residency requirements shape deployment architecture. Software development draws from specialized risk analytics talent pools, third-party API ecosystems, and certified audit documentation engines. Single-source vulnerability runs through concentrated AI threat detection model providers whose integration determines platform differentiation. Distribution runs through direct enterprise sales teams, managed service provider channels, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now favor orchestration layers that bridge fragmented continuity tools, with API interoperability emerging as the decisive moat as financial institutions consolidate vendor relationships under regulatory pressure.
For Market Incumbents: Build workflow integration moats by embedding continuity orchestration deeper into IT service management platforms before standalone risk-analytics specialists capture mid-market share. Acquire scenario-modeling capabilities to defend against digital twin virtualization entrants. Prioritize managed service provider channel certification in the United Kingdom and Germany where bundling with cyber insurance accelerates procurement velocity. For New Entrants and Emerging Players: Build out climate scenario stress-testing modules that satisfy both CSRD disclosure mandates and ISO 22301 exercise requirements, capturing ESG-reporting budget pools. Target Brazil's operational resilience resolution requirements where local data residency mandates disadvantage global platforms without regional infrastructure. Lead with subscription pricing that preserves buyer balance sheet flexibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among testing-services providers whose documented exercise evidence generates durable margin pools independent of disruption frequency. Long-term viability hinges on regulatory enforcement durability rather than cyclical risk awareness. Target acquisition candidates with embedded auditor relationships and cross-sell potential into governance-risk-compliance suites. Monitor FFIEC examination guideline enforcement intensity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Enables seamless integration with ServiceNow and MetricStream platforms for unified orchestration. |
| Managed Service Provider Certification | Opens midmarket access through UK cyber insurance bundling without direct enterprise sales cycles. |
| Digital Twin Virtualization | Compresses tabletop exercises into automated simulations for automotive and aerospace production lines. |
| ISO 22301 Auditor Training Investment | Addresses certification body capacity constraints constraining market expansion in Luxembourg and Ireland. |
| Local Data Residency Infrastructure | Satisfies Brazil Central Bank resolution requirements and German DORA implementation timelines. |
Methodological Framework
Desk research of regulatory filing databases, continuity platform technical documentation, and financial institution procurement records preceded structured interviews with chief risk officers, IT resilience directors, regulatory compliance leads, and managed service provider channel managers. Primary fieldwork across North American and European financial centers was validated against FFIEC examination guidelines, EU Digital Operational Resilience Act implementation timelines, and ISO 22301 certification body capacity data. Bottom-up segment sizing was triangulated with top-down market aggregation.
Assumptions held fixed include sustained regulatory enforcement intensity across US federal banking agencies and European Supervisory Authorities, continued cloud migration preference over on-premises retention, and stable ISO 22301 certification demand curves. The analytical framework modeled deployment model, organization size, vertical regulatory pressure, and geographic adoption pattern across the projection horizon. CAGRs were derived from segment-level growth rate synthesis anchored to documented procurement cycle compression and certification deadline clustering.
Stress conditions across auditor training throughput, multi-cloud API compatibility, and regional data sovereignty enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and acknowledge potential revision from regulatory enforcement relaxation, substitute technology emergence, or macroeconomic contraction affecting resilience investment prioritization. Quarterly review of examination guideline enforcement patterns and certification body capacity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market