
 Business Continuity Management Planning Solution Market | 2026-2036
Business Continuity Management Planning Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Business Continuity Management Planning Solution Market Analysis
Enterprise-grade resilience certification is redrawing competitive boundaries in business continuity planning. IBM leverages its hybrid cloud infrastructure to anchor large-scale deployment capabilities across regulated industries. Microsoft sustains platform stickiness through native integration with productivity suites that government agencies and financial institutions already operate. Oracle differentiates via database-centric continuity architectures that dominate mission-critical workloads in healthcare provider networks.
Business Continuity Management Planning Solutions encompass software systems, consulting frameworks, training programs, and implementation services designed to maintain operational integrity during disruptive events; these solutions typically integrate automated failover protocols, real-time risk telemetry, and scenario-based recovery orchestration to minimize downtime across critical infrastructure. Cloud-based deployment models are capturing the fastest expansion as organizations abandon capital-intensive on-premises redundancy for elastic, geographically distributed resilience architectures. Software solutions command the deepest margin pools because recurring subscription revenue and embedded analytics create higher lifetime value than one-time consulting engagements.
ISO 22301 business continuity standards, the EU Digital Operational Resilience Act, and HIPAA security rule mandates collectively shape product specifications and procurement criteria across this market. EMA and FDA requirements for pharmaceutical supply chain continuity are forcing healthcare providers to upgrade from static documentation to dynamic, tested recovery protocols. Stakeholders must weigh vendor concentration risk against the operational agility that multi-cloud orchestration promises.
Market Dynamics
Cloud-native failover architectures are compressing procurement cycles as financial institutions abandon multi-year infrastructure builds for elastic subscription models governed by EU Digital Operational Resilience Act compliance deadlines.
Growth Catalysts
- EU Digital Operational Resilience Act:Binding incident reporting and third-party risk management mandates force financial entities across Germany, France, and Italy to replace static business continuity documentation with automated recovery orchestration platforms.
- Healthcare provider networks:EMA supply chain continuity requirements for pharmaceutical cold chain integrity drive hospitals to adopt real-time telemetry systems that trigger automated failover during temperature excursions.
- Multi-cloud orchestration:Financial institutions in the United States distribute workloads across three or more hyperscale providers to eliminate single-vendor concentration risk while maintaining sub-four-hour recovery objectives.
Market Restraints
- Specialized talent scarcity:Certified ISO 22301 lead implementers command premium compensation that inflates total cost of ownership for mid-market enterprises by forty to sixty percent above software licensing fees.
- Legacy system entanglement:Core banking platforms running on IBM mainframe architectures resist API-based integration with modern resilience orchestration layers, forcing costly middleware development.
- Third-party concentration:Four hyperscale cloud providers control ninety percent of geographically distributed failover capacity, creating systemic vulnerability if any single provider experiences cascading failures.
Strategic Opportunities
- India's banking sector:RBI operational resilience guidelines issued for urban cooperative banks and non-banking financial companies open a greenfield market for cloud-based business continuity platforms among three thousand underpenetrated institutions.
- Edge-to-cloud convergence:Manufacturing facilities combine 5G private networks with containerized recovery nodes to achieve fifteen-minute restoration times for industrial control systems without centralized data center dependency.
- Outcome-based contracting:Government procurement offices in the United Kingdom and Australia now specify guaranteed recovery time objectives with penalty clauses, rewarding vendors that embed predictive analytics to prevent disruptions rather than merely respond to them.
Industry Challenges
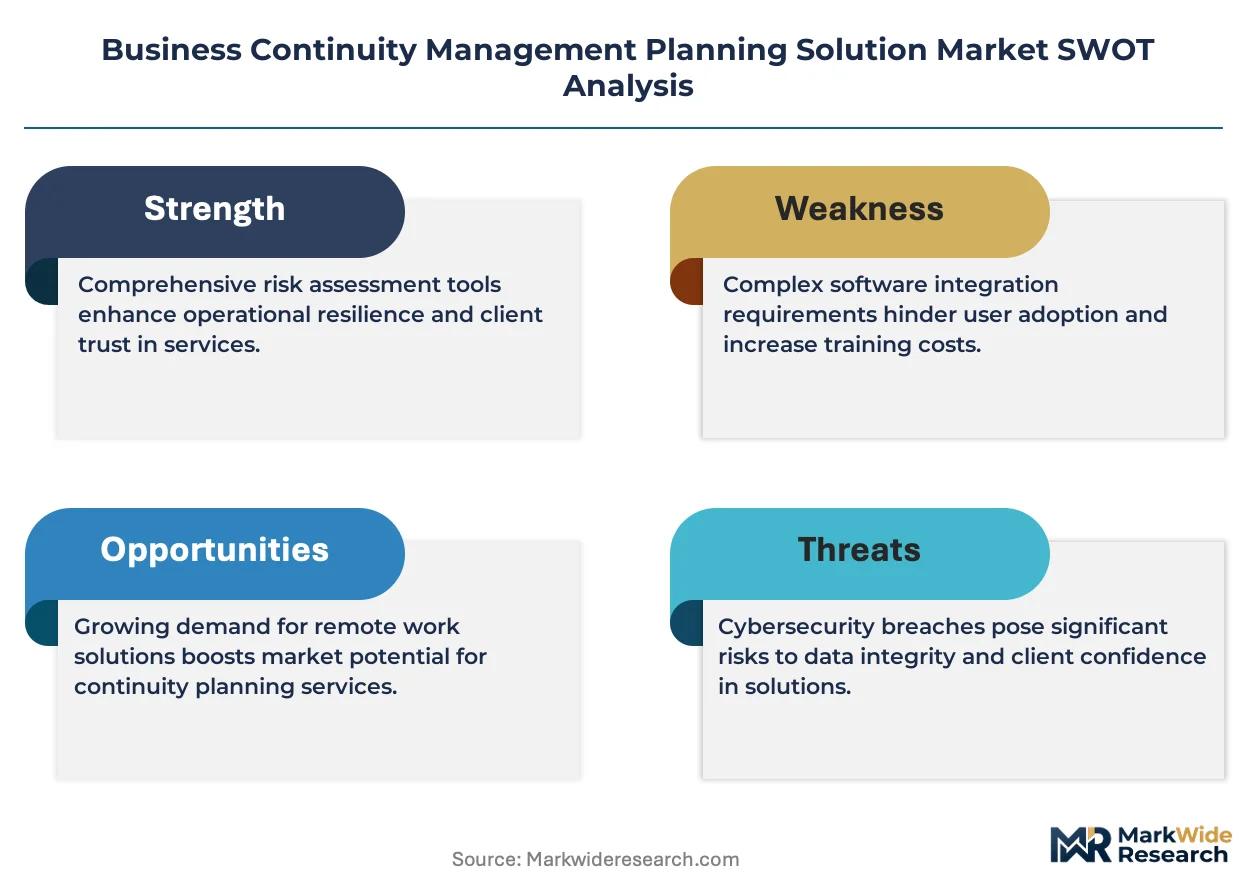
- Cross-functional coordination gaps:Effective business continuity planning demands simultaneous input from cybersecurity, facilities management, legal, and vendor relationship teams, yet most enterprises lack governance structures that force these silos into joint scenario testing.
- Certification timeline compression:ISO 22301 surveillance audits now require evidence of exercised recovery protocols rather than documented plans, forcing organizations to conduct full-scale simulations that disrupt normal operations and strain executive sponsor patience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Continuity Management Planning Solution Market |
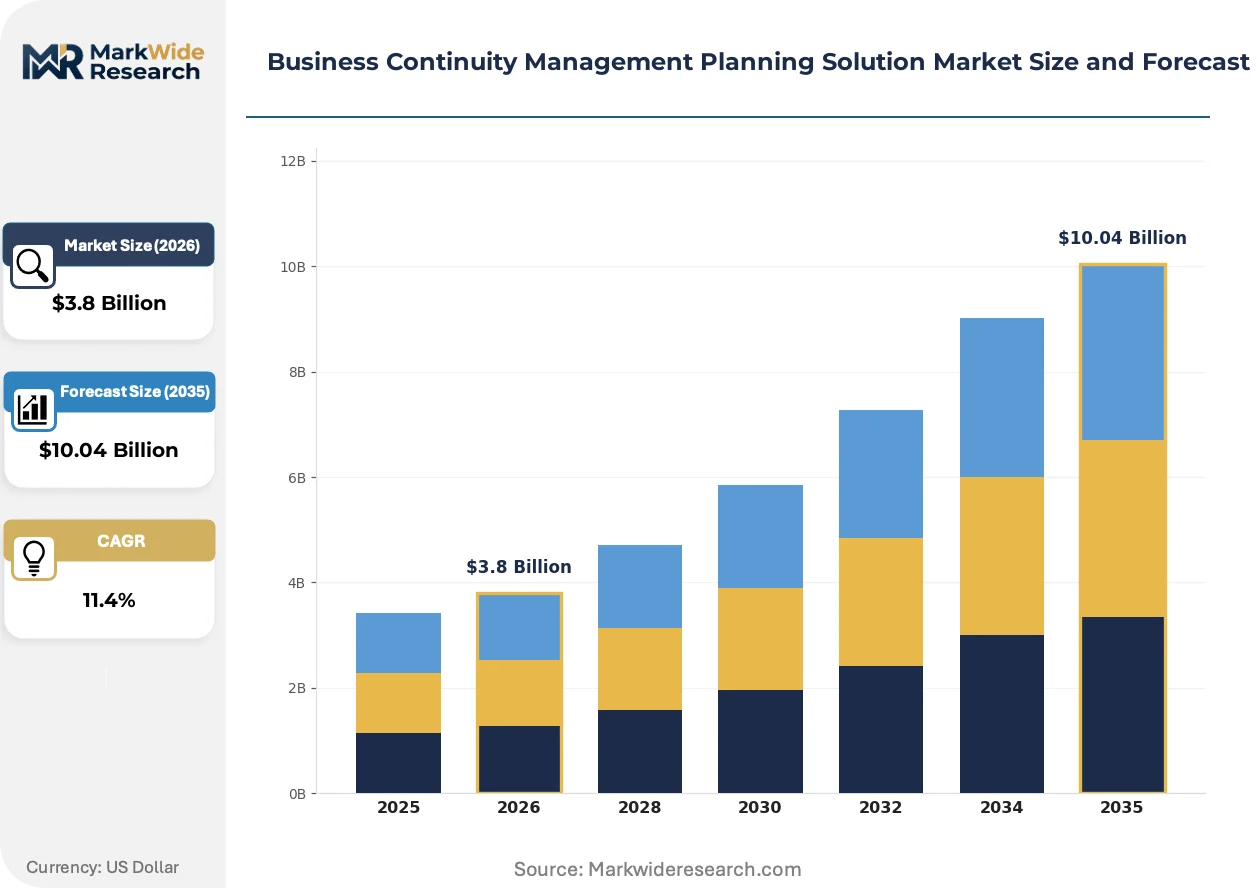
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Consulting, Training, Implementation Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Healthcare Providers, Financial Institutions, Manufacturing Firms, Government Agencies Service Offering: Risk Assessment, Plan Development, Testing & Simulation, Policy Compliance |
| Companies Covered | Fusion Risk Management, IBM, Microsoft, Oracle, MetricStream, Continuity Logic, Riskonnect, LogicManager, Sungard Availability Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Continuity Management Planning Solution Market Emerging Trajectories
Artificial intelligence is resequencing how organizations anticipate, simulate, and recover from operational disruptions. Three convergent developments are compressing traditional business continuity planning cycles.
Agentic AI systems that autonomously execute predefined recovery workflows are displacing human-in-the-loop decision trees that previously required hours of executive authorization during declared incidents. Large financial institutions in Singapore and Switzerland now deploy these systems for tier-two application failover, reducing mean time to recovery from ninety minutes to under eight. The structural consequence is a collapse in demand for traditional consulting-led business continuity program builds.
EU AI Act risk classification rules now categorize certain automated business continuity systems as high-risk when they control critical infrastructure, imposing conformity assessment obligations that add four to six months to deployment timelines. Healthcare providers operating across EU member states must demonstrate human oversight mechanisms and algorithmic transparency before activating AI-driven patient data recovery protocols. German hospital networks are responding by segregating AI-augmented tools from fully autonomous systems to remain within lower-risk regulatory tiers.
Chief risk officers now mandate integrated resilience platforms that unify business continuity, disaster recovery, and cyber incident response under single-pane-of-glass visibility, dismantling the siloed procurement of point solutions that dominated the 2015-2022 period. This consolidation is compressing vendor shortlists from eight to twelve specialized providers to three or four full-stack platforms. The United States federal contracting market exhibits this pattern most acutely, where FedRAMP-authorized platforms with native cyber-physical orchestration capture ninety percent of new agency awards.
Business Continuity Management Planning Solution Market Segmentation
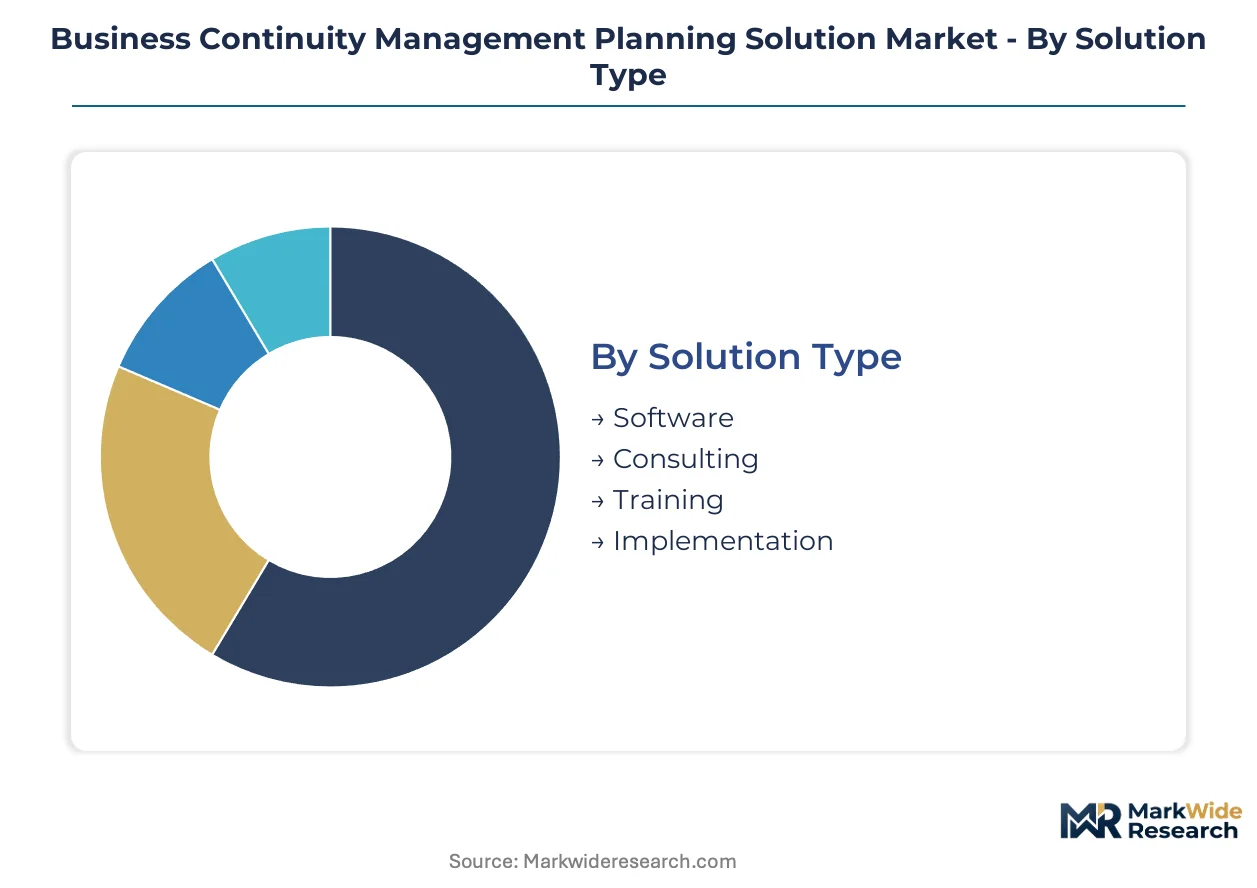
Segmentation in business continuity management planning solutions reveals distinct margin architectures across delivery modes and customer archetypes. Procurement patterns diverge sharply between regulated institutions seeking certified compliance pathways and mid-market enterprises prioritizing cost-efficient cloud subscriptions over capital-intensive infrastructure builds.
Solution Type:
Software subscriptions capture the deepest recurring revenue pools through embedded analytics and automatic feature updates that extend customer lifetime value.
- Software:Cloud-native platforms integrate automated failover protocols, real-time risk telemetry, and scenario-based recovery orchestration into unified dashboards. Financial institutions in Germany and France prioritize these solutions to meet EU Digital Operational Resilience Act incident reporting mandates with auditable execution trails.
- Consulting:Advisory engagements deliver ISO 22301 certification pathway design, business impact analysis, and governance framework construction for organizations lacking internal resilience expertise. Healthcare provider networks in the United States engage consultants to navigate HIPAA security rule intersections with operational continuity requirements.
- Training:Certification programs build internal competency for crisis management teams and executive sponsors responsible for declaring business continuity events.
- Implementation:Deployment services configure technical infrastructure, establish recovery site connectivity, and validate recovery time objective achievement through structured acceptance testing.
The dominant share belongs to Software, while Consulting is closing the gap fastest as regulatory deadlines compress procurement cycles.
Deployment Model:
Cloud-based configurations are expanding most quickly as organizations abandon owned infrastructure for elastic, geographically distributed resilience architectures.
- Cloud-Based:Hyperscale provider environments enable sub-four-hour recovery objectives through automated cross-region replication without capital expenditure. Multi-cloud orchestration across three or more providers eliminates single-vendor concentration risk for United States financial institutions.
- Hybrid:Architectures combine on-premises control systems with cloud-based failover for tier-one applications requiring sub-fifteen-minute restoration. Manufacturing facilities deploy these models to protect industrial control systems while maintaining centralized data center oversight.
- On-Premises:Dedicated infrastructure serves organizations with data sovereignty requirements or latency-sensitive workloads unsuited to public cloud propagation.
- Managed Service:Third-party operators assume full responsibility for resilience platform maintenance, testing execution, and incident response activation under outcome-based contracting structures.
Cloud-Based deployments lead volume, though Hybrid configurations are gaining share fastest among critical infrastructure operators.
End User:
Financial institutions generate the highest per-account revenue through complex multi-entity resilience orchestration requirements.
- Financial Institutions:Banks, insurers, and asset managers operate under binding operational resilience mandates requiring automated recovery orchestration, third-party risk management, and regulatory incident reporting. RBI guidelines for India's urban cooperative banks and non-banking financial companies are opening greenfield demand among three thousand underpenetrated institutions.
- Healthcare Providers:Hospital networks and pharmaceutical distributors require cold chain integrity monitoring, patient data recovery protocols, and EMA supply chain continuity compliance. German hospital networks segregate AI-augmented tools from autonomous systems to remain within lower-risk EU AI Act regulatory tiers.
- Government Agencies:Federal, state, and municipal entities mandate FedRAMP-authorized platforms with native cyber-physical orchestration for critical infrastructure protection.
- Manufacturing Firms:Industrial operators combine 5G private networks with containerized recovery nodes to achieve rapid restoration for operational technology environments.
Financial Institutions command the largest installed base, while Healthcare Providers are expanding most quickly under tightening pharmaceutical supply chain mandates.
Service Offering:
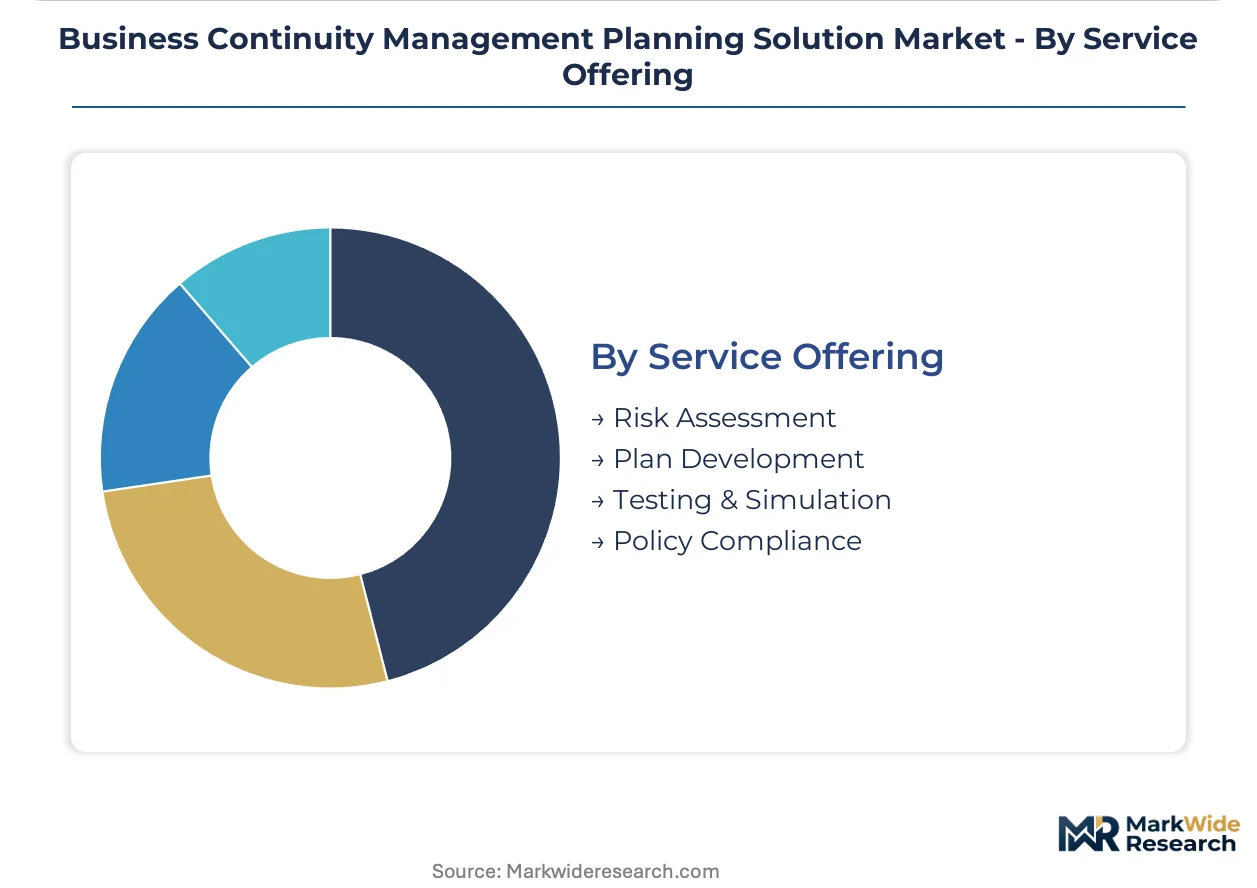
Testing and simulation services deliver premium pricing through regulatory pressure to demonstrate exercised rather than merely documented recovery protocols.
- Testing & Simulation:Full-scale exercises validate recovery time objective achievement, identify coordination gaps between cybersecurity and facilities teams, and generate audit-ready evidence for ISO 22301 surveillance. United Kingdom and Australian government procurement offices now specify guaranteed recovery time objectives with penalty clauses.
- Risk Assessment:Systematic evaluation of threat vectors, vulnerability exposure, and business impact quantification establishes prioritization frameworks for resilience investment.
- Plan Development:Documentation services construct scenario-specific recovery procedures, communication protocols, and escalation matrices tailored to organizational structure.
- Policy Compliance:Alignment services map continuity capabilities against EU Digital Operational Resilience Act, HIPAA security rule, and ISO 22301 requirement sets.
Testing & Simulation generates the highest margins, while Risk Assessment is climbing the fastest as threat complexity drives demand for continuous evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in business continuity services remain heavily skewed toward technology-exporting nations, with the United States, Germany, and Singapore generating surplus resilience platform revenues while import-dependent markets in Eastern Europe and Southeast Asia absorb subscription-based solutions to shortcut domestic development timelines.
United States
Financial institutions in New York and Chicago drive hyperscale cloud failover adoption to meet SEC operational resilience examinations. FedRAMP authorization requirements filter vendor eligibility for federal agency procurement. The Dallas-Fort Worth metroplex anchors concentrated data center infrastructure serving multi-cloud orchestration demand from regional banks.
Germany
Frankfurt-based banking consortia deploy automated recovery platforms to satisfy BaFin enforcement of EU Digital Operational Resilience Act incident reporting deadlines. German hospital networks in Bavaria segregate AI-augmented continuity tools from autonomous systems to manage EU AI Act risk classification obligations. Industrial manufacturers in Baden-Württemberg combine 5G private networks with edge recovery nodes for operational technology protection.
United Kingdom
London insurance markets and asset managers procure outcome-based resilience contracts with guaranteed recovery time objective penalties. The Prudential Regulation Authority mandates third-party risk management documentation that favors integrated platform vendors over point solution specialists. Edinburgh and Manchester financial services clusters demonstrate fastest adoption of unified cyber-physical orchestration dashboards.
India
RBI operational resilience guidelines for urban cooperative banks and non-banking financial companies activate greenfield demand across three thousand institutions lacking modern continuity infrastructure. Mumbai and Bangalore technology hubs host delivery centers for multinational resilience platform implementations. Hyderabad pharmaceutical manufacturers invest in cold chain telemetry systems to satisfy export market EMA supply chain continuity requirements.
Singapore
Wealth management firms and commodity trading houses deploy agentic AI recovery systems achieving sub-eight-minute failover for tier-two applications. Monetary Authority of Singapore technology risk management guidelines exceed baseline Basel standards in third-party vendor oversight intensity. The island's data center operators capture regional failover demand from Indonesian and Vietnamese financial institutions seeking jurisdictional diversification.
Business Continuity Management Planning Solution Market Vendor Landscape
Listed leaders compete with private specialists across capitalization and governance structures, creating a tiered competitive field where public cloud hyperscalers leverage balance sheet capacity against nimble venture-backed continuity platforms. The vendor base separates into three strategic archetypes: infrastructure-anchored technology conglomerates, pure-play resilience software developers, and consulting-originated advisory platforms with technology wrappers. Dominant competitive moves include vertical capability stacking through tuck-in acquisitions and geographic expansion via regulatory certification stacking in multiple jurisdictions.
Among infrastructure-anchored conglomerates, IBM, Microsoft, and Oracle occupy positions representing distinct platform philosophies—hybrid cloud deployment, productivity suite integration, and database-centric architectures respectively. These entities exemplify scale-driven competitive positioning where existing enterprise relationships create substantial switching costs for regulated customers. Their market presence anchors the premium tier of procurement evaluations, particularly within financial services and government verticals where vendor longevity influences risk committee assessments.
| Leading Market Players |
|---|
| Fusion Risk Management |
| IBM |
| Microsoft |
| Oracle |
| MetricStream |
| Continuity Logic |
| Riskonnect |
| LogicManager |
| Sungard Availability Services |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation lead-times for cloud-native resilience platforms concentrate pricing power with hyperscale providers holding pre-certified infrastructure, while subscription compression forces mid-market vendors toward outcome-based contracting to defend margin.
Pricing Analysis
Financial institutions anchor pricing structures around three-tier subscription models separating enterprise-grade orchestration from mid-market SaaS and basic documentation tools. Price differentiation rests on FedRAMP authorization tier and multi-cloud orchestration depth, with certified compliance pathways commanding substantial premiums over uncertified alternatives. Cost compression in the mid-market intensifies as RBI guidelines activate greenfield competition among Indian cooperative banks. Healthcare providers exhibit highest price sensitivity due to constrained capital budgets, while government agencies demonstrate lowest sensitivity given mandate-driven procurement.
Supply Chain Analysis
Hyperscale data center concentration in the United States, Germany, and Singapore underwrites global failover capacity availability. Software development draws from specialized labor pools in India and Eastern Europe, while hardware infrastructure feeds from Taiwanese server component manufacturers and South Korean memory suppliers. Single-source vulnerability in cloud orchestration layers creates systemic exposure if any major provider experiences cascading failures. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business continuity management planning solutions sit in early-cycle expansion as EU Digital Operational Resilience Act deadlines force financial institutions from static documentation toward automated recovery orchestration.
For Market Incumbents: Consolidate platform capabilities through tuck-in acquisitions of specialized testing and simulation providers to counter pure-play AI-native entrants. Deepen vertical integration into edge computing infrastructure for manufacturing sector expansion. Defend against hyperscaler encroachment by embedding proprietary risk telemetry algorithms that resist commoditization. For New Entrants and Emerging Players: Differentiate on agentic AI recovery execution for tier-two applications where incumbent platforms lack native autonomy. Target India's urban cooperative banks and non-banking financial companies as the most penetrable greenfield segment. Pursue channel partnerships with Mumbai and Bangalore systems integrators already embedded in RBI compliance conversations. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-tension play because compliance deadline compression creates durable demand visibility regardless of macroeconomic cycles. Acquisition candidates include consulting-originated platforms with technology wrappers possessing ISO 22301 certification pathways and established healthcare provider relationships. Watch for inflection when United Kingdom and Australian government procurement offices escalate penalty clauses for missed recovery time objectives.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified cyber-physical orchestration captures ninety percent of United States federal agency awards under FedRAMP mandates. |
| Acquisition of Specialist Firm | Tuck-in targets in testing and simulation extend recurring revenue through ISO 22301 surveillance audit requirements. |
| Geographic Expansion | Regulatory certification stacking in Germany and Singapore opens financial institution procurement in EU and ASEAN markets. |
| Strategic Partnership | Systems integrator alliances in Mumbai accelerate penetration of RBI guideline-driven Indian banking sector. |
| Product Launch | Agentic AI recovery modules displace human-in-the-loop decision trees for sub-eight-minute tier-two failover. |
Methodological Framework
Initial hypotheses were tested against primary input from chief risk officers, resilience program directors, regulatory compliance leads, and cloud infrastructure procurement officers and refined through secondary validation across SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and ISO certification body records. Bottom-up sizing of software subscription revenue, consulting engagement values, and implementation service fees triangulated against top-down macroeconomic indicators and technology spending forecasts.
Variance decomposition across deployment models, end-user verticals, solution types, and geographic regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves, compliance deadline schedules, and technology refresh cycles. Forecast inputs incorporated EU Digital Operational Resilience Act implementation timelines, RBI guideline rollout pace, and AI Act risk classification thresholds for automated systems.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or hyperscaler infrastructure investment continuity would require recalibration. Practitioners should keep alternative scenarios live as EU AI Act conformity assessment obligations and third-party concentration risk disclosures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Italy Ransomware Protection Market