
 Global Subsea Systems Market | 2026-2036
Global Subsea Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subsea Systems Market Foresight
The EU F-Gas Regulation is decoupling legacy insulation chemistries from new subsea project specifications, forcing suppliers to reformulate pipeline coating and sealing systems at higher R&D cost. TechnipFMC leverages its integrated engineering-to-installation model to absorb these compliance costs across bundled contracts. Aker Solutions anchors its position through proprietary low-global-warming-potential insulation platforms purpose-built for North Sea and Atlantic basin conditions.
Subsea systems comprise pressure-containing and flow-control equipment deployed on the seabed to extract, process, and transport hydrocarbons from offshore reservoirs to surface facilities, typically rated for depths exceeding 1,500 meters and pressures above 10,000 psi. Subsea trees dominate capital allocation due to their wellhead control function and unit value concentration, while umbilicals represent the fastest-growing product category as tieback architectures multiply and field electrification demands more power and communication lines. Electro-hydraulic technology still occupies the majority of installed base, though electro-mechanical systems are displacing legacy architectures in greenfield deepwater projects where umbilical weight and installation complexity drive specification shifts.
OSHA, the EPA, and Norway's Petroleum Safety Authority shape operational safety, emissions accountability, and equipment certification requirements across the Atlantic basin project pipeline. The EU AI Act and emerging MEE guidelines in China are beginning to influence subsea monitoring equipment standards, particularly for autonomous inspection and predictive maintenance systems. Stakeholders must monitor how divergent digital-equipment certification pathways between the North Sea and Asia-Pacific affect interoperability and aftermarket service economics.
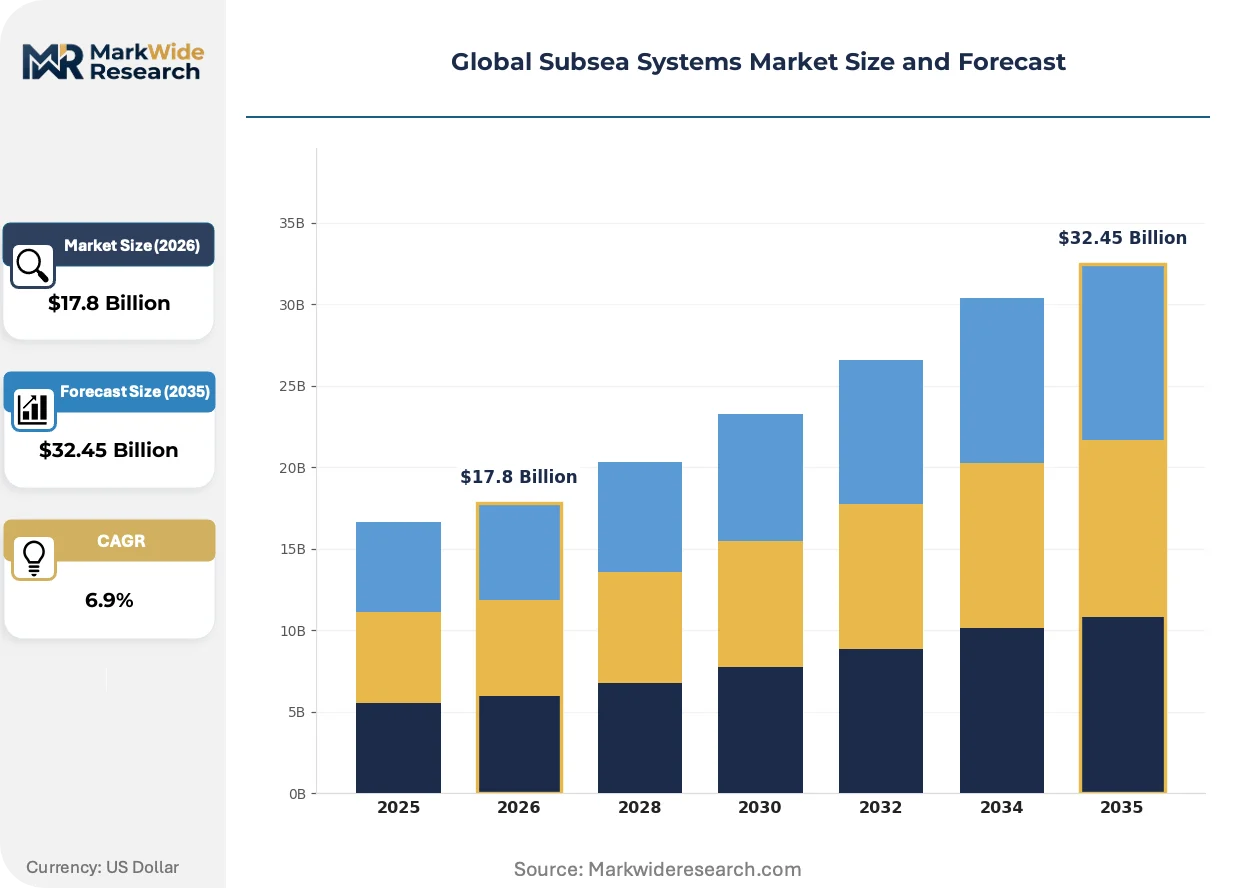
Market Dynamics
Deepwater exploration economics are compressing project timelines and forcing bundled engineering-procurement-installation contracts that favor integrated suppliers over component specialists. The EU F-Gas Regulation's phase-down timeline is accelerating material transitions in pipeline insulation and sealing systems across Atlantic basin developments.
Growth Catalysts
- Pre-salt field development in Brazil:Petrobras and international partners are sanctioning multi-billion-dollar subsea tieback projects requiring trees, manifolds, and umbilicals at unprecedented scale.
- REACH-compliant material innovation:European suppliers are reformulating pipeline coatings with low-global-warming-potential chemistries ahead of regulatory deadlines, creating first-mover certification advantages.
- Electrification of subsea infrastructure:Power-from-shore architectures and subsea processing modules are multiplying umbilical line counts and communication bandwidth requirements per well.
Market Restraints
- High-grade steel and titanium input volatility:Pressure-rated forgings and corrosion-resistant alloys face concentrated supply from Japanese and Austrian metallurgical specialists with limited surge capacity.
- Installation vessel scarcity:Heavy-lift and reel-lay vessel availability constraints in the North Sea and Gulf of Mexico are extending project lead times and inflating day rates.
- Fluorinated gas substitution complexity:The EU F-Gas Regulation is forcing premature retirement of validated insulation chemistries before qualified alternatives achieve full thermal performance parity.
Strategic Opportunities
- Autonomous inspection systems:The EU AI Act and emerging MEE guidelines in China are creating certification pathways for predictive maintenance robotics in subsea monitoring.
- Retrofit electrification of brownfield assets:Aging North Sea infrastructure requires umbilical upgrades and subsea power distribution units to support platform decommissioning and tieback conversion.
- Standardized subsea processing skids:Modular separation and boosting systems are opening vendor access to mid-size independents previously excluded from custom-engineered developments.
Industry Challenges
- Subsea controls engineering talent scarcity:Specialized expertise in electro-hydraulic and all-electric actuation systems is concentrated among retiring workforce cohorts in Norway and Scotland.
- Cross-regional certification divergence:The EU AI Act's digital equipment standards are misaligned with emerging Chinese MEE guidelines, complicating interoperability for autonomous inspection platforms.
- Legacy system integration friction:Brownfield tiebacks must interface with decades-old wellhead architectures lacking digital instrumentation or standard communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subsea Systems Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $32.45 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subsea Trees, Umbilicals, Manifolds, Control Systems, Monitoring Equipment Technology: Electro-Hydraulic, Electro-Mechanical, Fiber Optic, Acoustic, Hydraulic Application: Offshore Oil Extraction, Natural Gas Processing, Deepwater Exploration, Pipeline Monitoring, Marine Research End User Industry: Energy Corporations, Offshore Contractors, Marine Engineering Firms, Environmental Agencies |
| Companies Covered | TechnipFMC, Subsea 7, Aker Solutions, OneSubsea, Dril-Quip, Baker Hughes, Schlumberger, Oceaneering International, National Oilwell Varco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subsea Systems Market Shifts & Advancements
Subsea architecture decisions are migrating from discrete component procurement toward integrated system performance guarantees, compressing vendor count per development and elevating engineering accountability. Material science advances and digital monitoring capabilities are reshaping equipment specification standards.
Electro-mechanical actuation is expanding into greenfield deepwater projects as operators seek to eliminate hydraulic fluid columns and reduce umbilical diameter. Supermajors developing pre-salt and Lower Tertiary reservoirs are specifying all-electric trees and valves for wells beyond 2,500 meters depth. This architecture is expanding into marginal field developments previously uneconomic under electro-hydraulic weight and complexity constraints.
The EU F-Gas Regulation's phasedown mandates are forcing immediate formulation changes in thermal insulation foams and sealing elastomers used across pipeline and jumper systems. Suppliers must recertify materials under REACH and offshore equipment directives before 2030 deployment windows. North Sea operators are accelerating qualification programs with Norwegian and German chemical specialists to secure compliant supply ahead of project sanctioning deadlines.
Performance-based contracting is displacing traditional component purchase models as operators transfer operational risk to equipment suppliers. Integrated service agreements now bundle installation, commissioning, and life-of-field maintenance for subsea production systems. This restructuring is most advanced in Brazil and Norway, where Petrobras and Equinor have established long-term alliance frameworks with preferred engineering contractors.
Global Subsea Systems Market Segmentation
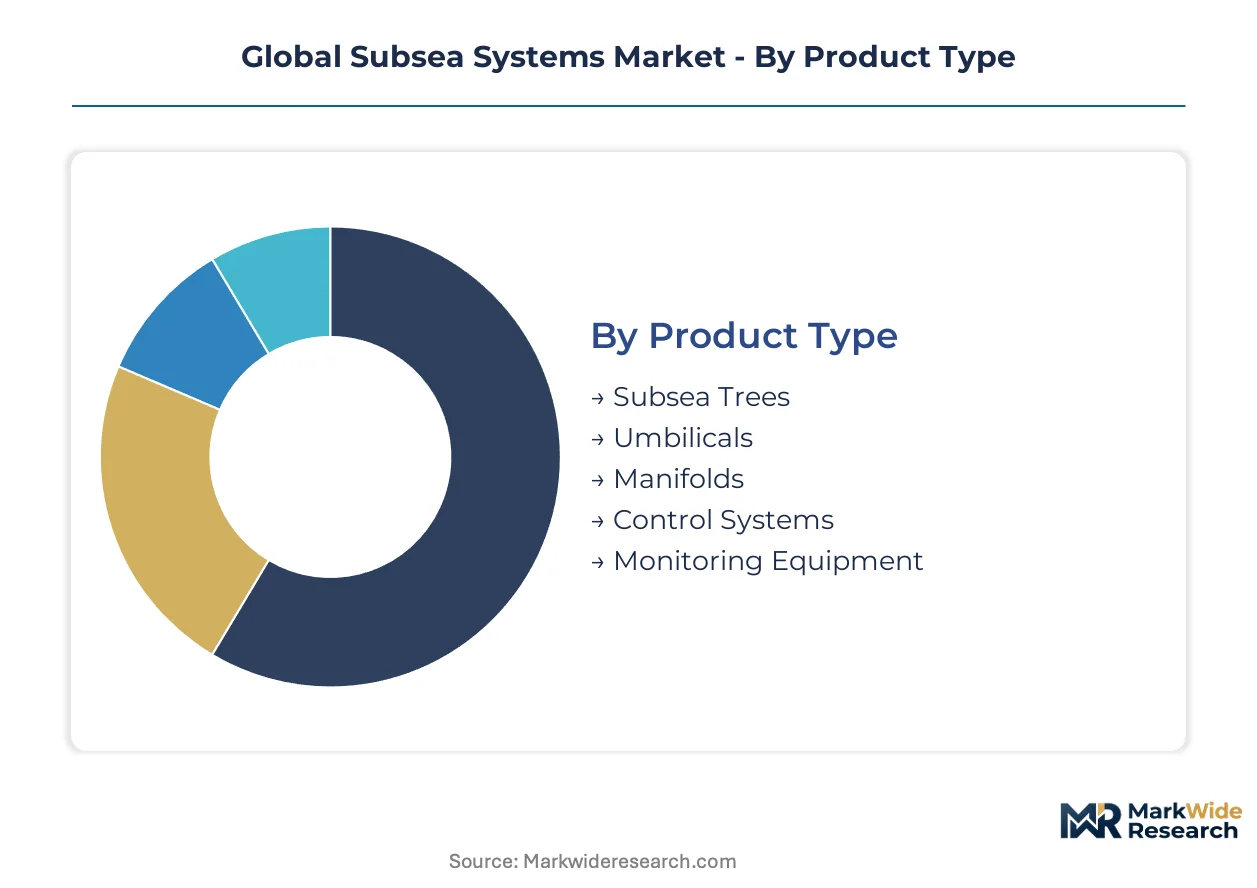
Subsea systems procurement varies dramatically by technical complexity and field architecture. Operators balance capital intensity against operational flexibility when specifying equipment across product categories and technology platforms.
Product Type:
Standardization concentrates in high-volume commodity equipment while custom engineering dominates pressure-rated assemblies.
- Subsea Trees:Wellhead-mounted assemblies control hydrocarbon flow through master valves, wing valves, and choke mechanisms rated for extreme pressure and temperature. Petrobras pre-salt developments in Brazil are driving tree procurement at volumes exceeding North Sea field totals by multiples, though Norwegian suppliers retain specification influence through integrated service contracts.
- Umbilicals:Bundled hydraulic, electrical, and fiber-optic lines connect subsea equipment to surface facilities, with line counts expanding rapidly under electrification mandates. Brazil and West Africa developments are specifying power-from-shore umbilicals with integrated high-voltage conductors, forcing manufacturers to qualify new armoring and insulation chemistries ahead of EU F-Gas Regulation deadlines.
- Manifolds:Seabed structures gathering flow from multiple wells into export pipelines.
- Control Systems:Electro-hydraulic and all-electric architectures governing subsea valve actuation.
- Monitoring Equipment:Sensors and autonomous inspection platforms tracking flow assurance and structural integrity.
Most installed capacity flows through Subsea Trees. Expansion is steepest in Umbilicals.
Technology:
Technology selection tracks water depth, with deeper reservoirs demanding lighter, more reliable actuation methods.
- Electro-Hydraulic:Dominant installed base combining electrical control signals with hydraulic power transmission for valve actuation. North Sea brownfield tiebacks continue specifying this proven architecture despite weight penalties, as Equinor and other operators prioritize operational certainty over marginal installation cost savings in harsh Atlantic conditions.
- Electro-Mechanical:All-electric actuation eliminating hydraulic fluid columns and reducing umbilical diameter by half. Shell and TotalEnergies are specifying this technology for Lower Tertiary developments in the Gulf of Mexico, where 3,000-meter water depths make hydraulic umbilical weight prohibitive and reliability requirements exceed electro-hydraulic fault tolerance.
- Fiber Optic:High-bandwidth communication lines for subsea distributed sensing and real-time monitoring.
- Acoustic:Wireless control and data transmission for interventions where umbilical connection is impractical.
- Hydraulic:Legacy direct-hydraulic actuation retained in shallow-water marginal fields.
Electro-Hydraulic retains the largest installed footprint. Electro-Mechanical is climbing the fastest as deepwater sanctioning accelerates.
Application:
Application segmentation reflects reservoir characteristics and development economics rather than equipment differences alone.
- Offshore Oil Extraction:Primary revenue driver encompassing subsea production systems for crude oil reservoirs. Brazil's pre-salt carbonate formations are generating tree and manifold demand at scale unmatched since North Sea peak development, with Petrobras alliance frameworks concentrating procurement among integrated engineering contractors.
- Deepwater Exploration:Frontier developments beyond 1,500 meters requiring specialized high-pressure high-temperature equipment. US Gulf of Mexico Lower Tertiary and West African pre-salt analogs are pushing specification boundaries for metallurgy, sealing, and insulation systems, with qualification timelines extending procurement cycles.
- Natural Gas Processing:Subsea compression and separation systems for gas-condensate fields.
- Pipeline Monitoring:Flow assurance and integrity management systems for export infrastructure.
- Marine Research:Scientific seabed observatories and oceanographic instrumentation.
Offshore Oil Extraction commands the dominant share of capital deployment. Deepwater Exploration is expanding most quickly as supermajors replenish depleting portfolios.
End User Industry:
Customer concentration varies by project scale and contracting structure across the value chain.
- Energy Corporations:Supermajors and national oil companies holding reservoir access and development rights. Equinor, Petrobras, and Shell are consolidating procurement through long-term alliance frameworks that bundle engineering, equipment supply, and installation services, compressing vendor count and elevating performance guarantees.
- Offshore Contractors:Engineering-procurement-construction firms executing field developments on behalf of operators. TechnipFMC and Subsea 7 are leveraging integrated capabilities to capture bundled contracts in Brazil and Norway, while specialist contractors compete for component supply outside alliance structures.
- Marine Engineering Firms:Niche technical service providers for installation and intervention operations.
- Environmental Agencies:Regulatory bodies and research institutions monitoring seabed conditions and decommissioning compliance.
Energy Corporations direct the majority of specification authority. Offshore Contractors are gaining procurement influence through integrated service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized subsea controls engineers cluster around Stavanger, Aberdeen, and Houston, anchoring Atlantic basin project execution capacity. These workforce concentrations shape where operators locate engineering centers and where suppliers maintain technical service hubs.
Brazil
Petrobras pre-salt carbonate developments are driving tree, manifold, and umbilical procurement volumes unmatched since North Sea peak production. ANVISA and environmental licensing requirements govern offshore equipment certification timelines. The Santos Basin cluster near Rio de Janeiro concentrates fabrication yards and subsea installation vessel mobilization points.
Norway
Equinor's platform decommissioning and tieback conversion programs are accelerating demand for umbilical upgrades and subsea power distribution units. The Petroleum Safety Authority enforces operational safety and emissions accountability standards across the continental shelf. Stavanger anchors engineering talent pools for electro-hydraulic and all-electric actuation system design.
United States
Shell and other operators are specifying electro-mechanical trees for Lower Tertiary developments in the Gulf of Mexico where 3,000-meter depths exceed hydraulic umbilical weight limits. EPA and OSHA frameworks shape emissions accountability and equipment certification requirements. Houston hosts engineering-procurement-construction headquarters for integrated service contract execution.
China
MEE guidelines are beginning to influence subsea monitoring equipment standards for autonomous inspection and predictive maintenance systems. Emerging domestic qualification programs target subsea processing module localization. The Yangtze River Delta cluster is developing fabrication capacity for standardized subsea processing skids.
United Kingdom
Aging North Sea infrastructure requires retrofit electrification and umbilical upgrades to support platform decommissioning timelines. REACH and offshore equipment directives govern material recertification for pipeline insulation and sealing systems. Aberdeen maintains subsea controls engineering expertise despite workforce retirement pressures.
Global Subsea Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across bundled engineering-procurement-installation contracts and component supply niches. The vendor base organizes into three tiers: integrated service providers capturing alliance frameworks, technology specialists anchoring specific product categories, and regional fabricators serving installation and maintenance demand. Two dominant competitive moves are reshaping positioning: strategic partnerships bundling engineering accountability with life-of-field service guarantees, and technology licensing arrangements accelerating electro-mechanical system qualification.
Among integrated engineering contractors, TechnipFMC exemplifies the bundled service model through its engineering-to-installation capability spanning Atlantic and Latin American developments. Aker Solutions occupies a position within the low-global-warming-potential insulation technology tier, with proprietary platforms purpose-built for North Sea and Atlantic basin regulatory conditions. Subsea 7 represents the installation-specialist archetype, leveraging heavy-lift and reel-lay vessel fleets to capture project execution roles outside alliance structures.
| Leading Market Players |
|---|
| TechnipFMC |
| Subsea 7 |
| Aker Solutions |
| OneSubsea |
| Dril-Quip |
| Baker Hughes |
| Schlumberger |
| Oceaneering International |
| National Oilwell Varco |
| Others |
Supply & Pricing Matrix
Titanium forgings from Austrian and Japanese metallurgical specialists flow through three pricing tiers before reaching subsea tree manufacturers, with high-grade steel alloys commanding premium positions against commodity pressure-rated components. Bundled engineering-procurement-installation contracts absorb upstream volatility through long-term alliance frameworks, while component specialists face spot-market exposure.
Pricing Analysis
Bundled service contracts dominate Atlantic basin developments, with integrated suppliers capturing premium pricing through performance guarantees while component specialists compete on unit cost. Price differentiation rests on certification grade—REACH-compliant low-global-warming-potential insulation commands tier-one positioning against legacy fluorinated formulations—and volume scale, where Petrobras pre-salt procurement aggregates demand for preferential terms. Pricing pressure stems from installation vessel scarcity inflating project economics, squeezing margins at the standard tier. National oil companies exhibit lowest price sensitivity due to reservoir scale and alliance lock-in, while mid-size independents remain most exposed to unit-cost volatility.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Austrian metallurgical specialists for pressure-rated titanium forgings and corrosion-resistant alloys, with limited surge capacity amplifying disruption risk. Manufacturing concentrates in Norway, Brazil, and the United States, drawing from concentrated upstream inputs including high-grade steel, specialty elastomers, and fiber-optic conductors. Supply chain risk centers on regulatory restriction—the EU F-Gas Regulation's phasedown timeline accelerates material transitions before qualified alternatives achieve thermal parity. Distribution runs through engineering-procurement-construction headquarters in Stavanger, Rio de Janeiro, and Houston, with fabrication yards clustered near installation vessel mobilization points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electrification-driven umbilical upgrades and REACH-compliant material platforms, where regulatory tailwinds support premium-tier positioning against legacy insulation chemistries.
For Market Incumbents: Anchor market position through captive supply of low-global-warming-potential insulation platforms ahead of EU F-Gas Regulation deadlines, while deepening installation vessel alliances to lock in project execution capacity against emerging contractor competition. Defend against electro-mechanical displacement by embedding electro-hydraulic expertise into brownfield service contracts with extended maintenance terms. For New Entrants and Emerging Players: Enter via standardized subsea processing skids targeting mid-size independents excluded from custom-engineered developments, where modular architectures bypass integrated supplier lock-in. Focus initial penetration on China's Yangtze River Delta fabrication cluster, where domestic qualification programs for processing modules create first-mover certification pathways under emerging MEE guidelines. For Investors and Strategic Acquirers: Consolidation pressure builds where electro-hydraulic engineering expertise concentrates among retiring workforce cohorts in Norway and Scotland, creating acquisition scarcity value for specialized controls capabilities. Long-term viability favors vendors with demonstrated REACH compliance and Brazilian alliance access. Watch electro-mechanical qualification velocity as the inflection signal—accelerated adoption beyond Lower Tertiary developments indicates structural architecture shift.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Platform | First-mover certification under EU F-Gas Regulation secures Atlantic basin procurement preference through 2030 deployment windows. |
| Installation Vessel Alliance | Heavy-lift capacity lock-in with Subsea 7 or equivalent captures Brazilian pre-salt project execution roles outside spot markets. |
| Electro-Mechanical Qualification | All-electric actuation certification for 3,000-meter depths opens Lower Tertiary and pre-salt frontier developments. |
| Brownfield Electrification Service | Umbilical upgrade bundling with North Sea platform decommissioning timelines captures Equinor tieback conversion demand. |
| Autonomous Inspection Certification | EU AI Act pathway completion for predictive maintenance robotics differentiates monitoring equipment offerings. |
Research Methodology
Coverage spans Brazil, Norway, the United States, the United Kingdom, and China, with primary inputs from each region combining interviews with subsea controls engineers, procurement leads at national oil companies, EPC contract managers, and aftermarket service heads with secondary validation. Secondary sources include SEC filings from integrated engineering contractors, ANVISA certification databases, Petroleum Safety Authority incident reports, and customs data on high-grade steel imports. Bottom-up project sanctioning tallies triangulate against top-down equipment category spend estimates.
Rate-of-change decomposition separates volume growth in tree and umbilical procurement from value expansion in electrification and material compliance premiums across the projection horizon. Segmentation dimensions modeled include product type, actuation technology, water depth tier, and regulatory framework cluster. CAGRs derive from weighted project sanctioning timelines and equipment lead time adjustments. Industry-specific inputs encompass Petrobras alliance contract structures and EU F-Gas Regulation phase-down schedules.
Inputs from ANVISA, the Petroleum Safety Authority, and EPA filings were available through the study window; gaps in Chinese MEE guideline finalization introduce uncertainty bands around autonomous inspection certification timelines. Forecasts reflect assumptions on pre-salt development continuity and vessel availability recovery. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market