
 Liquefied Natural Gas Market | 2026-2036
Liquefied Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Liquefied Natural Gas Market Outlook
Utility buyer concentration is hardening across Asian power markets, with state-backed generators consolidating long-term procurement into fewer, larger tenders. Shell plc leverages its integrated trading arm to capture margin across liquefaction, shipping, and regasification nodes. QatarEnergy anchors supply security through North Field expansion capacity, while Cheniere Energy, Inc. competes on Gulf Coast feedstock cost and destination-flexible contracting.
Liquefied natural gas is natural gas cooled to approximately minus 162 degrees Celsius, reducing volume by a factor of 600 for intercontinental marine transport in cryogenic carriers. The process enables cost-efficient movement of methane from stranded reserves to demand centers lacking pipeline connectivity. Liquefaction terminals dominate capital deployment and margin capture, while small scale LNG shows the fastest infrastructure growth for bunkering and remote industrial supply. Floating LNG occupies a niche in pre-salt and marginal field development where onshore construction faces geographic or political constraints.
The US Federal Energy Regulatory Commission governs LNG export terminal siting and environmental review, while the International Maritime Organization shapes vessel design and fuel standards through the IGF Code and carbon intensity regulations. The EU F-Gas Regulation and methane emission rules under the EU Green Deal are tightening lifecycle accountability for gas sold into European terminals. Stakeholders must monitor how divergent carbon border treatments between the US, European Union, and China reshape contract pricing and source-of-origin certification requirements.
Market Dynamics
Asian power utilities are consolidating procurement into mega-tenders that favor suppliers with integrated liquefaction-to-regasification capabilities, compressing margins for pure-play traders and rewarding asset-heavy portfolios.
Growth Catalysts
- IMO 2023 sulfur caps:The International Maritime Organization's marine fuel regulations are forcing container lines and bulk carriers to convert engine systems to LNG propulsion, expanding bunkering demand at Rotterdam, Singapore, and Shanghai port clusters.
- China's provincial network buildout:State-owned distributors are extending cryogenic pipeline infrastructure into inland manufacturing provinces, connecting stranded industrial demand to coastal import terminals.
- Combined-cycle gas turbine efficiency gains:Advanced turbine designs achieving 62% thermal efficiency are electrifying power sector interest in LNG baseload replacement of coal plants across Korea, Japan, and Taiwan.
Market Restraints
- Henry Hub price volatility:US Gulf Coast feedstock costs swing with domestic shale production cycles, exposing long-term offtake contracts to margin erosion when domestic gas prices spike.
- Qatari supply concentration:The North Field expansion will concentrate 40% of incremental global liquefaction capacity in one geography, creating single-source dependency risk for European and Asian buyers.
- Carbon border adjustment friction:The EU Green Deal's methane emission certification requirements are creating non-tariff barriers to US and Russian supply, fragmenting contract standardization.
Strategic Opportunities
- Vietnam's power shortage corridor:Northern industrial provinces face 10-15% electricity deficits, creating first-mover advantage for floating storage and regasification unit deployment at Thi Vai and Son My.
- Small-scale LNG bunkering:Truck-to-ship and ship-to-ship transfer infrastructure at Antwerp and Hamburg is opening new revenue pools for regional distributors with cryogenic logistics expertise.
- EU F-Gas Regulation methane accounting:Lifecycle emission disclosure mandates are favoring suppliers with certified low-leakage liquefaction technology, creating premium pricing tiers for compliant cargoes.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized welding and process safety expertise for minus 162 degree Celsius systems is concentrated among retiring cohorts at legacy liquefaction facilities.
- Regasification terminal permitting timelines:US Federal Energy Regulatory Commission environmental review cycles now exceed 48 months for greenfield projects, delaying capacity additions needed for 2028-2030 demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquefied Natural Gas Market |
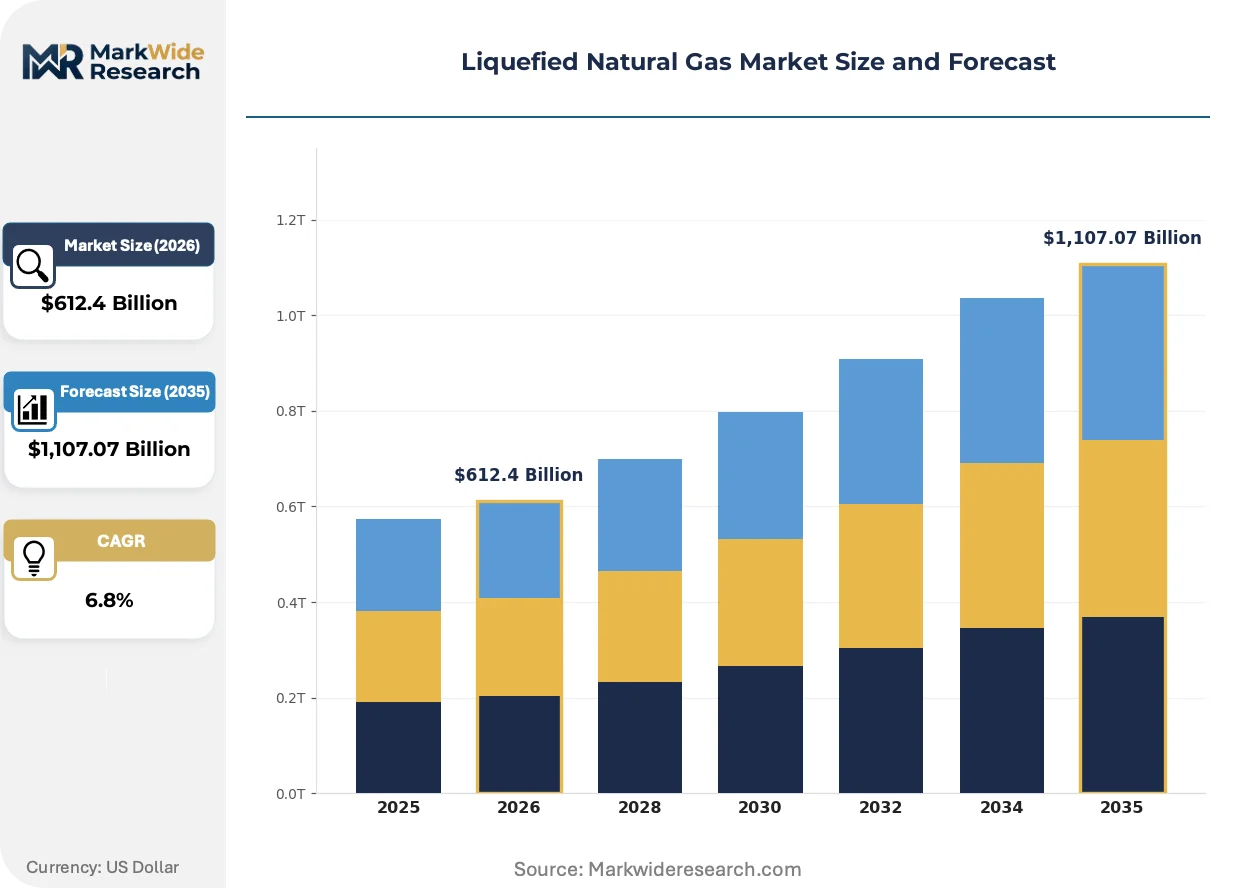
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Scale LNG, Floating LNG, Liquefaction Terminals, Regasification Terminals End User: Power Generation, Industrial Applications, Transportation, Residential Heating Distribution Channel: Pipelines, Shipping, Trucking, On-site Delivery Application: Fuel Supply, Energy Generation, Petrochemical Industry, Export |
| Companies Covered | Shell plc, ExxonMobil Corporation, TotalEnergies SE, BP p.l.c., Chevron Corporation, QatarEnergy, Cheniere Energy, Inc., Equinor ASA, ConocoPhillips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquefied Natural Gas Market Strategic Shifts
Modular liquefaction technology and carbon intensity tracking systems are compressing project development cycles and reshaping how buyers evaluate supply source competitiveness beyond delivered cost alone.
Electric drive liquefaction trains are electrifying the efficiency frontier in greenfield export terminals. ConocoPhillips and other engineering firms are deploying variable-speed motors to replace gas turbine drivers, cutting parasitic fuel consumption by 15-20%. QatarEnergy's North Field East project is adopting this configuration, setting a new performance benchmark that Gulf Coast competitors must match to maintain contract win rates.
The EU F-Gas Regulation and methane emission rules under the EU Green Deal are tightening lifecycle accountability for gas sold into European terminals. Importers must now document upstream leakage rates and liquefaction carbon intensity, with non-compliant cargoes facing carbon border adjustment penalties. This is forcing US exporters to invest in certified low-emission production and optical gas imaging monitoring systems to preserve market access.
Utility procurement teams are unbundling long-term offtake contracts into volume-flexible, destination-clause-free structures that mirror spot market liquidity. Japanese power utilities led this shift post-Fukushima, and Korean and Taiwanese buyers are now demanding similar terms. The change compresses trader margins while rewarding suppliers with diversified liquefaction assets and chartered shipping fleets that can pivot between Atlantic and Pacific basin price arbitrage.
Liquefied Natural Gas Market Segmentation
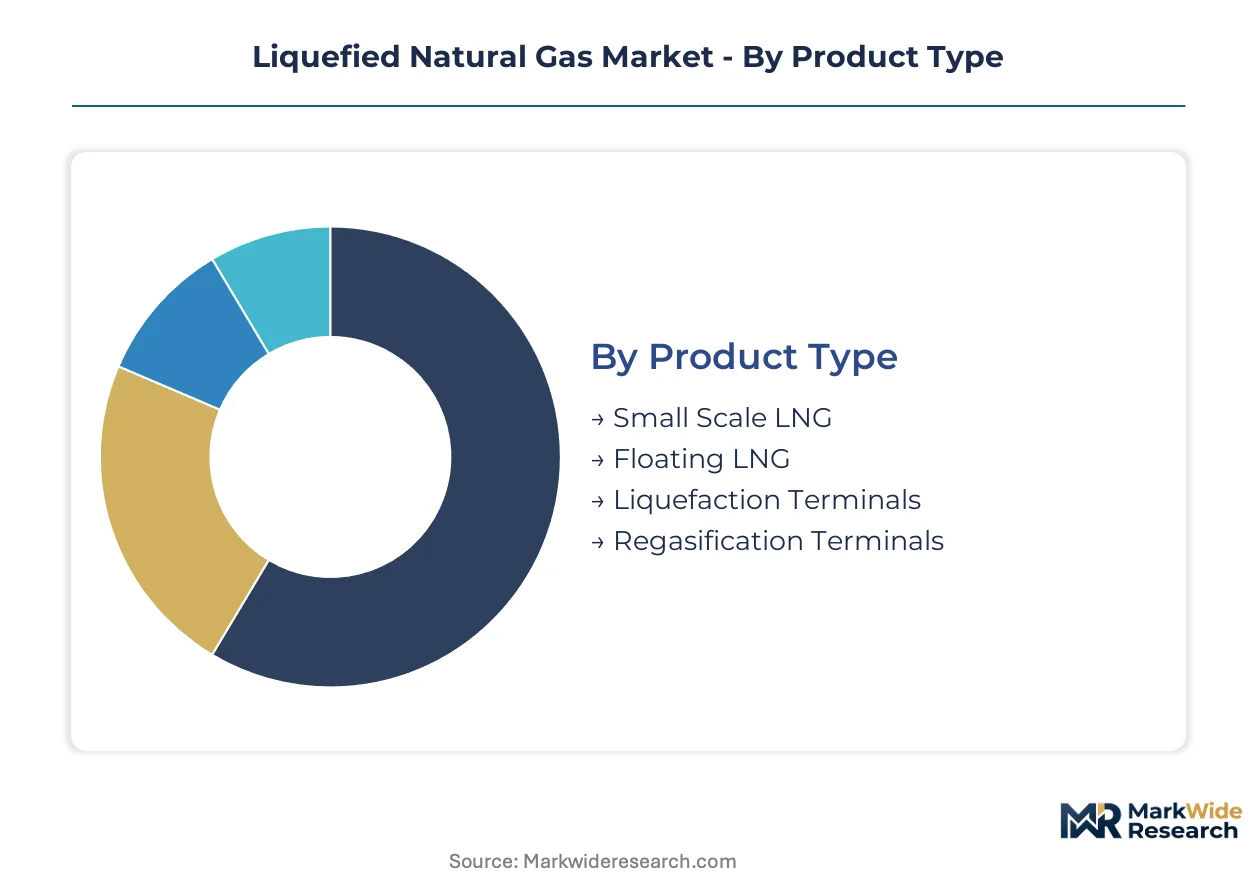
Segmentation in LNG markets separates infrastructure-heavy liquefaction assets from nimble distribution modes. Understanding these divides clarifies where capital concentrates and where margin compression threatens.
Product Type:
Liquefaction terminals command premium valuations through integrated margin capture, while small-scale LNG trades volume accessibility against unit cost premiums.
- Liquefaction Terminals:These facilities cool feedstock gas to minus 162 degrees Celsius using multi-stage refrigeration cycles. QatarEnergy's North Field East and Gulf Coast projects anchor supply growth in Qatar and the United States, with destination-flexible contracts commanding price premiums over oil-indexed alternatives.
- Small Scale LNG:Modular liquefaction and truck-to-ship bunkering infrastructure serves stranded industrial demand and marine fuel conversion. Rotterdam, Singapore, and Shanghai port clusters are expanding truck-to-ship transfer capacity to capture IMO 2023 compliance-driven vessel conversions.
- Regasification Terminals:Coastal import facilities vaporize cryogenic cargo for pipeline injection.
- Floating LNG:Offshore liquefaction vessels target pre-salt and marginal fields where onshore construction faces geographic constraints.
Today's leader: Liquefaction Terminals. Tomorrow's challenger: Small Scale LNG.
End User:
Power generators dominate contract volumes, yet transportation is climbing fastest on marine fuel regulation.
- Power Generation:Combined-cycle gas turbines achieving 62% thermal efficiency are electrifying Asian utility procurement. State-backed generators in Korea, Japan, and Taiwan are consolidating tenders into mega-contracts that favor integrated suppliers.
- Transportation:Container lines and bulk carriers are retrofitting engines to meet IMO 2023 sulfur caps. Bunkering demand at Antwerp, Hamburg, and Singapore is accelerating infrastructure buildout for LNG marine fuel.
- Industrial Applications:Glass, ceramics, and chemical manufacturers switch from coal to gas where pipeline connectivity permits.
- Residential Heating:Provincial distributors in China extend cryogenic networks into inland manufacturing belts.
Power Generation anchors current volumes. Transportation is gaining share fastest on regulatory compliance deadlines.
Distribution Channel:
Shipping captures intercontinental value, while trucking unlocks last-mile flexibility at higher unit cost.
- Shipping:Specialized cryogenic carriers with membrane or spherical containment systems move 600-times-compressed methane across basins. Chartered fleets with destination flexibility command arbitrage premiums in volatile price environments.
- Pipelines:Regasified gas moves through high-pressure transmission networks to demand centers.
- Trucking:Cryogenic tanker trailers serve remote industrial sites and bunkering nodes lacking pipeline connectivity.
- On-site Delivery:Dedicated small-scale liquefaction serves isolated mining and drilling operations.
Shipping dominates value capture. Trucking is expanding most quickly into bunkering corridors.
Application:
Fuel supply and energy generation split the market, with petrochemical feedstock emerging as a volume growth vector.
- Fuel Supply:Marine bunkering and remote power generation drive small-scale infrastructure deployment. Port clusters at Rotterdam, Singapore, and Shanghai are prioritizing LNG fueling capacity to capture vessel traffic.
- Energy Generation:Baseload power replacement of coal plants concentrates demand in Asian markets with carbon reduction commitments.
- Petrochemical Industry:Ethane and propane extraction from LNG feedstock supports olefin production.
- Export:Destination-flexible contracting enables arbitrage between Atlantic and Pacific basin price differentials.
Fuel Supply leads current investment. Petrochemical Industry holds the steepest expansion trajectory on feedstock demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic engineers and process safety experts cluster around legacy liquefaction hubs in Qatar, the United States, and Australia, anchoring regional capacity expansion decisions.
United States
Gulf Coast petrochemical demand and power utility procurement are absorbing record export volumes from Louisiana and Texas terminals. The Federal Energy Regulatory Commission governs siting and environmental review for new liquefaction capacity, with review cycles now exceeding 48 months. The Port of Corpus Christi anchors small-scale bunkering infrastructure buildout for IMO 2023 compliance.
Qatar
North Field expansion capacity underpins supply security commitments to Asian and European offtakers. QatarEnergy leverages state-backed financing to capture integrated margin across liquefaction, shipping, and regasification. Ras Laffan Industrial City concentrates cryogenic engineering talent and modular construction expertise for greenfield train deployment.
China
Provincial gas distribution networks are extending into inland manufacturing belts, connecting stranded industrial demand to coastal import terminals. The Ministry of Ecology and Environment enforces methane emission monitoring standards under dual carbon goals. Yangtze River Delta port clusters are prioritizing LNG bunkering capacity to capture container line traffic.
Japan
Utility procurement teams are unbundling long-term offtake contracts into volume-flexible, destination-clause-free structures. METI oversees energy security policy and import diversification requirements. Tokyo Bay and Osaka Bay regasification terminals are retrofitting for spot market cargo flexibility.
Germany
Industrial gas demand from chemicals and steel sectors is accelerating floating storage and regasification unit deployment at Wilhelmshaven and Brunsbüttel. The EU F-Gas Regulation and methane emission rules under the EU Green Deal tighten lifecycle accountability for terminal imports. Hamburg port authorities are expanding truck-to-ship bunkering infrastructure for Baltic Sea vessel traffic.
Liquefied Natural Gas Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across liquefaction, trading, and regasification nodes. The market structure concentrates around integrated players with captive upstream reserves and chartered shipping fleets, compressing margins for asset-light traders. Two dominant archetypes emerge: state-backed national champions with preferential reserve access, and independent exporters competing on feedstock cost and contract flexibility. Capacity expansion and destination-flexible contracting represent the primary competitive moves reshaping contract win rates.
Among state-backed national champions, QatarEnergy anchors supply security through North Field expansion capacity. Shell plc and Cheniere Energy, Inc. occupy positions within the integrated trading and independent exporter archetypes respectively, with the former leveraging global trading arms and the latter competing on Gulf Coast Henry Hub-linked pricing.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| TotalEnergies SE |
| BP p.l.c. |
| Chevron Corporation |
| QatarEnergy |
| Cheniere Energy, Inc. |
| Equinor ASA |
| ConocoPhillips |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal methane certification requirements gate qualified supply and premium-tier pricing access for cargoes entering European terminals. Buyers lacking certified low-leakage documentation face carbon border adjustment penalties that compress their contract win rates against compliant competitors.
Pricing Analysis
Bundled liquefaction-to-regasification services command premiums over unbundled spot trading. Contract structures stratify across oil-indexed long-term offtake, Henry Hub-linked flexible pricing, and destination-clause-free spot equivalents. Price differentiation hinges on carbon intensity certification and volume scale commitments. Pricing pressure stems from Asian utility mega-tenders that compress trader margins. Pure-play trading houses show highest price sensitivity; integrated majors with captive reserves and chartered fleets absorb pressure through arbitrage flexibility.
Supply Chain Analysis
Marine freight costs swing with charter rates for membrane and spherical containment carriers, amplifying delivered cost volatility between Atlantic and Pacific basins. Liquefaction capacity concentrates in Qatar, the United States, and Australia. Feedstock gas, specialized cryogenic steel, and electric drive compressor systems anchor component dependencies. Single-source vulnerability runs through Qatari supply concentration from North Field expansion. Distribution runs through long-term chartered fleets with destination flexibility, supplemented by spot market vessel procurement during price arbitrage windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through electric drive liquefaction technology adoption that cuts parasitic fuel consumption. Premium-tier shifts toward certified low-emission cargoes reward early compliance investment with pricing power in EU terminals.
For Market Incumbents: Extend destination-flexible contracting capabilities to capture Asian utility mega-tender volumes. Add modular liquefaction capacity at Gulf Coast sites before FERC permitting timelines lengthen further. Electric drive train adoption at greenfield projects defends margin position against QatarEnergy efficiency benchmarks. Backward integration into certified low-leakage production preserves EU market access under tightening methane rules.
For New Entrants and Emerging Players: Launch via small-scale LNG bunkering infrastructure at Rotterdam, Singapore, or Shanghai port clusters. Vietnam's northern power shortage corridor offers penetrable demand for floating storage and regasification deployment. Truck-to-ship transfer services at Antwerp and Hamburg present white-space revenue pools. Target cryogenic logistics partnerships with regional distributors lacking marine fuel expertise.
For Investors and Strategic Acquirers: Roll-up economics work for small-scale LNG distributors because bunkering demand fragmentation resists consolidation by integrated majors. Five-to-ten year viability favors asset-heavy positions with chartered fleet access and multi-basin arbitrage capability. Acquisition targets should show cryogenic logistics expertise and port authority relationships. Watch IMO marine fuel enforcement stringency as inflection indicator for bunkering infrastructure returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Liquefaction Deployment | QatarEnergy's North Field East adoption sets efficiency benchmarks competitors must match. |
| Destination-Flexible Contracting Expansion | Japanese utility unbundling demands volume-flexible structures mirroring spot liquidity. |
| Small-Scale Bunkering Infrastructure Buildout | Rotterdam port cluster expansion captures IMO 2023 vessel conversion demand. |
| Methane Certification Investment | EU F-Gas Regulation compliance preserves premium-tier access for US exporters. |
| Floating Storage and Regasification Deployment | Vietnam's Thi Vai terminal addresses northern industrial province electricity deficits. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from utility procurement officers, LNG trading desk heads, EPC contractors, and FERC regulatory specialists. Secondary validation drew from EIA production data, IEA market reports, FERC environmental filings, and Lloyd's List vessel tracking databases. Bottom-up project capacity modeling and top-down demand aggregation triangulated volume estimates across the analysis window.
Historical reference periods anchored demand growth assumptions against power sector coal displacement trends and marine fuel conversion timelines. The forecast framework segmented by liquefaction terminal scale, small-scale distribution mode, power generation versus transportation end-use, and regional regulatory cluster. CAGRs derived from project pipeline commissioning schedules and offtake contract tenor analysis. Henry Hub price volatility and carbon border adjustment implementation pace served as key sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical supply disruption or accelerated green hydrogen substitution in European power markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Frac Tree Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Downhole Motor Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Oil and Gas Separation Equipment Market