
 Oil and Gas Downstream Market | 2026-2036
Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Downstream Market Analytics
Product-service bundling in refining contracts is decoupling as buyers demand unbundled tolling arrangements with transparent margin splits. Saudi Aramco leverages its crude production scale to anchor long-term offtake agreements with Asian buyers. ExxonMobil sustains technology leadership through proprietary hydrocracking catalyst systems. Royal Dutch Shell competes by positioning its Singapore and Rotterdam hubs as global trading and blending arbitrage centers.
Oil and gas downstream operations transform crude petroleum into finished fuels and petrochemical feedstocks through fractional distillation, catalytic cracking, and hydrotreating processes operating at temperatures exceeding 400°C and pressures above 100 bar. Refining margins fluctuate with crack spreads between crude acquisition costs and product slate realizations across gasoline, diesel, and jet fuel outputs. Hydrocracking technology leads capital deployment as refiners process heavier sour crudes into middle distillates with higher cetane and lower sulfur content. Catalytic reforming occupies a mature but essential role in octane enhancement for gasoline blending pools where aromatics specifications tighten.
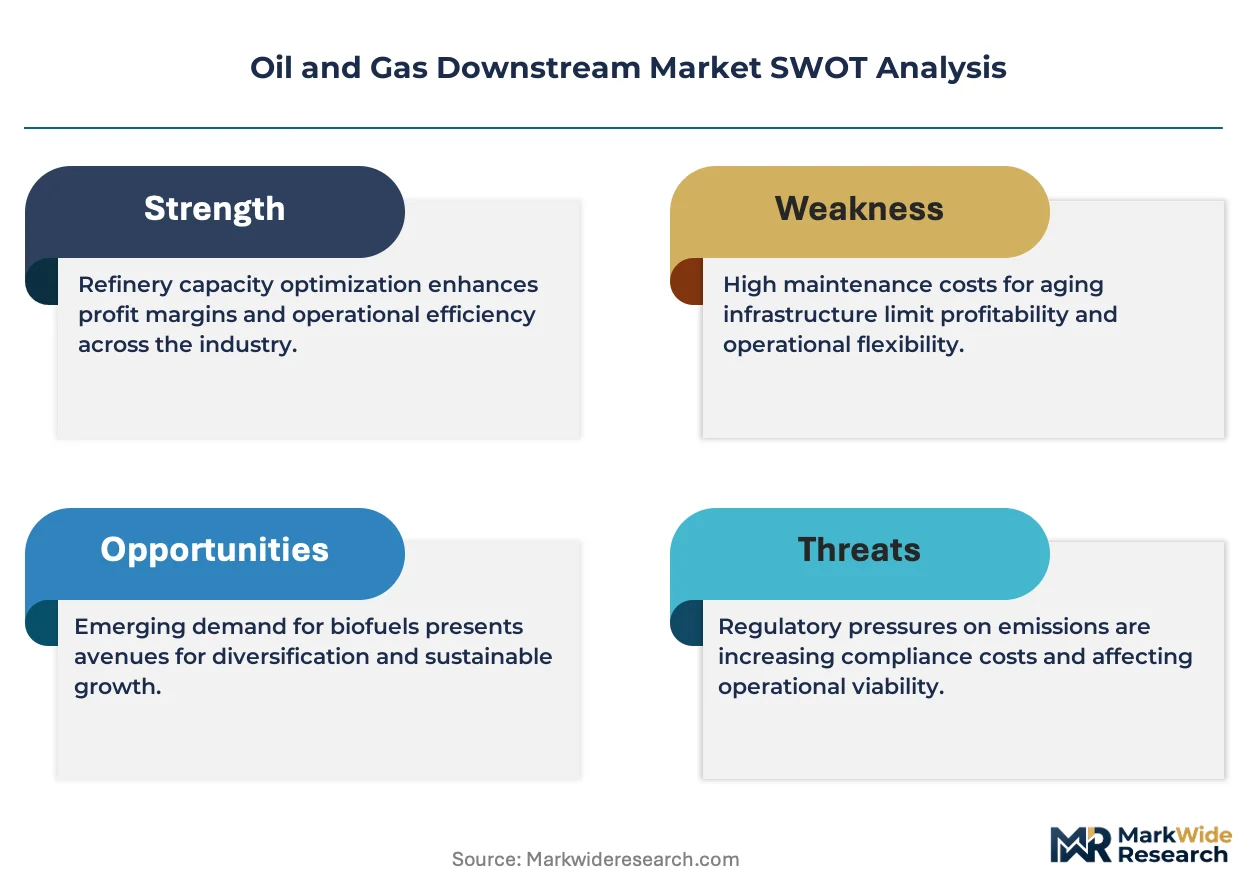
The US EPA enforces Tier 3 gasoline sulfur limits at 10 parts per million, compelling refiners to invest in additional hydrotreater capacity or face product exclusion from the country's largest transport fuel market. The EU F-Gas Regulation and REACH framework constrain refinery process emissions and chemical handling protocols across European downstream assets. China's MEE implements dual carbon goals that mandate efficiency benchmarks and carbon intensity caps for coastal refining complexes. Stakeholders must monitor how carbon border adjustments and clean fuel standards in multiple jurisdictions reshape crude sourcing decisions and product slate optimization.
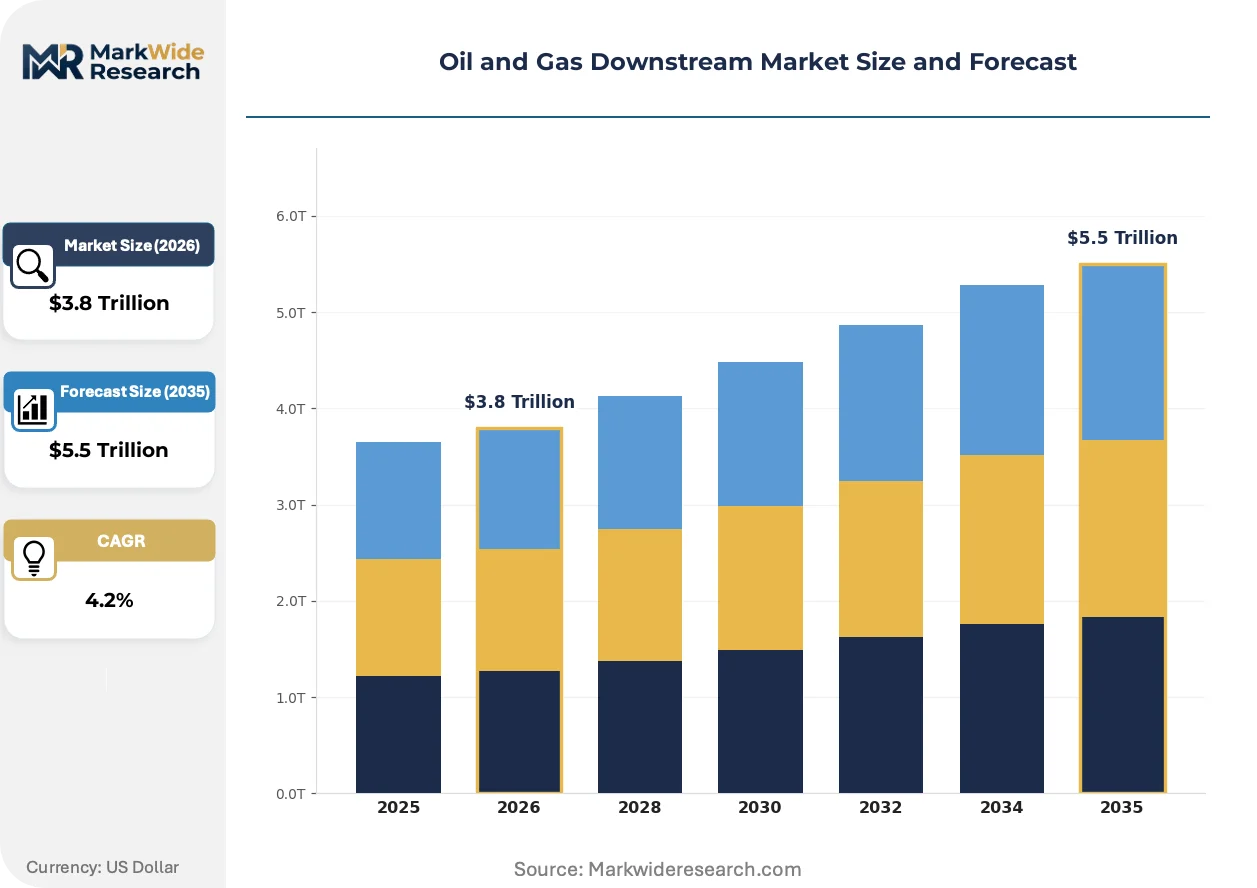
Market Dynamics
Transport fuel margin compression is forcing integrated refiners to pivot capacity toward petrochemical feedstocks, restructuring the traditional refining economics that governed downstream operations for decades.
Growth Catalysts
- China's dual carbon goals:The MEE mandates efficiency benchmarks and carbon intensity caps that accelerate refinery modernization investments across coastal complexes.
- Hydrocracking deployment:Advanced catalyst systems enable heavier sour crude processing into higher-cetane middle distillates, expanding accessible feedstock supply.
- Desulfurization mandates:US EPA Tier 3 sulfur standards at 10 parts per million compel hydrotreater capacity additions that upgrade product slate quality.
Market Restraints
- Crude slate volatility:Heavy sour crude price differentials fluctuate with OPEC+ production decisions, compressing crack spread predictability for complex refiners.
- Carbon border exposure:The EU Carbon Border Adjustment Mechanism threatens export competitiveness for refiners without verified emissions accounting systems.
- Electrification substitution:Battery electric vehicle penetration in passenger transport erodes long-term gasoline demand pools that anchor refinery economics.
Strategic Opportunities
- Circular feedstock integration:Chemical recycling of plastic waste into synthetic crude streams offers alternative raw material sourcing for integrated complexes.
- Hydrogen hub positioning:The US IRA production tax credits incentivize refinery retrofitting to serve as blue hydrogen production and offtake nodes.
- Biorefinery co-location:Renewable diesel and sustainable aviation fuel capacity additions at existing sites capture LCFS credit value in California and Oregon markets.
Industry Challenges
- Process control expertise scarcity:Advanced digital twin implementation requires instrumentation engineers with hybrid chemical engineering and data science competencies that command premium compensation.
- Turnaround complexity:Synchronized hydrotreater and reformer maintenance windows strain contractor availability, extending offline periods and deferring margin capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Downstream Market |
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.5 Trillion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refining, Retail, Distribution, Logistics Product Type: Gasoline, Diesel, Jet Fuel, Lubricants Application: Transportation, Heating, Power Generation, Industrial Use Technology: Hydrocracking, Catalytic Reforming, Alkylation, Desulfurization |
| Companies Covered | Saudi Aramco, ExxonMobil, Royal Dutch Shell, BP, Reliance Industries, China National Petroleum Corporation, Chevron, TotalEnergies, Valero Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Downstream Market Evolving Landscape
Digital instrumentation and advanced process control systems are compressing the latency between operational anomaly detection and corrective action, reshaping how refiners manage energy intensity and yield optimization.
Artificial intelligence-driven predictive maintenance is automating the identification of heat exchanger fouling and catalyst deactivation patterns before they degrade unit performance. Integrated majors deploy these systems across hydrocracking and catalytic reforming trains to compress unplanned shutdown frequency. The technology is automating the shift from time-based to condition-based turnaround scheduling, extending run lengths and deferring capital-intensive revamp cycles.
The EU F-Gas Regulation and REACH framework constrain refinery process emissions and chemical handling protocols across European downstream assets. These rules force reformulation of cooling and refrigeration chemistries while mandating comprehensive substance tracking through complex supply chains. Refiners in the Netherlands and Germany respond by consolidating chemical management under centralized EHS platforms that automate compliance documentation.
Buyers of refined products are fragmenting their supply relationships, rejecting bundled term contracts in favor of transparent tolling arrangements with explicit margin splits. Trading houses and independent marketers in Singapore and Rotterdam arbitrage this disaggregation by offering unbundled logistics, storage, and blending services. This behavioral shift concentrates pricing power with crude producers that anchor long-term offtake through integrated supply chain offerings.
Oil and Gas Downstream Market Segmentation
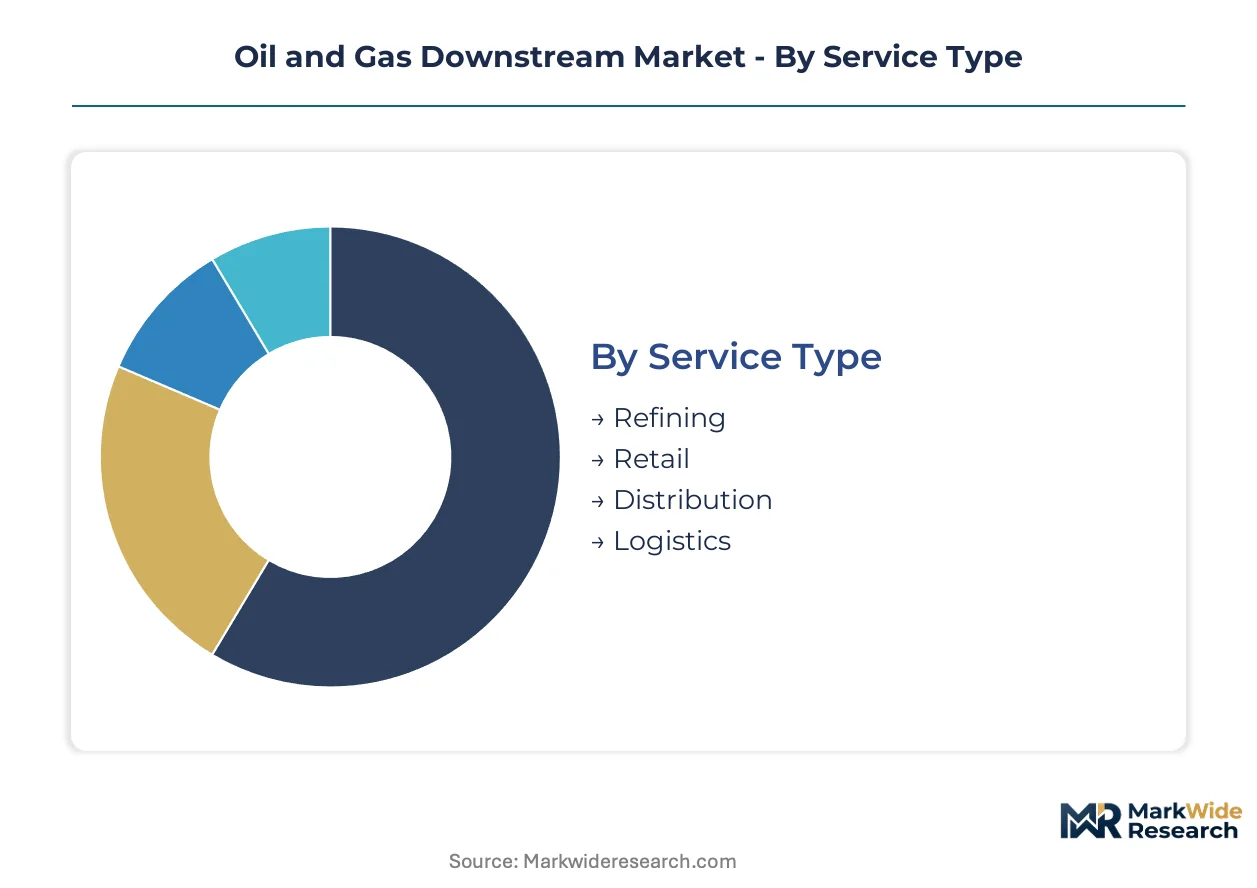
Downstream segmentation reveals how margin capture migrates across value chain nodes as transport fuel demand erodes. Refiners restructure asset configurations to concentrate capital where petrochemical integration and specialty product premiums offset commodity margin compression.
Service Type:
Volume concentrates in refining infrastructure while premium economics shift toward integrated logistics and retail branding.
- Refining:Fractional distillation, catalytic cracking, and hydrotreating operations transform crude into finished products at temperatures exceeding 400°C. Coastal complexes in China and the US Gulf Coast dominate capacity additions as integrated majors seek scale economies for heavy sour crude processing.
- Retail:Branded fuel stations and convenience store networks capture downstream margin through location-based pricing power and loyalty program data. Site rationalization accelerates in mature markets where electric vehicle penetration erodes throughput per station.
- Distribution:Midstream terminals, pipeline networks, and bulk storage facilities bridge refinery output with end-market delivery. Third-party access regulations in the EU and US force open-book tariff structures that compress incumbent returns.
- Logistics:Marine bunkering, railcar fleets, and trucking operations manage product flow timing and geographic arbitrage. Trading houses in Singapore and Rotterdam leverage floating storage and blending capabilities to capture crack spread volatility.
Today's leader: Refining. Tomorrow's challenger: Retail.
Product Type:
Application-driven demand splits between transport fuels facing electrification pressure and industrial products with structural growth anchors.
- Gasoline:Light distillate for passenger vehicle spark-ignition engines, requiring 87-94 octane ratings depending on market specifications. US EPA Tier 3 sulfur limits at 10 parts per million compel additional hydrotreater investment that elevates production costs.
- Diesel:Middle distillate serving compression-ignition engines in freight transport, agriculture, and marine applications. Cetane number specifications above 51 in Euro VI markets favor hydrocracking-derived production over straight-run distillation.
- Jet Fuel:Kerosene-range product meeting strict freeze point and smoke point specifications for aviation turbine engines. Sustainable aviation fuel co-processing at existing hydrocrackers offers LCFS credit capture in California and Oregon regulatory frameworks.
- Lubricants:Base oil blends and additive packages reducing friction in industrial machinery and automotive powertrains. Group II and Group III base oil upgrading commands premium pricing in manufacturing-intensive economies.
Diesel anchors current revenue density. Sustainable aviation fuel integration is expanding most quickly.
Application:
End-use concentration determines product slate optimization and regional capacity deployment priorities.
- Transportation:Road, rail, marine, and aviation fuel consumption representing the dominant demand pool for refined products. Battery electric vehicle penetration in passenger segments forces refiners to accelerate marine and aviation fuel diversification.
- Heating:Residential, commercial, and industrial fuel oil combustion for space conditioning and process heat. Building electrification mandates in Germany and the Netherlands accelerate demand erosion for middle distillate heating oils.
- Power Generation:Diesel and fuel oil firing in remote grids, backup systems, and peaking capacity. Dual-fuel turbine installations at industrial co-generation sites sustain residual demand as renewable penetration rises.
- Industrial Use:Feedstock inputs for petrochemical production, asphalt manufacturing, and metallurgical processes. Naphtha cracking margins in Asia determine refinery operating rates for integrated chemical complexes.
Transportation retains volume dominance. Industrial use is gaining share fastest.
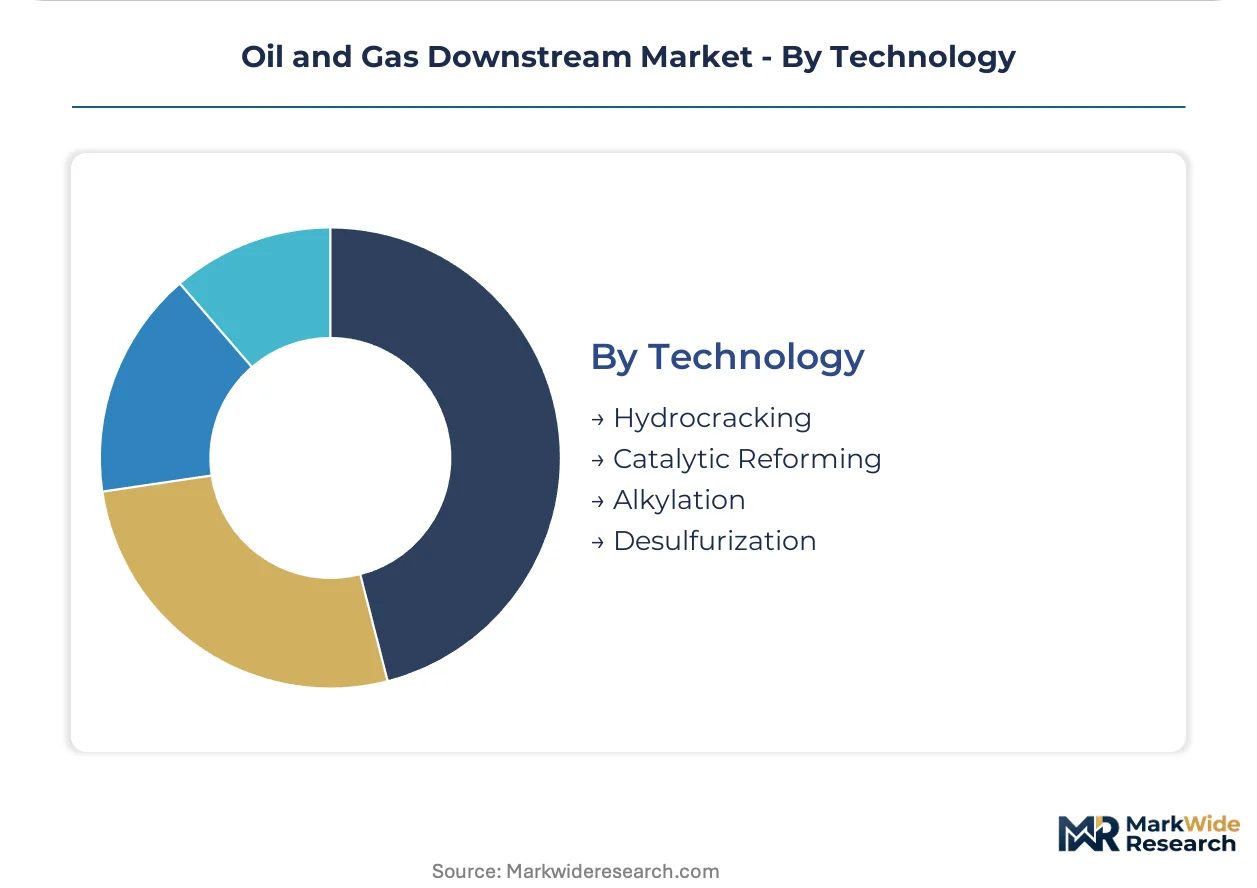
Technology:
Capital deployment prioritizes conversion depth and emissions compliance over incremental distillation capacity.
- Hydrocracking:High-pressure hydrogen addition cracking heavy vacuum gas oil into middle distillates with superior cetane and low sulfur content. Chevron, ExxonMobil, and Shell license proprietary catalyst systems that determine unit yields and cycle lengths.
- Catalytic Reforming:Platinum-rhenium catalyst platforms converting naphtha into high-octane reformate for gasoline blending pools. Aromatics extraction integration captures benzene, toluene, and xylene values for petrochemical feedstock markets.
- Alkylation:Acid-catalyzed combination of light olefins and isobutane producing high-octane, low-vapor-pressure gasoline blendstock. Sulfuric acid and hydrofluoric acid process variants face permitting constraints in densely populated refining corridors.
- Desulfurization:Hydrotreating and hydrodesulfurization units removing sulfur, nitrogen, and metals to meet product specifications. US EPA and Euro VI mandates drive capacity additions that consume hydrogen and compress clean product differentials.
Hydrocracking commands capital allocation. Alkylation faces regulatory headwinds as the challenger technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern refining traces its industrial lineage to the Pennsylvania oil boom of the 1860s, where fractional distillation first achieved commercial scale. Today's downstream geography reflects this evolution through concentrated coastal complexes that process heavier crudes into higher-value chemical feedstocks.
United States
Gulf Coast refineries process Permian Basin light sweet crude alongside imported heavy sour barrels for export-oriented product slates. The US EPA Tier 3 sulfur standards at 10 parts per million compel hydrotreater investments across the PADD 3 refining corridor. Houston and Port Arthur anchor the world's largest concentration of complex coking capacity.
China
Coastal refining hubs in Zhejiang and Guangdong provinces drive mega-complex investments that integrate petrochemical production with fuel manufacturing. The MEE dual carbon goals mandate efficiency benchmarks and carbon intensity caps for new refinery approvals. Zhoushan and Dalian host integrated complexes processing heavier crudes into higher-value chemical feedstocks.
Saudi Arabia
Crude production scale anchors long-term offtake agreements with Asian buyers through integrated supply chain offerings. The national oil company leverages upstream control to secure downstream market access across refining and petrochemical ventures. Jubail and Yanbu industrial cities concentrate conversion capacity for export-oriented product slates.
Germany
Building electrification mandates accelerate demand erosion for middle distillate heating oils across industrial and residential segments. The EU F-Gas Regulation and REACH framework constrain refinery process emissions and chemical handling protocols. The Rhine-Ruhr corridor hosts integrated complexes adapting to carbon border adjustment exposure through emissions accounting system investments.
Singapore
Trading houses and independent marketers arbitrage disaggregated supply relationships through unbundled logistics, storage, and blending services. The port's floating storage and blending capabilities capture crack spread volatility across Asian product markets. Jurong Island concentrates hydrocracking and catalytic reforming capacity serving regional bunkering and petrochemical demand.
Oil and Gas Downstream Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology licensing and crude supply integration dimensions. The downstream sector consolidates around integrated majors with proprietary catalyst systems and national oil companies with captive crude access. Three archetypes dominate: technology licensors monetizing process know-how, crude-integrated players securing feedstock advantage, and trading-anchored operators capturing geographic arbitrage. Capacity expansion and strategic partnerships constitute the dominant competitive moves as refiners reposition toward petrochemical integration.
Within the crude-integrated tier, Saudi Aramco exemplifies upstream-downstream linkage through production-scale offtake anchoring. ExxonMobil occupies a position as technology licensor with proprietary hydrocracking catalyst systems. Royal Dutch Shell sits within the trading-anchored archetype, positioning hub operations for geographic arbitrage capture.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil |
| Royal Dutch Shell |
| BP |
| Reliance Industries |
| China National Petroleum Corporation |
| Chevron |
| TotalEnergies |
| Valero Energy |
| Others |
Value Network & Pricing Analysis
Asian integrated chemical buyers anchor long-term offtake negotiations through crude-linked tolling arrangements that transparently split refining margins between feedstock suppliers and processing operators. This buyer concentration forces Western refiners toward unbundled service contracts that expose underlying cost structures.
Pricing Analysis
Contract-based long-term offtake agreements dominate crude procurement and product sales, with pricing stratifying across premium, standard, and economy tiers based on sulfur content and cetane specifications. Price differentiation rests on crude quality grade and geographic delivery cost to coastal hubs. Margins are tightening due to transport fuel demand erosion from battery electric vehicle penetration. Independent marketers and trading houses exhibit highest price sensitivity, while national oil companies with captive crude access show least elasticity.
Supply Chain Analysis
Instrument engineers with hybrid chemical engineering and data science competencies command premium compensation across US Gulf Coast, Rotterdam, and Singapore refining corridors, constraining digital twin deployment timelines. Crude supply concentrates in Saudi Arabia, Russia, and the US Permian Basin, with hydrocracking catalysts and hydrogen feedstock as critical component dependencies. Single-source vulnerability around proprietary catalyst systems from Chevron, ExxonMobil, and Shell creates supply chain risk. Distribution runs through marine terminals at Houston, Rotterdam, and Singapore with floating storage arbitrage capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in downstream operations hinges on accelerating petrochemical integration that captures premium feedstock values while transport fuel economics compress. Hydrocracking catalyst efficiency gains and carbon intensity reduction investments anchor this shift.
For Market Incumbents: Anticipate electrification-driven gasoline demand erosion by accelerating hydrocracker retrofits for sustainable aviation fuel co-processing. Defend market position through proprietary catalyst licensing to Asian mega-complexes. Prioritize carbon accounting system investments that insulate against EU Carbon Border Adjustment Mechanism exposure. For New Entrants and Emerging Players: Launch via circular feedstock integration models that chemical recycle plastic waste into synthetic crude streams for existing refinery infrastructure. Target underpenetrated biorefinery co-location opportunities in California and Oregon LCFS credit markets. Lead with hydrogen hub positioning that captures US IRA production tax credits at stranded refinery assets. For Investors and Strategic Acquirers: National oil companies with integrated upstream-downstream control represent the most active acquirer category in this space, seeking technology licensors with proprietary conversion capabilities. Five-to-ten year viability favors complexes with deep petrochemical integration and verified low-carbon process routes. Monitor sustainable aviation fuel offtake agreement velocity as inflection indicator for refinery asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Petrochemical Integration Deepening | Reliance Industries and Saudi Aramco anchor mega-complex investments that offset transport fuel margin compression through naphtha cracking economics. |
| Hydrocracking Capacity Expansion | ExxonMobil and Chevron license proprietary catalyst systems that determine unit yields and cycle lengths for heavy sour crude processing. |
| Sustainable Aviation Fuel Co-Processing | California LCFS credit capture incentivizes hydrocracker retrofitting at existing sites to serve aviation decarbonization mandates. |
| Hydrogen Hub Positioning | US IRA production tax credits drive refinery retrofitting to serve as blue hydrogen production nodes for industrial offtake. |
| Carbon Accounting System Investment | Rhine-Ruhr corridor refiners deploy emissions tracking platforms to defend export competitiveness under EU Carbon Border Adjustment Mechanism. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, catalyst technology licensors, marine terminal operators, and petrochemical procurement leads with secondary validation through EIA refinery capacity reports, IEA oil market outlooks, EPA Tier 3 compliance filings, and EU ETS emissions data. Bottom-up capacity modeling and top-down demand triangulation anchored market sizing across the analysis window.
Segment-weighted forecasting applied differential growth assumptions across hydrocracking, catalytic reforming, alkylation, and desulfurization technology categories, with additional granularity by product type spanning gasoline, diesel, jet fuel, and lubricants. CAGRs derived from crack spread elasticity modeling and petrochemical margin correlation analysis, incorporating crude slate heaviness trends and carbon intensity benchmark trajectories as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under OPEC+ production policy shifts and accelerated battery electric vehicle penetration scenarios. Forecasts reflect assumptions around regulatory compliance timelines and carbon border adjustment implementation scope. Material deviation in sustainable aviation fuel mandate adoption rates or hydrogen infrastructure deployment velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market