
 Floating Production Systems (FPS) Market | 2026-2036
Floating Production Systems (FPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Production Systems (FPS) Market Foresight
The capital-intensity divergence between turnkey specialists and fabrication-heavy conglomerates is reorganizing competitive tiers in floating production. SBM Offshore leverages its Fast4Ward hull standardization program to compress delivery schedules. Hyundai Heavy Industries anchors Asian fabrication capacity for hull and topside integration. MODEC Inc specializes in leased FPSO contracting, sustaining long-term charter revenue visibility.
Floating Production Systems encompass moored or dynamically positioned vessels and platforms that extract, process, store, and offload hydrocarbons from offshore fields, typically operating in water depths exceeding 300 meters with storage capacities ranging from one to two million barrels. These systems serve as standalone production hubs where subsea tiebacks prove uneconomical or where pipeline infrastructure remains absent. FPSO units dominate installed base and new order flow, reflecting their versatility across field sizes and water depths. Semi-submersible platforms retain structural importance in harsh-environment North Sea and Gulf of Mexico deployments where motion characteristics prove critical. Spar platforms occupy a narrower niche in ultradeepwater US Gulf developments where minimal heave response supports dry-tree completion strategies.
The American Bureau of Shipping and DNV classification societies enforce hull structural and stationkeeping standards that directly shape steel grading, mooring configuration, and subsea connector specifications. Brazil's national petroleum regulator ANP mandates local content requirements that redirect equipment procurement toward domestic fabrication yards and engineering consortia. Stakeholders must monitor how decommissioning liability frameworks and carbon-intensity disclosure rules reshape project economics for brownfield redeployments versus greenfield FPS orders.
Market Dynamics
Deepwater project sanctioning by national oil companies is compressing front-end engineering cycles while API RP 2SK stationkeeping standards force hull-mooring integration redesigns across all major fabrication yards.
Growth Catalysts
- Pre-salt basin development:Brazil's ANP production-sharing frameworks accelerate FPSO deployment schedules in ultradeepwater blocks where subsea tiebacks remain uneconomical.
- Fast4Ward standardization:Hull design repetition is compressing steel-cutting to sail-away timelines by enabling parallel topside integration at multiple Asian fabrication sites.
- Dynamic positioning adoption:DP-3 redundancy requirements for disconnectable FPSOs are expanding addressable water depths beyond 2,000 meters in West African developments.
Market Restraints
- Steel price volatility:High-tensile marine-grade plate cost swings directly erode lump-sum EPC margins for hull fabrication contracts.
- Asian yard concentration:Korean and Singaporean shipbuilders control over 70 percent of FPSO hull capacity, creating queue bottlenecks during sanctioning waves.
- ANP local content mandates:Brazil's domestic procurement quotas extend equipment delivery timelines and inflate engineering man-hour costs for foreign contractors.
Strategic Opportunities
- West African frontier:Pre-salt analog geology offshore Senegal and Mauritania offers greenfield FPSO demand as exploration drilling confirms commercial reserves.
- Brownfield redeployment:Existing FPSO hulls approaching contract expiry present lower-carbon alternatives to newbuilds for marginal field developments.
- Electrification integration:Shore power connection standards are enabling FPSOs to reduce onboard gas turbine runtime and associated Scope 1 emissions reporting.
Industry Challenges
- Marine warranty surveyor scarcity:DNV and ABS-certified specialists for dynamic positioning validation command premium day rates that extend commissioning schedules.
- Subsea integration complexity:High-pressure high-temperature riser systems require synchronized installation windows that compress hookup timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Production Systems (FPS) Market |
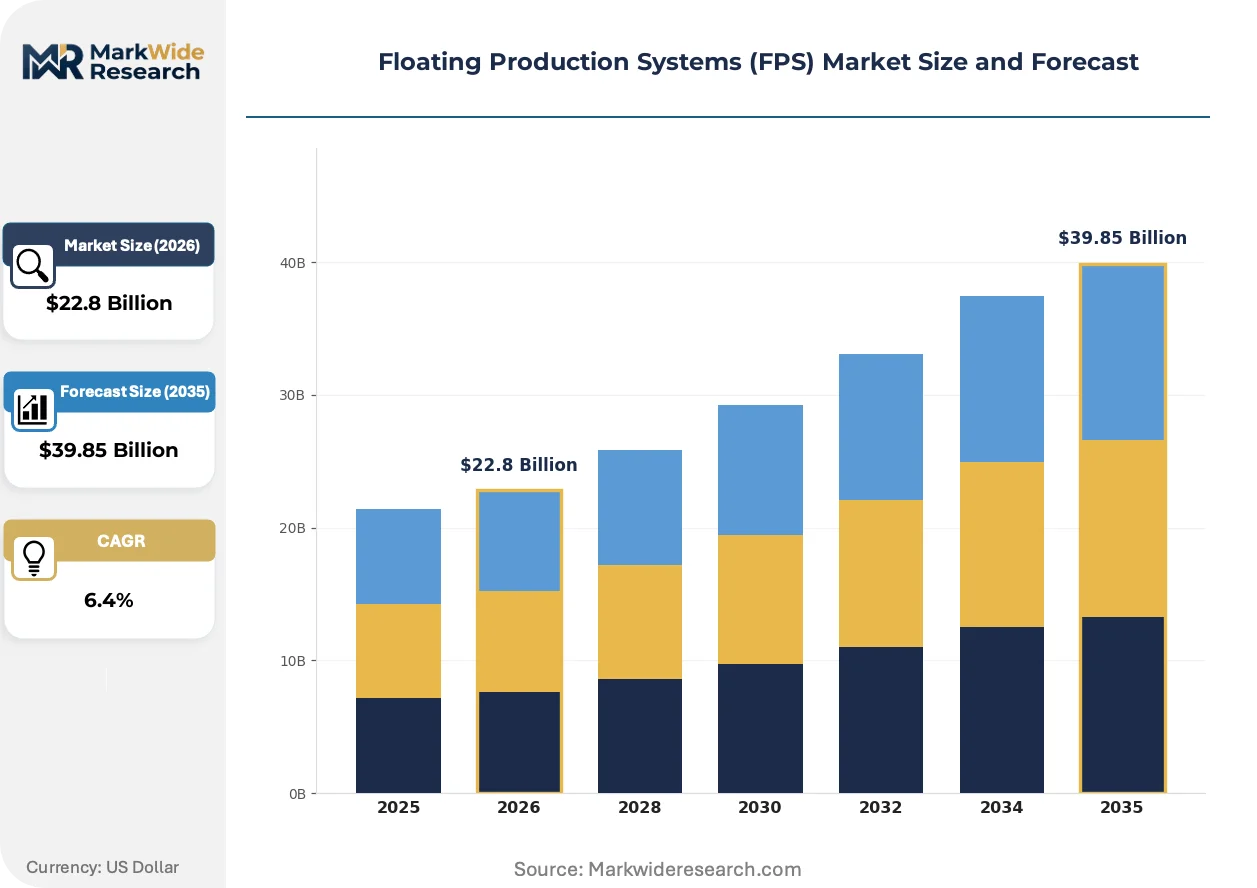
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: FPSO, Semi-Submersible, Spar Platform, Tension Leg Platform Technology: Subsea Processing, Enhanced Oil Recovery, Remote Monitoring, Dynamic Positioning Application: Deepwater Development, Marginal Field Operations, Gas Processing, Oil Storage End User: Oil Companies, Engineering Contractors, Offshore Service Providers, Equipment Manufacturers |
| Companies Covered | SBM Offshore NV, MODEC Inc, TechnipFMC PLC, BW Offshore Ltd, Bumi Armada Berhad, Keppel Offshore and Marine Ltd, Samsung Heavy Industries Co Ltd, Hyundai Heavy Industries Co Ltd, Mitsubishi Heavy Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Production Systems (FPS) Market Shifts & Advancements
Digital twin deployment and modular topside fabrication are compressing offshore commissioning durations while classification societies rewrite rules for autonomous marine operations.
Subsea processing technology is miniaturizing separation and boosting equipment for seabed installation, reducing topside weight allowances and enabling smaller hull configurations. National oil companies in Brazil and West Africa are specifying subsea compression for pre-salt gas reinjection schemes. This equipment downsizing is miniaturizing the minimum viable FPSO storage capacity threshold, expanding the addressable market to marginal fields below 100 million barrel recoverable reserves.
The EU Green Deal carbon border adjustment mechanism is reshaping steel sourcing decisions for European-flagged FPSO projects, favoring electric-arc furnace producers with verified emissions disclosures. Hull fabricators must now document Scope 3 upstream emissions or face tariff penalties on steel plate imports. North Sea operators are responding by qualifying Norwegian and Swedish mill suppliers despite 15-20 percent cost premiums over Asian alternatives.
Charter contracting structures are fragmenting as national oil companies demand greater operational control and earlier purchase options. Lease-plus-operate agreements are displacing bareboat charters for pre-salt units, transferring manning and maintenance liability to equity holders. This shift is most pronounced in Brazil, where Petrobras has renegotiated three major FPSO contracts to hybrid structures since 2022.
Floating Production Systems (FPS) Market Segmentation
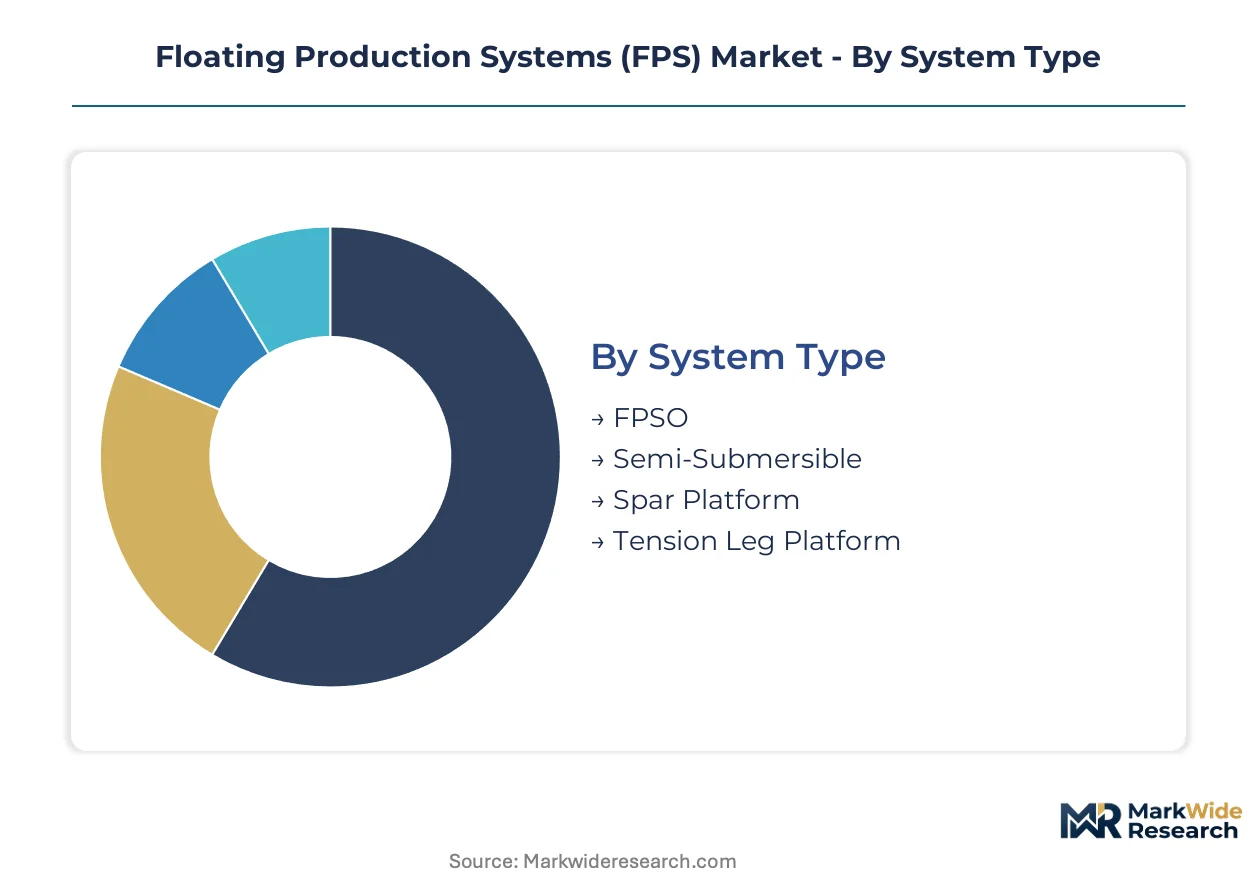
Floating production segmentation reveals divergent capital deployment patterns across water depths and field economics. System type and technology choices determine whether projects proceed under lump-sum EPC contracts or long-term lease structures.
System Type:
FPSO demand concentrates in export-led markets where pipeline infrastructure remains absent, while spar and TLP deployments cluster in domestic US Gulf developments.
- FPSO:These vessel-based systems integrate processing, storage, and offloading capabilities for fields lacking pipeline connectivity. Brazil's pre-salt basins and West African frontiers anchor procurement volumes where shuttle tanker economics outperform subsea tieback alternatives. FPSO holds the largest share; momentum sits with semi-submersible configurations for harsh-environment redeployment.
- Semi-Submersible:Column-stabilized platforms deliver superior motion characteristics in North Sea and Norwegian Sea conditions. Petrobras and Equinor specify these units for marginal field developments where dry-tree access supports intervention flexibility.
- Spar Platform:Single-column hulls with deep-draft ballast minimize heave response for dry-tree completions in ultradeepwater US Gulf blocks.
- Tension Leg Platform:Vertical tendon mooring systems enable minimal vertical motion for drilling and production integration in benign environments.
FPSO configurations dominate installed base; semi-submersible orders are climbing fastest on brownfield redeployment demand.
Technology:
Cost tier separation distinguishes mature topside processing from capital-intensive subsea systems requiring integrated project execution.
- Subsea Processing:Seabed separation and boosting equipment reduces topside weight allowances, enabling smaller hull configurations for marginal fields below 100 million barrel recoverable reserves. ANP-mandated gas reinjection schemes in Brazil's pre-salt blocks accelerate adoption timelines.
- Enhanced Oil Recovery:Gas lift and water injection systems extend field plateau production for mature basins. North Sea operators prioritize E retrofits over greenfield FPS orders to defer decommissioning liabilities.
- Remote Monitoring:Digital twin deployment compresses commissioning durations through predictive maintenance algorithms.
- Dynamic Positioning:DP-3 redundancy specifications expand addressable water depths beyond 2,000 meters in West African developments.
Subsea processing commands premium engineering margins; remote monitoring adoption is expanding most quickly across charter fleets.
Application:
Customer type stratification separates national oil company deepwater programs from independent operator marginal field strategies.
- Deepwater Development:Standalone production hubs in water depths exceeding 1,500 meters require integrated hull-mooring-riser systems. Brazil and West Africa concentrate sanctioning activity where local content mandates reshape contractor selection.
- Marginal Field Operations:Small-scale FPSOs with sub-500,000 barrel storage capacities unlock stranded reserves. Southeast Asian independents favor leased units to preserve balance sheet capacity.
- Gas Processing:Acid gas removal and dehydration topsides serve associated gas streams from oil-dominant fields.
- Oil Storage:Buffer tankage capacity enables offtake scheduling flexibility for shuttle tanker operations.
Deepwater applications absorb majority capital allocation; marginal field contracting is gaining share fastest among leased unit providers.
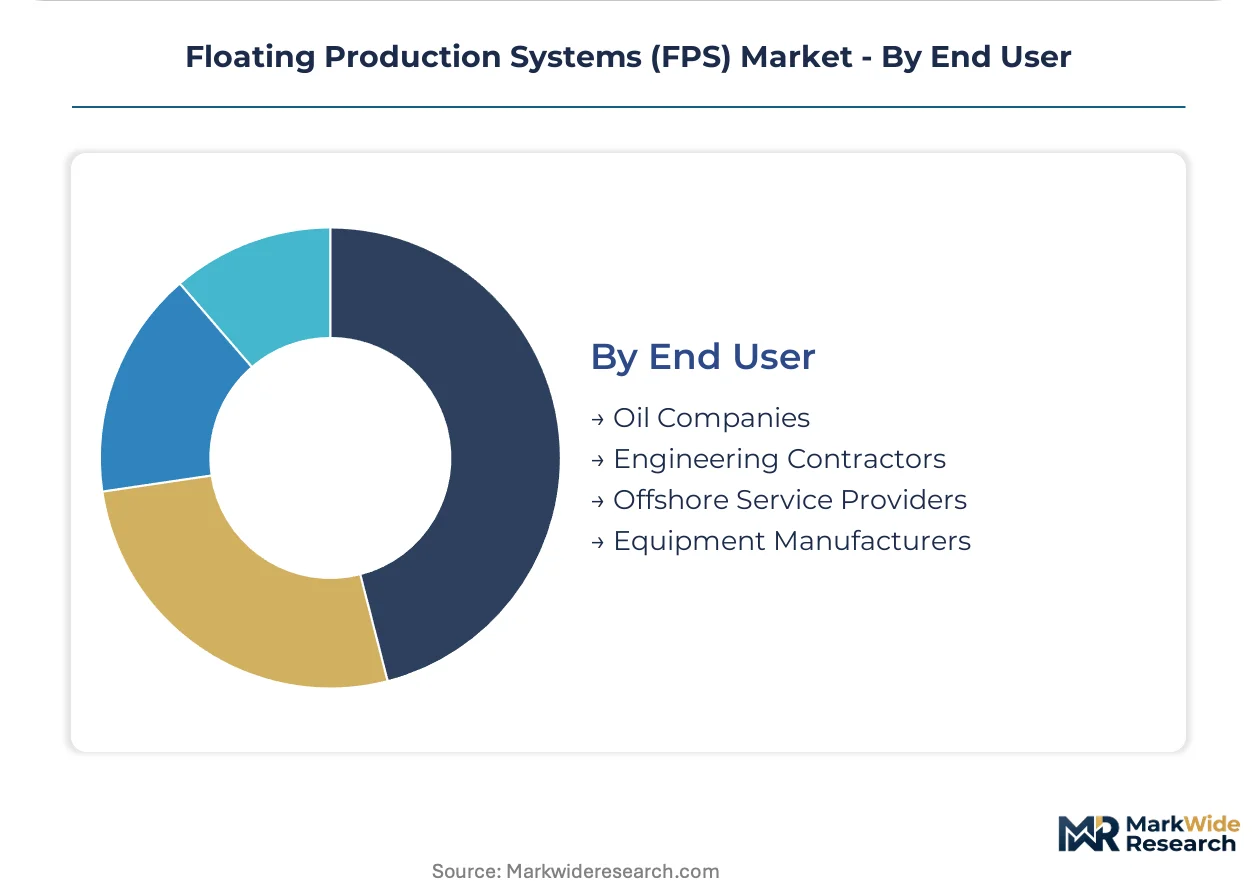
End User:
Supply concentration among Asian fabrication yards creates divergent procurement leverage for integrated oil companies versus engineering contractors.
- Oil Companies:National oil companies in Brazil, Nigeria, and Angola specify lease-plus-operate structures transferring operational liability to equity holders. Petrobras has renegotiated three major contracts to hybrid charter arrangements since 2022.
- Engineering Contractors:Turnkey specialists manage hull-topside integration risk across multiple Asian fabrication sites. SBM Offshore and MODEC sustain long-term charter revenue visibility through leased FPSO portfolios.
- Offshore Service Providers:Installation contractors coordinate heavy-lift vessel schedules for mooring system deployment.
- Equipment Manufacturers:Subsea riser and connector suppliers synchronize delivery windows with hull sail-away dates.
Oil companies direct majority procurement decisions; engineering contractors are expanding their share through integrated lease offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes floating production systems through lease-plus-operate structures that transfer operational liability to contractors, while the United States and Norway favor owner-operated models with integrated project execution. This consumption-mix differential reflects divergent regulatory frameworks and national oil company procurement philosophies across deepwater basins.
Brazil
Petrobras anchors FPSO deployment volumes through pre-salt production-sharing contracts in ultradeepwater blocks. ANP local content mandates redirect equipment procurement toward domestic fabrication yards in Rio de Janeiro state. The Porto do Açu industrial complex hosts hull integration activities for foreign contractors seeking quota compliance.
United States
Gulf of Mexico operators specify spar platforms and semi-submersibles for dry-tree completions in ultradeepwater lease blocks. The Bureau of Safety and Environmental Enforcement enforces well control and containment standards that shape hull-mooring integration designs. Houston's engineering corridor concentrates project management offices for major integrated oil companies.
Norway
Equinor deploys semi-submersible platforms for marginal field developments in the Norwegian Sea and Barents Sea. The Petroleum Safety Authority mandates functional safety requirements for dynamic positioning systems in harsh-environment operations. Stavanger's subsea technology cluster supports riser system engineering and marine warranty surveyor capacity.
Singapore
Jurong Shipyard and Sembcorp Marine anchor Asian FPSO hull fabrication and topside integration capacity. The Maritime and Port Authority administers shipyard safety and environmental compliance frameworks. Tuas industrial zone expansion is adding heavy-lift quayside infrastructure for simultaneous multi-vessel construction programs.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries control bulk hull steel-cutting capacity for export-led FPSO projects. The Korean Register of Shipping classification society validates hull structural designs for international flag registries. Ulsan and Geoje shipbuilding complexes compete for conversion and newbuild contracts from West African and Brazilian national oil companies.
Floating Production Systems (FPS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with turnkey contractors and fabrication-heavy conglomerates occupying distinct competitive positions. The market structure reflects capital-intensity divergence between lease portfolio operators and lump-sum EPC providers. Three archetypes dominate: Dutch lease specialists, Asian fabrication conglomerates, and integrated engineering-procurement-construction contractors. Competitive moves center on hull standardization programs and hybrid charter structure renegotiations.
Among Dutch lease specialists, SBM Offshore NV and BW Offshore Ltd exemplify the turnkey contractor archetype through long-term charter revenue models. MODEC Inc, a Japanese specialist, occupies a parallel position within the leased FPSO tier. Asian fabrication conglomerates anchor the supply side, with Hyundai Heavy Industries Co Ltd representing Korean hull capacity and Samsung Heavy Industries Co Ltd competing for conversion and newbuild contracts. These named entities illustrate how geographic origin and corporate structure shape strategic positioning without determining specific market outcomes.
| Leading Market Players |
|---|
| SBM Offshore NV |
| MODEC Inc |
| TechnipFMC PLC |
| BW Offshore Ltd |
| Bumi Armada Berhad |
| Keppel Offshore and Marine Ltd |
| Samsung Heavy Industries Co Ltd |
| Hyundai Heavy Industries Co Ltd |
| Mitsubishi Heavy Industries Ltd |
| Others |
Supply & Pricing Matrix
Long-term charter-plus-operate contracts lock in hull fabrication slots at Korean and Singaporean yards while capping price escalation exposure for Petrobras and other national oil companies. These structures tie supply access to predictable cost corridors across multi-year deployment cycles.
Pricing Analysis
Project-based lump-sum EPC contracting dominates greenfield FPSO awards, with price differentiation driven by hull standardization tier and ANP local content compliance grade. Premium pricing attaches to Fast4Ward hulls with pre-certified ABS or DNV stationkeeping configurations. Cost compression in bareboat charter rates is intensifying because Brazilian NOCs are extracting operational control concessions from contractors. Independents in Southeast Asian marginal fields exhibit highest price sensitivity; integrated oil companies in ultradeepwater blocks show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites heavy-lift vessel scheduling for hull modules originating from Ulsan and Geoje shipyards. Supply concentrates in South Korea, Singapore, and China for marine-grade steel plate and topside module fabrication. Raw material dependencies span high-tensile steel plate, subsea riser alloys, and dynamic positioning thruster systems. Single-source vulnerability concentrates in Korean hull-cutting capacity where Samsung Heavy Industries and Hyundai Heavy Industries control queue priority. Distribution runs through engineering-procurement-construction contractors coordinating multi-site integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
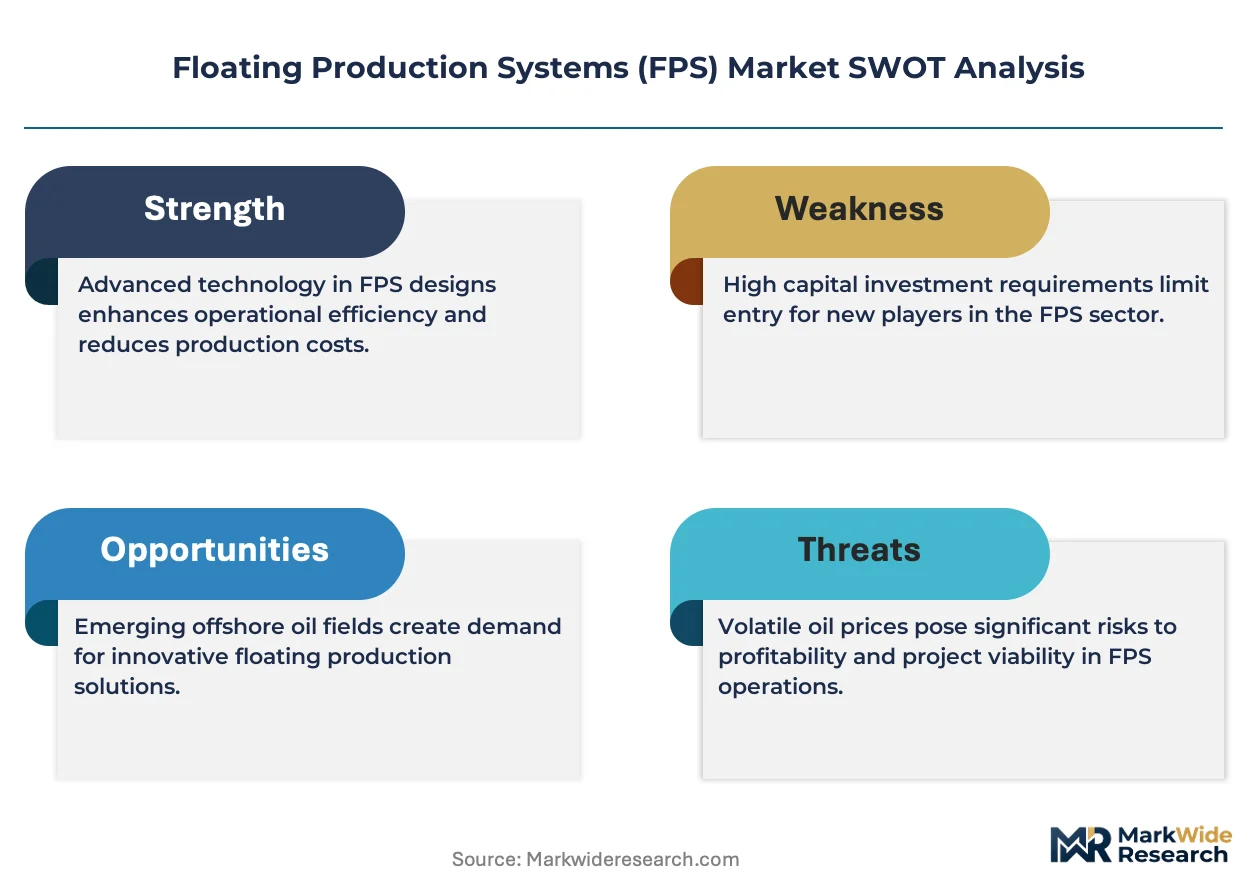
Floating production systems face substitution pressure from subsea tieback solutions and platform electrification retrofits that reduce standalone hull demand. Incumbents must navigate this technology displacement while defending charter revenue visibility.
For Market Incumbents: Shield lease portfolio value by embedding purchase options that complicate operator substitution to subsea-only architectures. Secure backward integration into marine warranty surveyor capacity to compress commissioning timelines and defend day-rate premiums. Counter emerging competition from integrated oil companies building in-house FPSO project capabilities through exclusive hull yard partnerships at Jurong and Tuas.
For New Entrants and Emerging Players: DNV DP-3 certification fast-tracks entry into West African disconnectable FPSO demand where contractor scarcity extends bidding windows. Target marginal field operators in Southeast Asia with leased semi-submersible configurations sized below 500,000 barrel storage thresholds. Penetrate through modular topside fabrication partnerships that reduce upfront capital requirements.
For Investors and Strategic Acquirers: Turnkey contractors with chartered unit backlogs and established ANP compliance track records offer the most defensible cash flow profiles across energy transition scenarios. Long-term viability hinges on brownfield redeployment capabilities that extend asset lifecycles without newbuild carbon exposure. Monitor ANP local content quota adjustments as the inflection signal for foreign contractor margin compression or opportunity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hull Standardization Program | Fast4Ward repetition compresses steel-cutting to sail-away timelines at multiple Asian fabrication sites. |
| Lease-Plus-Operate Contracting | Hybrid structures transfer manning liability to equity holders while preserving contractor revenue visibility. |
| Subsea Processing Integration | Seabed separation equipment reduces topside weight allowances for marginal field hull configurations. |
| DP-3 Redundancy Certification | ABS and DNV validation expands addressable water depths beyond 2,000 meters in West African blocks. |
| ANP Local Content Compliance | Domestic procurement quotas redirect equipment sourcing toward Rio de Janeiro state fabrication yards. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with FPSO project directors, marine warranty surveyors, ANP regulatory affairs leads, and Korean shipyard procurement managers. Secondary validation drew from ABS classification bulletins, DNV offshore standards documentation, ANP production-sharing contract registries, and Bureau of Safety and Environmental Enforcement incident reports. Bottom-up hull delivery schedules and top-down national oil company capex disclosures were triangulated to anchor volume estimates.
Across the analysis window, forecasts model system type, water depth tier, and contracting structure as primary segmentation dimensions. CAGRs derive from project sanctioning velocity observed in Brazilian pre-salt and West African frontier basins, cross-referenced with hull yard capacity utilization at Ulsan, Geoje, and Jurong complexes. Subsea processing adoption curves and electrification retrofit penetration serve as industry-specific demand modifiers.
Underlying assumptions cover sustained Brent price corridors supporting deepwater project economics, with deviation risk concentrated in Brazilian fiscal regime adjustments and Asian steel price volatility. Practitioners should keep alternative scenarios live as ANP local content enforcement intensity and EU carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market