
 Norway Oil and Gas Market | 2026-2036
Norway Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Oil and Gas Market Outlook
Integrated production services bundled with digital reservoir analytics is pivoting contract structures toward outcome-based remuneration. Equinor ASA leverages its Johan Sverdrup platform to sustain full-field optimization across multiple phases. Aker BP ASA anchors its position through aggressive automation of subsea operations. Vår Energi AS competes on scale in the Norwegian Continental Shelf's high-pressure, high-temperature segments.
Norway oil and gas encompasses upstream hydrocarbon extraction, midstream transport, and downstream processing of crude oil, natural gas, and LNG, with operations typically conducted in water depths from 80 to 2,000 meters using subsea tieback or fixed-platform architectures designed for North Sea conditions. The sector supplies feedstock to European power generation, petrochemical complexes, and marine bunkering markets. Natural gas from the Norwegian Continental Shelf leads in production volume due to sustained European pipeline demand, while LNG export capacity represents the fastest-growing delivery category as global buyers seek alternatives to piped supply. Refined products face mature demand profiles domestically, with margin pools shifting toward low-sulfur marine fuels and specialized petrochemical intermediates.
The Norwegian Petroleum Directorate enforces strict recovery factor requirements that shape field development schedules and capital allocation across license holders. The EU Green Deal and Norway's alignment with its emission benchmarks force operators to integrate electrification and carbon capture into project designs. The Petroleum Safety Authority Norway mandates continuous barrier management standards that elevate operational expenditure baselines. Stakeholders must monitor how carbon border adjustments and evolving North Sea tax treatments reshape project sanctioning timelines and partnership structures.
Market Dynamics
Carbon capture mandates under the EU Green Deal framework are restructuring field development economics across the Norwegian Continental Shelf, forcing operators to embed electrification and emissions reduction into every project phase.
Growth Catalysts
- EU Green Deal alignment:Norway's carbon capture requirements create regulatory certainty that accelerates sanctioned project timelines. Operators gain financing access tied to emission benchmarks.
- Western coast industrial offtake:Petrochemical complexes and marine bunkering terminals along Norway's coastline expand long-term purchase agreements. These contracts anchor production volumes for North Sea shelf operators.
- Subsea tieback technology:Mature infrastructure enables lower-cost development of marginal fields. High-pressure, high-temperature drilling capabilities unlock previously uneconomic reservoirs.
Market Restraints
- Capital intensity escalation:Electrification platforms and carbon capture equipment add 15-25% to baseline capex requirements. Smaller license holders face constrained balance sheets.
- Supply concentration in subsea equipment:A limited vendor base controls high-pressure wellhead systems and subsea processing modules. Lead times extend 18-24 months for critical components.
- European pipeline dependency:Natural gas offtake relies on continental European demand patterns. Grid congestion and storage capacity limits create price volatility exposure.
Strategic Opportunities
- LNG export capacity expansion:Global buyers seeking alternatives to piped supply drive investment in Norwegian liquefaction infrastructure. Asian and emerging European markets represent new demand anchors.
- Digital reservoir analytics convergence:Integration of real-time monitoring with automated subsea operations enables outcome-based service contracts. Technology providers capture recurring revenue streams.
- Petrochemical feedstock positioning:Low-carbon intensity Norwegian crude and gas command premiums in European refineries. Marine bunkering markets shift toward low-sulfur fuels from North Sea sources.
Industry Challenges
- Subsea automation skill scarcity:Remote operations centers require specialized technicians capable of managing unmanned platform systems. Training pipelines lag deployment schedules.
- Continuous barrier compliance:Petroleum Safety Authority Norway mandates elevate operational expenditure baselines. Documentation and verification protocols consume engineering resources.
- Legacy platform integration:Electrification retrofits on mature fixed installations face space constraints and power system incompatibilities. Decommissioning timelines accelerate for non-viable assets.
Report Scope
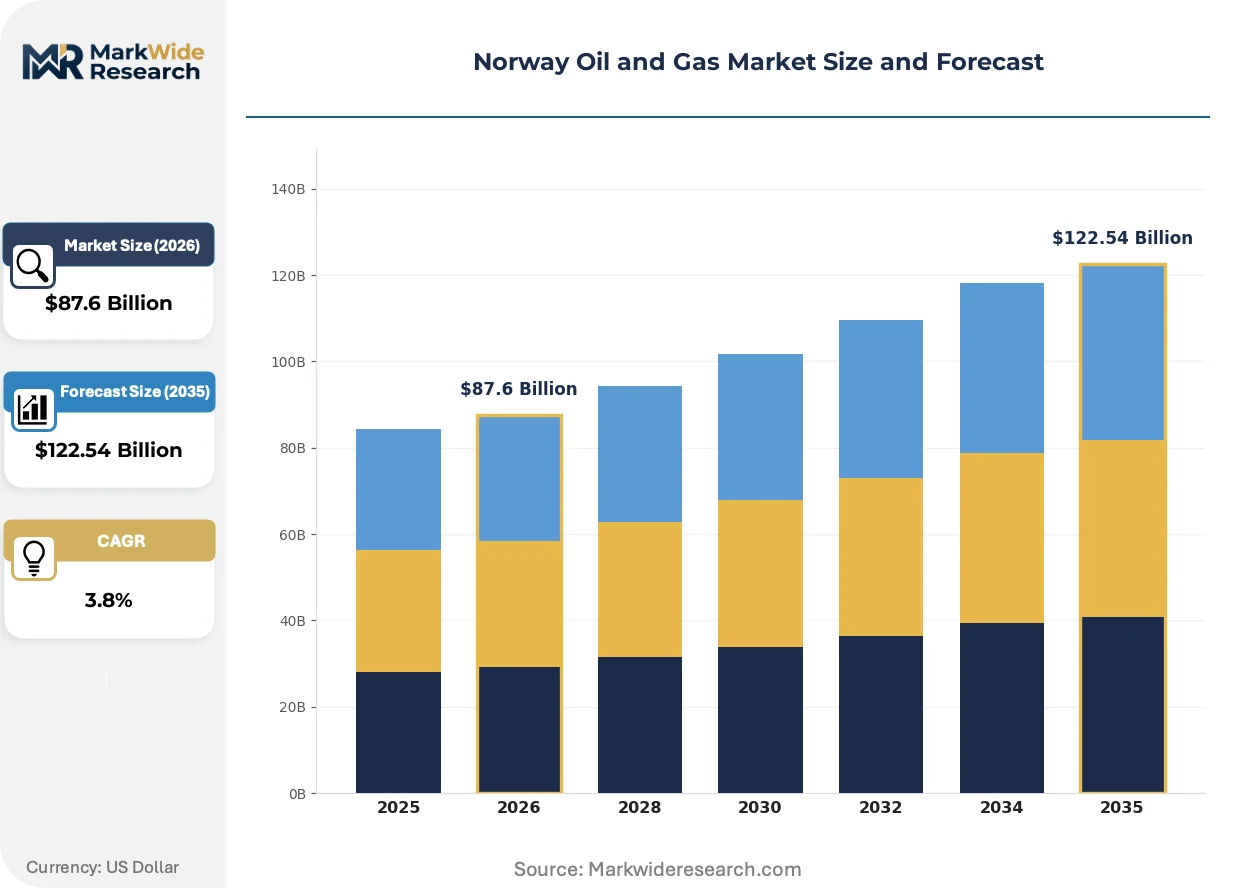
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Oil and Gas Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Liquefied Natural Gas, Refined Products Service Type: Exploration, Production, Transportation, Refining Delivery Mode: Pipeline, Shipping, Trucking, Rail End User: Power Plants, Industrial Users, Commercial Enterprises, Export Markets |
| Companies Covered | Equinor ASA, Aker BP ASA, Vår Energi AS, TotalEnergies SE, Shell PLC, Exxon Mobil Corporation, ConocoPhillips Skandinavia AS, OMV (Norge) AS, Neptune Energy Norge AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Oil and Gas Market Strategic Shifts
Platform electrification powered from shore is compressing offshore emission profiles while enabling new development concepts previously blocked by carbon intensity thresholds.
Subsea power distribution and variable speed drive technology is electrifying well intervention and processing equipment previously dependent on topside generators. Equinor and Aker BP deploy all-electric subsea compression at Johan Sverdrup and Ærfugl fields. This architecture eliminates offshore gas turbines, reducing maintenance cycles and enabling deeper water tiebacks.
The EU Green Deal's carbon border adjustment mechanism tightens emission accounting for imported energy. Norwegian operators face competitive pressure to document full lifecycle carbon intensity. Fields with integrated carbon capture gain preferential access to German and Dutch industrial buyers.
Industrial buyers along Norway's western coast consolidate procurement through multi-year offtake frameworks. Petrochemical complexes and marine fuel terminals negotiate volume commitments directly with producers. This disintermediation compresses trading margins while securing supply certainty for capital-intensive downstream investments.
Norway Oil and Gas Market Segmentation
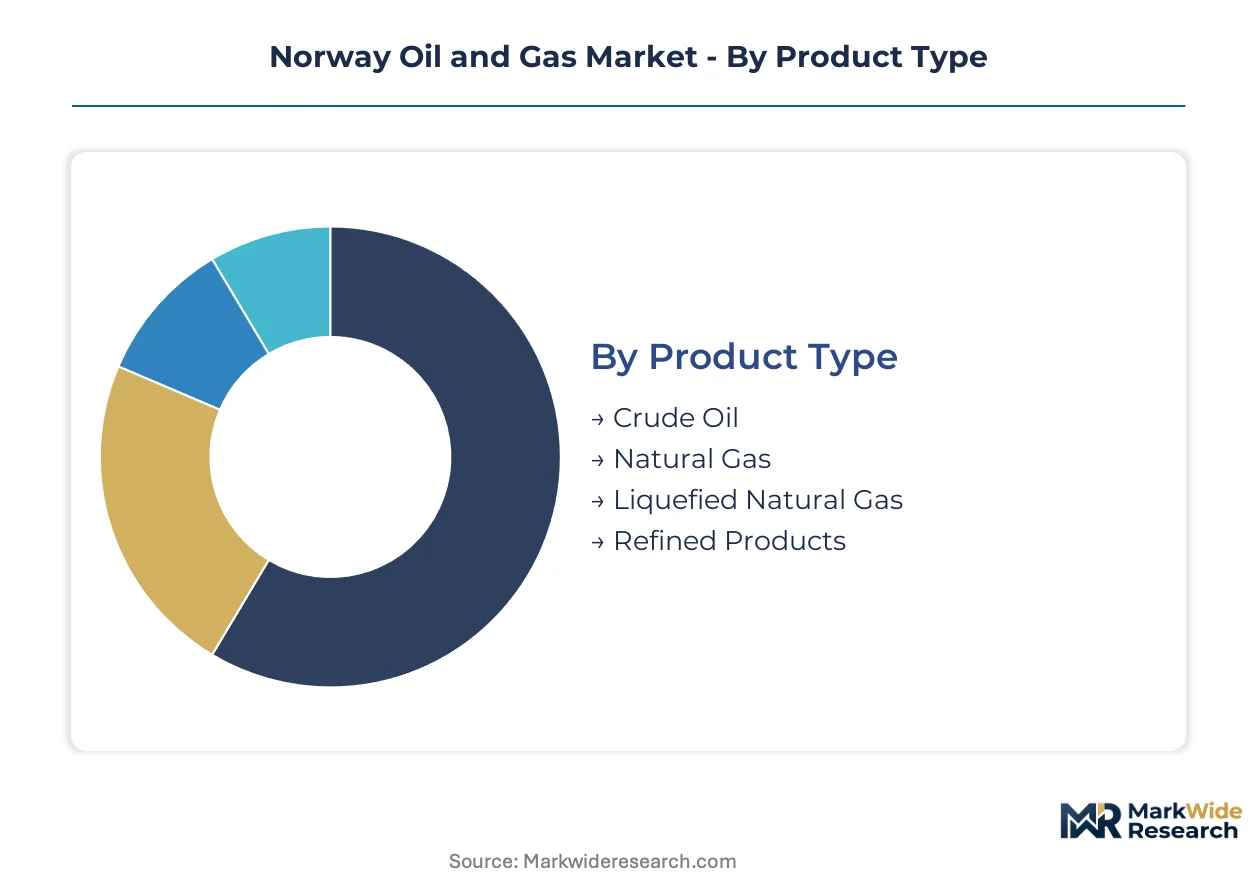
Segmentation in the Norwegian oil and gas sector reveals how regulatory pressure and infrastructure maturity reshape commercial priorities. Operators allocate capital across product and service categories based on electrification requirements and offtake security rather than volume alone.
Product Type:
Supply concentration in natural gas processing infrastructure dominates investment flows across the Norwegian Continental Shelf, with pipeline connectivity to European markets determining field development sequencing.
- Natural Gas:Dry and wet gas streams from high-pressure reservoirs feed directly into the integrated transport network serving German, Dutch, and British industrial buyers. Norwegian gas commands premium positioning due to lower carbon intensity relative to continental alternatives.
- Crude Oil:Light sweet grades from the North Sea shelf, including Johan Sverdrup's low-sulfur barrels, supply European refineries seeking marine fuel compliance and petrochemical feedstock. Gravity and sulfur specifications align with stricter EU emission benchmarks.
- Liquefied Natural Gas:Small-scale liquefaction at Hammerfest and prospective western coast expansions target Asian and emerging European buyers seeking supply diversification beyond piped routes.
- Refined Products:Domestic refining at Mongstad and Slagen produces low-sulfur marine fuels and specialized intermediates for coastal bunkering markets.
Today's leader: Natural Gas. Tomorrow's challenger: Liquefied Natural Gas.
Service Type:
Cost tier differentiation separates capital-intensive production services from lower-margin transportation operations, with electrification retrofits compressing returns on mature field support.
- Production:Subsea tieback installations, platform automation, and reservoir management services command premium pricing tied to recovery factor guarantees. Equinor and Aker BP bundle digital analytics with physical operations.
- Exploration:Seismic acquisition and wildcat drilling face compressed activity cycles as the Norwegian Petroleum Directorate prioritizes proven area redevelopment over frontier basin testing.
- Transportation:Pipeline tariffs and shipping logistics operate on regulated or spot-based structures with thinner margin profiles than upstream services.
- Refining:Downstream processing margins fluctuate with European product demand and carbon border adjustment exposure on imported crude alternatives.
Production services capture the steepest expansion trajectory as operators prioritize recovery optimization over new field discovery.
Delivery Mode:
Application-specific infrastructure requirements lock in delivery mode selection, with pipeline economics dominating continental European commitments while shipping flexibility serves spot LNG buyers.
- Pipeline:Subsea trunklines from the Troll, Ormen Lange, and Åsgard fields deliver dry gas directly to Emden, Zeebrugge, and Dornum. Capacity constraints at continental landing points create periodic price volatility.
- Shipping:LNG carriers and product tankers from Melkøya and Mongstad terminals access global markets beyond pipeline reach. Vessel charter rates and carbon intensity documentation shape contract terms.
- Trucking:Refined product distribution serves coastal industrial clusters and marine bunkering terminals along the western fjords.
- Rail:Limited domestic rail infrastructure handles specialized petrochemical feedstock movements to inland processing plants.
Pipeline infrastructure anchors current volume flows. Shipping capacity is gaining share fastest as LNG export ambitions expand.
End User:
Customer type concentration in industrial procurement is restructuring contractual relationships, with direct producer-buyer frameworks displacing traditional trading intermediaries.
- Industrial Users:Petrochemical complexes at Rafnes, Bamble, and Mongstad negotiate long-term offtake agreements for ethane, propane, and naphtha feedstocks. Carbon intensity certifications determine supplier selection.
- Export Markets:German chemical manufacturers, Dutch power utilities, and British industrial gas buyers anchor Norwegian production volumes through take-or-pay structures.
- Power Plants:Combined cycle gas turbines in continental Europe and domestic district heating networks consume seasonal gas volumes with weather-dependent demand curves.
- Commercial Enterprises:Marine bunkering terminals and coastal fuel retailers represent fragmented, lower-volume demand with higher service requirements.
Industrial Users dominate contract value today. Export Markets are expanding most quickly as Asian LNG buyers enter procurement discussions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sources more Norwegian natural gas than any continental buyer, while the Netherlands competes for pipeline capacity through the Zeebrugge terminal complex. Both countries anchor North Sea offtake volumes through diverging procurement strategies.
Germany
Industrial gas demand from BASF Ludwigshafen and Bayer Leverkusen complexes drives contract negotiations for Norwegian pipeline supply. The EU Green Deal's carbon border adjustment mechanism favors verified low-carbon intensity Norwegian gas over Russian alternatives. Emden landing terminals handle the majority of Troll and Ormen Lange volumes.
Netherlands
Dutch power utilities and chemical manufacturers at Rotterdam-Botlek seek long-term Norwegian supply to replace declining Groningen field output. REACH chemical regulations and national hydrogen transition targets shape buyer specifications for feedstock gas. Zeebrugge terminal operators expand compression capacity to accommodate higher Norwegian import volumes.
United Kingdom
British industrial gas buyers and North Sea interconnectors absorb Norwegian supply through the FLAGS and Vesterled pipeline systems. The UK's North Sea Transition Authority mandates emission reductions that favor Norwegian lower-carbon imports over domestic production. St Fergus terminal complexes in Scotland process significant Norwegian gas volumes for UK distribution.
France
French petrochemical clusters at Dunkirk and Fos-sur-Mer negotiate direct Norwegian supply contracts outside traditional trading intermediaries. ANSM environmental compliance frameworks and national decarbonization roadmaps prioritize verified carbon intensity documentation. Dunkirk LNG terminal operators explore small-scale Norwegian cargo opportunities.
Belgium
Belgian chemical manufacturers at the Port of Antwerp-Bruges anchor demand for Norwegian ethane and propane feedstocks. Federal environmental regulations and EU emission trading scheme obligations drive preference for documented low-carbon supply sources. Zeebrugge LNG and pipeline interconnections enable flexible Norwegian offtake arrangements.
Norway Oil and Gas Market Competitive Environment
Branded specialists and contract operators split share differently across segments, with integrated majors dominating production licenses while service providers capture digital and subsea niches. The Norwegian Continental Shelf exhibits tiered consolidation around three to four license holders controlling majority equity in sanctioned developments. Strategic archetypes separate electrification-focused operators, subsea automation specialists, and carbon capture integrators. Competitive moves concentrate on portfolio high-grading and partnership restructuring to spread electrification capex burdens.
Among Norway-based operators, Equinor ASA and Aker BP ASA exemplify divergent automation strategies, while Vår Energi AS occupies a position scaling high-pressure, high-temperature developments. These three entities represent distinct archetypes within the license-holder tier: the integrated major with full-field optimization platforms, the automation-first independent, and the scale-focused specialist. Their positioning illustrates how capital allocation separates across electrification readiness, digital integration depth, and reservoir complexity tolerance.
| Leading Market Players |
|---|
| Equinor ASA |
| Aker BP ASA |
| Vår Energi AS |
| TotalEnergies SE |
| Shell PLC |
| Exxon Mobil Corporation |
| ConocoPhillips Skandinavia AS |
| OMV (Norge) AS |
| Neptune Energy Norge AS |
| Others |
Value Chain & Pricing Dynamics
North Sea Brent crude futures cascade through Norwegian field economics into differentiated supply tiers, with carbon intensity certifications separating premium pipeline gas from standard spot cargoes and economy-grade residual fuel oil.
Pricing Analysis
Capacity additions in Hammerfest and prospective western coast liquefaction terminals are reshaping price floors for Norwegian gas exports. Long-term offtake contracts dominate pipeline deliveries to Germany and the Netherlands, while spot LNG cargoes command volatility premiums from Asian buyers. Carbon intensity documentation under EU Green Deal frameworks drives price differentiation between electrified platform supply and legacy turbine-powered production. Industrial buyers at Rafnes and Mongstad show highest price sensitivity to carbon border adjustments, whereas marine bunkering terminals absorb cost pass-through with limited negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Norwegian subsea equipment fabricators controlling high-pressure wellhead systems and subsea processing modules. Raw material dependencies span specialized alloy forgings from Germany, subsea umbilical sheathing from Scotland, and high-specification electronics from Japan. Tariff exposure on steel inputs and extended lead times for critical components amplify supply chain fragility. Distribution runs through integrated pipeline networks to continental Europe and LNG carrier charters to global markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's oil and gas sector functions as a regulatory compounder where EU Green Deal carbon capture mandates accelerate capital rotation toward electrified infrastructure and documented low-carbon supply chains.
For Market Incumbents: Deepen backward integration into subsea automation capabilities to offset vendor concentration risks and capture service margin pools. Prioritize certification investment for carbon intensity verification to defend premium positioning against emerging lower-cost LNG suppliers. Electrification capex burdens favor consolidation plays that spread platform retrofit costs across enlarged production bases. For New Entrants and Emerging Players: Direct-to-industrial procurement platforms offer white-space entry around western coast petrochemical complexes seeking disintermediated supply relationships. Target digital reservoir analytics services where incumbent bundling remains incomplete. Marine bunkering terminals represent the most penetrable segment given fragmented demand and limited incumbent loyalty mechanisms. For Investors and Strategic Acquirers: Asymmetric upside sits with subsea technology specialists holding proprietary electrification IP and established Norwegian Continental Shelf track records. Long-term viability hinges on exposure to sanctioned field developments with recovery factor guarantees rather than exploration-dependent license portfolios. Monitor German industrial gas procurement auction volumes as the inflection signal for Norwegian supply premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Electrification Retrofit | EU Green Deal compliance secures preferential access to German chemical buyers at BASF Ludwigshafen. |
| Subsea Automation Partnership | Aker BP's unmanned platform architecture reduces operational expenditure baselines below manned alternatives. |
| LNG Export Capacity Expansion | Hammerfest liquefaction trains capture Asian demand diversification away from Russian piped supply. |
| Carbon Capture Integration | Field-level emission reductions qualify Norwegian gas for Dutch hydrogen transition feedstock specifications. |
| Digital Reservoir Analytics Acquisition | Real-time monitoring capabilities enable outcome-based service contracts with recovery factor guarantees. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Equinor field operators, Aker BP automation engineers, Norwegian Petroleum Directorate licensing officials, and German industrial gas procurement managers at BASF and Bayer with secondary validation from NPD production statistics, Gassco transport data, EU ETS carbon price records, and Norwegian Ministry of Petroleum and Energy policy documents. Bottom-up field-level production estimates and top-down continental demand projections were triangulated to anchor volume forecasts.
Historical reference periods spanning mature field decline curves and sanctioned project ramp-up phases anchored the projection horizon across the analysis window. Segmentation dimensions modeled include hydrocarbon product type, service category, delivery infrastructure, and end-user industrial segment, with regional regulatory framework clusters treated as distinct demand environments. CAGRs were derived from production capacity buildout schedules, depletion rates from existing fields, and offtake contract renewal patterns. Electrification capex trajectories and carbon border adjustment mechanism implementation timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for subsea all-electric compression or shore-powered platform architectures would alter the outlook for emission intensity benchmarks and field development economics. Forecasts reflect assumptions around EU Green Deal enforcement consistency, Norwegian tax regime stability, and continental European gas demand elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Denmark Oil and Gas Market