
 Conditional Access System (CAS) Market | 2026-2036
Conditional Access System (CAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Conditional Access System (CAS) Market Intelligence
Market Context
India's expanding digital broadcast infrastructure is reshaping competitive dynamics across the Conditional Access System landscape. Verimatrix leverages its software security portfolio to capture OTT platform contracts in emerging markets. Irdeto anchors its position through deep integration with satellite television operators across Africa and the Middle East. Cisco Systems competes on enterprise-grade middleware deployments for tier-one cable television networks.
Technical Definition and Segment Structure
A Conditional Access System comprises encryption, authorization, and subscriber management technologies that restrict digital television and streaming content to authenticated users, typically employing AES-128 or DES algorithms with secure key distribution protocols. Software security solutions are displacing smart card architectures as primary revenue generators, while hardware security modules retain dominance in high-integrity broadcast environments. IPTV and OTT platforms represent the fastest-expanding product type segments, whereas cable television sustains mature, replacement-driven demand across established markets. Service operators command the largest end-user margin pool due to multi-year licensing structures and technical support dependencies.
Regulatory Environment
India's TRAI enforces interoperability mandates and tariff regulations that shape set-top box and CAS procurement decisions for domestic broadcasters. The EU's GDPR and Audiovisual Media Services Directive impose data handling and cross-border content security standards on middleware and streaming deployments. China's SAMR and MIIT coordinate national encryption certification requirements for terrestrial and satellite television systems. Stakeholders must monitor evolving sovereign content protection mandates as governments tighten control over domestic media distribution architectures.
Market Dynamics
Cloud-native software security architectures are systematically dismantling smart card-based conditional access infrastructure, forcing middleware vendors to restructure licensing models and accelerate API-first platform development.
Growth Catalysts
- India's digitization mandates:TRAI's interoperability directives compel broadcasters to upgrade set-top box security layers, creating procurement waves for software CAS solutions.
- OTT platform encryption requirements:Streaming operators across Southeast Asia deploy multi-DRM integration to secure live sports and premium content bundles.
- Rural satellite expansion:Indonesia's direct-to-home subscriber base in remote provinces drives demand for low-cost, high-availability authorization systems.
Market Restraints
- Legacy hardware depreciation cycles:Cable operators in mature markets delay CAS replacement due to embedded smart card infrastructure investments.
- Semiconductor supply volatility:Hardware security module manufacturers face lead time compression for cryptographic processors sourced from concentrated foundry networks.
- Fragmented sovereign encryption standards:China's SAMR certification requirements diverge from IEC protocols, forcing dual-compliance engineering overhead.
Strategic Opportunities
- Software-as-a-service licensing:Tier-two broadcasters in Vietnam and Philippines adopt subscription-based security platforms to avoid capital-intensive hardware procurement.
- 5G broadcast convergence:Mobile network operators integrate CAS functionality into multicast streaming cores for stadium and venue content delivery.
- Post-quantum cryptographic migration:NIST's algorithm standardization timeline creates upgrade windows for AES-128 dependent authorization systems.
Industry Challenges
- Embedded systems engineering scarcity:Firmware developers with secure enclave expertise command premium compensation, constraining vendor scaling velocity.
- Multi-DRM interoperability certification:OTT platforms require simultaneous compliance with Google Widevine, Apple FairPlay, and Microsoft PlayReady protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conditional Access System (CAS) Market |
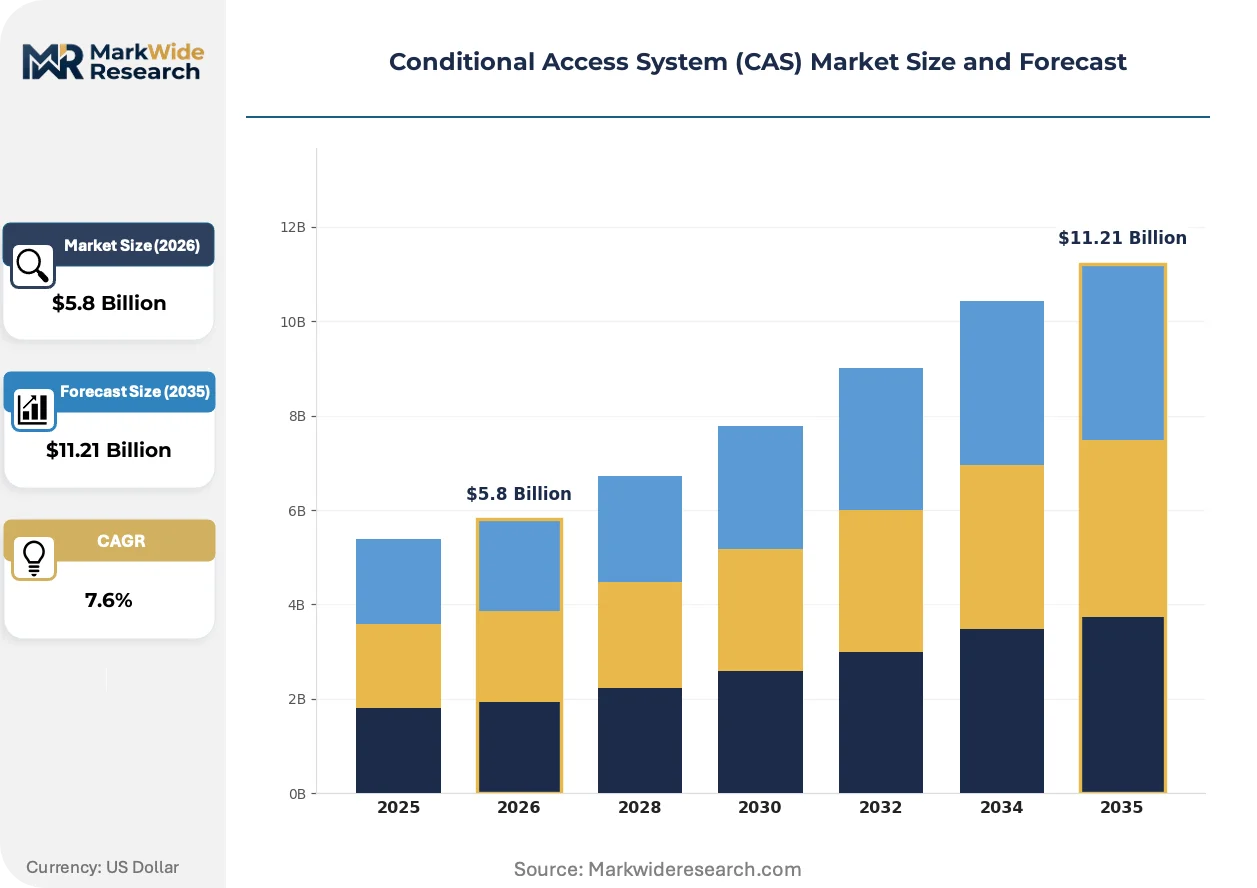
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Card, Middleware, Software Security, Hardware Security Product Type: IPTV, Cable Television, Satellite Television, OTT Platforms End User: Residential Users, Commercial Users, Content Providers, Service Operators Delivery Mode: Streaming, Broadcast, Download, Hybrid |
| Companies Covered | Verimatrix, Alticast Corporation, Cisco Systems, China Digital TV Holding, Wellav Technologies, Irdeto, Viaccess-Orca, ABV International Pte. Ltd., Nagravision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conditional Access System (CAS) Market Strategic Shifts & Innovations
Conditional access infrastructure is undergoing a fundamental architectural pivot from hardware-bound trust anchors to cloud-orchestrated authorization fabrics, compressing deployment timelines and redistributing value toward software engineering competencies.
Blockchain-based entitlement registries are digitizing subscriber rights management for fractional content ownership models. European broadcasters pilot these architectures for pay-per-view boxing and concert streaming. The technology is digitizing how revenue shares distribute across content licensors, distributors, and platform operators in real-time settlement structures.
The EU's Audiovisual Media Services Directive imposes cross-border content portability requirements that force CAS vendors to redesign geo-fencing logic. Middleware providers must now support simultaneous multi-territory licensing without hardware reconfiguration. French and German operators face the steepest compliance curves due to complex rights clearance traditions.
Aggregated security procurement is consolidating vendor relationships as media conglomerates centralize multi-platform content protection. Disney and Warner Bros. Discovery-style portfolio operators now negotiate enterprise-wide CAS licenses spanning cable, satellite, and streaming endpoints. This pattern is most pronounced in North American and Western European markets where vertical integration between studios and distributors has accelerated.
Conditional Access System (CAS) Market Segmentation
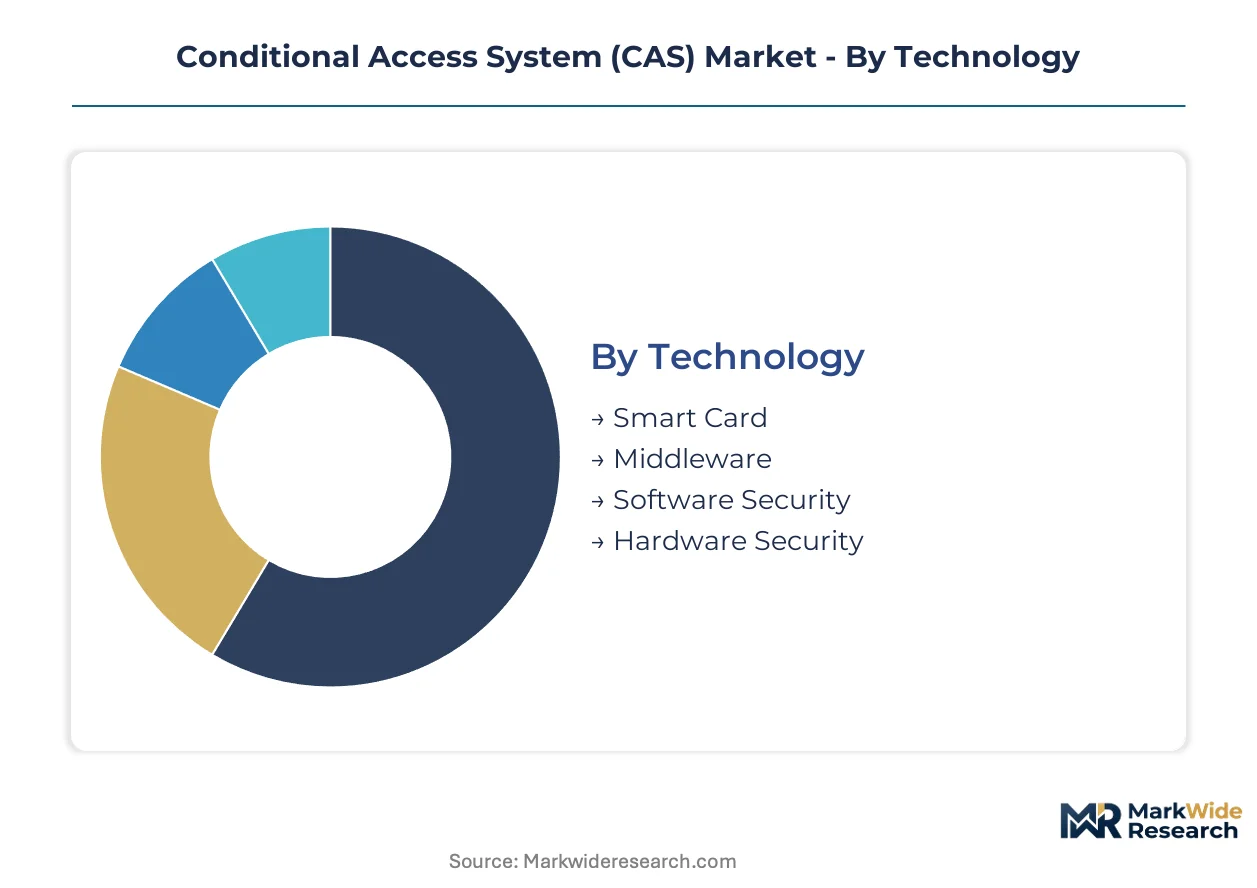
Conditional Access System segmentation reveals how encryption architectures fragment across legacy infrastructure and cloud-native deployments. Technology choices determine capital intensity, while delivery modes reflect shifting viewer consumption patterns across broadcast and streaming ecosystems.
Technology:
Mature hardware-based trust anchors coexist with emerging software-defined security layers as operators navigate depreciation cycles and cloud migration timelines.
- Smart Card:Physical chip-based authentication modules store decryption keys in tamper-resistant silicon. Indonesian DTH operators and legacy cable networks across Southeast Asia maintain procurement for subscriber bases where hardware replacement cycles extend seven to ten years.
- Middleware:Software abstraction layers mediate between CAS security cores and set-top box operating systems. India's TRAI interoperability mandates are accelerating middleware upgrades as domestic broadcasters decouple security from hardware vendors to enable STB portability across service providers.
- Software Security:Cloud-native authorization engines eliminate hardware dependencies through downloadable credentials and API-based entitlement management.
- Hardware Security:Dedicated cryptographic processors and secure enclaves maintain dominance in high-integrity broadcast environments requiring FIPS 140-2 or Common Criteria certification.
Middleware handles the majority of throughput; Software Security is the fastest mover on share.
Product Type:
Application contexts range from managed broadcast networks to unmanaged internet delivery, with distinct security architectures governing each endpoint category.
- IPTV:Managed IP multicast networks deliver encrypted television through telco-controlled infrastructure. Vietnam's fiber-to-the-home expansion and Thailand's broadband penetration are concentrating middleware procurement for IPTV security stacks.
- Cable Television:Hybrid fiber-coaxial networks employ embedded CAS within legacy set-top box populations. Mature markets face replacement-driven demand cycles constrained by embedded smart card infrastructure depreciation.
- Satellite Television:Direct-to-home transmission requires robust conditional access for wide-area broadcast footprints. Indonesia's rural subscriber expansion across remote provinces is driving low-cost, high-availability authorization system demand.
- OTT Platforms:Internet-delivered streaming services integrate multi-DRM architectures spanning Widevine, FairPlay, and PlayReady protocols.
Cable Television retains installed base dominance; OTT Platforms are climbing the fastest on revenue contribution.
End User:
Customer types span individual subscribers through enterprise content aggregators, with procurement authority and technical sophistication determining vendor engagement models.
- Residential Users:Individual households consume encrypted content through retail set-top box or smart TV applications. India's digitization directives are reshaping residential security layers as analog switch-off deadlines force hardware upgrades.
- Commercial Users:Hospitality, healthcare, and enterprise verticals deploy centralized content distribution with bulk licensing requirements.
- Content Providers:Studios and rights holders specify encryption standards and DRM requirements for distribution partners.
- Service Operators:Pay-TV platforms and telecommunications carriers command the largest margin pool through multi-year CAS licensing and technical support dependencies.
Service Operators concentrate procurement volume; Content Providers are gaining leverage fastest on security specification authority.
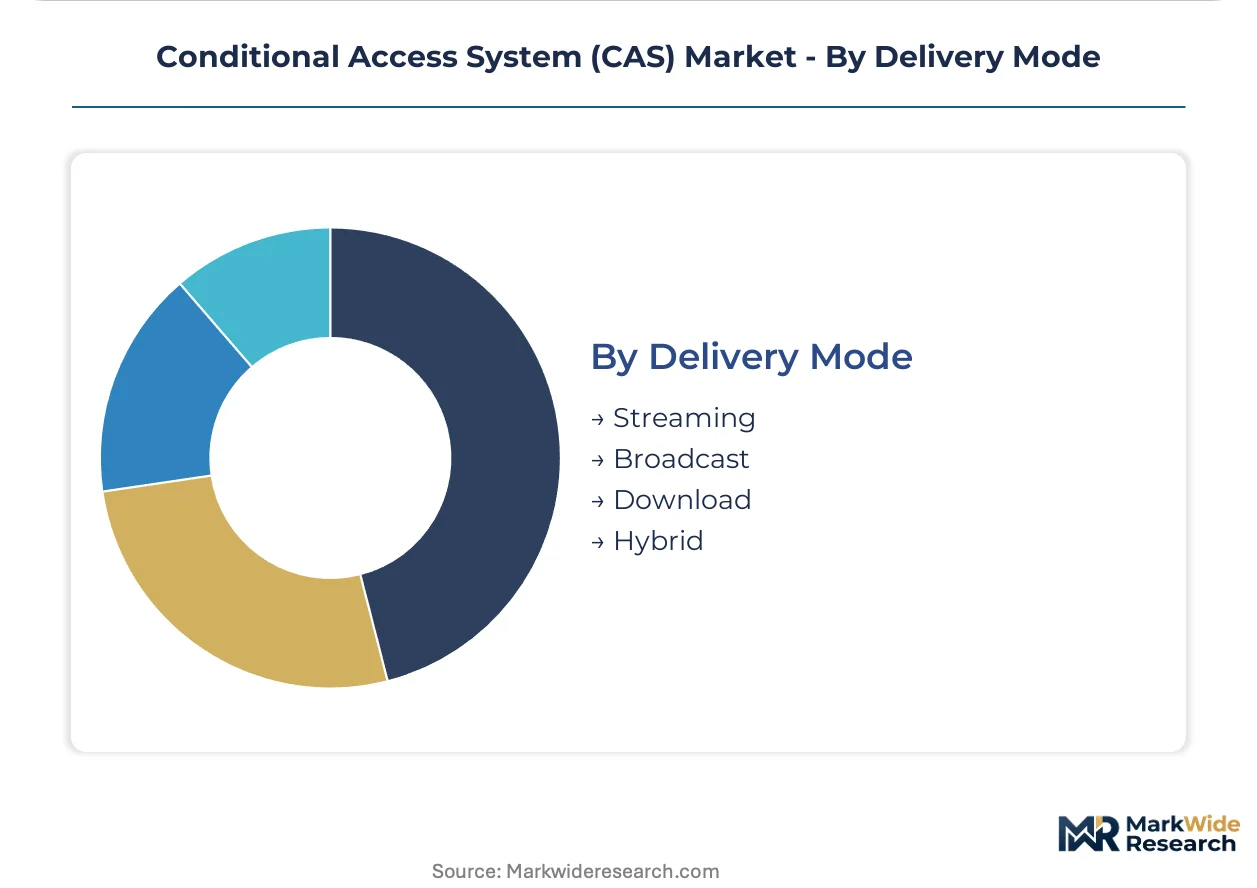
Delivery Mode:
Distribution architectures fragment across real-time and time-shifted consumption patterns, with security implications for live broadcast versus on-demand asset protection.
- Streaming:Continuous IP-based content delivery requires session-based authentication with adaptive bitrate encryption. Southeast Asian sports broadcasters are deploying streaming CAS for live event coverage with concurrent viewer spikes.
- Broadcast:Scheduled transmission over dedicated spectrum employs static entitlement tables with periodic key rotation. Terrestrial and satellite broadcasters across India and Indonesia maintain broadcast CAS for mass-market reach.
- Download:Offline content consumption through secure local storage with time-bound playback windows.
- Hybrid:Combined broadcast-broadband delivery leverages linear channels for efficiency and IP return paths for interactivity.
Broadcast retains the widest deployment footprint; Streaming is expanding most quickly on new installation share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Asia-Pacific broadcast infrastructure hubs where government digitization mandates and rural satellite expansion converge. India's TRAI interoperability directives and Indonesia's direct-to-home subscriber growth anchor procurement volumes for software security and middleware solutions.
India
Domestic broadcasters upgrade set-top box security layers under Ministry of Information and Broadcasting digitization deadlines. TRAI's interoperability mandates compel middleware decoupling from hardware vendors to enable subscriber portability. Maharashtra and Karnataka house the densest clusters of CAS deployment for cable and DTH operators.
Indonesia
Rural direct-to-home subscriber expansion across remote provinces drives demand for low-cost authorization systems. The Ministry of Communication and Informatics coordinates national encryption standards for terrestrial and satellite television platforms. Jakarta and Surabaya serve as primary distribution hubs for middleware procurement to regional operators.
China
Terrestrial and cable television operators migrate toward cloud-native security architectures under MIIT coordination. SAMR certification requirements for domestic encryption modules diverge from IEC protocols, forcing dual-compliance engineering. Beijing and Shanghai concentrate R&D activity for hardware security module development.
Vietnam
Fiber-to-the-home expansion and IPTV penetration concentrate middleware procurement for telco-controlled infrastructure. The Ministry of Information and Communications regulates content encryption standards for multi-screen delivery. Ho Chi Minh City and Hanoi anchor software CAS adoption among tier-two broadcasters.
United States
Tier-one cable networks pursue enterprise-grade middleware deployments for hybrid broadcast-broadband convergence. FCC regulations shape set-top box security requirements for regional cable operators. Los Angeles and New York media clusters drive aggregated security procurement from content conglomerates.
Conditional Access System (CAS) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in encryption algorithm and secure processor supply. The vendor base spans three tiers: multinational technology conglomerates with broadcast middleware portfolios, regional security specialists focused on smart card and software CAS deployment, and emerging cloud-native entrants targeting OTT multi-DRM integration. Consolidation pressure intensifies as media conglomerates centralize enterprise-wide licensing negotiations. Strategic moves cluster around API-first platform development and SaaS licensing model restructuring.
Within the multinational tier, Cisco Systems and Verimatrix occupy positions spanning enterprise middleware and cloud-native software security. Irdeto anchors the specialist tier with deep integration patterns across satellite television operators. Chinese fabricators including China Digital TV Holding and Wellav Technologies exemplify regional encryption module development under sovereign certification frameworks.
| Leading Market Players |
|---|
| Verimatrix |
| Alticast Corporation |
| Cisco Systems |
| China Digital TV Holding |
| Wellav Technologies |
| Irdeto |
| Viaccess-Orca |
| ABV International Pte. Ltd. |
| Nagravision |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's secure processor fabrication facilities is compressing margins for hardware security module manufacturers while simultaneously accelerating the shift toward software-centric licensing models that eliminate silicon dependencies.
Pricing Analysis
India's TRAI interoperability directives dictate the pricing tier structure across the Conditional Access System landscape, forcing middleware vendors to decouple security layers from hardware bundles. Pricing stratifies across premium FIPS 140-2 certified modules, standard middleware integrations, and economy-tier smart card replacements. Cost compression in the hardware tier is intensifying because semiconductor foundries are prioritizing higher-margin AI chip production. Tier-two broadcasters in Vietnam and the Philippines exhibit the highest price sensitivity, whereas tier-one cable networks in the United States prioritize certification grade over unit cost.
Supply Chain Analysis
Extended payment terms from Indonesian direct-to-home operators are straining working capital for middleware vendors deploying rural authorization systems. Supply concentrates in China, Taiwan, and South Korea for cryptographic processors and secure enclave silicon. The ecosystem draws from specialized foundry capacity for tamper-resistant hardware, AES-128 algorithm IP cores, and API orchestration platforms. Single-source vulnerability in advanced node semiconductor fabrication represents the dominant structural risk. Distribution runs through systems integrators that bundle CAS security with set-top box procurement for pay-TV operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Conditional Access System market sits in early-cycle expansion as cloud-native software security architectures displace legacy smart card infrastructure across Southeast Asian broadcast markets.
For Market Incumbents: Insulate middleware revenue streams through deeper API-first platform development and accelerated SaaS licensing transitions. The threat from emerging cloud-native entrants targeting OTT multi-DRM integration demands defensive certification investment in Common Criteria and FIPS 140-2 tiers. Channel control over tier-one cable networks in North America and Western Europe remains the critical defensive lever.
For New Entrants and Emerging Players: Rural satellite expansion across Indonesia's outer provinces offers the most penetrable white-space target for low-cost authorization systems. Vietnam's fiber-to-the-home buildout and tier-two broadcaster segment present secondary entry points. A direct SaaS sales motion to provincial operators bypasses incumbent systems integrator relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among middleware vendors with multi-year service operator licensing structures and technical support dependencies. The five-to-ten year viability window favors cloud-native software security platforms over hardware-dependent legacy architectures. Watch for NIST post-quantum cryptographic standardization timelines as the signal for accelerated replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables TRAI-compliant middleware decoupling for Indian broadcasters seeking STB portability. |
| Multi-DRM Integration Partnership | Secures OTT platform contracts across Southeast Asian sports streaming operators. |
| SaaS Licensing Model Transition | Captures tier-two broadcasters in Vietnam and Philippines avoiding capital-intensive hardware. |
| Post-Quantum Cryptographic Migration | Positions vendors for NIST-standardized algorithm upgrades across AES-128 dependent systems. |
| 5G Broadcast Convergence Investment | Integrates CAS functionality into mobile network multicast cores for stadium content delivery. |
Research Approach
Operator-level perspectives from pay-TV platform executives, broadcast engineering directors, set-top box procurement managers, and OTT platform security architects anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against TRAI regulatory filings, Ministry of Information and Broadcasting digitization directives, and customs data for cryptographic hardware imports. SEC disclosures from Cisco Systems and Verimatrix, alongside ASEAN telecommunications regulatory circulars, provided financial and policy context. Bottom-up subscriber penetration modeling and top-down encryption infrastructure spend estimates were triangulated for cross-validation.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic, baseline, and conservative tracks reflecting divergent digitization enforcement intensity and semiconductor supply normalization timelines. Segmentation dimensions modeled include technology architecture, product type, delivery mode, and regional regulatory cluster. CAGRs were derived from subscriber growth trajectories, replacement cycle compression, and software licensing mix shifts. Industry-specific forecast inputs incorporated Indonesia's rural DTH expansion targets and India's analog switch-off deadlines.
Practitioners should monitor sovereign encryption standard divergence, post-quantum algorithm standardization timelines, and 5G broadcast deployment velocity for early signals of forecast deviation. The analysis reflects assumptions regarding continued regulatory enforcement of interoperability mandates and stable foundry capacity allocation for security silicon. Macroeconomic contraction in emerging market broadcast advertising, abrupt shifts in national encryption certification requirements, or faster-than-anticipated smart card infrastructure abandonment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
APAC Machine Vision Systems Market
Others
Europe Indoor Air Purification Market
Others
Rotary Dial Machine Market
Others
Smart Home Gateways Market
Others
LAMEA Astrology Market
Others
South America Halal Food and Beverages Market
Others
Mainframe Computers Market
Others
Global Pumpkin Candles Market
Others
Live IP Broadcast Equipment Market
Others
Cellular-Connected Laptops Market
Others
US 3D Printing Construction Market
Others
Aircraft Exterior Lighting Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Education and Learning Analytics Market
Others
Europe Street Lighting Market
Others
Receiving Scales Market