
 Buchner Funnels Market | 2026-2036
Buchner Funnels Market Size, Share, and Industry Trends Forecast 2026-2036
Buchner Funnels Market Analysis
Multi-sourcing of borosilicate glass feedstock is decoupling from traditional European supply bases as manufacturers diversify procurement across Asia-Pacific melting facilities. Corning Incorporated leverages captive glass-forming technology to sustain premium positioning in analytical-grade funnel production. Thermo Fisher Scientific anchors its portfolio through integrated distribution spanning North American research institutions. Merck KGaA competes on pharmacopeia-compliant certification depth across European laboratory markets.
Buchner funnels are perforated filtration vessels, typically constructed from borosilicate glass or polypropylene, designed for vacuum-assisted solid-liquid separation using filter media placed across the flat perforated plate. The device operates on pressure differential principles, with standard pore plate specifications ranging from 10 mm to 150 mm diameter to accommodate varying sample volumes in chemical synthesis and environmental testing workflows. Glass material segments dominate analytical applications where thermal shock resistance and solvent compatibility are non-negotiable, while plastic variants capture educational institutions and high-throughput screening environments where breakage risk and cost sensitivity predominate. Laboratory use applications generate the most intensive replacement demand due to sterilization protocols and cross-contamination prevention requirements, whereas chemical processing buyers prioritize large-format and custom-sized configurations for pilot-scale operations.
FDA cGMP guidelines for pharmaceutical manufacturing equipment validation shape material traceability requirements for Buchner funnel suppliers serving drug substance producers. REACH substance restrictions and EU MDR technical documentation obligations compel European vendors to maintain comprehensive chemical composition declarations for glass and polymer contact surfaces. ISO 4793 laboratory glassware standards provide the baseline dimensional and thermal performance benchmarks that procurement teams reference in qualified supplier audits. Stakeholders must monitor evolving biopharma facility investments in single-use technologies against sustained demand for durable glassware in analytical method development.
Market Dynamics
Pharmaceutical quality control laboratories in India are expanding sterile filtration workflows, pulling borosilicate glass Buchner funnel demand away from traditional European supply bases as manufacturers diversify procurement across Asia-Pacific melting facilities.
Growth Catalysts
- EU MDR material compliance:Tightening technical documentation obligations for laboratory glassware imported into Europe compel vendors to maintain comprehensive chemical composition declarations, favoring certified suppliers with existing pharmacopeia depth.
- Borosilicate glass thermal properties:Analytical applications where thermal shock resistance and solvent compatibility are non-negotiable sustain replacement demand from sterilization protocols and cross-contamination prevention requirements.
- Germany's chemical processing corridor:Demand concentrates around Ludwigshafen and Leverkusen for large-format and custom-sized configurations serving pilot-scale operations.
Market Restraints
- European feedstock concentration:Traditional borosilicate glass supply bases in Europe face decoupling pressure as multi-sourcing strategies shift procurement toward Asia-Pacific melting facilities, creating transitional supply friction.
- Single-use technology substitution:Biopharma facility investments in disposable filtration systems threaten sustained demand for durable glassware in analytical method development workflows.
- REACH substance restrictions:Chemical composition declaration requirements for polymer contact surfaces add compliance cost layers for European vendors serving regulated end-uses.
Strategic Opportunities
- Indian pharmaceutical expansion:Quality control laboratory buildouts in Mumbai and Hyderabad create pull for pharmacopeia-compliant borosilicate glass filtration vessels with documented thermal performance.
- ISO 4793 certification depth:Procurement teams reference dimensional and thermal performance benchmarks in qualified supplier audits, rewarding vendors with established standard compliance.
- Educational plastic variants:Polypropylene configurations capture institutional buyers where breakage risk and cost sensitivity predominate over analytical-grade specifications.
Industry Challenges
- Pharmacopeia certification timelines:FDA cGMP validation requirements for pharmaceutical manufacturing equipment extend material traceability documentation cycles, compressing supplier response windows.
- Feedstock reconfiguration:Decoupling from European glass supply bases requires technical qualification of Asia-Pacific melting facility outputs against established thermal shock benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buchner Funnels Market |
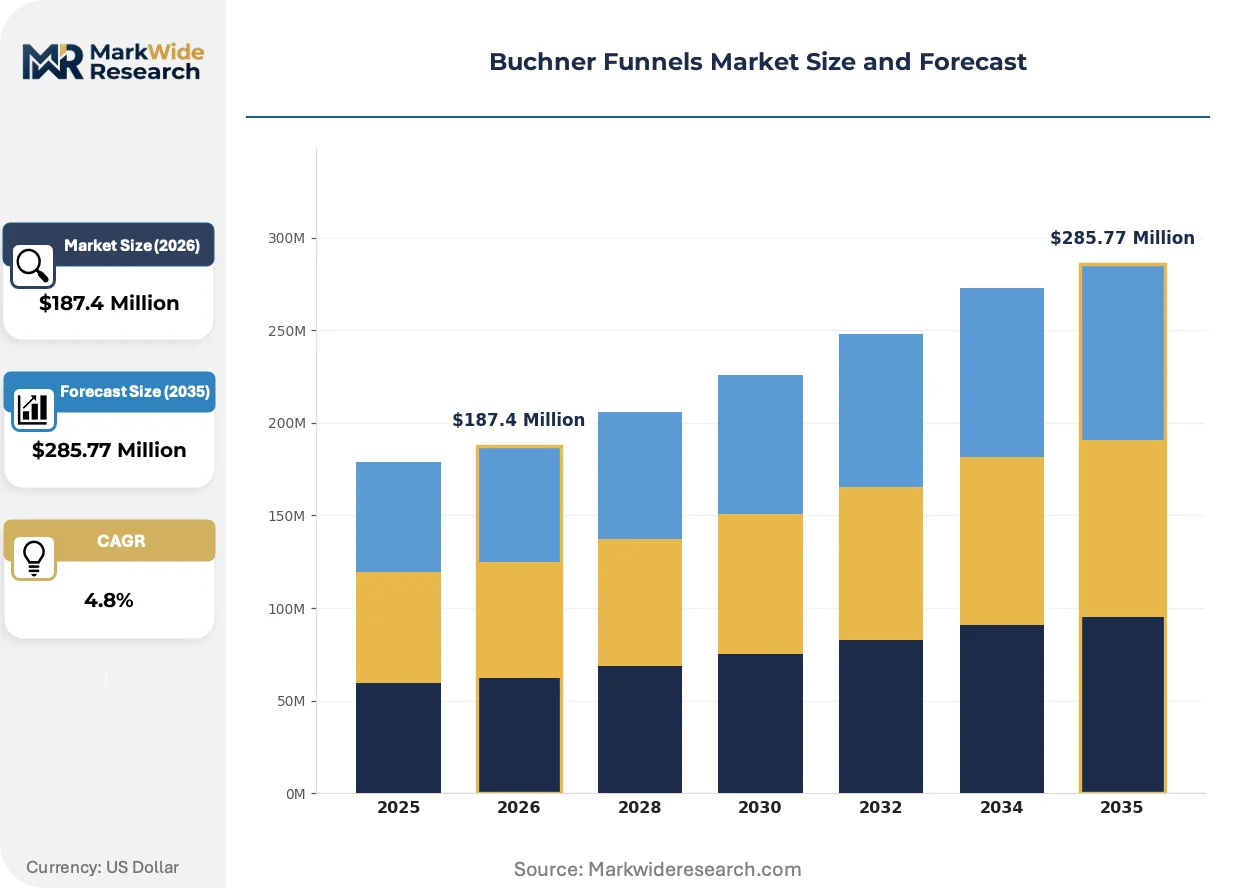
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Stainless Steel, Ceramic Size: Small, Medium, Large, Custom Application: Chemical Processing, Water Treatment, Laboratory Use, Educational Institutions Type: Standard, Venting, High Viscosity, Others |
| Companies Covered | Corning Incorporated, Thermo Fisher Scientific, Merck KGaA, VWR International, Sigma-Aldrich, Kimble Chase, Avantor, DURAN Group, Labconco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buchner Funnels Market Emerging Trajectories
Filtration vessel technology is absorbing pressure from dual-use demands spanning sterile pharmaceutical workflows and high-throughput environmental testing, forcing material science adaptations across glass and polymer platforms.
Sintered glass frit technology is absorbing incremental performance requirements from analytical laboratories running aggressive solvent protocols. Contract research organizations in Boston and Basel are adopting fritted Buchner variants at accelerated replacement cycles. The technology is absorbing thermal stress tolerance demands that perforated plate designs cannot satisfy, compressing the addressable market for standard configurations.
REACH substance restrictions and EU MDR technical documentation obligations compel European vendors to maintain comprehensive chemical composition declarations for all contact surfaces. Laboratory glassware imports face heightened scrutiny at Rotterdam and Hamburg entry points. Analytical-grade suppliers with pre-positioned pharmacopeia depth are capturing procurement preference shifts from buyers front-loading compliance documentation.
Consolidated buying by multinational pharmaceutical quality control networks is compressing supplier bases toward vendors with integrated distribution and certification depth. Direct procurement from melting facility operators is displacing layered distributor relationships in North American research institutions. This concentration is most visible in Massachusetts and North Carolina biopharma clusters, where procurement teams prioritize single-source accountability over price differentiation.
Buchner Funnels Market Segmentation
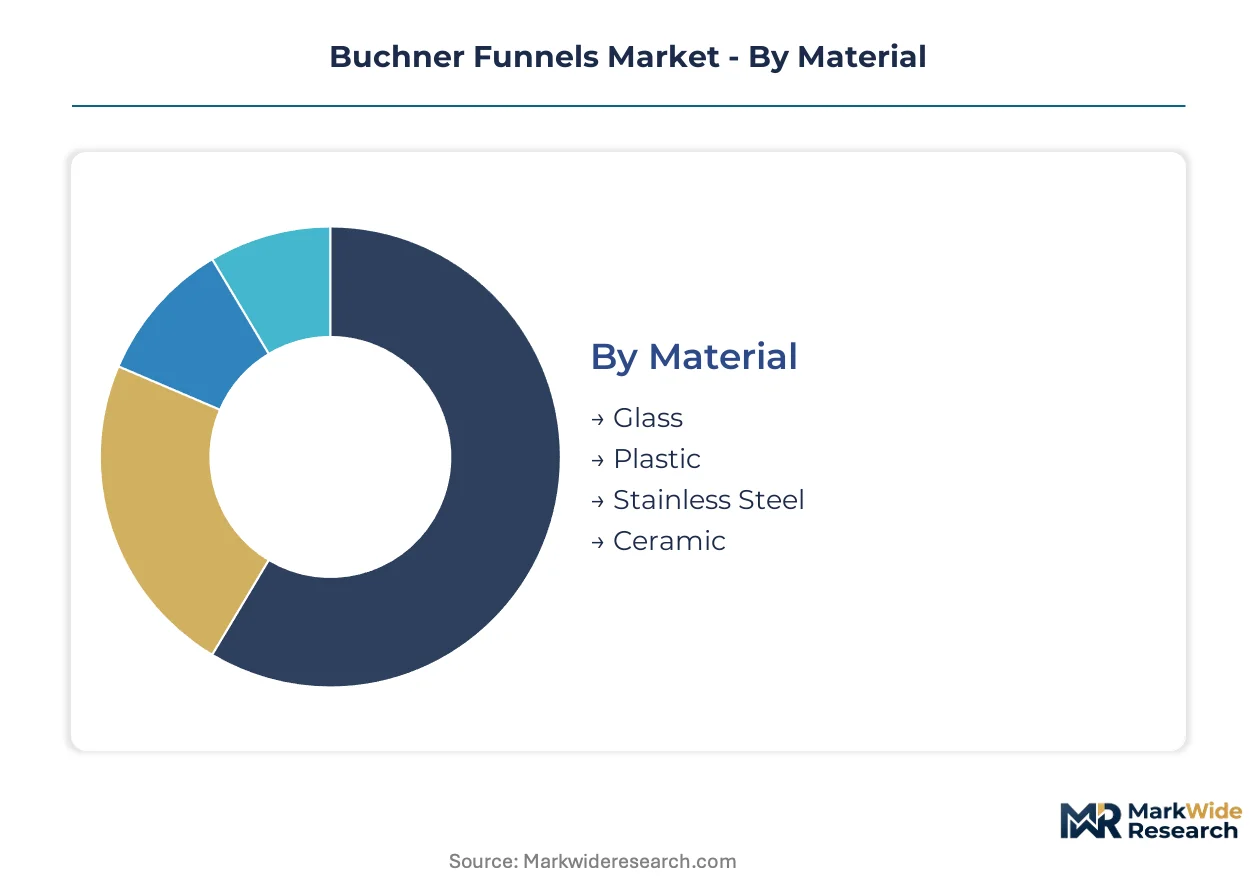
Material composition and dimensional specifications create divergent margin profiles across the Buchner funnels market. Procurement teams segment purchases by thermal performance requirements, breakage risk tolerance, and sterilization protocol intensity.
Material:
Volume concentrates in cost-driven segments, while premium pricing accrues to thermal performance leaders.
- Glass:Borosilicate formulations dominate analytical workflows where thermal shock resistance and solvent compatibility are mandatory. Pharmaceutical quality control laboratories in India and Germany's chemical processing corridor around Ludwigshafen sustain replacement demand from sterilization protocols and cross-contamination prevention requirements.
- Plastic:Polypropylene configurations capture educational institutions and high-throughput screening environments where breakage risk and cost sensitivity predominate over analytical-grade specifications. Procurement teams prioritize volume discounts for institutional buyers running non-aggressive solvent protocols.
- Stainless Steel:Industrial-scale filtration operations deploy corrosion-resistant variants for aggressive chemical processing environments.
- Ceramic:Specialized applications in high-temperature synthesis workflows require thermal stability beyond glass limits.
Today's leader: Glass. Tomorrow's challenger: Plastic.
Size:
Application scale determines diameter selection, with pilot operations driving custom specification growth.
- Small:Analytical method development and environmental testing workflows standardize on 10-50 mm diameters for limited sample volumes.
- Medium:Quality control laboratories deploy 60-100 mm configurations for routine pharmaceutical filtration tasks.
- Large:Chemical processing buyers in Germany's Leverkusen cluster prioritize 120-150 mm formats for pilot-scale solid-liquid separation operations.
- Custom:Contract research organizations commission non-standard dimensions to integrate with proprietary reactor configurations, climbing the fastest among size categories.
Standard sizes anchor procurement volume. Custom specifications capture margin expansion.
Application:
Regulatory intensity varies sharply across end-use environments, shaping material certification requirements.
- Chemical Processing:Pilot-scale operations demand large-format configurations with documented thermal performance for aggressive solvent protocols.
- Water Treatment:Environmental testing laboratories standardize on medium-diameter glassware for particulate filtration compliance workflows.
- Laboratory Use:Replacement cycles accelerate from sterilization protocols and cross-contamination prevention mandates in pharmaceutical quality control settings.
- Educational Institutions:Cost-sensitive procurement prioritizes plastic variants where breakage risk and budget constraints override analytical precision requirements.
Laboratory use commands replacement frequency. Educational institutions drive volume scale.
Type:
Functional specialization segments address pressure differential and flow characteristics.
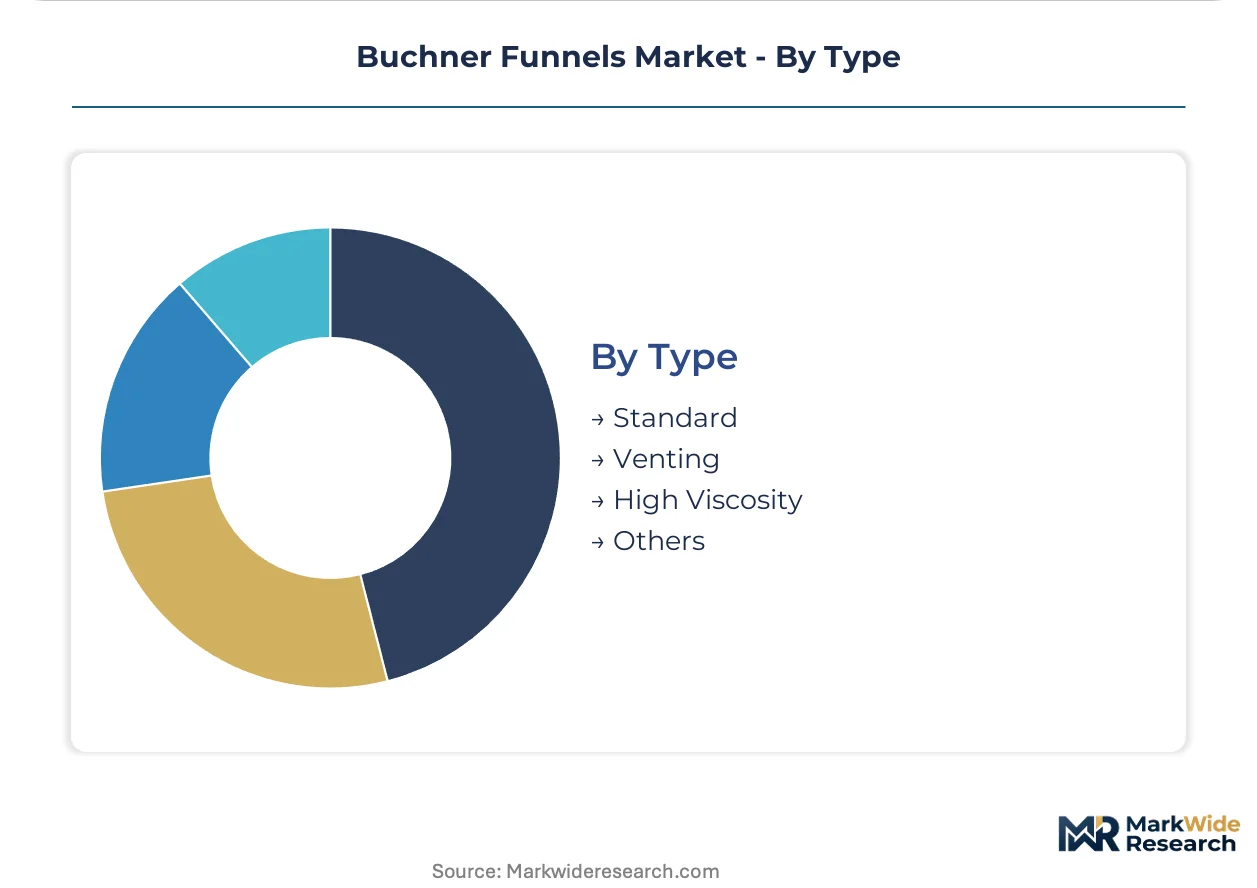
- Standard:Perforated plate designs satisfy routine vacuum-assisted filtration across research and educational settings.
- Venting:Pressure-equalization features prevent seal failure in high-throughput screening environments.
- High Viscosity:Optimized pore geometry accommodates dense slurries in chemical processing workflows.
- Others:Fritted glass variants absorb thermal stress tolerance demands that perforated designs cannot satisfy in aggressive solvent protocols.
Standard configurations dominate unit volume. High viscosity designs capture process-scale premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as EU MDR compliance costs widen the gap between European manufacturing and Asia-Pacific melting facility outputs. Manufacturers are diversifying borosilicate glass feedstock procurement toward lower-cost certification environments while maintaining pharmacopeia-grade quality benchmarks.
Germany
BASF and Bayer operations in Ludwigshafen and Leverkusen sustain concentrated demand for large-format Buchner funnels in pilot-scale chemical processing. REACH substance restrictions and EU MDR technical documentation obligations compel domestic vendors to maintain comprehensive chemical composition declarations. The North Rhine-Westphalia chemical corridor anchors European demand for thermal-shock-resistant glassware.
United States
FDA cGMP guidelines for pharmaceutical manufacturing equipment validation shape material traceability requirements across Massachusetts and North Carolina biopharma clusters. Contract research organizations in Boston accelerate replacement cycles for fritted glass variants. Direct procurement from melting facility operators is displacing layered distributor relationships in research institutions.
India
Quality control laboratory buildouts in Mumbai and Hyderabad create pull for pharmacopeia-compliant borosilicate glass filtration vessels. CDSCO oversight of sterile manufacturing workflows tightens equipment validation protocols. Pharmaceutical quality control laboratories are expanding sterile filtration workflows, pulling demand toward Asia-Pacific supply bases.
China
NMPA regulation of laboratory equipment imports shapes procurement standards for analytical-grade glassware in Yangtze River Delta research parks. Domestic melting facilities are capturing multi-sourcing strategies from multinational manufacturers. Zhengzhou and Shanghai clusters concentrate glass-forming capacity serving regional chemical synthesis operations.
Switzerland
Swissmedic oversight of pharmaceutical quality systems drives premium-tier demand for ISO 4793-certified laboratory glassware in Basel contract research organizations. Sintered glass frit technology adoption is accelerating among analytical laboratories running aggressive solvent protocols. The country's precision manufacturing heritage supports high-margin specialty funnel configurations.
Buchner Funnels Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certification-depth differentiation in regulated pharmaceutical environments. The vendor base organizes around three strategic archetypes: integrated life sciences conglomerates with captive distribution networks, specialized laboratory glassware fabricators with pharmacopeia depth, and regional melting facility operators supplying private-label configurations. Consolidated buying by multinational pharmaceutical quality control networks is compressing supplier bases toward vendors with integrated distribution. Two dominant competitive moves are shaping positioning: backward integration into borosilicate glass feedstock production and geographic expansion toward Indian and Chinese pharmaceutical manufacturing corridors.
Among integrated life sciences conglomerates, Corning Incorporated and Thermo Fisher Scientific exemplify archetypes built on captive technology and distribution scale. Corning leverages glass-forming heritage to anchor premium positioning in analytical-grade segments. Thermo Fisher anchors portfolio breadth through North American research institution networks. Merck KGaA occupies a position defined by pharmacopeia-compliant certification depth across European laboratory markets, representing the specialized regulatory-depth archetype against scale-driven competitors.
| Leading Market Players |
|---|
| Corning Incorporated |
| Thermo Fisher Scientific |
| Merck KGaA |
| VWR International |
| Sigma-Aldrich |
| Kimble Chase |
| Avantor |
| DURAN Group |
| Labconco Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between pharmacopeia-compliant borosilicate glass and commodity polypropylene funnels manifests in both pricing power and supply chain architecture. Premium thermal performance tiers command 3-4x unit economics over educational plastic variants, with EU MDR documentation obligations compressing margin capture for uncertified suppliers while rewarding vendors with pre-positioned pharmacopeia depth.
Pricing Analysis
Distributor margin layers in laboratory glassware typically absorb 35-45 percent of end-user pricing before reaching research institutions or pharmaceutical quality control facilities. Three-tier pricing structure across premium, standard, and economy levels separates ISO 4793-certified analytical grades from institutional polypropylene and private-label imports. Cost compression in the educational plastic tier is intensifying because Asian melting facilities are flooding volume segments with undifferentiated feedstock. Contract research organizations in Basel and Boston exhibit the lowest price sensitivity, while secondary schools and community colleges drive aggressive procurement negotiations.
Supply Chain Analysis
Borosilicate glass feedstock rests on German, Chinese, and Indian melting facility operators with varying pharmacopeia qualification depth. Raw material dependencies center on high-purity silica sand, boron oxide sourcing, and platinum-rhodium alloy forming equipment. Single-source vulnerability concentrates around European specialty glass producers facing REACH substance restriction compliance costs. Distribution runs through integrated life sciences distributors and direct procurement channels serving North American research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation obligations compound procurement preference toward certified suppliers, creating durable demand insulation for vendors with pre-positioned pharmacopeia depth.
For Market Incumbents: Cement pharmacopeia certification moats through backward integration into borosilicate glass feedstock production, particularly across Asia-Pacific melting facilities. Expand ISO 4793 audit documentation to capture procurement preference shifts from multinational pharmaceutical quality control networks consolidating supplier bases. Single-use filtration technology substitution threatens durable glassware demand in biopharma method development workflows.
For New Entrants and Emerging Players: Launch via direct-to-laboratory distribution partnerships targeting Indian pharmaceutical quality control buildouts in Mumbai and Hyderabad. White-space concentration sits in custom-dimension fritted glass configurations for contract research organizations running aggressive solvent protocols. Penetrate through pharmacopeia-compliant certification investment rather than price undercutting.
For Investors and Strategic Acquirers: Consolidation pressure builds where pharmacopeia documentation depth overlaps with captive borosilicate glass-forming technology. Long-term viability favors vertically integrated specialists with melting facility control and established European regulatory compliance infrastructure. Watch sintered glass frit adoption rates among Boston and Basel analytical laboratories as inflection indicator for standard perforated plate displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive borosilicate glass production insulates margin capture from REACH compliance cost pass-through. |
| Pharmacopeia Certification Investment | EU MDR documentation depth captures procurement preference from consolidating pharmaceutical quality control networks. |
| Custom Dimension Development | Non-standard fritted configurations integrate with proprietary reactor setups at Basel contract research organizations. |
| Asia-Pacific Melting Facility Qualification | Technical validation of Chinese and Indian glass outputs decouples supply from European concentration risk. |
| Direct Distribution Channel Buildout | Single-source accountability displaces layered distributor relationships in Massachusetts biopharma clusters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory procurement managers, pharmaceutical quality control directors, chemical processing plant engineers, and borosilicate glass melting facility operators with secondary validation against FDA cGMP guidance documents, REACH substance restriction databases, ISO 4793 laboratory glassware standards, and customs trade flow records. Bottom-up segment sizing and top-down market reconciliation triangulated volume estimates.
Segment-weighting across material composition, dimensional specification, application intensity, and regional regulatory cluster density shaped the analytical framework. CAGRs derived from normalized replacement cycle frequencies, sterilization protocol expansion rates, and biopharma facility investment trajectories. Modeled inputs included CDSCO equipment validation timelines, EU MDR documentation obligation phase-ins, and single-use technology substitution elasticities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restriction amendments or accelerated biopharma adoption of disposable filtration systems. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Surface Green Mining Market
Others
Europe Aircraft Lighting Systems Market
Others
Bio-Based Leather Market
Others
Global Extruded Plastics Market
Others
Gas Radiators Market
Others
Middle East 3D Printing Construction Market
Others
South Korea Automotive LED Lighting Market
Others
Connected Homes Market
Others
China Smart Home Market
Others
GCC Cigarette Market
Others
Vegan Confectionery Market
Others
Asia-Pacific Laser Hair Removal Market
Others
Spinner Flask Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Gem Faceting Machine Market
Others
Nyerereite Market