
 Global Optical Comparator Market | 2026-2036
Global Optical Comparator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Comparator Market Foresight
Contract manufacturers serving medical device OEMs is rotating toward higher-accuracy digital comparator platforms. Mitutoyo Corporation leverages its metrology heritage to sustain dominance in Japanese and North American calibration labs. Starrett anchors its position through deep distribution into American job shops and vocational training channels. Nikon Metrology competes on optical system resolution, differentiating its offerings for semiconductor wafer inspection.
An optical comparator projects a magnified shadow or profile of a manufactured part onto a ground-glass screen for dimensional verification against calibrated overlays, typically achieving magnification ratios from 10x to 100x with resolution down to micrometer scales. Digital optical comparators command the widest installed base as shops phase out manual stage configurations. Quality control applications absorb the majority of unit volume, though research and development laboratories generate disproportionate margin pools due to custom configuration requirements. 3D measurement technology is displacing legacy 2D profiling in automotive powertrain inspection lines.
The U.S. Food and Drug Administration enforces process validation requirements that drive pharmaceutical subcontractors toward documented optical inspection protocols. Japan's Ministry of Economy, Trade and Industry promotes precision manufacturing standards that elevate domestic comparator specifications. China's State Administration for Market Regulation harmonizes GB metrology standards with ISO frameworks, easing import certification for European and Japanese equipment vendors. Stakeholders must weigh captive calibration service investments against third-party accreditation costs as buyer compliance requirements diverge across national inspection regimes.
Market Dynamics
3D optical measurement systems are compressing replacement cycles for legacy 2D shadowgraph comparators across precision manufacturing corridors, forcing incumbent vendors to defend installed bases through software retrofit programs and calibration service bundling.
Growth Catalysts
- ISO 10360 Tolerance Compression:German and Japanese machine shops face accelerated recertification mandates that obsolete manual-stage comparators before full depreciation, creating pull for automated digital platforms.
- Semiconductor Wafer Inspection:Sub-micron resolution requirements in advanced packaging processes are expanding optical comparator deployment into back-end lithography-adjacent quality stations.
- FDA Process Validation:Pharmaceutical subcontractors in the United States must document dimensional verification protocols, converting paper-based inspection logs into traceable digital measurement records.
Market Restraints
- CMOS Sensor Supply Concentration:Japanese and South Korean component fabricators control high-resolution imager supply, exposing comparator OEMs to allocation risk during fab capacity constraints.
- Coordinate Measuring Machine Substitution:Touch-probe CMMs with optical scanning heads capture 3D features in single setups, eroding the comparator's historical advantage in complex profile verification.
- RoHS Compliance Friction:European environmental directives restrict legacy leaded glass and mercury vapor illumination sources, complicating spare parts logistics for aging installed bases.
Strategic Opportunities
- India Medical Device Manufacturing:CDSCO regulatory harmonization with ISO 13485 is attracting contract manufacturers that require documented optical inspection for export certification.
- AI-Assisted Edge Detection:Machine vision algorithms paired with traditional optical projection are enabling automated pass-fail decisions without operator interpretation, opening high-volume automotive fastener inspection.
- Calibration-as-a-Service:Third-party metrology laboratories in the United States are unbundling annual recertification from equipment purchase, lowering capital barriers for job shop entry.
Industry Challenges
- Dimensional Metrology Technician Scarcity:Vocational programs in the United States and Germany are graduating fewer operators capable of interpreting optical overlay alignments against GD&T callouts.
- Legacy Integration Complexity:Digital comparator retrofits must interface with MES and QMS platforms through proprietary data formats, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Comparator Market |
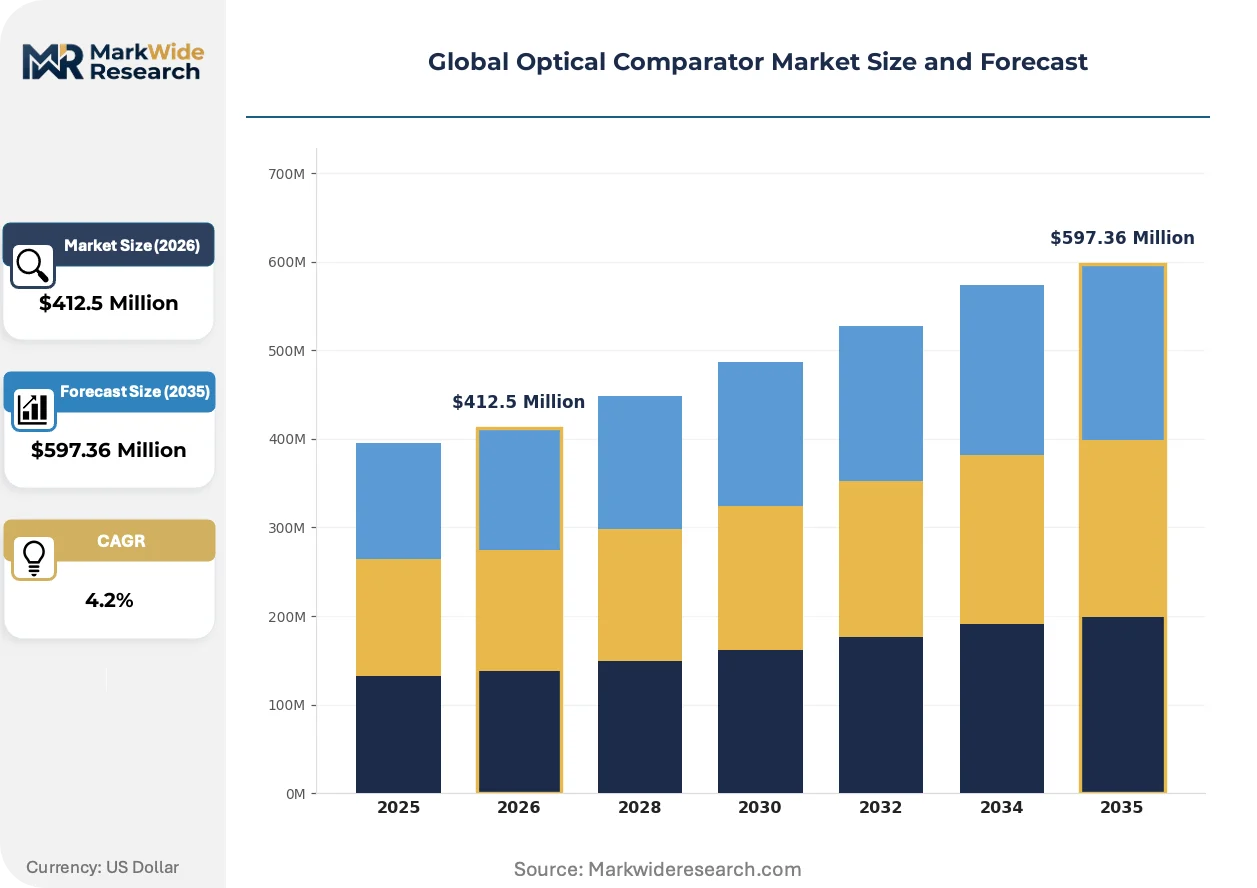
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Optical Comparators, Digital Optical Comparators, Automated Optical Comparators, Portable Optical Comparators End User: Aerospace, Automotive, Manufacturing, Electronics Technology: 2D Measurement, 3D Measurement, Laser Measurement, Image Processing Application: Quality Control, Product Inspection, Tool Making, Research & Development |
| Companies Covered | Mitutoyo Corporation, Starrett, Nikon Metrology, Quality Vision International Inc., Keyence Corporation, J&L Metrology, Inc., S-T Industries Inc., Hexagon Manufacturing Intelligence, Gagemaker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Comparator Market Shifts & Advancements
Optical comparator architecture is bifurcating between high-resolution digital capture systems for precision applications and cost-optimized configurations for routine shop-floor verification, with software functionality becoming the primary differentiation axis.
Telecentric lens arrays with sub-pixel edge detection algorithms are supplanting conventional shadowgraph projection in semiconductor and medical device inspection lines. Aerospace Tier-1 suppliers in the United States and France are adopting these configurations for turbine blade root profile verification. The shift is compressing tolerance bands below what ground-glass screen overlays can resolve, relegating analog comparators to training and rough-cut applications.
China's SAMR harmonization of GB metrology standards with ISO 10360 frameworks is eliminating technical barriers that previously required European and Japanese vendors to maintain separate product variants. Domestic Chinese manufacturers are leveraging this convergence to certify platforms for export markets, intensifying price competition in Southeast Asian procurement channels. Foreign OEMs are responding by localizing final assembly and calibration operations within Chinese free-trade zones.
Contract manufacturers serving automotive OEMs are consolidating vendor relationships and demanding bundled calibration, training, and spare parts availability through single-source agreements. This concentration is marginalizing small regional distributors that lack nationwide service networks. The pattern is most pronounced in the American Midwest and German Baden-Württemberg, where powertrain suppliers operate just-in-time inspection cells requiring four-hour response commitments.
Global Optical Comparator Market Segmentation
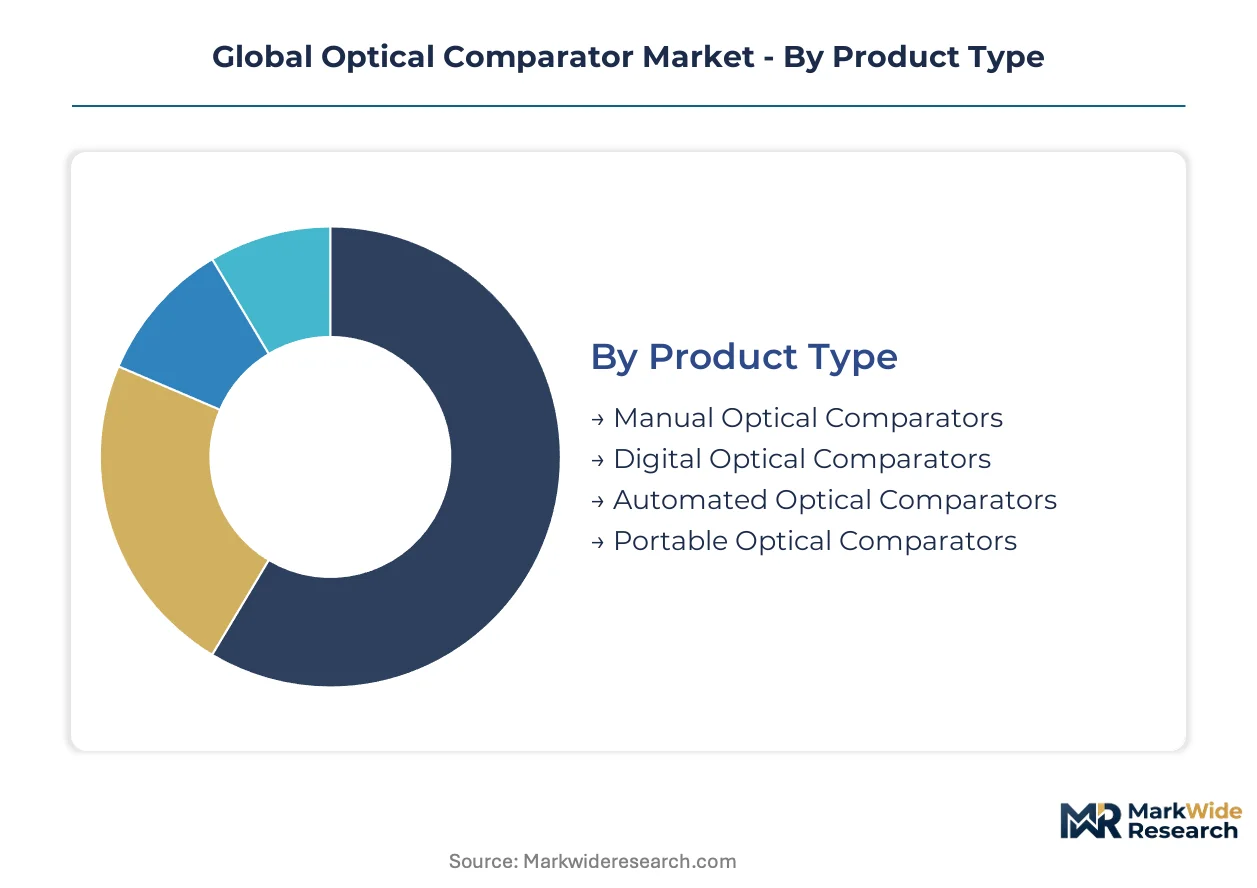
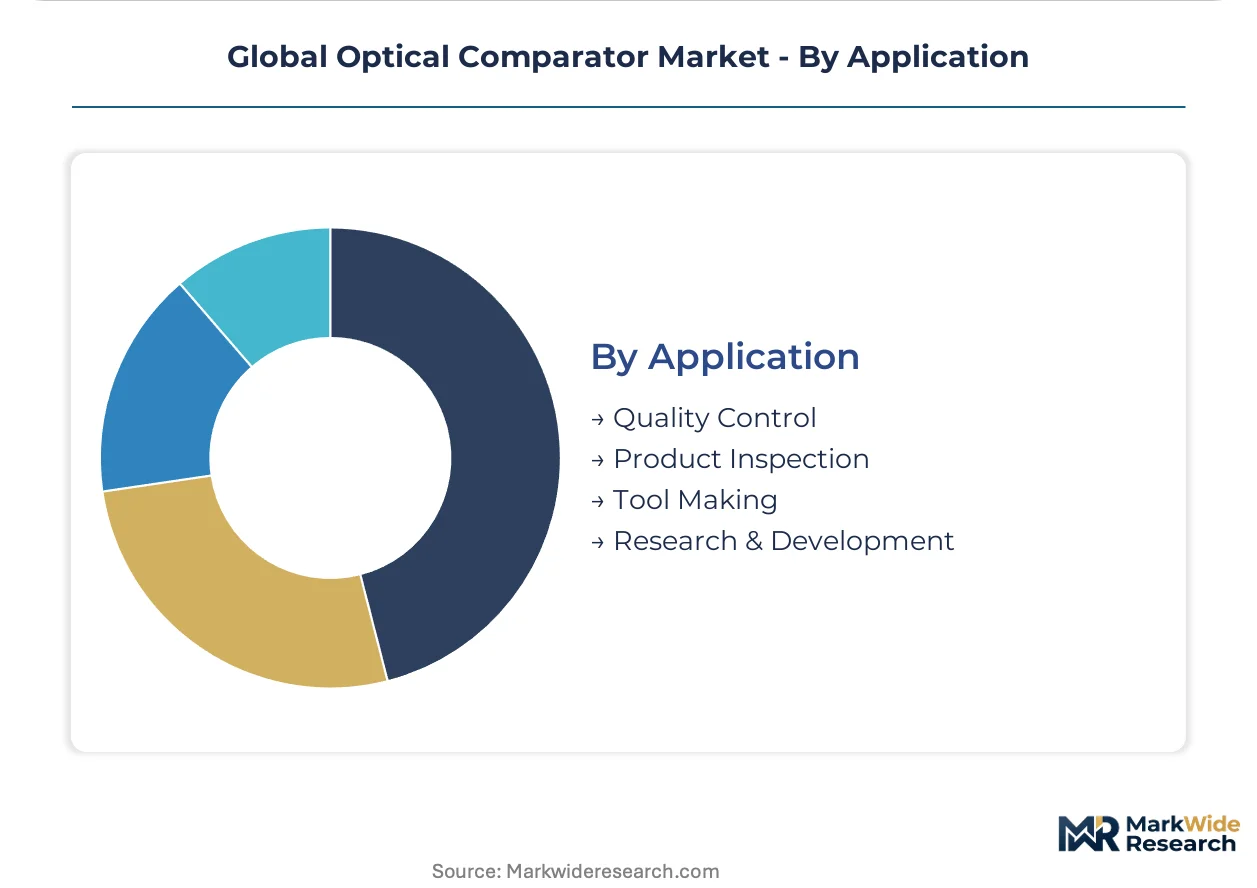
Optical comparator procurement patterns diverge sharply across product configurations, end-use industries, and measurement technologies. Regulatory validation requirements and tolerance compression mandates reshape segment prioritization for vendors and buyers alike.
Product Type:
FDA process validation in pharmaceutical subcontracting and ISO 10360 recertification mandates in Germany and Japan create divergent equipment specifications across comparator categories.
- Digital Optical Comparators:These platforms integrate CMOS sensors and software overlays to replace ground-glass screen interpretation. Aerospace manufacturers in the United States and France are consolidating procurement around these systems for turbine blade verification.
- Automated Optical Comparators:Motorized stages with programmable inspection routines eliminate operator-dependent alignment errors. Japanese machine shops facing METI precision manufacturing standards are accelerating replacement of manual configurations.
- Manual Optical Comparators:Basic shadowgraph projection remains prevalent in vocational training environments and rough-cut verification where tolerance bands exceed 25 micrometers.
- Portable Optical Comparators:Compact benchtop units serve field calibration and on-site inspection for construction equipment remanufacturing in the American Midwest.
Digital platforms handle the majority of throughput; automated systems are climbing the fastest on share.
End User:
Cost tier differentiation separates capital-intensive inspection cells from entry-level verification stations across manufacturing verticals.
- Aerospace:Tier-1 suppliers in the United States and France demand sub-micron resolution for turbine blade root profiles. FAA airworthiness directives mandate documented dimensional verification traceable to NIST standards.
- Automotive:Powertrain manufacturers in Germany's Baden-Württemberg region operate just-in-time inspection cells requiring four-hour service response commitments.
- Manufacturing:General precision machining corridors across the United States, China, and South Korea absorb volume for routine dimensional verification.
- Electronics:Semiconductor packaging processes in South Korea and Taiwan deploy optical comparators for back-end lithography-adjacent quality stations.
Manufacturing absorbs the highest unit volume; electronics shows the steepest expansion trajectory.
Technology:
Application maturity separates legacy shadowgraph methods from emerging capture systems in semiconductor and medical device inspection.
- 3D Measurement:Telecentric lens arrays with sub-pixel edge detection capture complex profiles in single setups. This technology is displacing legacy 2D profiling in automotive powertrain lines.
- 2D Measurement:Conventional shadowgraph projection remains cost-optimized for routine shop-floor verification where tolerance bands permit simpler architectures.
- Image Processing:Machine vision algorithms enable automated pass-fail decisions without operator interpretation, opening high-volume automotive fastener inspection.
- Laser Measurement:Non-contact scanning complements optical projection for soft or reflective surfaces in medical device polymer component verification.
2D systems retain the widest installed base; 3D platforms are gaining share fastest.
Application:
Customer type segmentation separates compliance-driven documentation requirements from exploratory engineering workflows.
- Quality Control:Production-line verification absorbs the majority of unit volume across automotive and electronics manufacturing corridors.
- Research & Development:Custom configuration requirements generate disproportionate margin pools due to non-standard optical path designs and specialized software integration.
- Product Inspection:Incoming material verification and outgoing shipment certification in pharmaceutical subcontracting require FDA-documented protocols.
- Tool Making:Cutting tool and die verification in German and Japanese mold shops maintains steady replacement demand.
Quality control dominates unit shipments; research and development commands the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision equipment exports flow primarily into American aerospace subcontracting networks and Japanese calibration laboratories, establishing a trade corridor that shapes regional procurement specifications.
United States
FAA airworthiness directives mandate documented dimensional verification for turbine blade suppliers. FDA process validation requirements drive pharmaceutical subcontractors toward traceable digital measurement records. Aerospace Tier-1 suppliers in Connecticut and Arizona deploy sub-micron resolution systems for root profile verification.
Germany
ISO 10360 tolerance compression accelerates recertification cycles in Baden-Württemberg machine shops. KBA automotive standards push powertrain manufacturers toward automated inspection cells. Stuttgart-based suppliers operate just-in-time verification stations requiring four-hour service commitments.
Japan
METI precision manufacturing standards elevate domestic comparator specifications for semiconductor packaging processes. PMDA quality system regulations extend documentation requirements to medical device subcontractors. Nagoya-area automotive clusters phase out manual-stage configurations for motorized platforms.
China
SAMR harmonization of GB standards with ISO 10360 eliminates technical barriers for European and Japanese equipment imports. MIIT industrial upgrading programs support domestic manufacturers certifying platforms for export. Yangtze River Delta precision machining corridors absorb volume for routine dimensional verification.
South Korea
MFDS medical device regulations align with ISO 13485 for contract manufacturers serving export markets. Back-end lithography-adjacent quality stations in semiconductor packaging deploy sub-micron resolution systems. Busan-Ulsan manufacturing belts concentrate demand for high-throughput automated inspection.
Global Optical Comparator Market Competitive Landscape
Listed leaders compete with private specialists across calibration service bundling and software retrofit capabilities. The vendor base separates into three tiers: multinational metrology conglomerates with full-service networks, mid-cap equipment specialists with regional calibration depth, and domestic fabricators competing on price-standardization. Two dominant competitive moves are reshaping positioning: strategic partnerships bundling hardware with third-party accreditation services, and geographic expansion through free-trade zone assembly to bypass import certification friction.
Among Japanese precision equipment manufacturers, Mitutoyo Corporation and Nikon Metrology exemplify the heritage-driven archetype, leveraging decades of metrology credibility to sustain dominance in calibration laboratory networks. Starrett, as an American limited company, occupies a position within the vocational training and job shop distribution tier, anchoring its presence through deep penetration of technical education channels. Keyence Corporation represents the factory automation convergence archetype, bridging optical inspection with broader sensor and control system portfolios.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Starrett |
| Nikon Metrology |
| Quality Vision International Inc. |
| Keyence Corporation |
| J&L Metrology, Inc. |
| S-T Industries Inc. |
| Hexagon Manufacturing Intelligence |
| Gagemaker |
| Others |
Supply & Pricing Matrix
CMOS sensor fabrication scale in Japan and South Korea establishes cost floors that cascade through comparator OEM pricing strategies, concentrating margin pressure on mid-tier equipment vendors lacking captive imager supply.
Pricing Analysis
Digital optical comparator platforms command substantial premiums over manual shadowgraph configurations, while emerging 3D telecentric systems price at the apex tier. Pricing stratifies across premium, standard, and economy tiers based on resolution specification and bundled calibration service depth. Cost compression in economy-tier manual units is intensifying because Chinese domestic manufacturers exploit GB standard harmonization to undercut import pricing. Job shops and vocational training channels exhibit highest price sensitivity; semiconductor fabs and aerospace Tier-1 suppliers demonstrate lowest.
Supply Chain Analysis
Japan and South Korea anchor high-resolution CMOS imager fabrication for digital comparator platforms. German precision optics suppliers and Chinese machined-base fabricators feed assembly operations across multiple OEMs. Tariff exposure concentrates in trans-Pacific component flows for American and European equipment vendors. Distribution runs through authorized metrology distributors with captive calibration laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical comparator architecture is transitioning toward software-defined measurement platforms where interoperability with MES and QMS ecosystems determines vendor viability, compressing standalone hardware margins.
For Market Incumbents: Secure calibration service bundling contracts in American Midwest and German Baden-Württemberg powertrain corridors to lock out third-party metrology laboratories. Acquire AI-assisted edge detection software capabilities before machine vision specialists displace traditional optical projection in automotive fastener inspection. Vertical integration into CMOS sensor supply buffers allocation risk during fab capacity constraints.
For New Entrants and Emerging Players: Calibration-as-a-service unbundling in United States job shop segments exposes white-space where incumbents tether equipment purchase to mandatory recertification contracts. Target Indian medical device contract manufacturers facing CDSCO regulatory harmonization with ISO 13485 documentation requirements. Pursue OEM partnerships with domestic Chinese fabricators leveraging SAMR standard convergence for Southeast Asian export certification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-retrofit specialists over legacy hardware manufacturers as 3D measurement displaces 2D profiling. Acquisition candidates with telecentric lens arrays and sub-pixel algorithm portfolios outlast conventional shadowgraph vendors. Watch semiconductor packaging capital expenditure cycles as inflection signal for sub-micron resolution demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Retrofit Program Launch | Extends installed base life against 3D CMM substitution in German automotive corridors. |
| Calibration-as-a-Service Unbundling | Lowers capital barriers for American job shop entry and captures recurring revenue streams. |
| AI-Assisted Edge Detection Integration | Automates pass-fail decisions for high-volume automotive fastener inspection lines. |
| Free-Trade Zone Assembly Localization | Bypasses SAMR import certification friction for European and Japanese equipment vendors. |
| Telecentric Lens Array Development | Captures semiconductor wafer inspection demand in South Korean back-end packaging facilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with quality control managers at aerospace Tier-1 suppliers, biomedical engineers at medical device OEMs, metrology laboratory directors, and precision machining shop owners. Secondary validation drew from FDA 483 inspection observations, SAMR GB standard harmonization documents, METI precision manufacturing guidelines, and semiconductor equipment capital expenditure disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the analysis window, forecasts modeled product type segmentation across digital, automated, manual, and portable configurations; end-use verticals spanning aerospace, automotive, manufacturing, and electronics; and technology dimensions including 2D, 3D, image processing, and laser measurement. CAGRs derived from regression analysis against industrial production indices and precision equipment import trade flows. Industry-specific inputs incorporated ISO 10360 recertification cycle acceleration and FDA process validation documentation mandates.
Underlying assumptions cover sustained semiconductor capital expenditure, stable CMOS sensor supply allocation, and continued ISO standard harmonization, with deviation risk concentrated in tariff regime shifts and dimensional metrology technician scarcity. Recalibration cycles align with material shifts in regulatory validation requirements and 3D measurement technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Nuclear Power Cables Market
Others
Allogeneic Human Chondrocyte Market
Others
Germany Smart Home Market
Others
Software Synthesizers Market
Others
North America Printed Signage Market
Others
Underwater Light Market
Others
Stichtite Market
Others
Heavy Duty Vacuum Bottle Market
Others
Medium-Voltage Switchgear Market
Others
US Luxury Travel Market
Others
Europe Electric Forklift Market
Others
Lined Tank Market
Others
Global Fertility Tracking Apps Market
Others
Wearable AI Market
Others
Smart Home Water Softener Market
Others
Global Cryogenic Tanks Market