
 Rotary Evaporators Market | 2026-2036
Rotary Evaporators Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Evaporators Market Analytics
Academic research laboratories are redrawing demand patterns for rotary evaporators as pharmaceutical quality control budgets tighten. Heidolph Instruments GmbH & Co. KG leverages its German manufacturing base to anchor supply across European research institutes. IKA Works GmbH & Co. KG differentiates through control interface integration that appeals to automation-focused buyers. Buchi Labortechnik AG dominates the premium manual segment where legacy protocols persist in established chemistry departments.
A rotary evaporator is a laboratory device that applies controlled heat, vacuum pressure, and rotational motion to evaporate solvents from samples at reduced boiling points, typically operating at rotation speeds between 20 and 280 rpm. The apparatus consists of a heated water or oil bath, a rotating evaporation flask, a condenser with active cooling, and a vacuum system with pressure regulation, serving primarily to concentrate compounds, remove low-boiling solvents, and reclaim expensive organic materials. Automatic and digital product types command expanding interest as laboratories seek reproducible protocols and remote monitoring capabilities. Solvent removal and distillation applications generate the bulk of installed base replacement demand, while concentration workflows in food and beverage testing represent a faster-growing use case where margin pools are deepening.
FDA oversight of pharmaceutical manufacturing equipment validation shapes product specifications for rotary evaporators deployed in GMP environments, while REACH and OSHA guidelines constrain solvent emission profiles and operator exposure limits across laboratory settings. ISO 9001 and ISO 13485 certifications increasingly filter vendor eligibility in institutional procurement frameworks, particularly for academic medical centers with dual research and clinical mandates. Stakeholders must weigh automation investment against protocol flexibility as regulatory stringency diverges between research-grade and production-grade operating environments.
Market Dynamics
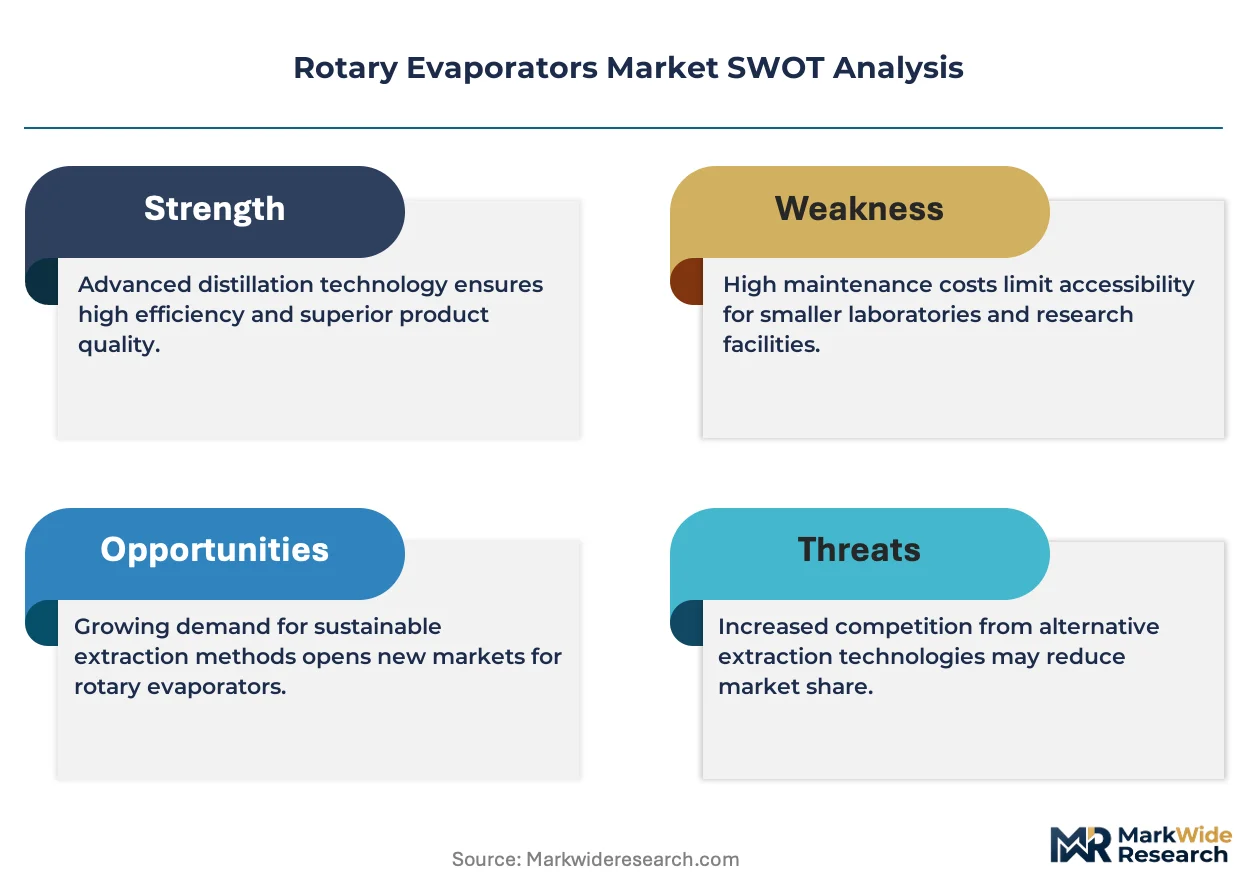
The rotary evaporators market is experiencing a structural compression between automation mandates and legacy protocol persistence, with REACH compliance in Europe accelerating equipment replacement cycles while academic budgets constrain premium unit adoption.
Growth Catalysts
- REACH solvent handling mandates:European laboratories face tightened emission controls that obsolete non-compliant units, forcing systematic replacement of aging evaporator fleets across research institutes in Germany and France.
- Pharmaceutical GMP validation requirements:FDA oversight of manufacturing equipment specifications expands addressable demand for validated rotary evaporators in quality control laboratories serving contract manufacturing organizations.
- Food safety testing protocols:Concentration workflows in beverage and agricultural testing laboratories generate incremental unit demand as regulatory sampling volumes expand in China and the United States.
Market Restraints
- Stainless steel and borosilicate glass supply concentration:Input cost volatility for evaporation flask materials concentrates in German and Chinese specialty glass manufacturers, compressing margin flexibility for mid-tier equipment vendors.
- Freeze-drying substitution in thermolabile samples:Lyophilization technology captures high-value pharmaceutical applications where rotary evaporation risks compound degradation, limiting premium segment expansion.
- OSHA exposure limit compliance costs:Operator safety certification requirements for solvent handling add implementation friction and extend sales cycles in United States academic procurement.
Strategic Opportunities
- Remote monitoring capability gaps:Integration of IoT-enabled pressure and temperature logging addresses unmet demand in distributed research networks where protocol reproducibility spans multiple laboratory sites.
- India pharmaceutical contract research expansion:CDSCO regulatory harmonization with ICH standards creates qualified demand for GMP-compliant rotary evaporators in Bangalore and Hyderabad manufacturing clusters.
- Green chemistry solvent reclamation incentives:EPA waste reduction frameworks and corporate sustainability targets position solvent recovery applications as a service-expandable revenue stream beyond equipment sales.
Industry Challenges
- Vacuum system integration complexity:Legacy diaphragm pump infrastructure in established chemistry departments creates retrofit friction for automated rotary evaporator upgrades, extending implementation timelines.
- ISO 13485 certification timeline compression:Academic medical centers with dual research-clinical mandates demand accelerated vendor qualification processes that strain smaller equipment manufacturers' quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Evaporators Market |
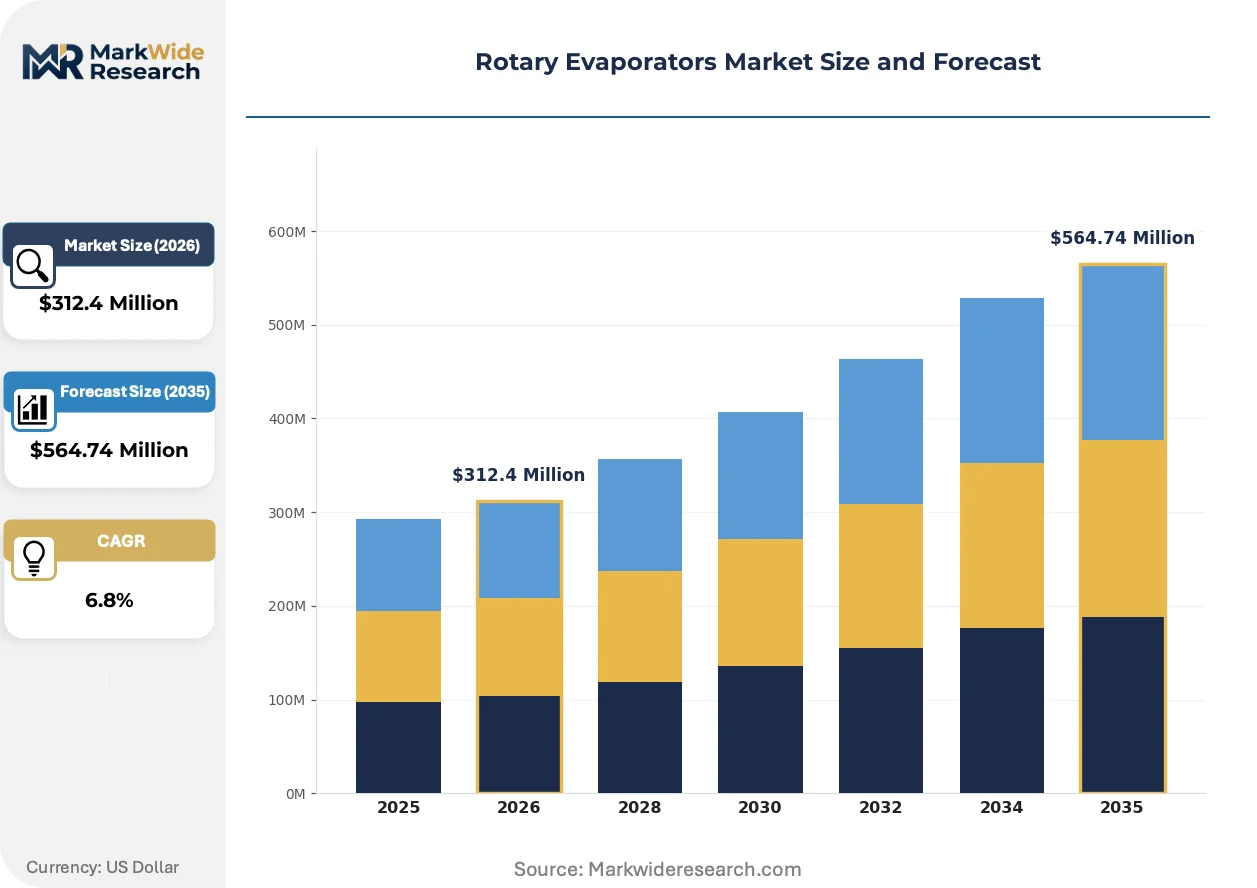
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Digital End User: Pharmaceuticals, Chemicals, Food & Beverage, Academic Research Application: Solvent Removal, Concentration, Distillation, Reclamation Technology: Cooling System, Heating Mantle, Vacuum Technology, Control Interfaces |
| Companies Covered | Buchi Labortechnik AG, Heidolph Instruments GmbH & Co. KG, IKA Works GmbH & Co. KG, Yamato Scientific Co., Ltd., LabTech S.r.l., Steroglass S.r.l., EYELA, Labinco BV, GWSI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Evaporators Market Evolving Landscape
Automation architectures and regulatory digitization are restructuring competitive advantage in laboratory evaporation equipment, compressing differentiation timelines for interface design and data integrity features.
Condenser cooling technology is decomposing traditional water circulation dependencies. Magnetic bearing chillers and closed-loop refrigeration systems reduce facility water consumption and temperature variability. Pharmaceutical quality control laboratories in Germany and Switzerland are adopting these units fastest. The technology is decomposing regional equipment specifications as water-scarce geographies bypass legacy infrastructure requirements.
REACH substance restriction amendments tighten solvent emission profiles across European research installations. The regulation forces replacement of open-bath designs with sealed-system architectures. Academic procurement frameworks in France and the Netherlands now embed compliance pre-qualification. Vendors with established EU service networks capture disproportionate share of institutional upgrade cycles.
Consolidated purchasing through group procurement organizations concentrates buyer power in United States academic and government laboratory segments. Traditional distributor relationships face disintermediation as GPOs negotiate direct manufacturer contracts with standardized service terms. This pattern is most visible in National Institutes of Health-funded research institutes where equipment standardization reduces training and maintenance overhead across multi-site operations.
Rotary Evaporators Market Segmentation
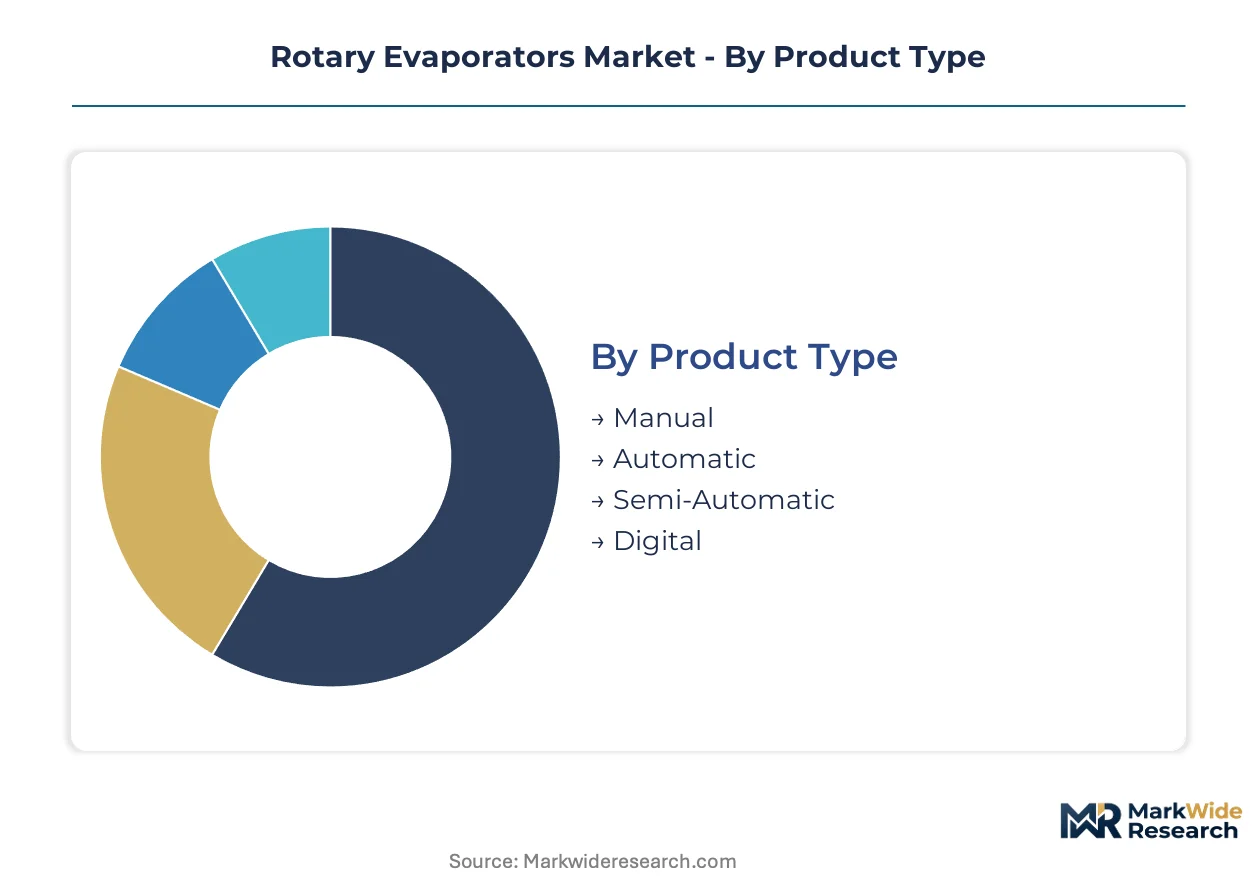
Rotary evaporator procurement patterns diverge sharply across product sophistication tiers and end-use environments. Segmentation reveals where automation investment outpaces legacy replacement, and which regulatory contexts reshape equipment specifications.
Product Type:
Domestic manufacturing in Germany and Switzerland anchors premium automatic unit supply, while manual and semi-automatic production concentrates in Chinese export-oriented facilities serving price-sensitive institutional buyers.
- Manual:Mechanical rotation and manual vacuum adjustment define these entry-level units. Established chemistry departments in France and Italy retain manual protocols where legacy SOPs resist automation migration, though REACH compliance deadlines erode this base.
- Automatic:Programmable pressure ramps and automated lift mechanisms enable unattended operation. Pharmaceutical QC laboratories in Germany and contract manufacturers in India drive specification intensity here, with FDA validation requirements filtering vendor eligibility.
- Semi-Automatic:Hybrid designs retain manual flask handling while automating vacuum control. Academic shared equipment facilities in the United States favor this compromise between throughput and capital constraint.
- Digital:Touchscreen interfaces with data logging satisfy audit trail requirements. Swiss and Dutch research institutes lead adoption where protocol reproducibility spans distributed laboratory networks.
Manual equipment still commands the largest installed base; momentum sits with automatic configurations as GMP validation requirements harden.
End User:
Capital deployment intensity separates pharmaceutical buyers pursuing validation-grade equipment from academic segments prioritizing multi-user durability.
- Pharmaceuticals:GMP-compliant rotary evaporators with IQ/OQ/PQ documentation support API manufacturing and quality control. CDSCO-harmonized facilities in Bangalore and Hyderabad represent emerging demand concentration.
- Chemicals:Solvent reclamation applications in specialty chemical production favor corrosion-resistant glassware configurations. German and Belgian industrial research clusters specify these units for process development scale-up.
- Food & Beverage:Concentration workflows for pesticide residue and flavor compound analysis expand fastest. Testing laboratories in California and São Paulo drive volume as regulatory sampling mandates widen.
- Academic Research:Shared core facilities balance protocol flexibility against training overhead. NIH-funded institutes in Maryland and Massachusetts concentrate procurement through group purchasing organizations.
Pharmaceutical end users contribute the highest unit margins; food safety testing climbs fastest on regulatory sampling expansion.
Application:
Process throughput requirements and solvent recovery economics determine equipment specification intensity across use cases.
- Solvent Removal:The foundational application for compound isolation and crude purification. Synthetic chemistry groups in German universities and Chinese pharmaceutical institutes generate replacement demand as solvent portfolios shift under REACH restrictions.
- Concentration:Gentle reduction of sample volume for analytical preparation. Beverage quality laboratories in Italy and agricultural testing stations in the United States adopt dedicated units for high-throughput screening protocols.
- Distillation:Fractional separation of close-boiling mixtures demands precise vacuum control. Swiss fine chemical manufacturers specify premium configurations for chiral compound purification.
- Reclamation:Recovery of expensive organic solvents for reuse aligns with corporate sustainability targets and EPA waste reduction frameworks. Contract research organizations in India and the United States monetize this as a service layer.
Solvent removal retains the broadest installed base; reclamation applications gain share fastest on green chemistry incentives.
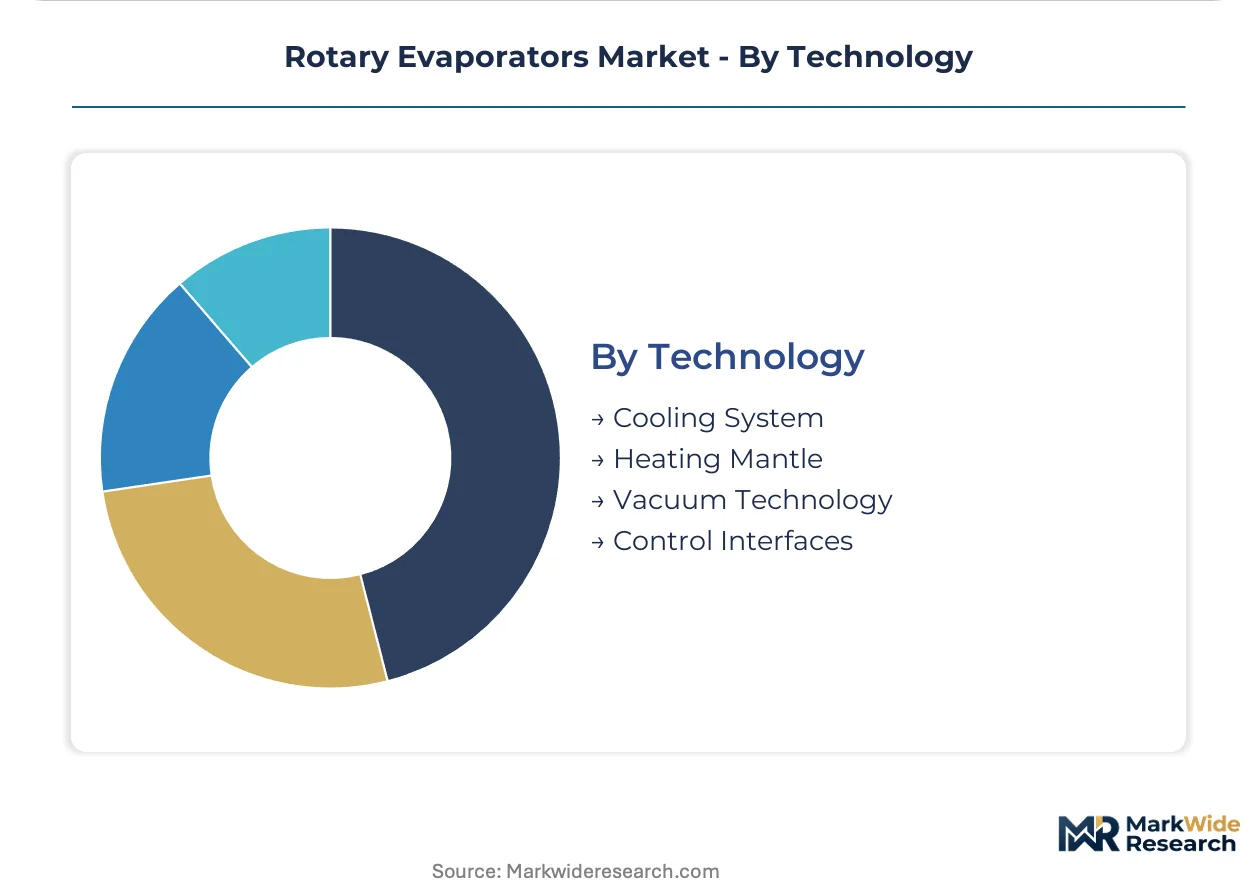
Technology:
Component integration complexity separates premium vendors with captive subsystem development from assembly-oriented competitors sourcing chillers and pumps externally.
- Cooling System:Magnetic bearing chillers and closed-loop refrigeration reduce water consumption. Pharmaceutical facilities in Switzerland and water-scarce regions in Spain specify these to bypass legacy cooling infrastructure.
- Heating Mantle:Oil bath alternatives with precise temperature uniformity serve thermolabile samples. Academic laboratories in Japan favor these for natural product isolation workflows.
- Vacuum Technology:Diaphragm pump integration with electronic pressure control enables programmable solvent-specific protocols. German equipment vendors anchor supply here through in-house pump manufacturing.
- Control Interfaces:IoT-enabled pressure and temperature logging addresses distributed research network requirements. Dutch and Danish institutional buyers prioritize these for multi-site protocol standardization.
Vacuum technology holds the largest value contribution; control interfaces expand most quickly on remote monitoring demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality control laboratories in Germany, academic research institutes in the United States, and contract manufacturing clusters in India concentrate procurement of automated rotary evaporator systems. These buyer archetypes drive specification intensity across three distinct regulatory environments.
Germany
REACH solvent handling mandates accelerate equipment replacement cycles across academic and industrial research facilities. ECHA substance restriction amendments force systematic upgrades of open-bath evaporator designs. Bavarian chemistry departments and Baden-Württemberg pharmaceutical manufacturers anchor European demand for sealed-system architectures with integrated vacuum control.
United States
NIH-funded research institutes consolidate procurement through group purchasing organizations, standardizing equipment across multi-site operations. FDA equipment validation requirements filter vendor eligibility for pharmaceutical quality control applications. Maryland and Massachusetts academic medical centers with dual research-clinical mandates drive specification intensity for ISO 13485-certified units.
China
NMPA regulatory harmonization with ICH standards expands qualified demand for GMP-compliant rotary evaporators in API manufacturing. Dual carbon goals incentivize solvent reclamation applications in corporate sustainability frameworks. Shanghai and Suzhou pharmaceutical manufacturing clusters specify automated units with remote monitoring capabilities for distributed quality control networks.
India
CDSCO regulatory alignment with ICH standards creates qualified demand for validated equipment in contract research and manufacturing organizations. PLI scheme incentives for pharmaceutical manufacturing deepen capital deployment intensity. Bangalore and Hyderabad manufacturing clusters drive specification requirements for IQ/OQ/PQ documentation in export-oriented facilities.
Switzerland
Swissmedic oversight of pharmaceutical manufacturing equipment shapes premium-tier specifications for validated rotary evaporators. Water scarcity in Alpine regions accelerates adoption of closed-loop refrigeration systems bypassing legacy cooling infrastructure. Basel and Zurich pharmaceutical quality control laboratories anchor demand for magnetic bearing chiller technology with precise temperature uniformity.
Rotary Evaporators Market Competitive Landscape
Player mix skews toward European precision engineering specialists with captive vacuum technology manufacturing and Asian export-oriented fabricators serving price-sensitive institutional segments. Market structure concentrates around three strategic archetypes: German-Swiss premium vendors with integrated subsystem development, Italian-Japanese mid-tier specialists emphasizing control interface differentiation, and Chinese scale producers leveraging glassware supply proximity. Competitive moves center on automation architecture licensing and service network expansion into pharmaceutical manufacturing clusters.
Within the European premium tier, Buchi Labortechnik AG and Heidolph Instruments GmbH & Co. KG occupy positions anchored by German manufacturing bases and established EU service networks. IKA Works GmbH & Co. KG exemplifies the control interface specialization archetype, representing vendors that differentiate through automation-focused buyer appeal. These GmbH-structured entities collectively illustrate how European vendor consolidation around REACH compliance capabilities captures disproportionate share of institutional upgrade cycles.
| Leading Market Players |
|---|
| Buchi Labortechnik AG |
| Heidolph Instruments GmbH & Co. KG |
| IKA Works GmbH & Co. KG |
| Yamato Scientific Co., Ltd. |
| LabTech S.r.l. |
| Steroglass S.r.l. |
| EYELA |
| Labinco BV |
| GWSI |
| Others |
Value Network & Pricing Analysis
Magnetic bearing chiller substitution for water-circulation cooling simultaneously redistributes manufacturing gravity toward Swiss and German precision engineering clusters while compressing price premiums on legacy open-bath configurations. This input transition concentrates value capture among vendors with captive refrigeration subsystem development, fragmenting pricing power for assembly-oriented competitors dependent on outsourced chiller procurement.
Pricing Analysis
Automatic-to-manual pricing gaps widen substantially across current-generation sealed-system architectures, prior-generation open-bath units facing REACH obsolescence, and emerging IoT-enabled configurations with remote monitoring capability. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and vacuum control precision. Cost compression in mid-tier semi-automatic equipment is intensifying because Chinese export-oriented fabricators leverage borosilicate glass supply proximity. Academic shared equipment facilities in the United States exhibit highest price sensitivity; pharmaceutical QC laboratories in Germany and Switzerland show lowest sensitivity due to GMP validation requirements.
Supply Chain Analysis
Inventory lead times for vacuum diaphragm pumps and magnetic bearing chillers extend procurement cycles for automated rotary evaporator configurations, particularly where German vendors maintain in-house manufacturing. Supply concentrates in Germany, Switzerland, and China for precision vacuum technology, closed-loop refrigeration systems, and borosilicate glassware respectively. Raw material dependencies rest on specialty borosilicate glass, corrosion-resistant stainless steel alloys, and rare-earth magnetic components for bearing systems. Single-source vulnerability concentrates in German diaphragm pump manufacturers serving premium automatic segments. Distribution runs through academic group purchasing organizations in the United States and direct manufacturer contracts with European research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH solvent handling mandates and FDA GMP validation requirements are accelerating equipment replacement cycles, creating a high-growth disruption window where automation-capable vendors capture disproportionate share of institutional upgrade demand.
For Market Incumbents: Shield premium positioning by accelerating ISO 13485 certification timelines for academic medical center procurement and deepening captive vacuum technology manufacturing in German facilities. Freeze-drying substitution in thermolabile pharmaceutical applications threatens margin expansion; counter by integrating closed-loop refrigeration as standard rather than optional configuration. Backward integration into magnetic bearing chiller production secures supply continuity against specialty component lead time volatility. For New Entrants and Emerging Players: Differentiate on IoT-enabled remote monitoring capability where established vendors lag in distributed research network applications. Target food and beverage testing laboratories in California and São Paulo as the most penetrable segment, where regulatory sampling expansion outpaces incumbent service network coverage. Pursue direct contracting with group purchasing organizations as the primary go-to-market angle, bypassing traditional distributor relationships that concentrate buyer power against fragmented vendor bases. For Investors and Strategic Acquirers: The market sits at a regulatory-driven replacement phase that favors vertically integrated precision engineering specialists with captive subsystem development and established EU service networks. Long-term viability over the next decade hinges on automation architecture licensing revenue streams and solvent reclamation service layer monetization. Acquisition target archetype: mid-tier Italian or Japanese control interface specialists with FDA pre-submission pathways. The signal to watch is CDSCO regulatory harmonization progress in Indian pharmaceutical manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Architecture Licensing | Enables revenue capture from distributed research networks requiring protocol standardization across multiple laboratory sites. |
| ISO 13485 Certification Acceleration | Qualifies vendors for academic medical center procurement frameworks with dual research-clinical mandates in Maryland and Massachusetts. |
| Closed-Loop Refrigeration Integration | Addresses water scarcity constraints in Alpine regions and pharmaceutical facilities in Spain bypassing legacy cooling infrastructure. |
| Solvent Reclamation Service Layer | Monetizes EPA waste reduction frameworks and corporate sustainability targets beyond equipment transactional revenue. |
| Group Purchasing Organization Direct Contracting | Reduces disintermediation risk from NIH-funded institutes consolidating procurement through standardized multi-site equipment terms. |
Research Methodology
Operator-level perspectives from laboratory managers, pharmaceutical QC directors, academic procurement officers, and aftermarket service technicians anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through ECHA regulatory filings, FDA equipment validation guidance documents, SEC 10-K disclosures from listed laboratory equipment vendors, and customs trade data for borosilicate glass and vacuum pump imports. Bottom-up unit demand estimates across product type, end user, and application segments triangulated against top-down market size assessments derived from procurement database analysis.
Sensitivity analysis around REACH compliance timeline assumptions and pharmaceutical GMP validation adoption rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product sophistication tier, end-use environment regulatory context, application workflow type, and geographic manufacturing cluster. CAGRs were derived from regression analysis of replacement cycle dynamics and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated solvent portfolio shift patterns under ECHA substance restrictions and CDSCO-ICH harmonization progress in Indian contract manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or accelerated FDA validation requirement expansion would require recalibration. Forecasts reflect documented assumptions regarding academic budget trajectories and specialty glass supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Fire Sprinklers Market
Others
Connected Living Room Market
Others
Europe Street Lighting Market
Others
5G Enabled Healthcare Services Market
Others
Semiconductor Gas Filters Market
Others
Vacuum Evaporators Market
Others
Air Purification Systems Market
Others
Corn Fiber Market
Others
Global Video Processing Platform Market
Others
Programmatic Display Market
Others
Global Transparent Plastics Market
Others
Global Thermally Conductive Grease Market
Others
Linseed Oil Market
Others
Digital Education Projector Market
Others
Propanil Market
Others
Molecular Spectroscopy Market