
 Global Active Speaker Market | 2026-2036
Global Active Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active Speaker Market Analysis
Chinese OEM assembly capacity is pivoting toward higher-margin active speaker modules with integrated DSP and amplification. Bose Corporation leverages its captive retail network and pro-audio service infrastructure to sustain premium positioning across North American installed-sound projects. Sony Corporation anchors its competitive stance through vertical control over transducer magnetics and wireless codec licensing. Yamaha Corporation dominates the Japan market for compact active monitors while extending its Dante-networked loudspeaker line into European live-sound rental channels.
An active speaker integrates power amplification, electronic crossover networks, and sometimes digital signal processing within the same enclosure as the driver assembly, eliminating the need for external amplifiers and enabling precise factory-tuned frequency response through onboard parametric EQ and limiter circuits. Smart speakers command the fastest expansion trajectory as voice-assistant integration and room-correction algorithms migrate from consumer living rooms into commercial hospitality and corporate meeting spaces. The mid-range product tier captures the deepest volume pool, though high-end segments retain superior margin density in professional monitoring and premium residential installations where flat frequency response and low distortion specifications justify price premiums.
The EU's Ecodesign Directive and REACH chemical compliance framework constrain material selection for enclosures and driver adhesives, while FCC emissions certification in the United States governs wireless transmission protocols for Bluetooth and Wi-Fi connectivity variants. China's GB standards for audio equipment safety and electromagnetic compatibility create parallel compliance obligations for manufacturers sourcing transducers from Shenzhen and Dongguan supply bases. Stakeholders must monitor how impending updates to energy-efficiency labeling regimes and right-to-repair mandates reshape product architecture decisions and aftermarket service economics.
Market Dynamics
The EU's Ecodesign Directive is compressing standby power limits and mandating material recovery rates, forcing manufacturers to redesign power supplies and enclosure assemblies across all price tiers.
Growth Catalysts
- Live event infrastructure expansion:Outdoor venues in Germany and touring circuits across North America are deploying Dante-networked active speaker arrays to reduce cabling complexity and accelerate load-in times.
- REACH chemical compliance:The EU's framework on substance restrictions is accelerating substitution of solvent-based adhesives in driver assembly, pushing suppliers toward UV-cured alternatives with faster production cycles.
- Voice-assistant integration:Hospitality and corporate meeting spaces are adopting smart active speakers with room-correction algorithms, extending consumer voice platforms into commercial installed-sound applications.
Market Restraints
- Neodymium magnet supply concentration:Rare-earth processing capacity clusters in China's Jiangxi and Inner Mongolia provinces, creating single-source vulnerability for high-performance transducer manufacturers.
- Class-D amplifier input cost volatility:Silicon carbide MOSFET pricing fluctuates with automotive sector demand, squeezing margins on mid-range active monitor production.
- FCC emissions certification friction:Wireless protocol testing for Bluetooth and Wi-Fi variants adds six-to-nine month timeline extensions for products targeting North American distribution.
Strategic Opportunities
- India commercial real estate audio:Bengaluru and Hyderabad's technology campus construction is generating demand for networked active ceiling speakers with centralized DSP control.
- Right-to-repair mandate preparation:The EU's forthcoming serviceability requirements create first-mover advantage for modular amplifier architectures with field-replaceable DSP modules.
- Spatial audio convergence:Object-based mixing formats are merging with wave-field synthesis hardware, opening specification opportunities in immersive cinema and themed entertainment installations.
Industry Challenges
- Acoustic measurement technician scarcity:Factory-tuned active speaker production requires skilled personnel for anechoic chamber calibration, with training pipelines lagging demand in Shenzhen and Dongguan manufacturing clusters.
- Legacy analog infrastructure integration:Installed-sound contractors face complexity bridging Dante/AES67 networked active speakers with existing 70V distributed systems in retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active Speaker Market |
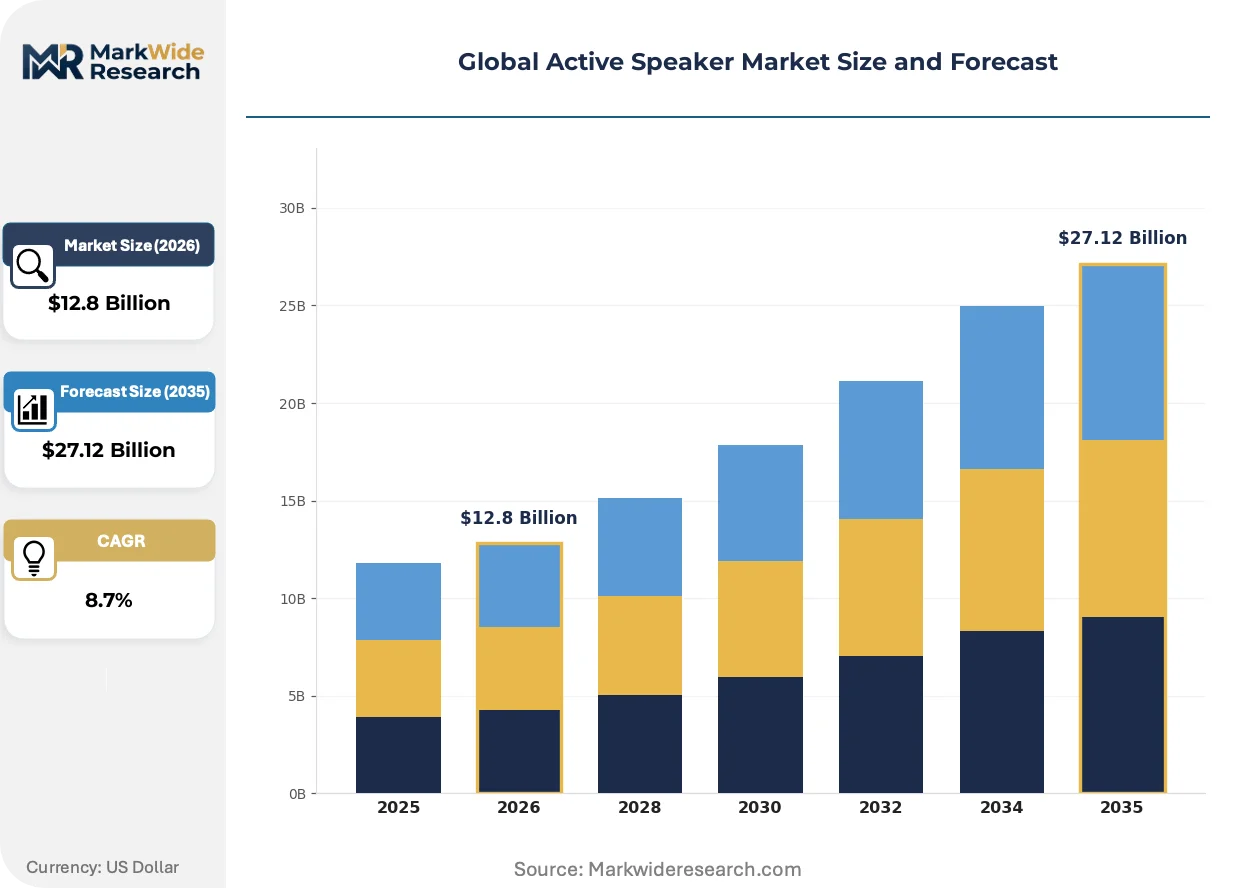
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Speakers, Smart Speakers, Wireless Speakers, Home Theater Systems End User: Residential, Commercial, Education, Automotive Connectivity: Bluetooth, Wi-Fi, USB, AUX Market Segment: High-End, Mid-Range, Budget, Others |
| Companies Covered | Bang & Olufsen A/S, Pioneer Corporation, Sony Corporation, Klipsch Group, Inc., Edifier International Limited, Bose Corporation, LG Electronics Inc., QSC Audio Products, LLC, Yamaha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active Speaker Market Emerging Trajectories
Beam-steering line arrays and machine-learning room correction are compressing the performance gap between installed and portable systems, reshaping how venues specify coverage and amplification.
Gallium nitride (GaN) power semiconductors are overtaking silicon MOSFETs in Class-D amplifier stages, enabling higher switching frequencies with reduced thermal mass. Live-sound rental companies in Germany and the United Kingdom are specifying GaN-based active subwoofers to cut weight and power draw on touring trucks. This transition is compressing the physical footprint of amplifier modules while extending peak output duration before thermal limiting.
The EU's Ecodesign Directive standby power regulations are tightening to sub-500 milliwatt thresholds for networked audio equipment, forcing redesign of always-on Wi-Fi and Bluetooth receiver circuits. Manufacturers serving European broadcast and installed-sound markets are implementing hardware sleep states and wake-on-LAN architectures to maintain connectivity compliance. Germany's professional audio manufacturing clusters in Berlin and Hamburg are piloting firmware-managed power sequencing to meet verification protocols.
Corporate AV procurement teams are consolidating vendor relationships around single-platform Dante ecosystems, displacing mixed-protocol installations. This concentration is elevating specification weight for networked active speakers with native AES67 compatibility and unified control software. The shift is most visible in North American technology sector headquarters, where facilities teams prioritize remote monitoring and automated fault detection over discrete component flexibility.
Global Active Speaker Market Segmentation
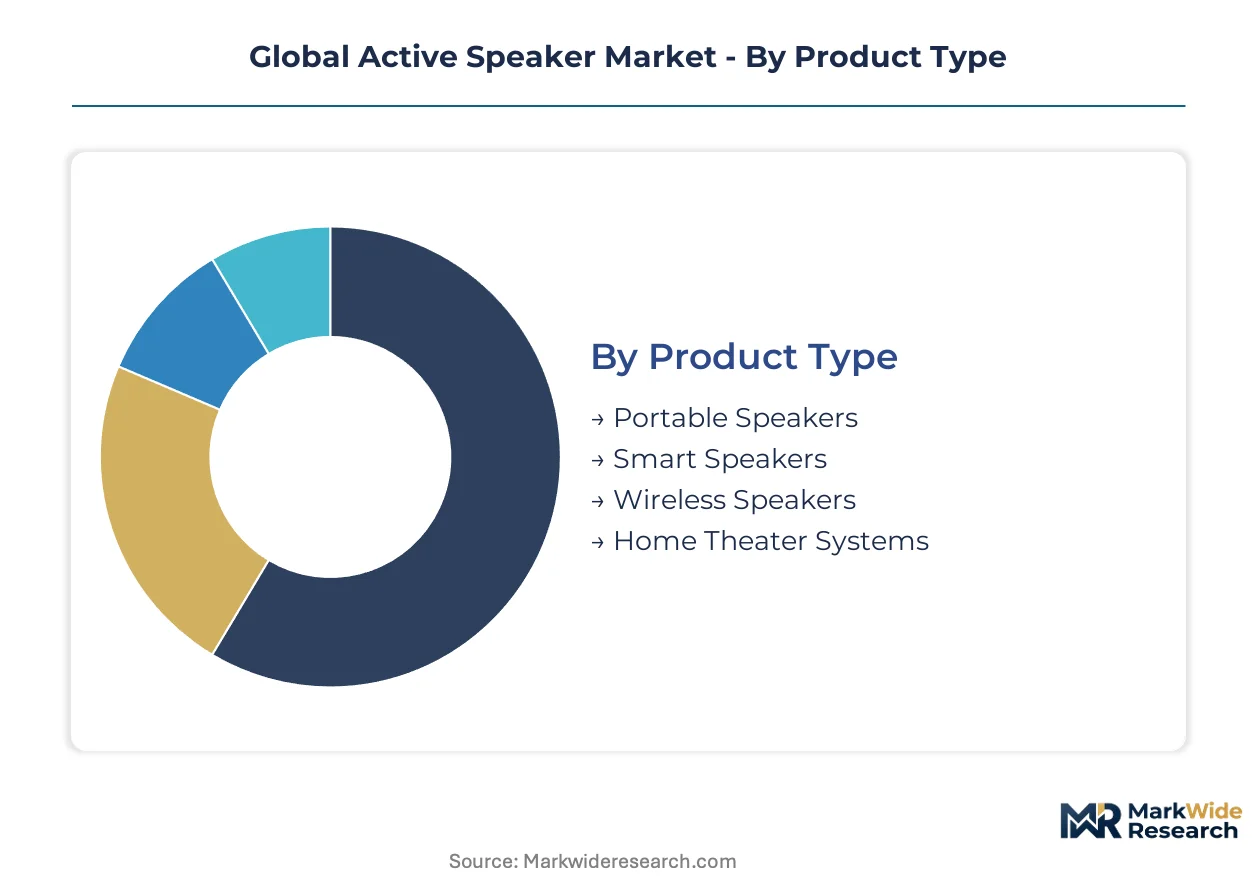
Active speaker architecture varies sharply across deployment contexts, with amplification topology, DSP integration depth, and enclosure materials calibrated to specific acoustic environments and price thresholds. Manufacturers configure transducer arrays, crossover networks, and wireless protocol stacks differently for touring rigs versus ceiling-mounted corporate installations.
Product Type:
Driver configuration and amplification topology distinguish performance envelopes across portable, installed, and intelligent speaker categories.
- Portable Speakers:Battery-powered Class-D amplification with passive radiator bass extension dominates this segment. Demand clusters in outdoor event production across Germany and touring infrastructure throughout North America, where rapid load-in protocols favor self-contained systems.
- Smart Speakers:Far-field microphone arrays and onboard voice-assistant processing require dedicated compute modules alongside amplification stages. Hospitality procurement teams in corporate campuses and hotel chains are specifying these for meeting spaces and guest rooms, extending consumer voice platforms into commercial environments.
- Wireless Speakers:Bluetooth and Wi-Fi receiver circuits integrate with single-point stereo drivers or true wireless stereo pairing configurations. Residential retrofits and secondary room audio drive volume.
- Home Theater Systems:Multi-channel active subwoofers and satellite configurations with wireless rear-channel connectivity. Premium residential installations in Japan and South Korea specify these for dedicated media rooms.
Mature deployment sits with Wireless Speakers. Newer deployment is concentrated in Smart Speakers.
End User:
Acoustic performance requirements and procurement authority structures diverge sharply between consumer, institutional, and mobility-integrated applications.
- Residential:Living room, bedroom, and outdoor patio deployments prioritize aesthetic integration and streaming service compatibility. Multi-room audio platforms are displacing discrete component systems in North American and Western European households.
- Commercial:Corporate AV teams specify Dante-networked active ceiling speakers with centralized DSP control for conference rooms and open-plan offices. Technology campus construction in Bengaluru and Hyderabad is generating concentrated demand for networked infrastructure.
- Education:K-12 and university installations require durability-rated enclosures and simplified control interfaces for non-technical staff. Lecture hall retrofit projects in the United States and United Kingdom specify active column arrays with beam-steering capabilities.
- Automotive:OEM integration demands compact amplifier modules with automotive-grade temperature tolerance and CAN bus connectivity. Electric vehicle platforms in China and Germany are specifying active door-mounted speakers with cabin-specific EQ tuning.
Procurement sophistication peaks in Commercial, where IT-AV convergence drives networked platform consolidation. Education represents the most price-sensitive volume pool.
Connectivity:
Wireless protocol selection determines latency profiles, multi-device pairing capacity, and regulatory certification obligations across target markets.
- Bluetooth:Low-complexity pairing dominates portable and entry-level residential applications. The standard's SBC and AAC codec implementations face specification pressure from aptX Adaptive and LC3 alternatives in premium tiers.
- Wi-Fi:Higher bandwidth enables lossless streaming and multi-room synchronization across active speaker networks. Whole-home audio platforms and commercial installed-sound deployments specify Wi-Fi for its range and infrastructure reuse.
- USB:Direct digital audio input with bus-powered amplification for desktop monitor and content creator applications. Podcast production and home studio setups in the United States and United Kingdom specify USB-C connectivity with integrated ADC stages.
- AUX:Analog line-level input persists in legacy integration scenarios and professional audio workflows. DJ equipment and analog mixing console connectivity maintain residual demand.
Bluetooth commands the deepest installed base. Wi-Fi is climbing the fastest as streaming service bitrate tiers expand and mesh networking improves whole-home reliability.
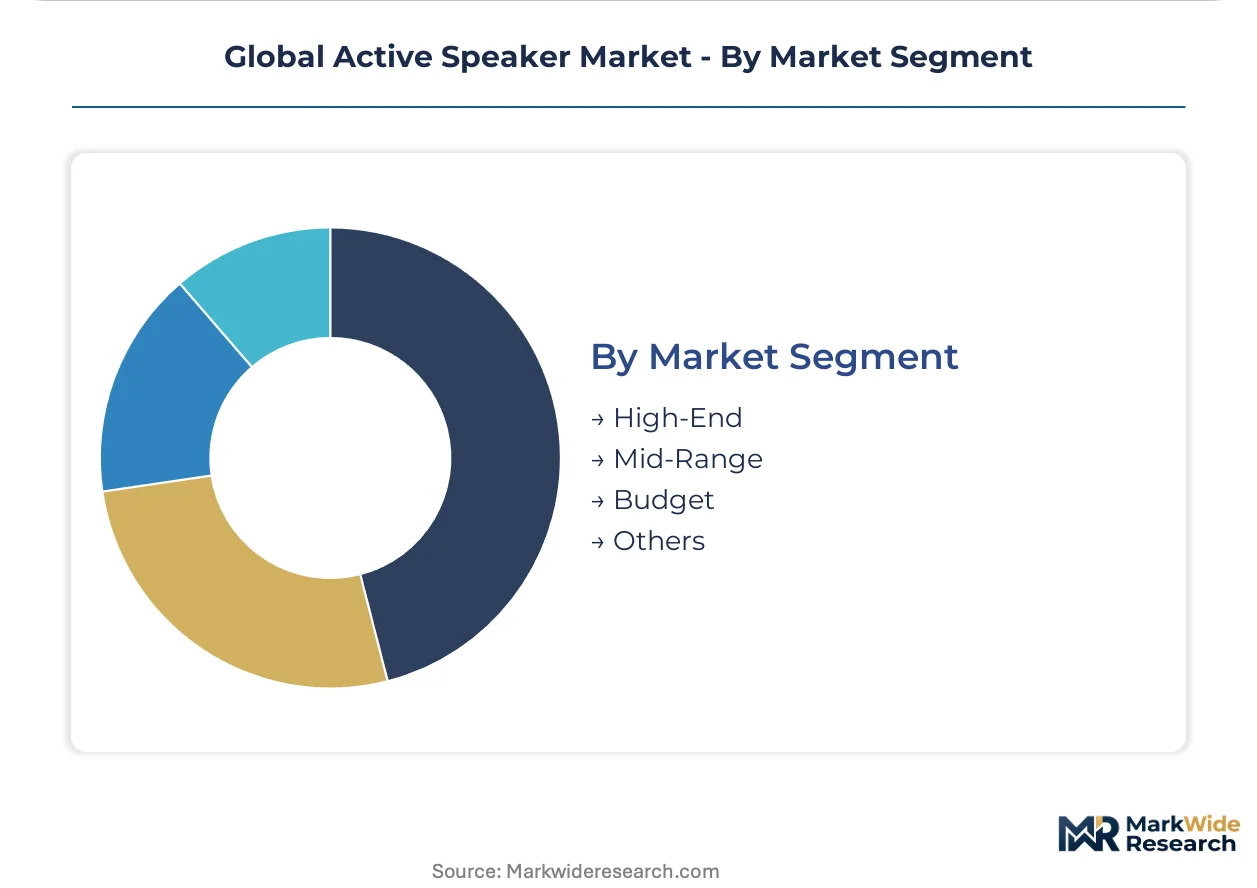
Market Segment:
Price tiering correlates with transducer material quality, amplifier topology sophistication, and factory calibration rigor.
- High-End:Beryllium or diamond-coated tweeters, gallium nitride Class-D amplification, and individual anechoic chamber calibration certificates. Professional monitoring studios and premium residential installations in Japan, Germany, and the United States specify these for flat frequency response and extended dynamic range.
- Mid-Range:Polypropylene or aluminum cone woofers with silicon MOSFET amplification and batch-matched crossover networks. This tier captures the deepest volume pool across residential and light commercial applications.
- Budget:Paper cone drivers with basic Class-AB or entry Class-D amplification, minimal DSP, and plastic enclosure construction. Emerging market volume and promotional retail channels concentrate here.
- Others:Specialized configurations including weatherized outdoor models, explosion-rated industrial speakers, and hearing-assist compliance systems for accessibility mandates.
Margin density concentrates in High-End, where transducer magnetics and calibration labor justify price premiums. Volume leadership belongs to Mid-Range, where manufacturing scale and component standardization optimize unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth processing capacity in China's Jiangxi and Inner Mongolia provinces anchors transducer magnetics supply for high-performance driver assemblies worldwide.
United States
Technology sector headquarters in Seattle and Austin drive Dante-networked ceiling speaker procurement for open-plan offices and conference facilities. FCC emissions certification governs Bluetooth and Wi-Fi protocol testing, adding six-to-nine month timelines for wireless-enabled products. Live-sound rental operators in Nashville and Los Angeles specify GaN-based active subwoofers to reduce touring truck weight.
Germany
Outdoor venue construction in Berlin and Hamburg accelerates deployment of self-powered line arrays for festivals and touring infrastructure. The EU's Ecodesign Directive mandates sub-500 milliwatt standby power thresholds, forcing firmware-managed power sequencing redesigns. Professional audio manufacturing clusters in Berlin-Brandenburg pilot modular amplifier architectures for forthcoming right-to-repair compliance.
China
Shenzhen and Dongguan assembly bases pivot toward higher-margin active speaker modules with integrated DSP and amplification stages. GB standards for audio equipment safety and electromagnetic compatibility create parallel certification obligations for export-bound production. Acoustic measurement technician scarcity in Pearl River Delta manufacturing clusters constrains anechoic chamber calibration capacity.
Japan
Compact active monitor demand concentrates in Tokyo and Osaka for broadcast and post-production studio applications. METI efficiency labeling programs shape consumer electronics power supply design requirements. Yamaha Corporation's Dante-networked loudspeaker line extends from domestic facilities into European live-sound rental channels through Nagoya-based production coordination.
India
Technology campus construction in Bengaluru and Hyderabad generates demand for networked active ceiling speakers with centralized DSP control. BIS certification requirements for electronic goods create compliance friction for imported professional audio equipment. Commercial real estate developers in Maharashtra prioritize IT-AV convergence specifications for new-build installations.
Global Active Speaker Market Vendor Landscape
Global majors compete with regional champions across amplification topology and networked protocol integration. The vendor base stratifies into three tiers: integrated electronics conglomerates with captive transducer supply, specialized professional audio houses with rental channel relationships, and consumer electronics brands leveraging retail distribution scale. Dominant competitive moves include backward integration into rare-earth magnet sourcing and strategic partnerships for voice-assistant platform licensing.
Among Japanese electronics conglomerates, Sony Corporation and Yamaha Corporation exemplify vertical control strategies over transducer magnetics and wireless codec licensing. Bose Corporation occupies a position anchoring premium positioning through captive retail infrastructure. Edifier International Limited represents the Shenzhen-based assembly specialist archetype, while QSC Audio Products, LLC sits within the professional rental channel specialist tier. Pioneer Corporation and LG Electronics Inc. illustrate diversified electronics portfolio approaches spanning consumer and commercial applications.
| Leading Market Players |
|---|
| Bang & Olufsen A/S |
| Pioneer Corporation |
| Sony Corporation |
| Klipsch Group, Inc. |
| Edifier International Limited |
| Bose Corporation |
| LG Electronics Inc. |
| QSC Audio Products, LLC |
| Yamaha Corporation |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet pricing volatility in China's Jiangxi and Inner Mongolia processing clusters cascades through transducer manufacturing costs, compressing margins on mid-range active monitors while amplifying premium-tier pricing power for manufacturers with captive rare-earth supply arrangements.
Pricing Analysis
Warranty bundling and field-service contracts separate premium-tier active speaker vendors from economy competitors, with Dante-networked installations commanding extended coverage premiums. Three-tier pricing structure across premium, standard, and economy levels reflects transducer material grades and factory calibration rigor. Cost compression in mid-range silicon MOSFET amplification is intensifying because automotive sector demand for silicon carbide components diverts foundry capacity. Education procurement teams exhibit highest price sensitivity, while broadcast facility engineers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke fulfillment patterns for European and Asia-Pacific live-sound rental channels. Transducer magnetics production concentrates in China, with final assembly clustering in Shenzhen and Dongguan facilities. GaN semiconductor substrates draw from Japanese and Korean wafer suppliers. Single-source vulnerability in rare-earth processing creates exposure to export quota fluctuations. Distribution runs through professional audio rental houses and AV integrators rather than retail channels for commercial-grade deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Ecodesign Directive functions as a cost-of-compliance moat, elevating capital requirements for standby power redesign and material recovery infrastructure that filters out undercapitalized competitors.
For Market Incumbents: Cement specification control by deepening backward integration into neodymium magnet sourcing and securing exclusive Dante protocol licensing for networked ceiling speaker lines. GaN amplifier module shortages threaten production continuity for touring-grade subwoofers. Capacity addition in Berlin-Brandenburg manufacturing clusters addresses right-to-repair compliance ahead of mandate implementation.
For New Entrants and Emerging Players: Live-sound rental operators in Germany and the United Kingdom represent the most penetrable channel partner type for GaN-based active subwoofer introductions. India's technology campus construction in Bengaluru and Hyderabad offers white-space opportunity for networked ceiling speaker deployments. Voice-assistant platform licensing partnerships accelerate hospitality market entry without proprietary NLP development.
For Investors and Strategic Acquirers: Modular amplifier architecture announcements from Berlin-Hamburg manufacturing clusters are the leading indicator that right-to-repair readiness is separating acquisition-ready assets from stranded legacy inventories. Long-term viability centers on serviceable DSP platforms with field-replaceable components. Acquisition targets should demonstrate firmware-managed power sequencing capabilities and UV-cured adhesive substitution progress under REACH frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Amplifier Module Integration | Enables weight reduction for touring subwoofers demanded by German rental operators. |
| Dante Protocol Certification | Secures specification priority for corporate AV procurement consolidation in North American technology headquarters. |
| REACH-Compliant Adhesive Substitution | Accelerates production cycles through UV-cured alternatives while satisfying EU chemical restrictions. |
| Right-to-Repair Modular Architecture | Positions vendors ahead of EU serviceability mandates through field-replaceable DSP modules. |
| Voice-Assistant Platform Licensing | Extends consumer voice platforms into commercial hospitality and meeting space installations. |
Methodological Framework
Multi-period observation of neodymium pricing indices, GaN semiconductor foundry utilization, and Dante protocol adoption rates anchored the trend analysis, supplemented by interviews with live-sound rental operators, corporate AV procurement directors, acoustic measurement technicians, and professional audio manufacturing plant managers. Secondary validation drew from FCC emissions certification databases, EU Ecodesign Directive implementation guidance, METI efficiency labeling program updates, and customs records of rare-earth magnet trade flows. Bottom-up volume estimates triangulated against top-down market sizing across product type, end user, connectivity, and market segment dimensions.
Segment-weighting approaches distributed value projections across portable, smart, wireless, and home theater product configurations, with additional calibration for amplification topology and DSP integration depth. CAGRs derived from logistic growth curve fitting to historical shipment data, adjusted for technology substitution effects and regulatory phase-in schedules. Forecast inputs incorporated anechoic chamber calibration capacity constraints in Pearl River Delta manufacturing clusters and hospitality sector voice-assistant deployment trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruptions to rare-earth supply chains, abrupt wireless protocol standard shifts, and pandemic-scale event industry shutdowns. Forecasts reflect documented assumptions regarding Ecodesign Directive enforcement timelines and REACH substance restriction expansion pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Turbo Mills Market
Others
Flexographic Printing Plate Market
Others
Aboveground Storage Tanks Market
Others
Europe Electric Forklift Market
Others
Africa 3D Printing Construction Market
Others
APAC Smart Home Market
Others
Cryogenic Storage Tanks Market
Others
Spain Smart Home Market
Others
HPHT Diamond Cubic Press Market
Others
China Smart Home Market
Others
Singapore Retail Market
Others
Global Computer Graphics Market
Others
Healthcare Bioconvergence Market
Others
North America Halal Food and Beverage Market
Others
Profiling Floats Market
Others
US Luxury Travel Market