
 North America Flexographic Printing Market | 2026-2036
North America Flexographic Printing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flexographic Printing Market Analytics
The EPA's Safer Choice program is restructuring procurement criteria across consumer goods supply chains, compelling converters to reformulate ink portfolios. Barry-Wehmiller leverages its systems integration expertise to capture retrofit demand from legacy solvent-based operations. Mark Andy sustains technology leadership in narrow-web digital-flexo hybrid configurations for label converters. Flint Group anchors North American supply security through captive resin and pigment manufacturing.
Flexographic printing employs raised rubber or photopolymer plates mounted on rotating cylinders to transfer fast-drying inks onto continuous web substrates at speeds exceeding 500 feet per minute, serving high-volume packaging and label production where cost efficiency and substrate versatility dominate purchasing decisions. Flexible packaging and labels command the largest share of installed press capacity, reflecting e-commerce fulfillment and food safety labeling requirements. UV-curable technology represents the fastest-expanding ink segment as converters navigate volatile organic compound restrictions without sacrificing production speeds. Water-based formulations retain cost advantages in corrugated container applications where absorption rates and porous substrates reduce curing complexity.
The EPA regulates volatile organic compound emissions through Maximum Achievable Control Technology standards, while OSHA governs workplace chemical exposure limits in pressroom environments; state-level extended producer responsibility laws in California and New York are extending compliance obligations downstream to converters and brand owners. FDA food contact notification requirements further constrain ink migration thresholds for direct-contact packaging applications. Stakeholders must monitor regulatory divergence between U.S. federal standards and emerging provincial frameworks in Canada, particularly Quebec's accelerated chemical restriction timelines, to anticipate reformulation investments and geographic capacity reallocation.
Market Dynamics
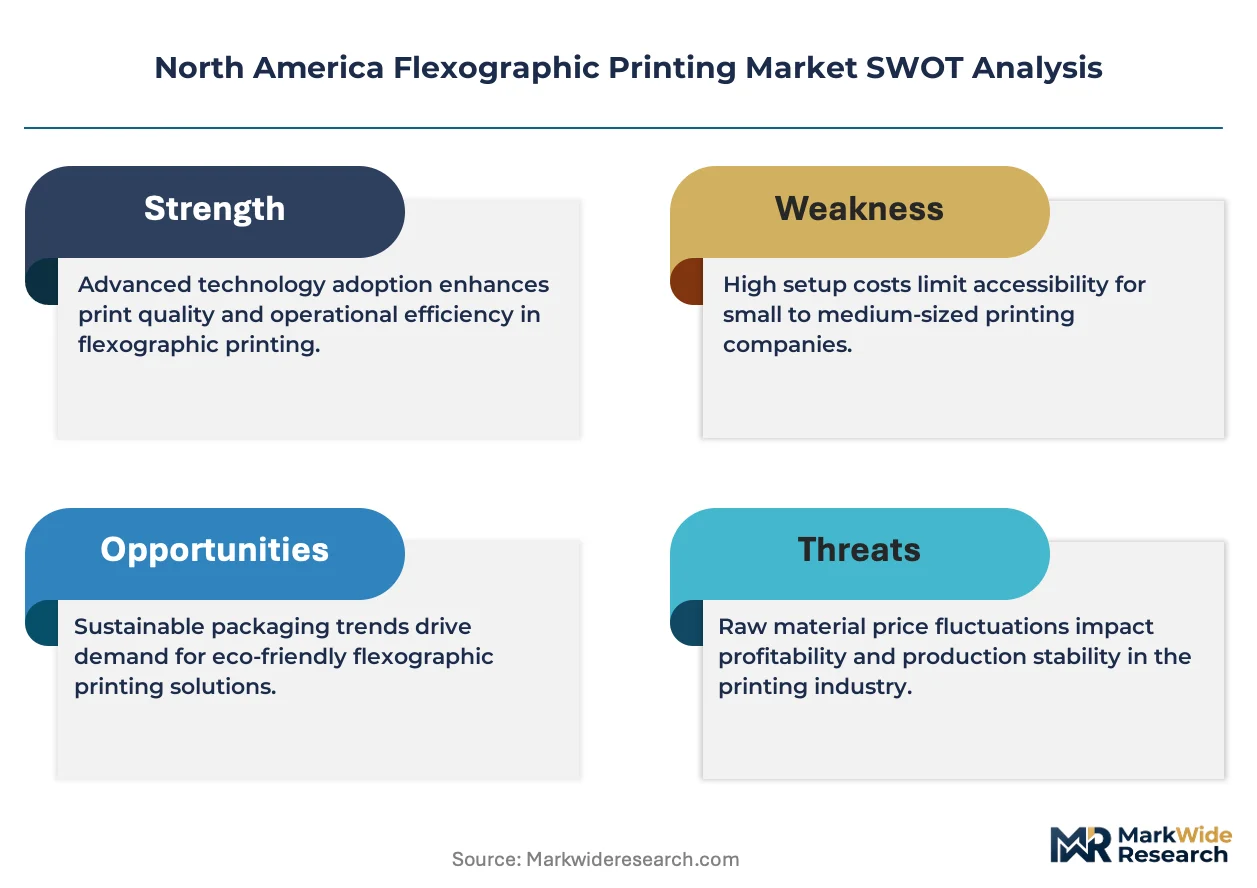
The EPA's Maximum Achievable Control Technology standards are forcing solvent-based ink systems into accelerated obsolescence across U.S. packaging corridors. Converters face simultaneous pressure from state extended producer responsibility mandates and brand-owner sustainability scorecards.
Growth Catalysts
- UV-curable ink chemistry:Food and beverage label converters adopt these systems to eliminate volatile organic compound emissions while maintaining press speeds above 500 feet per minute.
- California's extended producer responsibility framework:This legislation compels brand owners to fund recycling infrastructure, indirectly expanding demand for mono-material flexible packaging compatible with flexographic production.
- Midwest manufacturing corridor concentration:Proximity to corn-based substrate suppliers and resin producers reduces logistics costs for water-based ink formulators serving corrugated container markets.
Market Restraints
- Photopolymer plate cost volatility:Raw material dependence on petroleum-derived monomers exposes converters to crude price swings that compress margin predictability.
- Canadian supply concentration:Captive resin manufacturing for UV oligomers concentrates in southern Ontario, creating single-source vulnerability for U.S. Midwest printers.
- Migration threshold stringency:FDA food contact notification requirements for direct-contact applications impose technical barriers that exclude smaller converters from premium packaging segments.
Strategic Opportunities
- Quebec's accelerated chemical restriction timelines:Provincial frameworks banning specific photoinitiators create first-mover advantage for converters with reformulated UV ink portfolios.
- E-commerce fulfillment packaging:Corrugated void-fill and printed tape applications represent underpenetrated volume for narrow-web flexo configurations.
- Digital-flexo hybrid convergence:Variable data integration with traditional flexo units enables short-run versioning for craft beverage brands without plate changeover penalties.
Industry Challenges
- Press operator skill scarcity:Anilox roll maintenance and ink viscosity management require tacit knowledge that exits the workforce faster than training programs replenish.
- Legacy solvent system retrofit complexity:Existing drying infrastructure lacks thermal capacity for water-based alternatives, forcing capital-intensive hood replacement or press replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flexographic Printing Market |
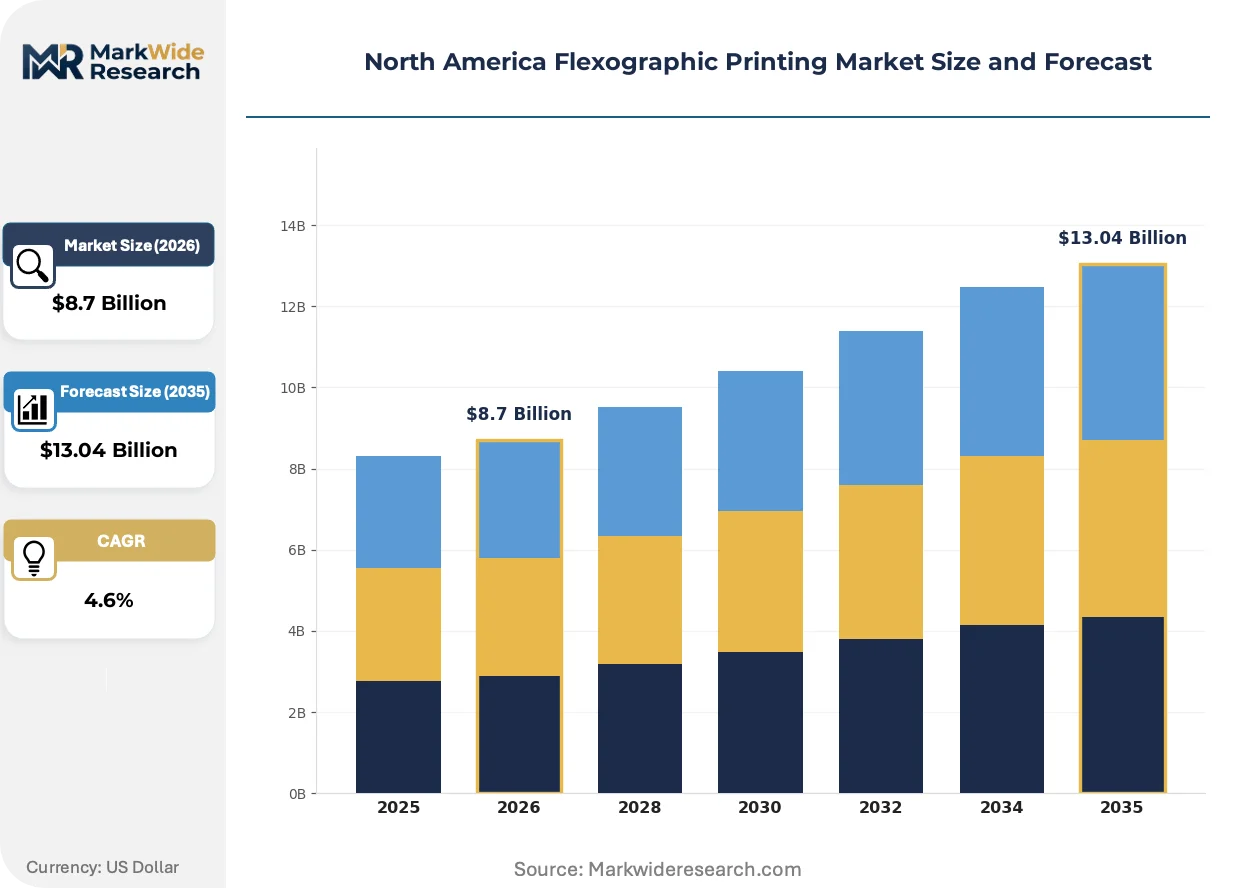
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Flexible Packaging, Corrugated Containers, Newspapers Technology: Water-Based, Solvent-Based, UV-Curable, Electron Beam End User: Food & Beverage, Consumer Goods, Pharmaceutical, Personal Care Application: Packaging, Printing, Branding, Decorative |
| Companies Covered | Barry-Wehmiller, Mark Andy, MPS Systems, Flint Group, Uteco North America, Koenig & Bauer, Bobst Group, Nilpeter, Anderson & Vreeland, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flexographic Printing Market Evolving Landscape
Active material substitution and regulatory compliance automation are compressing traditional equipment replacement cycles. Technology vendors now bundle environmental monitoring with press control systems.
Electron beam curing is absorbing market share from conventional thermal drying in high-end flexible packaging applications. Premium snack food brands in the U.S. Northeast specify these systems to eliminate photoinitiator migration risks entirely. The technology is absorbing capital allocation that previously funded incremental UV upgrades, reshaping vendor R&D roadmaps.
OSHA's updated permissible exposure limits for pressroom solvents triggered engineering control mandates across U.S. facilities. Converters now install automated ink dispensing with enclosed circulation to reduce airborne concentrations. Small and mid-sized operations in Mexico's Guadalajara cluster face disproportionate compliance costs relative to integrated multinational competitors.
Brand-owner sustainability scorecards now weight packaging recyclability above print decoration quality. Procurement teams at major food retailers specify mono-material polyethylene structures that simplify mechanical recycling streams. This preference rotation is most visible in California and New York, where state-level recycled content mandates create enforceable demand for compatible substrate-ink systems.
North America Flexographic Printing Market Segmentation
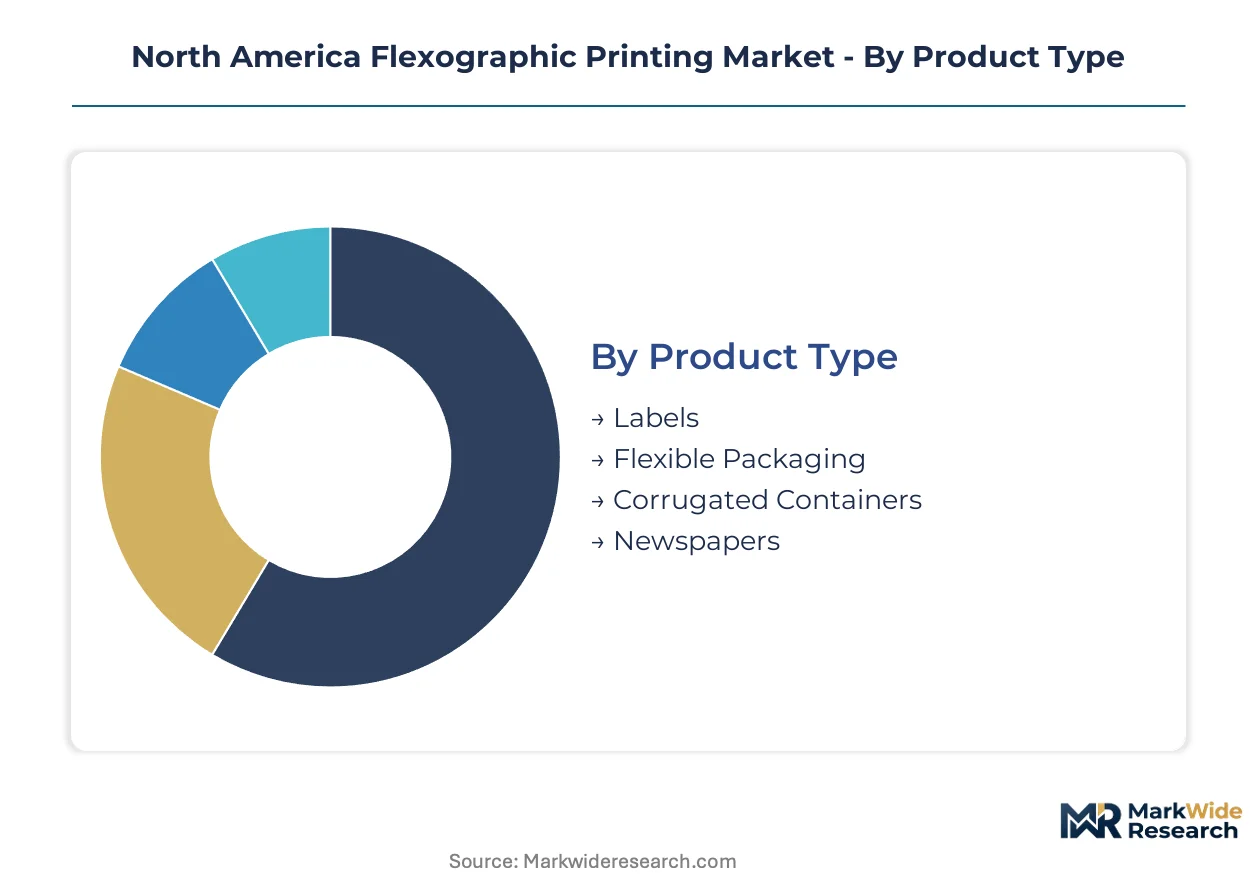
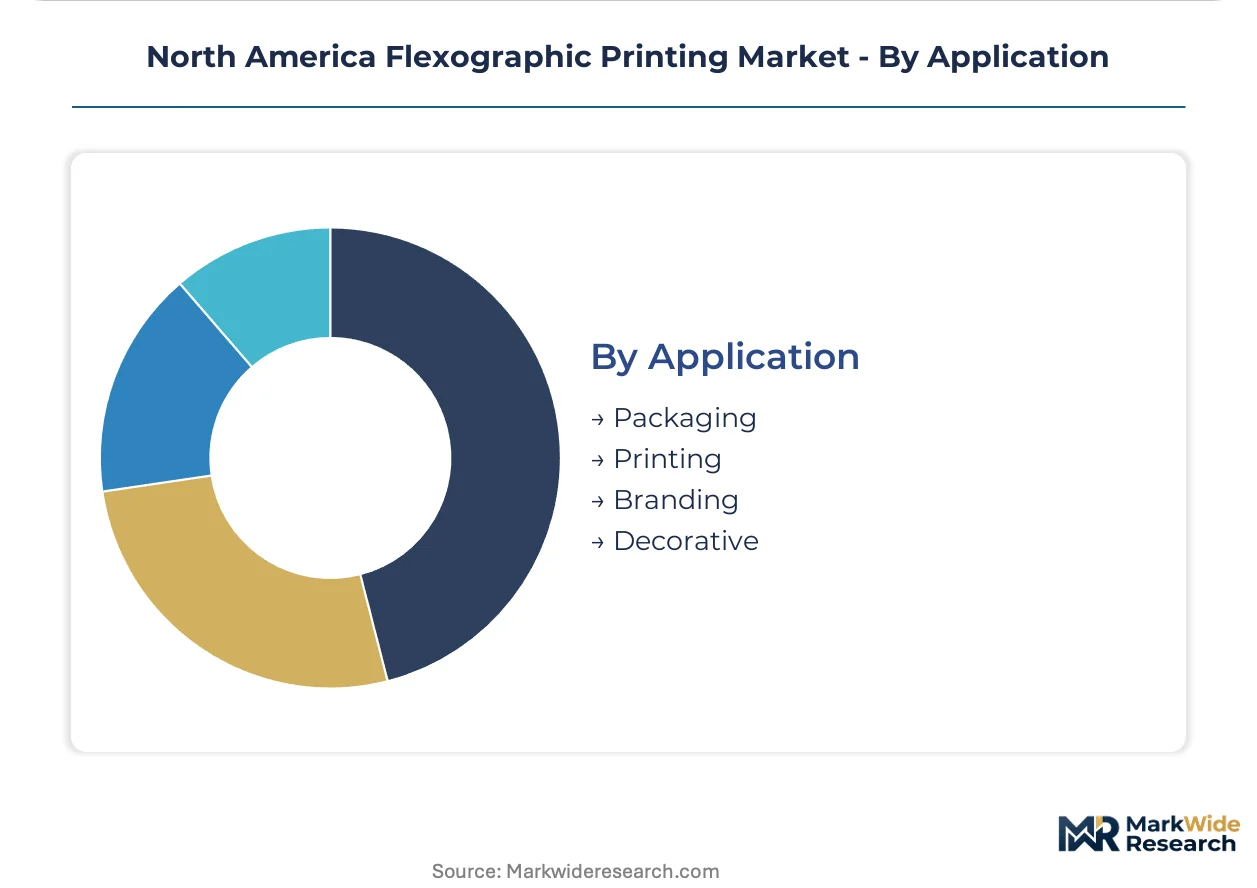
Segmentation in North American flexographic printing reveals how regulatory compliance burdens and substrate requirements fragment purchasing decisions across converters. Each dimension carries distinct certification obligations, equipment footprints, and margin structures that shape vendor positioning.
Product Type:
Certification intensity varies sharply across product categories, with FDA food contact notifications mandatory for flexible packaging and corrugated containers while decorative labels face lighter regulatory scrutiny.
- Flexible Packaging:Multi-layer film and pouch structures printed on CI flexo presses dominate food and beverage applications. California's extended producer responsibility mandates are accelerating mono-material specifications that simplify mechanical recycling without sacrificing barrier performance. Leading the category by volume: Flexible Packaging. Growing fastest: Labels.
- Labels:Pressure-sensitive and shrink-sleeve formats serve craft beverage brands and pharmaceutical compliance labeling. Demand concentrates in narrow-web digital-flexo hybrid configurations that enable short-run versioning without plate changeover penalties.
- Corrugated Containers:Post-print flexo on kraft board handles e-commerce void-fill and retail-ready displays. Water-based formulations dominate due to porous substrate absorption and reduced curing complexity.
- Newspapers:Coldset web offset conversion to flexo remains limited; thermal drying economics favor legacy infrastructure in regional dailies.
Flexible Packaging commands the largest installed press capacity. Labels are expanding most quickly.
Technology:
Technology selection directly determines capital intensity, with water-based systems requiring lower upfront investment than electron beam configurations that demand shielding infrastructure and ozone abatement systems.
- UV-Curable:Photoinitiator-based formulations cure instantly under mercury or LED lamps, preserving press speeds above 500 feet per minute while eliminating volatile organic compound emissions. EPA Maximum Achievable Control Technology standards are displacing solvent alternatives in Midwest manufacturing corridors where OSHA workplace exposure limits have tightened.
- Water-Based:Acrylic and styrene-acrylic emulsions serve corrugated and paperboard applications where substrate porosity enables ambient drying. Proximity to corn-based resin suppliers in Iowa and Nebraska reduces logistics costs for Midwest converters.
- Solvent-Based:Nitrocellulose and polyurethane systems retreat to specialty applications requiring adhesion to non-porous films. Regulatory obsolescence is accelerating as California and New York extend producer responsibility downstream.
- Electron Beam:Cationic chemistry cured by ionizing radiation eliminates photoinitiator migration risks entirely. Premium snack food brands in the U.S. Northeast specify these systems for direct-contact packaging despite capital premiums.
Water-Based retains the largest volume share. UV-Curable is climbing the fastest.
End User:
End-user concentration determines geographic demand clustering, with food and beverage procurement gravitating toward Midwest manufacturing corridors and pharmaceutical specifications favoring East Coast FDA-proximate facilities.
- Food & Beverage:Shelf-life extension and sustainability scorecards drive mono-material flexible packaging specifications. Major retailers now weight recyclability above print decoration quality in procurement criteria.
- Pharmaceutical:Serialization mandates and tamper-evident labeling require narrow-web flexo with integrated variable data printing. FDA food contact notification thresholds constrain ink migration specifications.
- Consumer Goods:Mass-market brands balance unit economics with shelf differentiation, favoring mid-tier press configurations with quick-change sleeve systems.
- Personal Care:Cosmetic and hygiene applications demand high-definition halftone reproduction on transparent films, pushing anilox specifications toward 2000+ line screens.
Food & Beverage dominates volume. Pharmaceutical is gaining share fastest.
Application:
Application purpose dictates margin structure, with functional packaging commanding premiums over decorative printing where commoditization pressures intensify.
- Packaging:Barrier protection and logistics durability requirements dominate corrugated and flexible formats. E-commerce fulfillment growth is expanding void-fill and printed tape specifications.
- Branding:Shelf-impact design and color consistency specifications drive pre-press investment in expanded gamut screening and spectrophotometric quality control.
- Printing:Informational and regulatory content requires variable data integration for lot codes and expiration dating.
- Decorative:Wallpaper and gift wrap applications face price compression from digital alternatives, limiting flexo penetration to high-volume commodity grades.
Packaging leads by volume. Branding is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the U.S. Midwest and Ontario manufacturing corridors while Mexican clusters absorb nearshoring demand from consumer brands. Consumption gravity shifts toward California and New York procurement hubs where extended producer responsibility mandates reshape substrate specifications. The regional split reflects divergent regulatory timelines and logistics cost optimization across the three-country footprint.
United States
Midwest manufacturing corridors in Illinois, Wisconsin, and Ohio host the densest press installations serving corrugated container and flexible packaging demand. EPA Maximum Achievable Control Technology standards accelerate solvent-based system obsolescence across these states. Chicago and Milwaukee anchor captive resin supply networks for water-based ink formulators.
Canada
Southern Ontario concentrates UV oligomer resin manufacturing and photopolymer plate fabrication for cross-border supply. Quebec's accelerated chemical restriction timelines ban specific photoinitiators ahead of federal schedules. Toronto and Montreal clusters face reformulation investment pressure to maintain U.S. market access.
Mexico
Guadalajara's packaging cluster serves North American brand owners executing nearshoring strategies for flexible film and label production. OSHA-aligned workplace exposure regulations impose compliance costs that disadvantage smaller converters relative to integrated multinationals. The Bajío Region attracts press manufacturer assembly operations serving Latin American export markets.
California
Extended producer responsibility frameworks mandate brand-owner funding of recycling infrastructure, indirectly expanding mono-material flexible packaging specifications. FDA food contact notification requirements for direct-contact applications constrain ink migration thresholds. Los Angeles and Central Valley distribution hubs prioritize shelf-ready corrugated formats for agricultural export packaging.
North America Flexographic Printing Market Competitive Landscape
The competitive structure tilts toward integrated systems providers with captive supply chain control over critical consumables. Press manufacturers and ink formulators occupy distinct but interdependent tiers, with consolidation pressure intensifying around environmental compliance bundling. Two archetypes dominate: full-line systems integrators combining hardware, software, and consumables; and specialized narrow-web equipment builders targeting label converter versioning needs. Competitive moves center on retrofit service expansion for legacy solvent-based operations and strategic partnerships linking press vendors with resin suppliers.
Among North American-based systems integrators, Barry-Wehmiller occupies a position exemplifying the full-line archetype through its multi-brand portfolio spanning press manufacturing and aftermarket services. Mark Andy represents the narrow-web specialization vector with digital-flexo hybrid configurations. Flint Group anchors the consumables-dominated tier through captive pigment and resin manufacturing. These three entities illustrate how competitive positioning fragments across equipment versus chemistry value capture.
| Leading Market Players |
|---|
| Barry-Wehmiller |
| Mark Andy |
| MPS Systems |
| Flint Group |
| Uteco North America |
| Koenig & Bauer |
| Bobst Group |
| Nilpeter |
| Anderson & Vreeland |
| Others |
Value Network & Pricing Analysis
Press operator skill scarcity in the U.S. Midwest and Guadalajara packaging cluster widens pricing-tier spreads between premium electron-beam installations and standard water-based configurations, as labor-cost differentials compound equipment-capital premiums for converters navigating EPA compliance deadlines.
Pricing Analysis
Cost-down pressure on mid-tier press configurations accelerates because brand-owner sustainability scorecards compress decoration budgets while demanding mono-material substrate compatibility. Three-tier pricing structure across premium electron-beam, standard UV-curable, and economy water-based levels reflects certification intensity and after-sales service bundling. Price differentiation hinges on FDA food-contact notification status and anilox specification grade. Smaller converters in Mexico's Guadalajara cluster exhibit highest price sensitivity due to disproportionate OSHA compliance costs; integrated multinationals with captive resin supply show lowest sensitivity.
Supply Chain Analysis
Dual-sourcing mandates from major food retailers compel ink formulators to qualify resin suppliers across southern Ontario, Illinois, and Ohio manufacturing corridors. Photopolymer plate fabrication draws from petroleum-derived monomer feedstocks anchored in Canadian petrochemical complexes and U.S. Gulf Coast refineries. Single-source vulnerability concentrates in UV oligomer resin manufacturing where southern Ontario facilities supply Midwest U.S. printers. Distribution runs through captive direct-to-converter channels for integrated systems providers and regional distribution partnerships for specialized narrow-web equipment builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-curable and electron-beam curing technologies are displacing legacy solvent-based infrastructure across North American packaging corridors, creating asymmetric reward structures for converters with reformulated ink portfolios and compliant press configurations.
For Market Incumbents: Deploy retrofit service bundling to capture legacy solvent-system upgrade demand before EPA Maximum Achievable Control Technology enforcement hardens. Deepen captive resin manufacturing in Iowa and Nebraska to secure corn-based acrylic supply chains against logistics cost volatility. Digital-flexo hybrid convergence from narrow-web specialists threatens equipment-replacement revenue; counter by integrating environmental monitoring systems into press control architectures. For New Entrants and Emerging Players: Launch via e-commerce fulfillment packaging applications where corrugated void-fill and printed tape specifications remain underpenetrated by established narrow-web configurations. Target craft beverage label versioning in California and New York where extended producer responsibility mandates create procurement friction for legacy converters. Pursue strategic partnerships with Quebec-based ink formulators to exploit accelerated photoinitiator restriction timelines ahead of U.S. federal schedules. For Investors and Strategic Acquirers: Re-rating potential sits with consumables-anchored formulators given EPA regulatory obsolescence timelines that compel recurring reformulation investment cycles. Long-term viability favors captive pigment and resin manufacturers with backward integration into photopolymer chemistry. Watch Quebec's chemical restriction enforcement velocity as the inflection signal for geographic capacity reallocation toward reformulation-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive UV oligomer production insulates Flint Group and Barry-Wehmiller from Canadian supply concentration risk. |
| Digital-Flexo Hybrid Platform Launch | Variable data integration enables short-run versioning for pharmaceutical serialization mandates without plate changeover penalties. |
| Electron Beam Curing Capacity Expansion | Premium snack food brands in the U.S. Northeast specify these systems to eliminate photoinitiator migration risks entirely. |
| Retrofit Service Portfolio Buildout | Legacy solvent-based press conversions capture stranded asset demand before EPA Maximum Achievable Control Technology enforcement tightens. |
| Quebec-First Reformulation Partnership | Accelerated chemical restriction timelines create first-mover advantage for UV ink portfolios compliant with provincial bans. |
Research Methodology
Independent corroboration across press manufacturer technical directors, ink formulation R&D leads, and corrugated converter procurement managers underwrites the qualitative findings. Primary fieldwork with anilox roll maintenance specialists and narrow-web label converter operations heads combined with secondary validation from EPA enforcement databases, OSHA permissible exposure limit updates, and FDA food contact notification filings. Bottom-up installed press capacity estimates triangulated against top-down ink consumption tonnage reported in customs and trade data.
Rate-of-change decomposition across technology substitution curves, regulatory compliance deadlines, and substrate specification shifts structured the analytical framework. Segmentation modeling captured product type, ink chemistry, end-user concentration, and application purpose dimensions throughout the forecast period. CAGRs derived from equipment replacement cycle analysis and consumables attach-rate projections, with specific inputs including photopolymer plate cost volatility indices and corn-based resin price series from Iowa and Nebraska suppliers.
Regulatory enforcement velocity, photoinitiator substitution cost curves, and workforce training program throughput are the dominant revision risks. Deviation in EPA Maximum Achievable Control Technology implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Process Spectroscopy Market
Others
Griffin Beaker Market
Others
Port Replicator Market
Others
Asia-Pacific Social Media Management Market
Others
China 3D Printing Construction Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Global Solder Balls Market
Others
Mini Personal Computer Market
Others
Hearables Market
Others
Aboveground Storage Tanks Market
Others
Hardwood Market
Others
Defense Optronics Market
Others
GCC Shisha Tobacco Market
Others
Europe Aircraft Lighting Systems Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Storm Surge Barriers Market