
 Printing Plate Market | 2026-2036
Printing Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Printing Plate Market Analytics
Skilled prepress technician availability is redrawing competitive boundaries in plate manufacturing. Kodak sustains technology leadership through digital workflow integration, while Fujifilm Holdings Corporation dominates photopolymer chemistry for flexographic applications. Flint Group International GmbH leverages vertical integration into raw resin production to control cost structures.
A printing plate is a surface matrix, typically aluminum, steel, polyester, or photopolymer, engineered with hydrophilic and oleophilic regions to transfer ink selectively onto substrates via offset, flexographic, gravure, or letterpress processes; plate thickness tolerances often fall within 0.15–0.40 mm depending on press configuration. Aluminum plates anchor the offset segment through established recycling infrastructure and dimensional stability under high-speed web tension. Photopolymer plates are gaining share in flexographic packaging as solvent-washout technologies yield to thermal and aqueous processing methods that reduce volatile organic compound exposure. The packaging industry end-user channel commands the dominant margin pool due to SKU proliferation and shorter run lengths requiring frequent plate changes.
EPA emissions guidelines and OSHA workplace chemical exposure limits shape North American plate chemistry formulations, while REACH and RoHS compliance in Europe restricts certain photoinitiators and heavy metal additives in plate construction. China's GB standards and MIIT circular economy directives are pressing domestic manufacturers toward recyclable aluminum substrates and reduced solvent usage in plate processing. Stakeholders must weigh regional regulatory divergence against the capital cost of maintaining parallel formulation portfolios.
Market Dynamics
Photopolymer chemistry evolution is compressing plate-making cycle times while regulatory pressure on solvent emissions forces capital retooling across manufacturing footprints.
Growth Catalysts
- E-commerce fulfillment surge:Packaging converters in China and India are expanding plate procurement to meet corrugated and flexible packaging volume spikes from online retail logistics networks.
- REACH chemical restrictions:European ECHA mandates on photoinitiator safety are accelerating adoption of aqueous-washout plate technologies that reduce volatile organic compound exposure in flexographic operations.
- Thermal processing diffusion:Solvent-free plate imaging systems are penetrating mid-tier converter operations, eliminating hazardous waste disposal costs and enabling faster plate-to-press turnaround.
Market Restraints
- Raw resin concentration:Photopolymer plate production depends on captive supply of specialized elastomers concentrated among petrochemical suppliers in Germany and Japan, creating input cost volatility.
- Aluminum substrate tariffs:Trade friction affecting rolled aluminum sheet imports into North American and European plate manufacturing clusters elevates base material costs for offset plate producers.
- Digital print substitution:Inkjet and toner-based direct-to-substrate systems are capturing short-run label and commercial print volumes that previously required conventional plate-based workflows.
Strategic Opportunities
- India packaging expansion:Domestic flexible packaging and label production growth under BIS quality certification schemes creates demand for imported photopolymer plate technologies and localized technical service.
- CE marking convergence:Unified EU machinery safety and chemical compliance frameworks enable plate manufacturers to engineer single-SKU products for pan-European distribution.
- Workflow software integration:Cloud-based prepress automation converging with plate imaging hardware is opening recurring revenue streams through subscription-based color management and asset tracking services.
Industry Challenges
- Prepress technician scarcity:Skilled operators capable of calibrating digital plate imagers and managing ICC color workflows are in short supply across converter operations in China and Southeast Asia.
- Legacy press integration:Retrofitting thermal plate processors and automated plate loaders into existing flexographic and offset press configurations demands extended downtime and specialized mechanical engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing Plate Market |
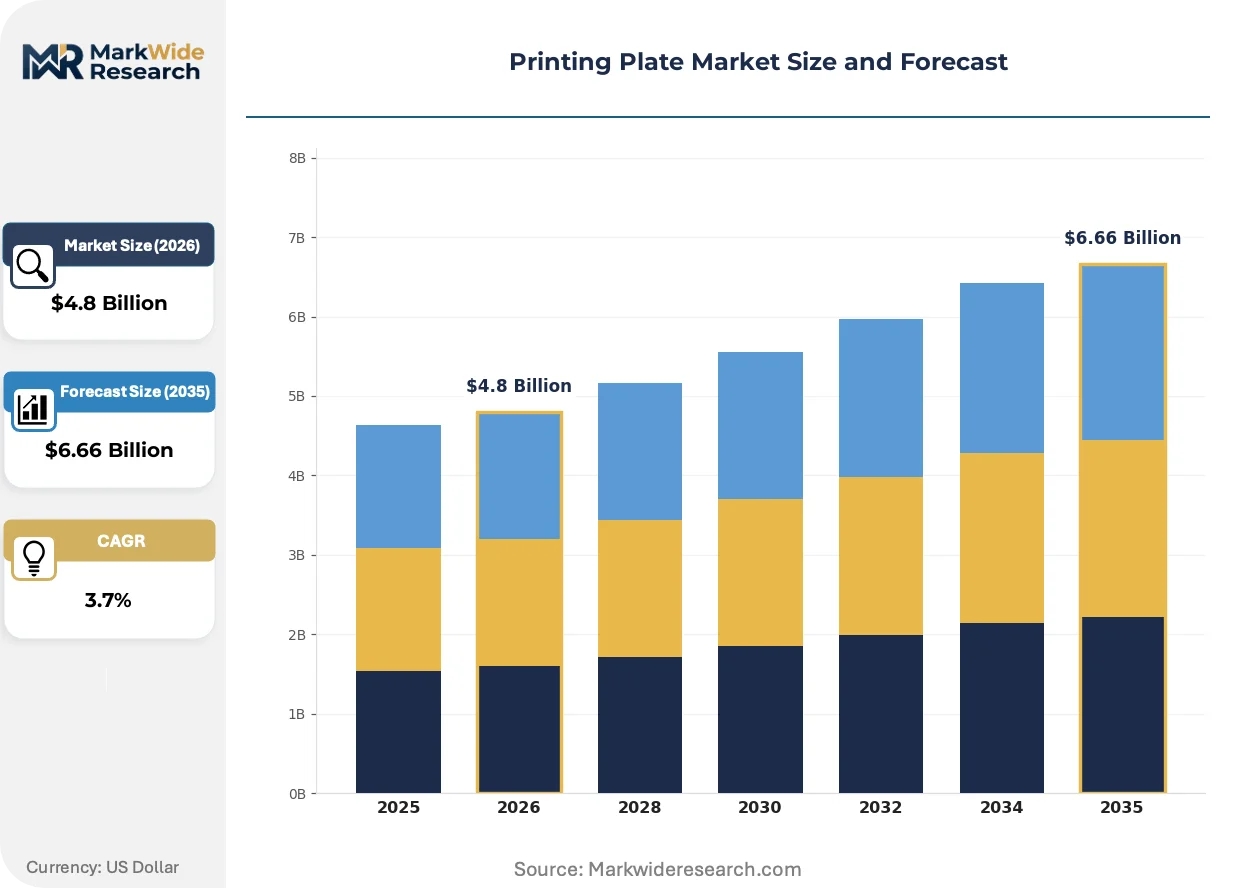
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photopolymer Plates, Steel Plates, Aluminum Plates, Polyester Plates Application: Flexographic Printing, Offset Printing, Letterpress Printing, Gravure Printing End User: Commercial Printing, Packaging Industry, Textile Printing, Newspaper Printing Technology: Digital Printing, Conventional Printing, Hybrid Printing, Laser Engraving |
| Companies Covered | Agfa-Gevaert N.V., Asahi Photoproducts Co., Ltd., Kodak, Miraclon Corporation, Flint Group International GmbH, Fujifilm Holdings Corporation, Toray Industries, Inc., XSYS, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing Plate Market Evolving Landscape
Digital workflow integration is collapsing traditional boundaries between design, prepress, and plate production, compressing time-to-press and redefining where value capture occurs in the supply chain.
Flat-top dot photopolymer plate technology is supplanting conventional round-top dot structures in high-line-count flexographic printing. Brand owners and premium food packaging converters in North America and Western Europe are adopting these plates at accelerating pace to achieve smooth vignettes and reduced ink consumption. The structural consequence is compression in makeready waste and enabled print consistency that supports brand color standardization across geographically distributed packaging supply chains.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and specific photoinitiators are reshaping photopolymer formulation chemistry across European plate manufacturing. Industrial consequence includes accelerated R&D investment in bio-based monomers and water-processable plate systems. The flexographic packaging segment is most affected, with converters in Germany, France, and the Netherlands retrofitting washout equipment to handle aqueous chemistry.
Converter procurement patterns are consolidating plate specification decisions at the corporate level rather than individual plant level. Large multinational packaging groups are centralizing prepress operations and negotiating master service agreements with plate suppliers that bundle hardware, consumables, and technical support. This consolidation is most visible in North American corrugated and folding carton operations where capital discipline favors vendor reduction and standardized plate specifications across multi-site networks.
Printing Plate Market Segmentation
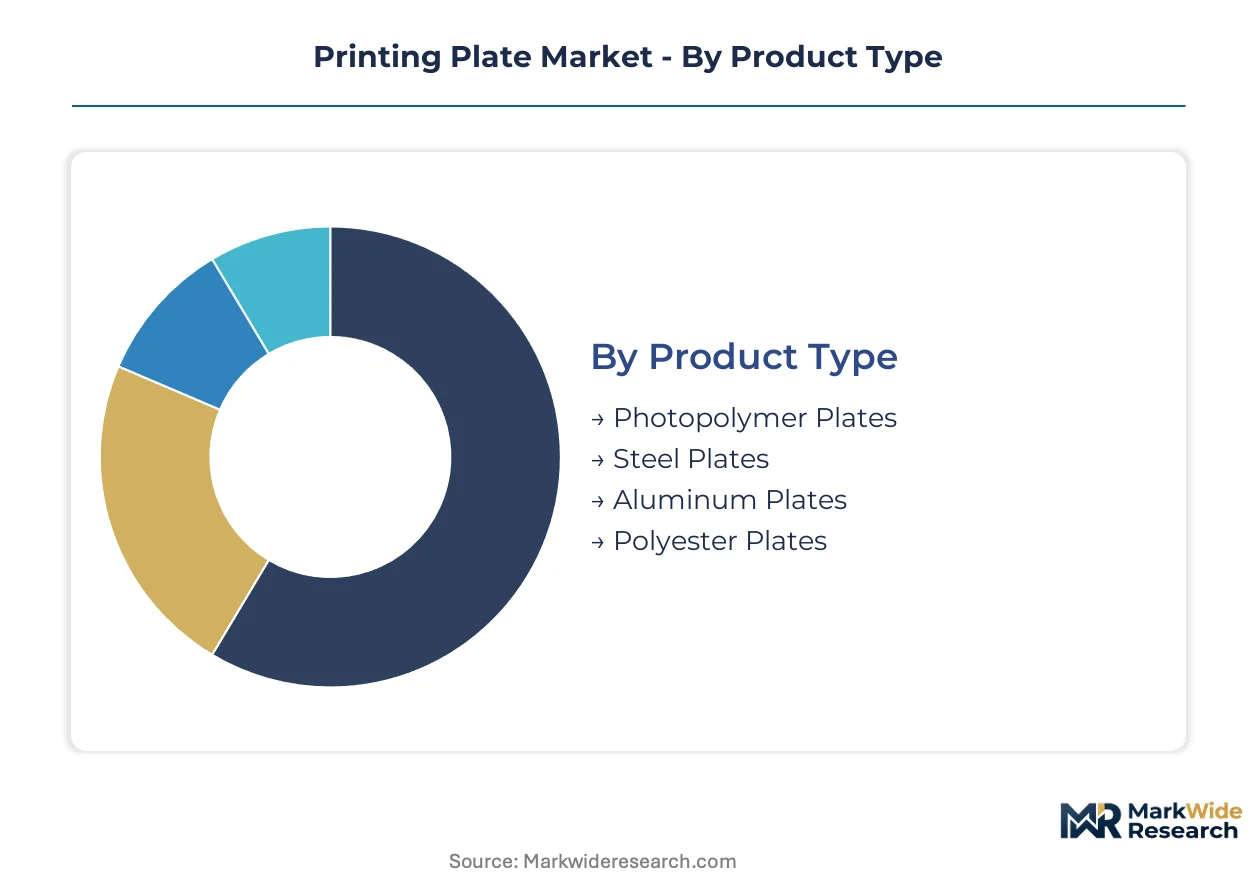
Printing plate procurement patterns diverge sharply by substrate chemistry and press technology, with packaging converters driving volume concentration while commercial print channels fragment across legacy and digital workflows. Segment boundaries are blurring as thermal processing and flat-top dot innovations reshape which plate types command premium positioning versus commodity substitution.
Product Type:
Domestic production of aluminum plates dominates North American and European supply chains through captive recycling infrastructure, while photopolymer plate demand concentrates in Asia-Pacific import channels serving flexible packaging growth.
- Photopolymer Plates:Elastomer-based matrices with ultraviolet-cured layers enable solvent-free thermal processing and aqueous washout systems. Demand concentrates in corrugated and flexible packaging converters across China and India where REACH-compliant formulations are displacing legacy solvent technologies amid tightening volatile organic compound regulations.
- Aluminum Plates:Grained anodized aluminum substrates deliver dimensional stability under high-speed web tension with established closed-loop recycling economics. North American offset newspaper and commercial print operations anchor procurement volume, though tariff exposure on rolled sheet imports is elevating base material cost structures.
- Steel Plates:Magnetic and non-magnetic variants serve specialized gravure cylinder bases and high-wear letterpress applications. German and Japanese industrial print equipment manufacturers specify these for heavy-duty packaging line configurations.
- Polyester Plates:Thin-gauge polymer films support short-run digital offset and proofing workflows with lower capital entry points. Independent commercial print shops in fragmented urban markets favor these for jobbing work and variable data applications.
Aluminum plates hold the largest share; momentum sits with photopolymer plates as aqueous processing gains regulatory tailwinds.
Application:
Cost tier stratification separates high-volume commodity packaging from precision commercial work, with makeready time and ink transfer efficiency determining plate specification economics.
- Flexographic Printing:Rotary relief printing using elastomer or photopolymer plates dominates flexible packaging, corrugated containers, and label production. Flat-top dot structures are displacing conventional round-top configurations in premium food packaging across North American brand owner supply chains, compressing makeready waste and enabling smoother vignettes.
- Offset Printing:Planographic lithography using aluminum plates commands newspaper, commercial sheetfed, and heatset web applications. The technology's maturity and recycling infrastructure sustain its position in high-volume publication and direct mail segments despite digital print incursion at the short-run margin.
- Letterpress Printing:Raised surface relief printing persists in security document, specialty label, and premium packaging niches requiring tactile impression quality. Steel and photopolymer plate configurations serve this declining but defensible application base.
- Gravure Printing:Intaglio cylinder engraving for ultra-long-run publication and packaging work employs chrome-plated steel bases with electromechanical or laser engraving. Asian publication gravure houses and European luxury packaging converters maintain this capital-intensive process for runs exceeding ten million impressions.
Offset printing retains volume leadership; flexographic printing is climbing the fastest as packaging SKU proliferation accelerates plate change frequency.
End User:
Customer type concentration is consolidating procurement authority at the corporate level among multinational packaging groups, while independent commercial printers fragment across jobbing and specialty niches.
- Packaging Industry:Corrugated, flexible film, folding carton, and label converters generate the dominant margin pool through SKU proliferation and shorter run lengths requiring frequent plate changes. E-commerce fulfillment networks in China and India are expanding plate procurement volumes for protective shipping materials and branded unboxing experiences.
- Commercial Printing:General jobbing, direct mail, catalog, and promotional print operations face sustained digital substitution pressure. Remaining plate-based volume concentrates in long-run catalog and directory work where offset economics persist.
- Newspaper Printing:Heatset and coldset web offset operations serving metropolitan dailies and community publications are contracting as digital news consumption displaces print circulation. Surviving operations consolidate onto regional printing centers with standardized aluminum plate specifications.
- Textile Printing:Rotary screen and flatbed applications for fabric decoration employ specialized photopolymer and steel plate configurations. Italian and Turkish fashion textile clusters sustain niche demand for high-resolution pattern reproduction.
Packaging industry holds the largest share; momentum sits with this segment as e-commerce logistics networks expand corrugated and flexible film requirements.
Technology:
Maturity gradients separate established conventional workflows from hybrid and fully digital systems, with capital availability and technical labor scarcity determining adoption velocity.
- Digital Printing:Computer-to-plate imaging and direct-to-substrate inkjet systems eliminate physical plate production entirely for appropriate run lengths. Short-run label converters in North America and Western Europe are adopting these workflows to compress time-to-market and enable versioned packaging for regional marketing campaigns.
- Conventional Printing:Analog plate production through film-based or direct laser exposure persists in high-volume newspaper and publication operations where amortized capital and established technician pools defend incumbent economics.
- Hybrid Printing:Configurations combining conventional plate-based units with inline digital finishing or variable data modules bridge run-length economics. European folding carton and commercial print operations deploy these for personalized direct mail and security applications.
- Laser Engraving:Direct cylinder and plate surface ablation for gravure and flexographic applications enables seamless digital-to-physical transfer without chemical processing. Japanese and German equipment manufacturers lead this capital-intensive technology tier.
Conventional printing holds the largest share; digital printing is gaining share fastest as run lengths compress and cloud-based prepress automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes photopolymer plates at volumes exceeding all other nations combined, while the United States and Germany anchor offset aluminum plate demand through legacy newspaper and commercial print infrastructure that Asian markets never replicated at scale.
China
E-commerce fulfillment networks in Shanghai and Shenzhen are driving corrugated and flexible packaging plate procurement at unprecedented velocity. MIIT circular economy directives press domestic manufacturers toward recyclable aluminum substrates and reduced solvent processing. The Yangtze River Delta manufacturing cluster hosts the densest concentration of photopolymer plate conversion equipment outside Europe.
United States
Offset newspaper operations in Chicago and Dallas sustain aluminum plate volumes despite digital news displacement, while flexible packaging converters in Wisconsin and Ohio adopt flat-top dot photopolymer systems for food-contact applications. EPA emissions guidelines and OSHA workplace chemical exposure limits constrain photoinitiator selection in plate formulations. The Southeast packaging corridor from Atlanta to Charlotte is consolidating prepress operations under corporate procurement mandates.
Germany
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and specific photoinitiators are accelerating aqueous-washout plate retrofits across flexographic operations in Düsseldorf and Stuttgart. ECHA compliance frameworks enable single-SKU engineering for pan-European distribution. The Baden-Württemberg industrial belt maintains specialized steel plate production for gravure cylinder bases serving luxury packaging export markets.
India
Domestic flexible packaging and label production growth under BIS quality certification schemes creates import demand for photopolymer plate technologies and localized technical service support. Maharashtra and Gujarat host the fastest-expanding converter bases, though skilled prepress technician scarcity constrains imaging equipment utilization rates. The Delhi-NCR corridor is emerging as a secondary hub for corrugated packaging plate procurement tied to logistics network expansion.
Japan
METI industrial standards and JIS certification requirements shape photopolymer formulation specifications for domestic converters and export-oriented equipment manufacturers. The Kanto and Kansai regions concentrate gravure plate production for ultra-long-run publication work, while laser engraving technology development centers in Nagoya supply capital equipment globally. Japanese petrochemical suppliers maintain captive elastomer supply positions that influence regional plate cost structures.
Printing Plate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with chemistry control and digital workflow integration serving as the primary elevation mechanisms. The upper tier commands pricing power through captive resin production and cloud-based prepress automation bundling, while mid-scale fabricants compete on regional service density and technical support responsiveness. Three archetypes define positioning: chemistry-integrated multinationals, hardware-digital workflow hybrids, and regional plate specialists with deep converter relationships. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships with press manufacturers for bundled equipment-consumables offerings.
Among chemistry-integrated multinationals, Fujifilm Holdings Corporation and DuPont de Nemours, Inc. exemplify the archetype of photopolymer science control extending into plate manufacturing. Flint Group International GmbH occupies a position representing vertical integration into raw resin production as a cost structure defense mechanism. Kodak anchors the hardware-digital workflow hybrid tier, with its historical imaging equipment footprint supporting recurring consumables attachment. These three entities collectively represent the strategic positioning spectrum: chemistry dominance, supply chain control, and workflow integration.
| Leading Market Players |
|---|
| Agfa-Gevaert N.V. |
| Asahi Photoproducts Co., Ltd. |
| Kodak |
| Miraclon Corporation |
| Flint Group International GmbH |
| Fujifilm Holdings Corporation |
| Toray Industries, Inc. |
| XSYS |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese elastomer facilities shapes both photopolymer plate cost floors and supplier pricing power across converter procurement channels. Scale concentration in specialized resin production enables captive supply premiums while compressing margin room for mid-tier fabricants competing on spot aluminum substrate markets.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational packaging groups and integrated plate manufacturers, though spot purchasing persists for independent commercial print shops with variable volume profiles. Three-tier pricing structure across premium flat-top dot systems, standard aqueous-washout configurations, and economy solvent-processed grades separates food-contact certified formulations from general industrial applications. Cost compression in standard-grade aluminum offset plates is intensifying because tariff exposure on rolled sheet imports elevates base material economics. Independent commercial printers exhibit highest price sensitivity due to digital substitution pressure, while multinational corrugated converters prioritize technical service bundling over unit cost minimization.
Supply Chain Analysis
Inventory cycles for specialized photoinitiators and elastomer precursors stretch lead times when petrochemical feedstock volatility disrupts Japanese and German chemical clusters. Manufacturing concentration centers on China for aluminum plate finishing, Germany for steel gravure cylinder bases, and Japan for photopolymer resin synthesis, with raw material flows drawing from bauxite refining networks, chrome plating facilities, and captive acrylate monomer operations. Single-source vulnerability in N-methyl-2-pyrrolidone supply creates formulation risk for European REACH compliance transitions. Distribution runs through converter-direct master service agreements for volume accounts and regional distributor networks for fragmented commercial print channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based prepress automation subscriptions are expanding faster than hardware sales as packaging groups centralize color management and asset tracking across multi-site networks. This service-attach dynamic redefines where value capture concentrates in plate supplier economics.
For Market Incumbents: Compound defensive positioning by deepening backward integration into photoinitiator chemistry and securing long-term resin offtake from Japanese petrochemical suppliers. Expand technical service density in India's Maharashtra and Gujarat corridors to offset prepress technician scarcity constraining equipment utilization. Digital print substitution in short-run label applications demands workflow software bundling to lock in consumables attachment. For New Entrants and Emerging Players: Differentiate on aqueous-washout plate formulations tailored to India's BIS quality certification schemes, where domestic flexible packaging growth outpaces local technical support infrastructure. Target mid-tier corrugated converters in China's Yangtze River Delta with thermal processing equipment lease-to-own structures that eliminate hazardous waste disposal capital burdens. Lead with localized prepress training programs to address skilled operator gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chemistry-integrated fabricants with captive resin production and established recycling infrastructure for aluminum substrates. Long-term viability hinges on regulatory compliance adaptability across REACH, FDA food-contact, and MIIT circular economy frameworks. Acquisition target archetype: regional plate specialists with deep converter relationships in underconsolidated South Asian markets. Watch flat-top dot adoption rates in North American food packaging as inflection indicator for premium formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Chemistry | Captive supply of REACH-compliant photoinitiators insulates margin structures from ECHA regulatory volatility. |
| Aqueous-Washout Technology Licensing | Technology transfer agreements enable European flexographic converters to retrofit solvent-based washout equipment. |
| Cloud Prepress Platform Integration | Subscription-based color management creates recurring revenue attachment beyond physical plate transactions. |
| Regional Technical Service Expansion | Localized prepress training addresses technician scarcity constraining imaging equipment utilization in India. |
| Thermal Processing Equipment Leasing | Lease-to-own structures eliminate capital barriers for mid-tier converters adopting solvent-free plate systems. |
Research Methodology
Desk research of trade customs data, SEC filings from listed chemical and imaging equipment manufacturers, and ECHA regulatory guidance documents preceded structured interviews with prepress operations directors at multinational packaging groups, technical sales managers at plate manufacturers, procurement leads at corrugated converters, and plant engineers at aluminum rolling facilities. Primary fieldwork across China's Yangtze River Delta, Germany's Baden-Württemberg industrial belt, and India's Maharashtra-Gujarat corridor validated secondary estimates through bottom-up and top-down triangulation.
Variance decomposition across substrate chemistry, press technology, and end-use channel dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured photopolymer versus aluminum versus steel plate substrates, flexographic versus offset versus gravure applications, and packaging versus commercial print versus newspaper end users. CAGRs derived from regression analysis against corrugated packaging production indices, e-commerce fulfillment volume proxies, and regulatory compliance cost curves. Industry-specific forecast inputs included REACH Annex XVII implementation timelines and MIIT circular economy directive enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce logistics expansion or accelerated digital print substitution would require recalibration. Forecasts reflect documented assumptions regarding elastomer supply continuity and aluminum tariff regimes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Food Marking Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Global Conductive Inks Market
Printing Inks
North America Printing Inks Market
Printing Inks
Ink Additives Market
Printing Inks
Food Grade Inks Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Flexible Letterpress Printing Ink Market