
 Fresh Pears Market | 2026-2036
Fresh Pears Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Pears Market Foresight
GlobalGAP certification is collapsing as the baseline qualification for export-oriented pear suppliers, replacing older farm assurance schemes with unified food safety and traceability benchmarks. Del Monte Foods leverages its integrated cold-chain infrastructure to sustain year-round supply continuity across multiple hemispheres. USA Pears (Pear Bureau Northwest) dominates North American varietal branding through controlled-origin marketing programs. Turkish Fruit Exporters Association anchors Black Sea supply corridors with specialized logistics for early-season Bartlett shipments.
Fresh pears are deciduous pome fruits of the species Pyrus communis and related cultivars, harvested at physiological maturity with firm flesh measuring 10-14 pounds pressure and soluble solids exceeding 12% for optimal post-harvest handling. The fruit serves commercial markets as a fresh-eating commodity, processing input for juice and baby food, and a premium dessert ingredient in food service channels. Bartlett and Anjou varieties lead volume trade due to established cold-storage tolerance and broad consumer recognition, while Bosc and Comice occupy higher margin pools in direct-to-retail and gourmet segments. Packaging type segmentation shows clamshells and retail bags expanding fastest in supermarket channels as retailers enforce standardized unitization for automated checkout compatibility.
USDA grading standards and FDA Food Safety Modernization Act requirements govern US market access, with the EPA regulating pesticide residue thresholds under tolerances for imported fruit. The EU Green Deal and EFSA phytosanitary protocols shape European import eligibility, while China's SAMR enforces GB national food safety standards for foreign pear entry. Stakeholders must monitor divergence between national maximum residue limits and emerging carbon-footprint disclosure mandates that threaten to fragment previously harmonized trade corridors.
Market Dynamics
The EU Green Deal's sustainable agriculture mandates are compressing certification timelines for export-oriented pear suppliers, forcing rapid orchard-level compliance upgrades across European production zones while reshaping competitive access to premium retail channels.
Growth Catalysts
- Heritage varietal demand:Food service chefs are incorporating heritage pear varieties into seasonal menus, creating pull-through demand for specialty cultivars with distinct flavor profiles and visual differentiation.
- Organized retail expansion:China's urban consumers are shifting toward premium imported pear varieties through supermarket chains and e-commerce platforms, concentrating volume in certified supply corridors.
- Cold-chain infrastructure:Integrated post-harvest handling systems are extending shelf-life windows for Bartlett and Anjou varieties, enabling year-round supply continuity across hemispheric production cycles.
Market Restraints
- Input cost volatility:Labor scarcity in Washington State and Oregon orchards is compressing harvest windows and elevating per-unit picking costs for hand-harvested varieties like Comice.
- Regulatory fragmentation:Divergence between EPA pesticide tolerances and EFSA maximum residue limits is forcing dual-track compliance investments for suppliers serving both US and EU markets.
- Substitution pressure:Fresh stone fruits and imported apples are displacing pear shelf space in European discount retail channels during peak summer availability windows.
Strategic Opportunities
- Carbon disclosure alignment:Early adopters of EU Green Deal carbon-footprint tracking are securing preferential listing terms with retailers implementing scope 3 emissions reduction targets.
- Clamshell packaging penetration:Automated checkout compatibility requirements in German and French supermarket chains are creating first-mover advantages for suppliers with standardized retail bag and clamshell unitization.
- Baby food processing contracts:Soluble solids specifications exceeding 12% are opening dedicated supply agreements with infant nutrition manufacturers seeking clean-label fruit inputs.
Industry Challenges
- GlobalGAP transition timelines:Orchard operators face compressed recertification deadlines as baseline farm assurance schemes sunset, requiring simultaneous documentation upgrades across traceability and food safety protocols.
- Post-harvest physiology expertise:Optimal harvest timing based on firmness pressure testing demands skilled labor pools that are thinning in traditional growing regions of Northern California and the Pacific Northwest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Pears Market |
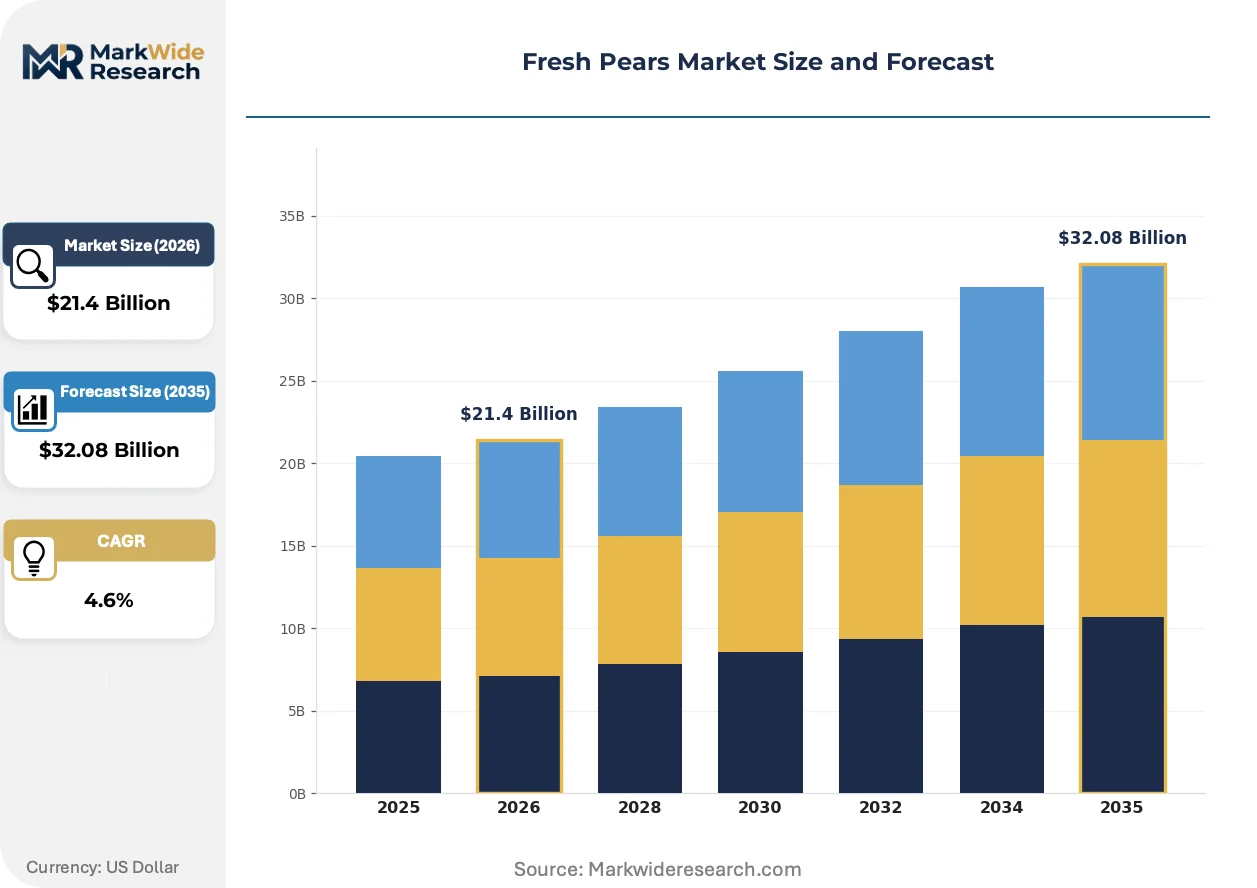
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $32.08 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Variety: Bartlett, Anjou, Bosc, Seckel, Comice, Forelle Packaging Type: Bulk Boxes, Clamshells, Retail Bags, Crates, Trays, Mesh Bags Distribution Channel: Supermarkets, Organic Stores, Online Grocers, Farmer Markets, Convenience Stores End User: Food Service, Home Consumers, Institutional Buyers, Exporters |
| Companies Covered | Del Monte Foods, Turkish Fruit Exporters Association, USA Pears (Pear Bureau Northwest), Indonesian Agricultural Trading Companies, European Pear Producers Cooperative, Duckwall Fruit, China National Fruit & Vegetable Wholesale Center, Russian Fruit Import Distributors, Northwest Packing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Pears Market Shifts & Advancements
Controlled-atmosphere storage protocols and precision agriculture sensors are restructuring how pear quality is maintained from orchard to retail, with technology adoption accelerating among large-scale operators seeking varietal differentiation.
Hyperspectral imaging systems for non-destructive ripeness assessment are decomposing traditional grading workflows that relied on manual pressure testing and visual inspection. Packing houses in Washington State and South Africa are deploying these systems to sort Bartlett and Bosc shipments by internal quality metrics. The technology is compressing rejection rates at destination markets by flagging physiological disorders before container loading.
REACH chemical authorization requirements are restricting post-harvest fungicide options available to EU-bound shipments, forcing suppliers toward integrated pest management and biological control agents in orchard sanitation protocols. Spanish and Italian producers are investing in ozone-based storage treatments to maintain phytosanitary compliance without banned active ingredients. The regulatory pressure is elevating operational costs for smallholder cooperatives lacking in-house compliance expertise.
Direct-to-retail procurement contracts are displacing traditional wholesale auction channels for premium varieties in East Asian markets. Japanese department store buyers and Chinese e-commerce platforms are contracting specific orchard blocks with documented provenance and harvest timing. The shift is most visible in Shanghai and Tokyo, where consumer willingness to pay for traceability is compressing intermediary margins and rewarding suppliers with captive cold-chain assets.
Fresh Pears Market Segmentation
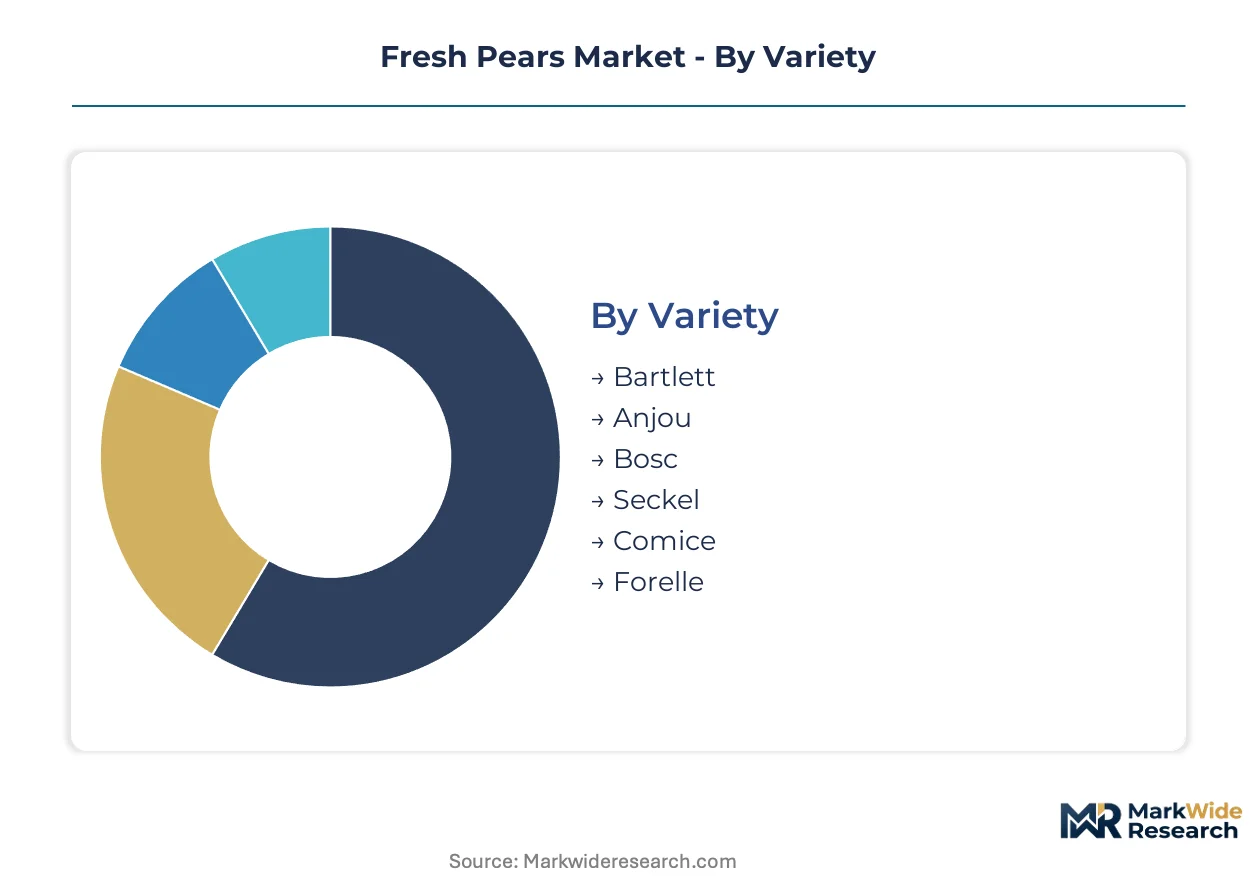
Pear suppliers configure their varietal portfolios and packaging formats around channel-specific requirements, with each segment demanding distinct cold-chain specifications and unit economics. Understanding how Bartlett volumes flow through supermarket networks versus how Comice reaches food service buyers determines margin capture and inventory risk.
Variety:
Channel-mix dynamics concentrate Bartlett and Anjou through mass retail and export corridors, while heritage varieties bypass wholesale auctions for contracted direct delivery.
- Bartlett:Harvested at 10-14 pounds pressure with soluble solids exceeding 12%, this variety tolerates controlled-atmosphere storage for 4-6 months, enabling Washington State and Argentine suppliers to sustain year-round supermarket supply. Demand concentrates in North American and Chinese organized retail, where standardized sizing supports automated checkout systems and private-label programs.
- Anjou:Green and red-skinned cultivars share cold-storage protocols with Bartlett but command shelf-space premiums in European discount channels during winter months. French and Belgian supermarket chains source Anjou through dedicated procurement contracts that specify harvest timing and internal quality metrics verified by hyperspectral imaging.
- Bosc:Distinctive russeted skin and firm flesh suit direct-to-retail and gourmet segments in Tokyo and Shanghai department stores.
- Seckel:Small size and intense sweetness target specialty food service and gift-box channels with limited volume scale.
- Comice:Hand-harvested requirements and delicate skin restrict this variety to premium direct sales and restaurant procurement in Paris and London.
- Forelle:Speckled appearance and crisp texture serve niche export markets in the Middle East and Southeast Asia with specialized packaging.
Bartlett dominates installed base across hemispheric production zones. Comice and Forelle represent where expansion concentrates for margin-focused suppliers.
Packaging Type:
Cost-tier stratification separates bulk export formats from retail-ready unitization, with automation compatibility driving format selection in German and French supermarket systems.
- Clamshells:Standardized plastic containers with fixed unit counts enable automated checkout scanning and reduce shrink in self-service produce departments. German retail chains mandate clamshell formats for Bartlett and Anjou shipments, with EFSA-compliant food-contact materials specified in procurement tenders.
- Retail Bags:Pre-weighed polypropylene bags with barcode labeling support high-volume throughput in hypermarket environments. Chinese e-commerce platforms and supermarket chains are expanding bag-format penetration for home delivery orders requiring damage-resistant handling.
- Bulk Boxes:Wooden or corrugated containers holding 18-20 kg remain the baseline for export consolidation and food service distribution.
- Crates:Reusable plastic crates serve closed-loop supply chains between major Spanish and Italian cooperatives and central European retail distribution centers.
- Trays:Single-layer cardboard trays with flow-wrap film protect premium varieties for direct-to-retail channels in Japanese department stores.
- Mesh Bags:Net packaging for open-display merchandising persists in traditional retail formats across Eastern Europe and Latin America.
Bulk Boxes dominate installed base in export corridors. Clamshells and Retail Bags are where expansion concentrates for automated retail compatibility.
Distribution Channel:
Customer-type stratification separates price-sensitive volume buyers from provenance-focused premium purchasers, with channel selection determining certification requirements and payment terms.
- Supermarkets:Multi-banner retail chains in China, Germany, and the United States consolidate procurement through centralized buying offices that enforce GlobalGAP certification and carbon-footprint disclosure. These channels absorb the majority of Bartlett and Anjou volumes with strict quality tolerances and just-in-time delivery windows.
- Online Grocers:E-commerce platforms in Shanghai and Tokyo are contracting specific orchard blocks with documented harvest timing and cold-chain integrity. Direct-to-consumer fulfillment demands damage-resistant packaging and precise ripeness staging to manage return rates.
- Organic Stores:Specialist retailers in France and Italy source heritage varieties through shorter supply chains with EU organic certification and reduced pesticide residue protocols.
- Farmer Markets:Direct producer-to-consumer sales in Pacific Northwest cities capture premium pricing for tree-ripe Comice and Seckel with minimal post-harvest handling.
- Convenience Stores:Limited assortment and high-turnover requirements in Japanese and South Korean urban formats favor single-serve clamshell configurations.
Supermarkets dominate installed base in volume terms. Online Grocers are where expansion concentrates for traceability-premium capture.
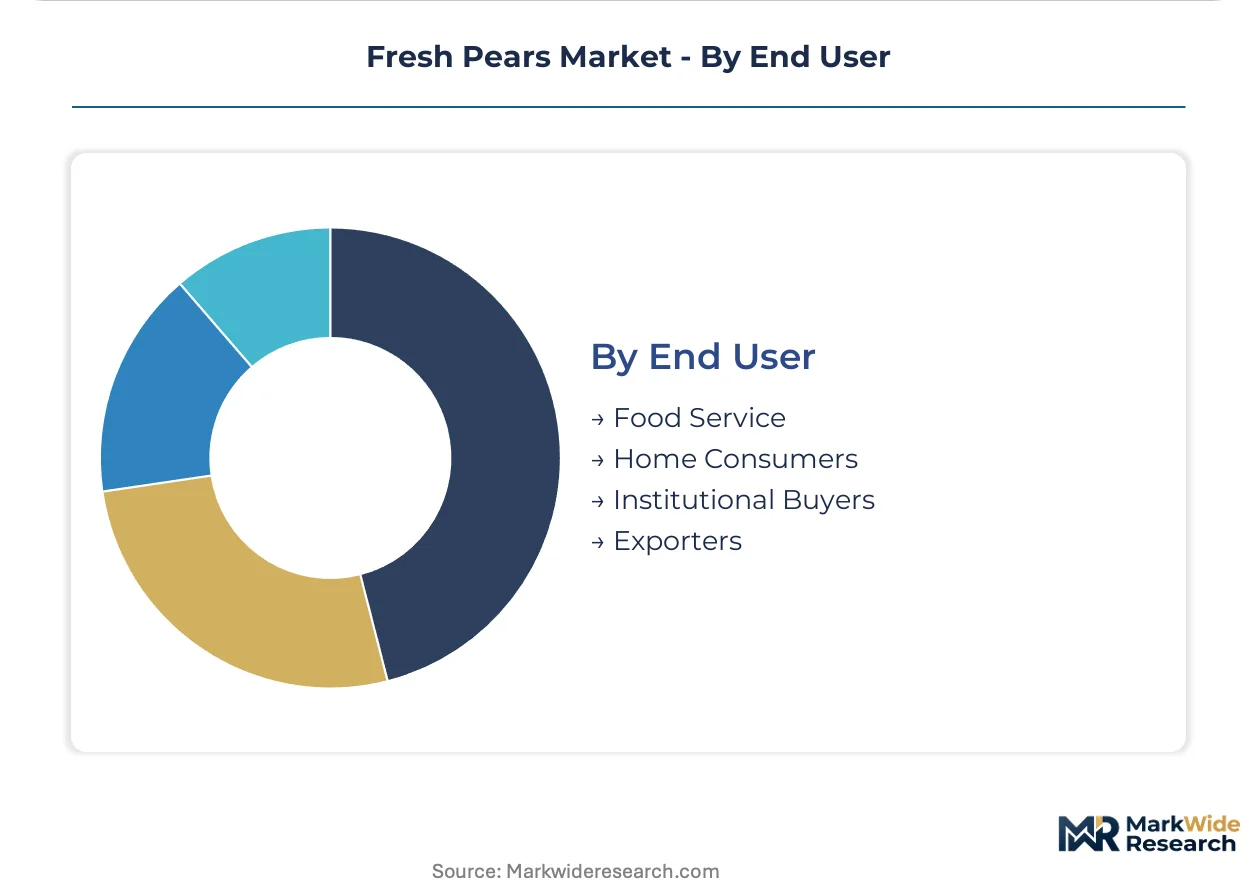
End User:
Application-specific requirements separate fresh-eating specifications from processing inputs, with soluble solids thresholds and defect tolerances defining supply suitability.
- Food Service:Restaurants and catering operations in Paris, London, and New York source heritage varieties for seasonal menu integration, requiring consistent sizing and ripeness staging for plate presentation. Chefs specify Bosc and Comice for dessert applications where visual differentiation commands menu premiums.
- Home Consumers:Retail purchasers in Chinese urban centers and North American suburbs drive volume demand for Bartlett and Anjou through supermarket and e-commerce channels, with convenience packaging and extended shelf-life influencing repeat purchase.
- Institutional Buyers:School nutrition programs and healthcare facilities in the United States procure canned and fresh pear components under USDA commodity specifications with firmness and Brix requirements.
- Exporters:Trading companies and import agents in Dubai, Singapore, and Hong Kong consolidate shipments for re-export to secondary markets, requiring phytosanitary compliance with multiple national regulators including China's SAMR and Saudi Arabia's SFDA.
Home Consumers dominate installed base across production regions. Food Service is where expansion concentrates for heritage varietal premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's sustainable agriculture mandates are accelerating orchard recertification timelines across major production zones. Washington State and Oregon face labor scarcity compressing harvest windows for hand-picked varieties. Chinese urban consumers are shifting toward premium imported pears through organized retail channels.
United States
Pacific Northwest producers dominate Bartlett and Anjou volumes through controlled-atmosphere storage enabling year-round supply. The EPA regulates pesticide residue thresholds under tolerances for exported fruit. Hood River Valley orchards in Oregon are deploying hyperspectral imaging systems for non-destructive ripeness assessment ahead of container loading.
China
Urban consumers in Shanghai and Beijing are concentrating demand for premium imported pear varieties through supermarket chains and e-commerce platforms. SAMR enforces GB national food safety standards for foreign pear entry. Shandong Province wholesale centers are consolidating procurement for re-export corridors across Southeast Asia.
Turkey
Early-season Bartlett shipments anchor Black Sea supply corridors through specialized logistics networks. EU phytosanitary protocols under EFSA shape European import eligibility for Turkish exporters. Bursa and İzmir packing houses are upgrading GlobalGAP certification to meet compressed compliance timelines.
Argentina
Counter-seasonal production extends Northern Hemisphere supply gaps with Bartlett varieties reaching maturity during February-April windows. National phytosanitary regulators enforce export certification aligned with Chinese and EU market access requirements. Río Negro Valley orchards are investing in integrated cold-chain infrastructure to sustain fruit quality through extended maritime transit.
Spain
Lleida and Huesca production zones supply Anjou and Bosc varieties to French and German supermarket chains under dedicated procurement contracts. REACH chemical authorization requirements are restricting post-harvest fungicide options for EU-bound shipments. Catalan cooperatives are adopting ozone-based storage treatments to maintain phytosanitary compliance without banned active ingredients.
Fresh Pears Market Competitive Landscape
Player mix skews toward integrated supply-chain operators with captive cold-chain assets and cooperative associations managing export consolidation. Market structure concentrates around three strategic archetypes: multinational food conglomerates with hemisphere-spanning sourcing networks, national producer cooperatives controlling varietal branding and quality standards, and regional packing houses with direct-to-retail procurement relationships. Dominant competitive moves include backward integration into orchard ownership and strategic partnerships with e-commerce platforms for traceability-premium capture.
Among integrated operators, Del Monte Foods exemplifies the multinational archetype with cross-hemisphere supply continuity, while USA Pears represents cooperative-controlled varietal branding through controlled-origin marketing programs. Turkish Fruit Exporters Association anchors the cooperative consolidation model for Black Sea corridor access.
| Leading Market Players |
|---|
| Del Monte Foods |
| Turkish Fruit Exporters Association |
| USA Pears (Pear Bureau Northwest) |
| Indonesian Agricultural Trading Companies |
| European Pear Producers Cooperative |
| Duckwall Fruit |
| China National Fruit & Vegetable Wholesale Center |
| Russian Fruit Import Distributors |
| Northwest Packing Company |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day controlled-atmosphere storage windows concentrate pricing power with Washington State and Argentine suppliers who bridge Northern Hemisphere supply gaps, while compressed harvest timelines in Oregon compress margins for hand-picked Comice and Bosc varieties. Inventory carrying costs across these extended cold-chain cycles feed directly into contract premiums for year-round Bartlett availability.
Pricing Analysis
Certification level creates the primary spread between export-grade Bartlett shipments and domestic-channel fruit, with GlobalGAP-certified volumes commanding shelf-space premiums in German supermarket chains while uncertified product flows to discount retail. Three-tier pricing structure across premium heritage varieties, standard Anjou and Bartlett, and economy-grade processing fruit reflects quality grade and harvest timing differentiation. Pricing pressure stems from labor scarcity in Pacific Northwest orchards elevating per-unit picking costs. Food service buyers in Paris and London show lowest price sensitivity for provenance-documented Comice, while European discount retail channels drive hardest bargaining on Anjou winter volumes.
Supply Chain Analysis
Ninety-day maritime transit windows from Argentina to Shanghai concentrate inventory risk with importers lacking captive cold-chain assets. Supply concentrates in Washington State, Argentina, and Turkey, with counter-seasonal production cycles drawing from Southern Hemisphere gaps. Raw material dependencies center on sulfur-based fungicides, controlled-atmosphere storage infrastructure, and specialized harvest labor pools. Single-source vulnerability runs through Turkish Black Sea corridors where early-season Bartlett shipments face EFSA phytosanitary compliance bottlenecks. Distribution runs through supermarket centralized buying offices in China and Germany, with direct-to-retail contracts displacing wholesale auction channels for premium varieties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from fresh stone fruits and imported apples displacing pear shelf space in European discount channels during peak summer windows. Defense requires securing year-round supply continuity and certification advantages that substitutes cannot replicate.
For Market Incumbents: Secure backward integration into orchard ownership in Washington State and Río Negro Valley to control harvest timing and quality staging. Lock in GlobalGAP recertification ahead of compressed EU Green Deal timelines to defend supermarket listing positions against Turkish and Argentine competitors. Channel control through direct-to-retail contracts with Shanghai e-commerce platforms insulates against wholesale price erosion. For New Entrants and Emerging Players: Differentiate on carbon-footprint transparency aligned with EU Green Deal scope 3 disclosure mandates, targeting German and French supermarket chains implementing emissions reduction targets. White-space exists in ozone-based storage treatment services for Spanish and Italian cooperatives lacking in-house REACH compliance expertise. Go-to-market through specialized logistics partnerships for early-season Bartlett from Bursa and İzmir packing houses. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Pacific Northwest packing houses facing generational transition and lacking capital for hyperspectral imaging deployment. Long-term viability hinges on cold-chain asset ownership and direct-to-retail channel relationships rather than commodity trading positions. Watch for inflection when Chinese SAMR enforcement tightens residue limits, accelerating consolidation among exporters lacking in-house compliance expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Ownership | Captive supply of Washington State and Argentine Bartlett secures year-round positioning against counter-seasonal competitors. |
| GlobalGAP Certification Acceleration | Early compliance with EU Green Deal timelines secures preferential listing terms with German centralized buying offices. |
| Direct-to-Retail E-Commerce Contracts | Shanghai platform partnerships capture traceability premiums and displace wholesale intermediary margins. |
| Hyperspectral Imaging Deployment | Non-destructive ripeness assessment reduces rejection rates at Tokyo and Shanghai destination markets. |
| Ozone-Based Storage Treatment Adoption | Spanish cooperatives maintain EU phytosanitary compliance without banned post-harvest fungicides under REACH. |
Research Methodology
A standing panel of orchard operations managers, supermarket category buyers, cold-chain logistics directors, and food service procurement chefs provided ongoing calibration across primary interview rounds. Secondary validation drew from USDA National Agricultural Statistics Service data, EFSA phytosanitary protocol filings, Chinese SAMR import inspection records, and EU Green Deal implementation guidance documents. Bottom-up variety-level volume estimates triangulated against top-down trade flow analysis from customs consolidation databases.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeled by variety, packaging format, distribution channel, and end-use application. CAGRs derived from historical trade flow trajectories and forward-looking procurement contract visibility, incorporating orchard planting cycles and climate yield variability as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of stable EU-China trade corridor access and continued labor availability in Pacific Northwest harvest windows; material deviation in phytosanitary enforcement or immigration policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Liquid-Cooled Heat Sink Market
Others
Asia-Pacific Road Safety Market
Others
Smart TV Platforms Market
Others
UK Cat Food Market
Others
Foldable Smartphone Market
Others
Europe Travel Retail Market
Others
Smart Home Controller Market
Others
Next Gen Video Codecs Market
Others
Global Emergency Spill Response Market
Others
Reduced-Risk Products (Rrps) Market
Others
Canada 3D Printing Construction Market
Others
Vortexers Market
Others
Sprockets Market
Others
United States Indoor LBS Market
Others
Asia-Pacific Eyelash Serum Market
Others
Radiation Detection Monitoring and Safety Market